
 Global Diet Food and Beverages Market | 2026-2036
Global Diet Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diet Food and Beverages Market Analysis
Stevia and monk fruit extracts are pivoting away from aspartame in diet soft drink formulations, altering cost structures and clean-label positioning across the category. PepsiCo Inc. leverages its beverage distribution network to accelerate stevia-based line penetration in Latin America. Danone S.A. anchors its portfolio in protein-forward dairy alternatives with probiotic fortification. Nestlé S.A. dominates ready-to-drink meal replacement formats through manufacturing scale in Europe and Asia.
Diet food and beverages comprise formulated consumables engineered for caloric reduction, macronutrient modulation, or metabolic management, typically achieving sub-200 kcal per serving through controlled carbohydrate loading and alternative sweetener systems. Products incorporate soluble fiber matrices and heat-stable probiotic strains to preserve gastrointestinal claims through shelf life. Protein shakes lead volume contribution due to gym-channel penetration and post-workout ritualization, while natural sweeteners capture fastest value growth as clean-label mandates harden in Western Europe. Online retail is deepening margin pools by disintermediating traditional wholesale markups and enabling direct subscription models.
The FDA enforces qualified health claim thresholds for fiber and reduced-disease-risk language, while EFSA's nutrient profiling model restricts diet claims on products exceeding sodium or saturated fat baselines. China's SAMR now mandates pre-approval for functional food labeling, tightening market access for imported meal replacement bars. Stakeholders must monitor evolving sweetener tolerance thresholds across Brazil, India, and Germany as regulators recalibrate acceptable daily intake benchmarks.
Market Dynamics
Clean-label mandates are compressing formulation timelines as manufacturers reformulate legacy portfolios around stevia and monk fruit extracts, abandoning artificial sweetener systems that dominated the prior decade.
Growth Catalysts
- EFSA Nutrient Profiling:Stricter baselines for sodium and saturated fat are forcing portfolio upgrades that align with metabolic health positioning, accelerating premium tier development.
- Brazil Middle-Income Expansion:Metabolic-health awareness among this demographic is pulling portion-controlled meal systems into mainstream retail channels.
- Soluble Fiber Matrix Technology:Heat-stable gastrointestinal claims through shelf life are unlocking extended distribution reach for ambient-stable formats.
Market Restraints
- Stevia Supply Concentration:Raw extract sourcing clusters in specific growing regions, exposing cost structures to climate volatility and harvest variability.
- China SAMR Pre-Approval:Mandatory functional food labeling review extends market access timelines for imported meal replacement bars by 12-18 months.
- Probiotic Strain Stability Limits:Heat-sensitive cultures restrict processing temperatures, constraining manufacturing flexibility and line throughput rates.
Strategic Opportunities
- India Regulatory Recalibration:FSSAI tolerance threshold reviews for alternative sweeteners may open formulation windows previously closed to imported products.
- Subscription Direct-to-Consumer:Online retail disintermediation enables recurring revenue models that bypass wholesale margin extraction entirely.
- Probiotic-Protein Convergence:Dairy alternative formats fortified with both macronutrients and live cultures address dual-positioning whitespace in functional nutrition.
Industry Challenges
- Clean-Label Reformulation Expertise:Shortage of food scientists skilled in natural sweetener stability and flavor masking slows product pipeline velocity.
- Dual Jurisdiction Compliance:Simultaneous FDA qualified health claim substantiation and EFSA nutrient profiling creates documentation burden for multinational portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diet Food and Beverages Market |
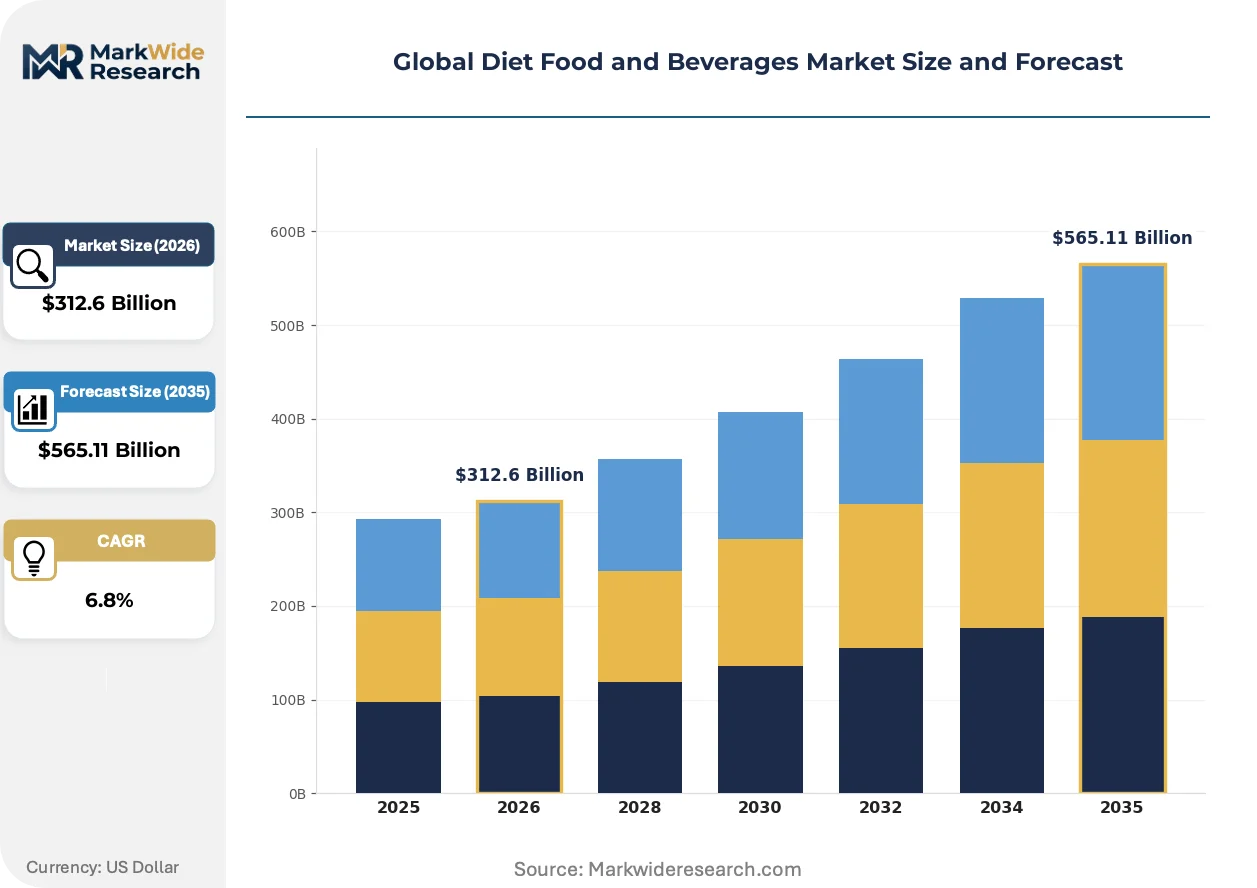
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Shakes, Low-Calorie Snacks, Diet Soft Drinks, Meal Replacement Bars Ingredient Type: Artificial Sweeteners, Natural Sweeteners, Fiber, Probiotics Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores Consumer Segment: Fitness Enthusiasts, Diabetics, Health-Conscious Individuals, Weight Watchers |
| Companies Covered | Nestlé S.A., PepsiCo Inc., Danone S.A., General Mills Inc., Abbott Laboratories, Kraft Heinz Company, Mondelez International Inc., The Coca-Cola Company, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diet Food and Beverages Market Emerging Trajectories
Natural sweetener systems are compressing the competitive window for legacy artificial alternatives, while regulatory harmonization efforts create both compliance burdens and first-mover advantages for prepared manufacturers.
Stevia extract purification technology is consolidating cost structures for high-purity Reb M and Reb D fractions that eliminate bitter aftertaste. Weight management clinics and gym-channel distributors are accelerating procurement of these next-generation sweetener systems. The technology is consolidating supplier power among extract processors with proprietary bioconversion capabilities, marginalizing commodity-grade stevia traders.
EFSA's tightened nutrient profiling model now restricts reduced-calorie claims on products exceeding baseline sodium or saturated fat thresholds. Reformulation costs are rising for legacy SKUs that previously qualified for diet positioning. Western European retail chains are responding by delisting non-compliant products ahead of enforcement deadlines, compressing shelf space for slower-moving manufacturers.
Subscription-based replenishment models are displacing traditional wholesale procurement in protein shake and meal replacement categories. Direct-to-consumer platforms capture recurring purchase patterns while traditional gym-channel distributors lose volume to home-delivery convenience. Brazil and Germany exhibit the fastest channel rotation as middle-income consumers prioritize convenience over point-of-sale discovery.
Global Diet Food and Beverages Market Segmentation
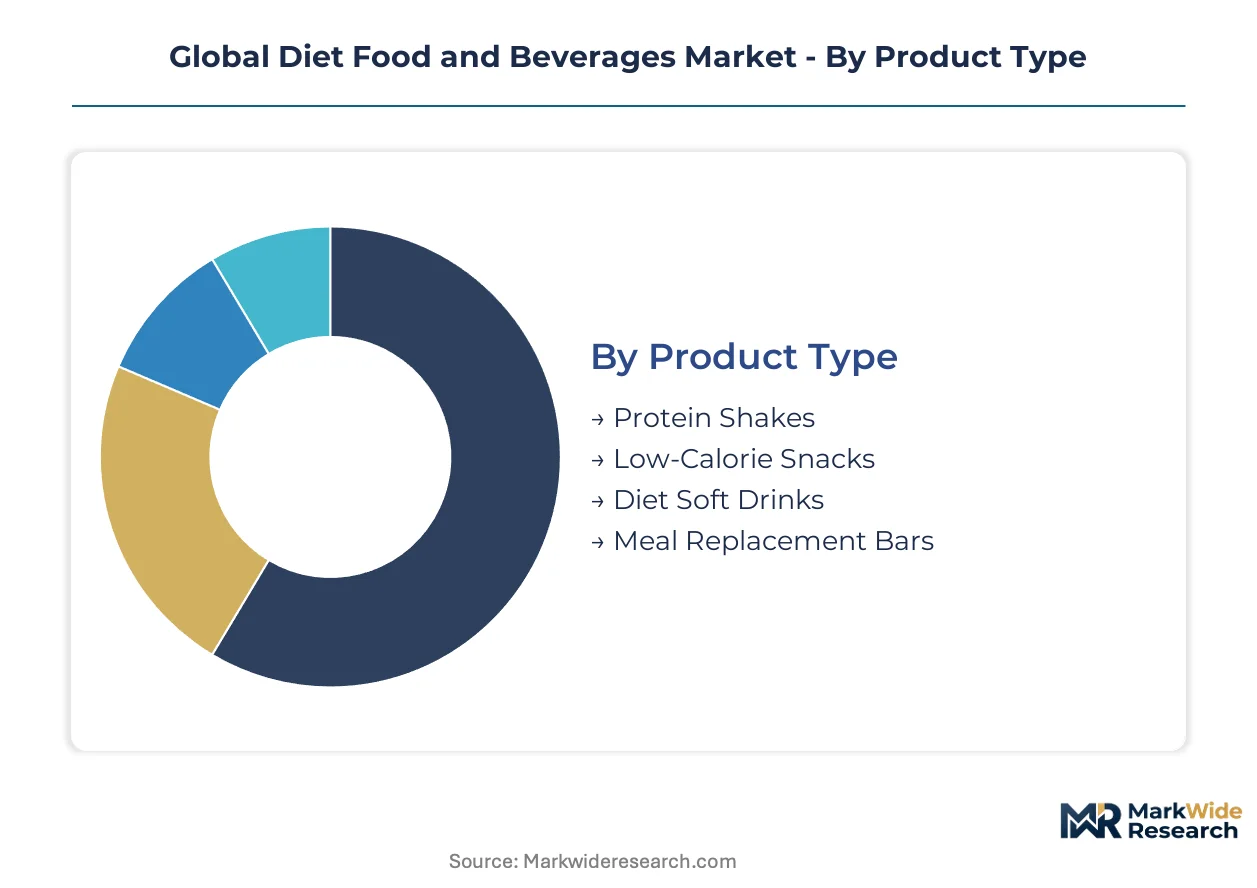
Segmentation in diet food and beverages separates volume-driven commodity formats from precision-formulated premium offerings. Product architecture, sweetener chemistry, channel access, and metabolic use-case each create distinct margin pools and regulatory exposure profiles.
Product Type:
Customization intensity spans engineered meal systems to grab-and-go refreshment, with formulation complexity driving the standardization spectrum.
- Protein Shakes:Ready-to-drink emulsions delivering 20-30g protein per serving through dairy or plant isolate bases. Demand concentrates in gym-channel procurement and post-workout ritualization across Brazil and Germany, where subscription models displace traditional wholesale.
- Low-Calorie Snacks:Portion-controlled formats achieving sub-150 kcal through controlled carbohydrate matrices and air-popped or baked processing. Weight management clinics in São Paulo and Rio de Janeiro are expanding procurement of these systems for patient adherence programs.
- Diet Soft Drinks:Carbonated formulations reformulating around stevia and monk fruit extracts.
- Meal Replacement Bars:Compressed nutrient-dense formats with shelf-stable protein and fiber.
Most installed capacity flows through Protein Shakes. Expansion is steepest in Low-Calorie Snacks.
Ingredient Type:
Cost tier stratification separates commodity synthetic inputs from extraction-dependent natural systems with volatile supply curves.
- Natural Sweeteners:Purified stevia Reb M/Reb D fractions and monk fruit mogroside extracts eliminating bitter aftertaste through proprietary bioconversion. Western European clean-label mandates are compressing formulation timelines and marginalizing commodity-grade stevia traders.
- Artificial Sweeteners:Aspartame, sucralose, and acesulfame potassium systems facing displacement.
- Fiber:Soluble matrices enabling heat-stable gastrointestinal claims through shelf life.
- Probiotics:Heat-sensitive cultures restricting processing temperatures and line throughput.
Natural Sweeteners command expanding formulation share. Artificial Sweeteners face steepest volume erosion.
Distribution Channel:
Customer type determines channel priority, with convenience-seeking subscription users diverging from discovery-oriented retail browsers.
- Online Retail:Direct-to-consumer platforms capturing recurring revenue through subscription replenishment, disintermediating wholesale markups entirely. Brazil and Germany exhibit fastest channel rotation as middle-income consumers prioritize home-delivery convenience.
- Supermarkets:Mass-market shelf space facing EFSA nutrient profiling delisting pressure for non-compliant legacy SKUs.
- Health Food Stores:Curated assortments targeting metabolic-health positioning.
- Convenience Stores:Impulse-oriented single-serve protein shake placement.
Online Retail captures margin expansion. Supermarkets retain volume concentration.
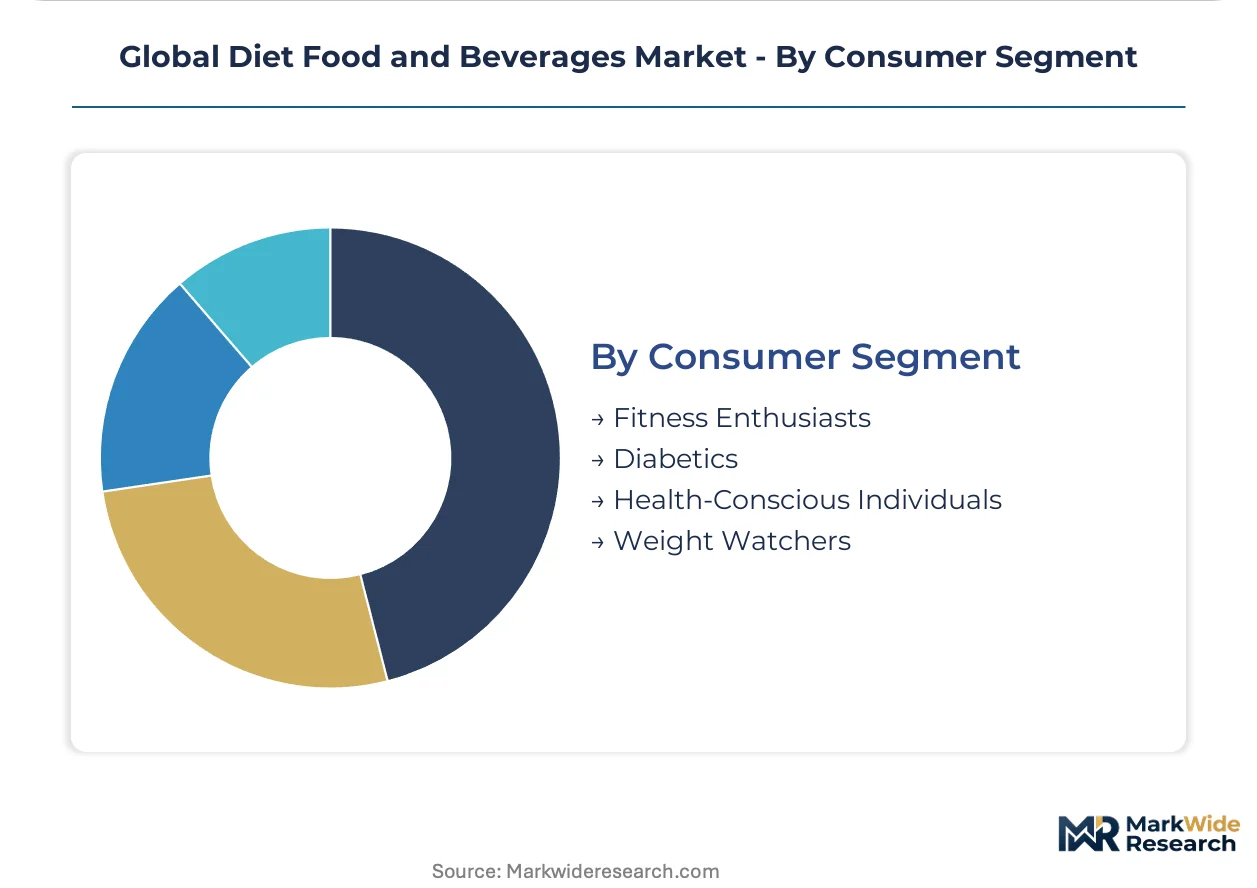
Consumer Segment:
Application specificity ranges from clinical metabolic management to discretionary fitness optimization, shaping regulatory scrutiny and claim substantiation burden.
- Diabetics:Glycemic-controlled formulations requiring precise carbohydrate quantification and FDA qualified health claim substantiation. China's SAMR pre-approval mandates extend market access timelines for imported meal replacement bars targeting this segment.
- Fitness Enthusiasts:Protein-forward consumption ritualized around training schedules.
- Health-Conscious Individuals:Broad prevention-oriented positioning with clean-label preference.
- Weight Watchers:Calorie-accounting behaviors driving portion-control demand.
Diabetics impose steepest regulatory compliance burden. Fitness Enthusiasts generate highest purchase frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates metabolic-health demand acceleration among middle-income consumers, pulling portion-controlled meal systems into mainstream retail channels across São Paulo and Rio de Janeiro.
Brazil
Weight management clinics in São Paulo and Rio de Janeiro are expanding procurement of portion-controlled meal systems for patient adherence programs. ANVISA monitors tolerance threshold recalibration for alternative sweeteners, creating formulation windows for stevia-based products. The São Paulo metropolitan corridor anchors national distribution for ambient-stable diet formats targeting middle-income households.
Germany
Fitness enthusiasts in Berlin and Munich drive subscription-model adoption for protein shakes, displacing traditional gym-channel wholesale procurement. EFSA's nutrient profiling model restricts reduced-calorie claims on products exceeding sodium baselines, forcing portfolio upgrades. The Bavarian industrial cluster hosts manufacturing scale for heat-stable probiotic fortification systems.
United States
Direct-to-consumer platforms capture recurring revenue through subscription replenishment, disintermediating traditional wholesale markups entirely. The FDA enforces qualified health claim thresholds for fiber and reduced-disease-risk language, tightening substantiation documentation. California's clean-label mandate leadership accelerates stevia and monk fruit extract reformulation timelines for legacy portfolios.
China
SAMR pre-approval requirements for functional food labeling extend market access timelines for imported meal replacement bars by 12-18 months. The Yangtze River Delta manufacturing belt concentrates ready-to-drink production capacity for domestic protein shake demand. Shanghai's retail chains prioritize glycemic-controlled formulations targeting diabetic consumer segments.
India
FSSAI tolerance threshold reviews for alternative sweeteners may open formulation windows previously closed to imported diet products. Maharashtra's Mumbai-Pune corridor anchors distribution infrastructure for natural sweetener penetration into traditional retail. Bangalore's health-conscious professional demographic drives online retail channel rotation for subscription-based meal systems.
Global Diet Food and Beverages Market Vendor Landscape
Global majors compete with regional champions across formulation expertise and distribution network depth, creating a tiered structure where scale-driven players anchor premium positioning while mid-cap specialists occupy clean-label niches. The vendor base separates into three archetypes: multinational conglomerates with manufacturing scale, regional champions with channel intimacy, and biotech-forward specialists with probiotic strain IP. Competitive moves concentrate on portfolio reformulation around natural sweetener systems and backward integration into stevia extract processing.
Among Switzerland-based conglomerates, Nestlé S.A. occupies a position exemplifying manufacturing scale across European and Asian production networks. PepsiCo Inc. represents the beverage-centric archetype with Latin American distribution leverage for stevia-based line penetration. Danone S.A. anchors the dairy-alternative specialist tier with protein-forward positioning and probiotic fortification capabilities.
| Leading Market Players |
|---|
| Nestlé S.A. |
| PepsiCo Inc. |
| Danone S.A. |
| General Mills Inc. |
| Abbott Laboratories |
| Kraft Heinz Company |
| Mondelez International Inc. |
| The Coca-Cola Company |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
Stevia Reb M/Reb D extract costs cascade through three pricing tiers as raw material volatility from Paraguay and China growing regions compresses margins for commodity-grade traders while rewarding processors with proprietary bioconversion capabilities. Natural sweetener premiums widen against eroding artificial alternatives, reshaping procurement strategies across Brazil, Germany, and the United States.
Pricing Analysis
Input-cost pass-through from stevia extract purification technology concentrates pricing power among bioconversion specialists commanding premium tiers, while commodity-grade traders face compression. Price differentiation hinges on clean-label certification grade and subscription-model volume scale. Pricing pressure intensifies downward as EFSA nutrient profiling delistings force legacy SKU clearance in Western European supermarkets. Weight management clinics exhibit lowest price sensitivity due to patient adherence program budgets, while convenience store impulse buyers show highest elasticity.
Supply Chain Analysis
Domestic-content mandates in China's SAMR pre-approval framework and India's FSSAI tolerance reviews are reshaping sourcing patterns for imported meal replacement formats. Supply concentrates in Paraguay and China for stevia raw extract, with Kenya and India emerging for monk fruit mogroside alternatives. Raw material dependencies center on Reb M/Reb D fractions, heat-stable probiotic strains, and soluble fiber matrices. Single-source vulnerability in Paraguayan growing regions exposes cost structures to climate volatility. Distribution runs through direct-to-consumer subscription platforms disintermediating traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on natural sweetener cost curves flattening through bioconversion scale, alongside premium-tier subscription models capturing recurring revenue pools.
For Market Incumbents: Anchor manufacturing scale in European and Asian production networks against stevia supply concentration risks. Prioritize backward integration into proprietary extract processing capabilities to defend margin position from commodity-grade trader displacement. Accelerate EFSA-compliant portfolio upgrades ahead of enforcement deadlines to secure supermarket shelf space retention.
For New Entrants and Emerging Players: Enter via subscription-based direct-to-consumer platforms in Brazil and Germany where channel rotation is accelerating fastest. Target diabetic consumer segments in China pending SAMR regulatory clarity, leveraging glycemic-controlled formulation whitespace. Deploy probiotic-protein convergence positioning to differentiate from incumbent dairy-alternative portfolios.
For Investors and Strategic Acquirers: Consolidation pressure builds where clean-label reformulation expertise scarcity intersects with multinational documentation burdens for dual FDA-EFSA compliance. Long-term viability favors biotech-forward specialists with heat-stable probiotic strain IP and stevia bioconversion capabilities. Watch FSSAI tolerance threshold recalibration in India as inflection signal for imported product formulation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stevia Bioconversion | Proprietary Reb M/Reb D processing eliminates bitter aftertaste while capturing extract margin pools. |
| Subscription Direct-to-Consumer Launch | Recurring revenue models in Brazil and Germany bypass wholesale markups entirely. |
| EFSA Nutrient Profiling Compliance Upgrade | Preemptive reformulation secures Western European retail shelf space ahead of delisting deadlines. |
| Probiotic-Protein Convergence R&D | Dairy alternative formats with live cultures address dual-positioning whitespace in functional nutrition. |
| Heat-Stable Gastrointestinal Claim Extension | Soluble fiber matrix technology unlocks ambient-stable distribution reach for meal replacement bars. |
Methodological Framework
Bottom-up metabolic-use-case modeling reconciled against top-down sweetener-system tracking forms the analytical core. Primary interviews with brand managers at multinational conglomerates, category buyers at Brazilian and German retail chains, regulatory affairs leads navigating SAMR and EFSA frameworks, and supply planners managing stevia extract procurement were cross-validated against secondary sources including FDA qualified health claim filings, EFSA nutrient profiling model documentation, ANVISA tolerance threshold notices, and Nielsen retail audit data for subscription channel penetration.
Historical trendline analysis across natural and artificial sweetener substitution patterns, clean-label mandate adoption curves, and direct-to-consumer channel rotation velocities informed projection frameworks. Segmentation dimensions modeled include product format architecture, sweetener chemistry tier, distribution channel type, and metabolic use-case specificity. CAGRs were derived from elasticity-adjusted volume trajectories calibrated against regulatory enforcement timelines and procurement pattern shifts from gym-channel wholesale to subscription replenishment.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time stevia harvest yield data and SAMR pre-approval processing timelines introduce uncertainty bands around near-term supply cost assumptions. Forecasts reflect documented assumptions regarding EFSA enforcement consistency, FSSAI recalibration timing, and middle-income consumer convenience prioritization persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Moringa Products Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Chamomile Market
Specialty Foods
Edible Mushroom Market
Specialty Foods
North America Hummus Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Superfood Bars Market