
 Immunochemicals Market | 2026-2036
Immunochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Immunochemicals Market Outlook
Biotechnology manufacturing clusters in Massachusetts and California is recalibrating global supply chains for monoclonal antibody production. Thermo Fisher Scientific leverages captive bioproduction infrastructure to sustain reagent consistency across North American and European channels. Danaher Corporation anchors its competitive stance through integrated workflow automation spanning sample preparation to detection. Merck KGaA differentiates via deep specialization in GMP-grade immunochemical raw materials for pharmaceutical manufacturing.
Immunochemicals comprise biologically active molecules—primarily antibodies, antigens, and labeled detection reagents—engineered for specific binding interactions with target analytes, typically manufactured through hybridoma culture, recombinant expression, or synthetic peptide chemistry with purity grades ranging from research-use-only to GMP-certified. These reagents enable quantitative and qualitative detection of biomarkers, pathogens, and therapeutic compounds across diagnostic, research, and drug development applications. Antibodies command the largest value share within product type segmentation due to their irreplaceable specificity and lengthy development cycles that create supplier stickiness. ELISA technology dominates instrument-installed bases but flow cytometry reagent demand is expanding fastest as multiplexed cell analysis penetrates immuno-oncology workflows. Academic institutions represent a mature, price-sensitive end user segment while pharmaceutical companies concentrate margin pools through long-term supply agreements for qualified reagent lots.
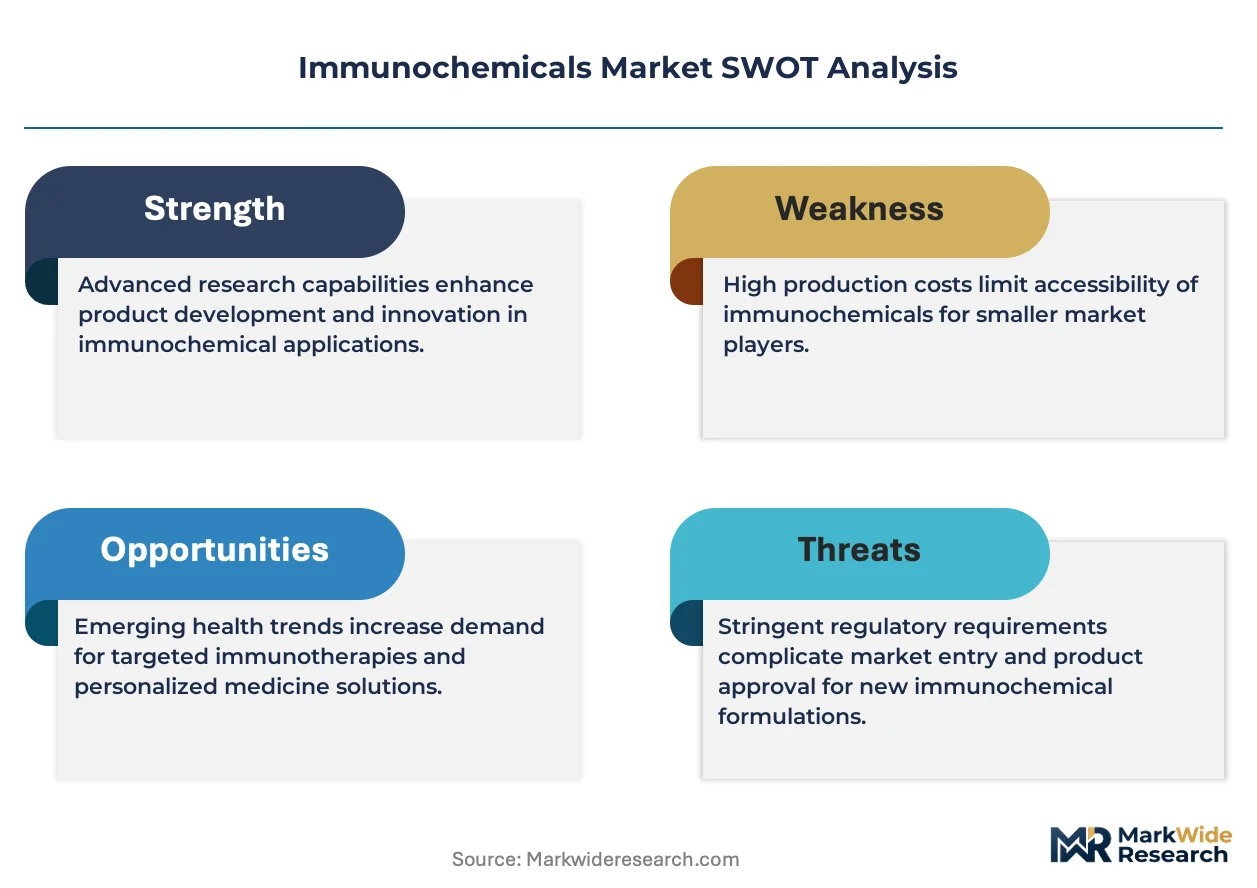
The FDA enforces stringent analytical validation requirements under CLIA for clinical diagnostic immunochemicals, while the EU MDR and IVDR frameworks impose expanded conformity assessment obligations on assay kit manufacturers seeking European market access. China's NMPA has accelerated review pathways for innovative diagnostic reagents but mandates local clinical evidence generation that shapes foreign supplier entry strategies. ISO 13485 certification serves as a baseline quality expectation that filters qualified suppliers from commodity traders across institutional procurement channels. Stakeholders must monitor evolving harmonization gaps between FDA breakthrough device criteria and EU IVDR Class C performance standards when prioritizing regulatory investment sequencing.
Market Dynamics
Automated immunoassay platforms are compressing turnaround times in clinical diagnostics while simultaneously raising the technical bar for reagent manufacturers to maintain lot-to-lot consistency under continuous-run conditions.
Growth Catalysts
- EU IVDR Class C Performance Standards:The tightened validation requirements for high-risk diagnostic assays are accelerating replacement cycles for legacy reagent kits across European clinical laboratories.
- Flow Cytometry Reagent Demand:Multiplexed cell analysis workflows in immuno-oncology research are expanding faster than traditional ELISA applications, pulling specialized detection reagents into pharmaceutical R&D pipelines.
- Heidelberg Precision Diagnostics Cluster:Concentrated demand from Germany's university hospital network and contract research organizations is anchoring specialized antibody procurement volumes for companion diagnostic development.
Market Restraints
- Hybridoma Cell Line Instability:Batch-to-batch variability in monoclonal antibody production creates qualification overhead that extends lead times for GMP-grade material.
- Freight-Derived Cold Chain Costs:Temperature-controlled logistics for protein reagents absorb disproportionate margin, particularly for cross-Atlantic shipments of heat-sensitive detection conjugates.
- Synthetic Peptide Chemistry Substitution:Engineered binding proteins and aptamer technologies are capturing share in research-use applications where antibody specificity advantages diminish.
Strategic Opportunities
- China NMPA Innovative Diagnostic Pathway:Accelerated review timelines for novel reagents with local clinical evidence are opening procurement channels previously dominated by domestic suppliers.
- Sample-to-Answer Workflow Integration:Convergence of microfluidic sample preparation with automated detection hardware is creating attach-rate opportunities for bundled reagent contracts.
- Point-of-Care Immunoassay Expansion:Decentralized testing infrastructure in ambulatory settings is generating demand for lyophilized reagent formats with extended ambient stability.
Industry Challenges
- ISO 13485 Auditor Capacity Bottleneck:Extended certification queue times are delaying market entry for qualified reagent lots intended for clinical diagnostic kits.
- Legacy LIMS Integration Friction:Automated immunoassay platforms require data architecture upgrades that strain IT resources at mid-sized hospital laboratory networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunochemicals Market |
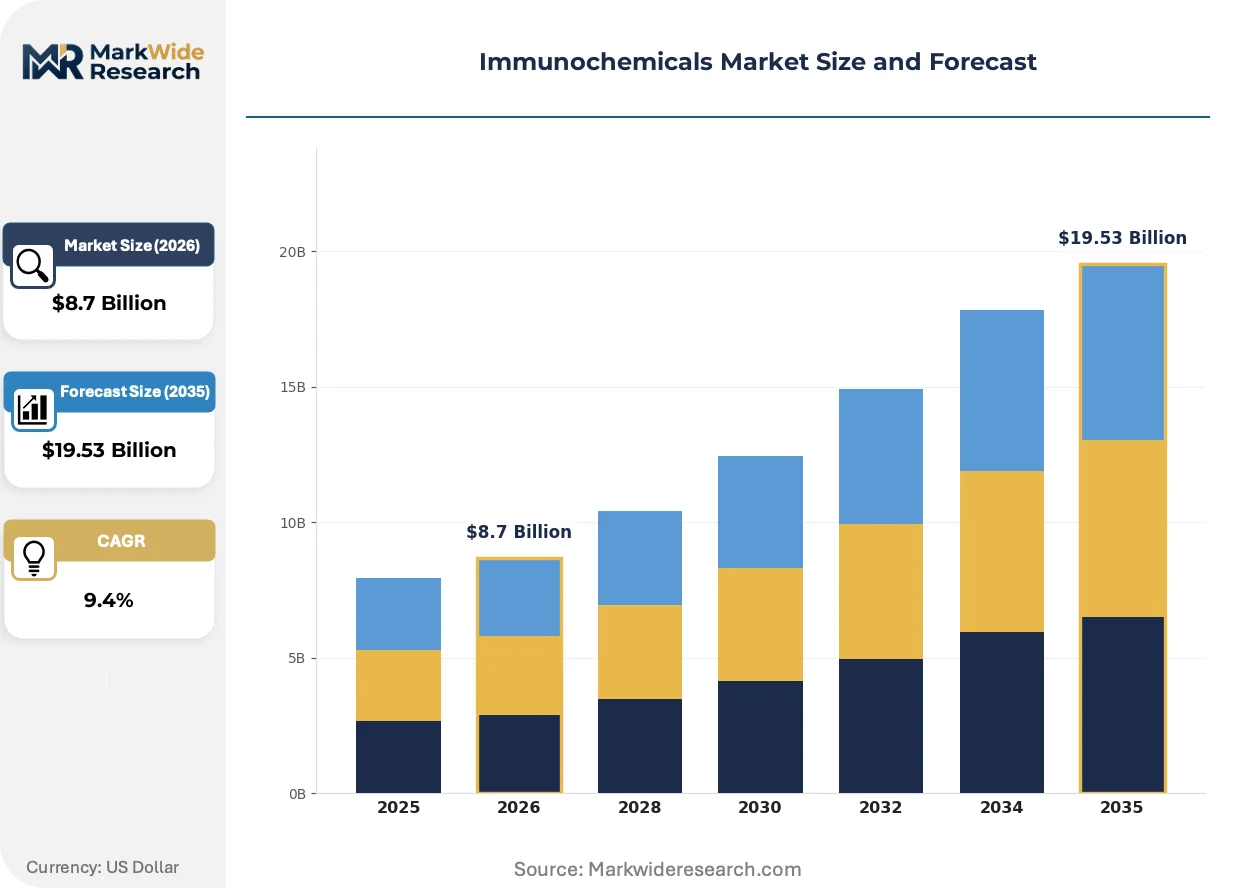
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibodies, Antigens, Assay Kits, Reagents Application: Clinical Diagnostics, Research Laboratories, Drug Development, Environmental Testing End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Clinical Laboratories Technology: ELISA, Western Blotting, Flow Cytometry, Immunohistochemistry |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Merck KGaA, Agilent Technologies, Inc., Bio-Rad Laboratories, Inc., F. Hoffmann-La Roche Ltd, Becton, Dickinson and Company, Abcam plc, Bio-Techne Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunochemicals Market Strategic Shifts
Multiplexed detection architectures are redefining throughput expectations across research and clinical workflows, compressing the economic viability of single-analyte test formats.
Single-molecule array technology is overtaking traditional ELISA sensitivity limits for low-abundance biomarker quantification. Pharmaceutical bioanalytical groups are adopting Simoa and Ella platforms for pharmacokinetic studies requiring femtomolar detection thresholds. This sensitivity escalation is overtaking the market position of conventional chemiluminescent immunoassays in precision medicine applications.
EU IVDR's expanded conformity assessment obligations are forcing assay kit manufacturers to rebuild technical documentation for legacy products. The MDR-aligned framework requires clinical performance data that many research-grade reagent suppliers cannot generate without partner laboratories. Small-to-mid diagnostic firms are responding by narrowing product portfolios to focus resources on Class C device recertification.
Academic procurement committees are consolidating vendor relationships around qualified supplier status rather than optimizing for unit cost. University core facilities are shifting from spot-buying to multi-year framework agreements that bundle reagent supply with instrument service coverage. This consolidation pattern is most visible in Massachusetts and California biotechnology corridors where shared resource centers coordinate purchasing across multiple principal investigator labs.
Immunochemicals Market Segmentation
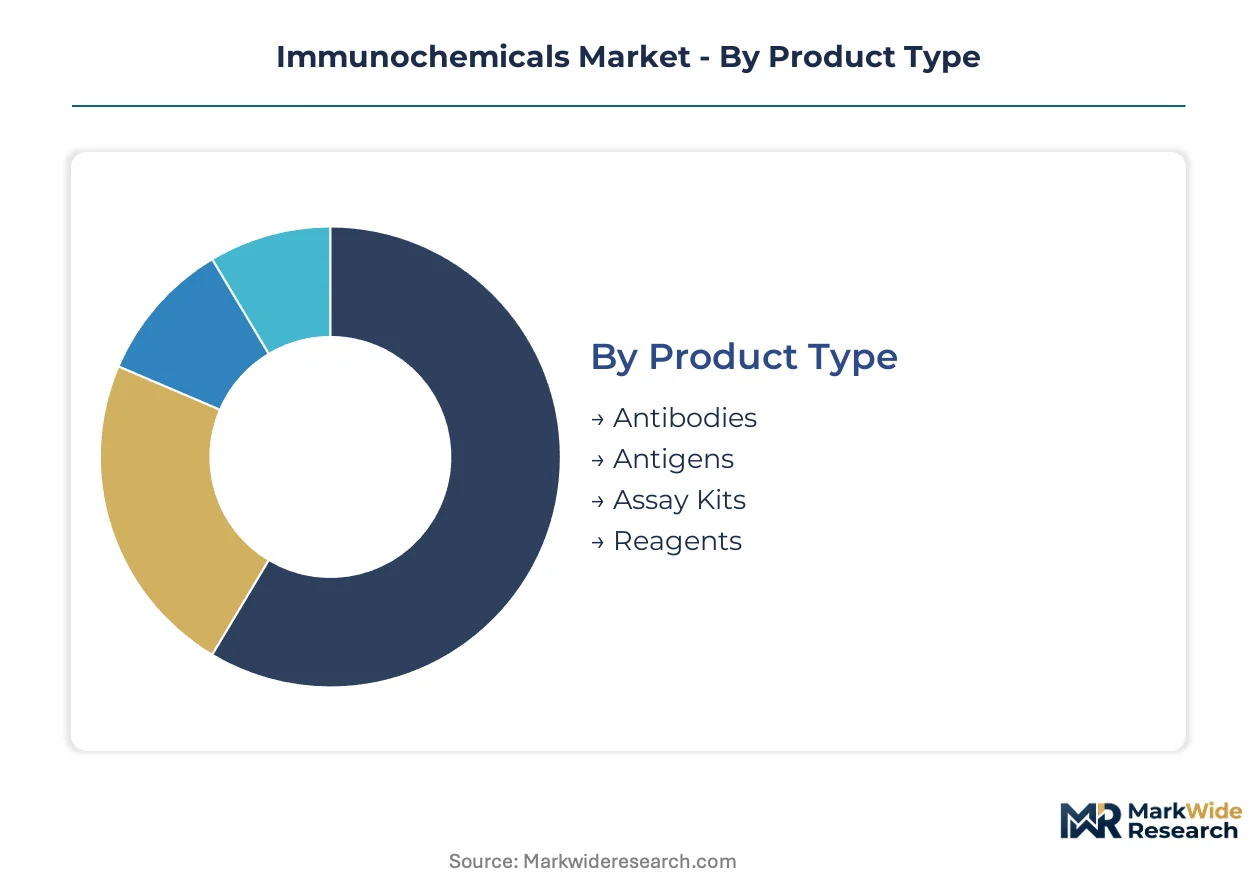
Immunochemicals span a specification gradient from research-grade reagents to GMP-certified diagnostic components. Segmentation reveals how purity requirements, automation compatibility, and regulatory qualification reshape procurement patterns across end-use verticals.
Product Type:
Standardization intensity varies sharply across this category, with pharmaceutical manufacturing demanding lot-matched consistency while research applications tolerate broader specification bands.
- Antibodies:Monoclonal and polyclonal immunoglobulins engineered for target specificity through hybridoma or recombinant production. Massachusetts biotechnology clusters anchor procurement volumes for GMP-grade monoclonal lots used in companion diagnostic development, with supplier stickiness reinforced by lengthy cell line qualification cycles.
- Antigens:Purified proteins, peptides, or synthetic constructs serving as immunization targets or assay calibrators. Heidelberg precision diagnostics networks concentrate demand for recombinant viral antigens in infectious disease assay panels, though batch-to-batch immunogenicity variability constrains multi-source procurement strategies.
- Assay Kits:Pre-configured detection systems bundling capture/detection antibodies, substrates, and protocols.
- Reagents:Labeled detection conjugates, buffers, and substrate chemistries enabling signal generation.
Most installed capacity flows through Antibodies. Expansion is steepest in Assay Kits as integrated workflow automation penetrates clinical laboratory networks.
Application:
Cost tier stratification separates high-volume clinical screening from premium-priced pharmaceutical bioanalytical services.
- Clinical Diagnostics:Quantitative biomarker detection in patient specimen analysis requiring CLIA or IVDR compliance. United States hospital laboratory networks drive automated immunoassay platform adoption, compressing turnaround times while raising lot-to-lot consistency thresholds for reagent suppliers.
- Drug Development:Pharmacokinetic and immunogenicity studies supporting therapeutic compound registration. California biotechnology corridors concentrate demand for femtomolar-sensitivity detection reagents as single-molecule array platforms displace conventional chemiluminescent methods in precision medicine workflows.
- Research Laboratories:Exploratory biomarker discovery and mechanistic studies with flexible specification tolerance.
- Environmental Testing:Contaminant and pathogen detection in water, soil, and food matrices.
Clinical Diagnostics commands the largest revenue pool. Drug Development is climbing the fastest as immuno-oncology pipelines expand multiplexed cell analysis requirements.
End User:
Customer type determines contract structure, with long-term supply agreements dominating pharmaceutical procurement and spot purchasing characterizing academic channels.
- Pharmaceutical Companies:Integrated therapeutic developers requiring qualified reagent lots for regulated bioanalytical studies. These organizations concentrate margin pools through multi-year framework agreements that bundle reagent supply with instrument service coverage, particularly visible in Massachusetts and California biotechnology corridors.
- Clinical Laboratories:Hospital and reference laboratory networks performing high-throughput diagnostic testing. Germany's university hospital network around Munich and Heidelberg anchors specialized antibody procurement volumes for companion diagnostic co-development with pharmaceutical partners.
- Biotechnology Firms:Emerging therapeutic developers outsourcing bioanalytical capabilities.
- Academic Institutions:University core facilities and principal investigator laboratories with price-sensitive procurement patterns.
Pharmaceutical Companies lock in the highest per-unit pricing. Clinical Laboratories are gaining share fastest as decentralized testing infrastructure expands.
Technology:
Maturity gradients separate established instrument-installed bases from emerging multiplexed detection architectures.
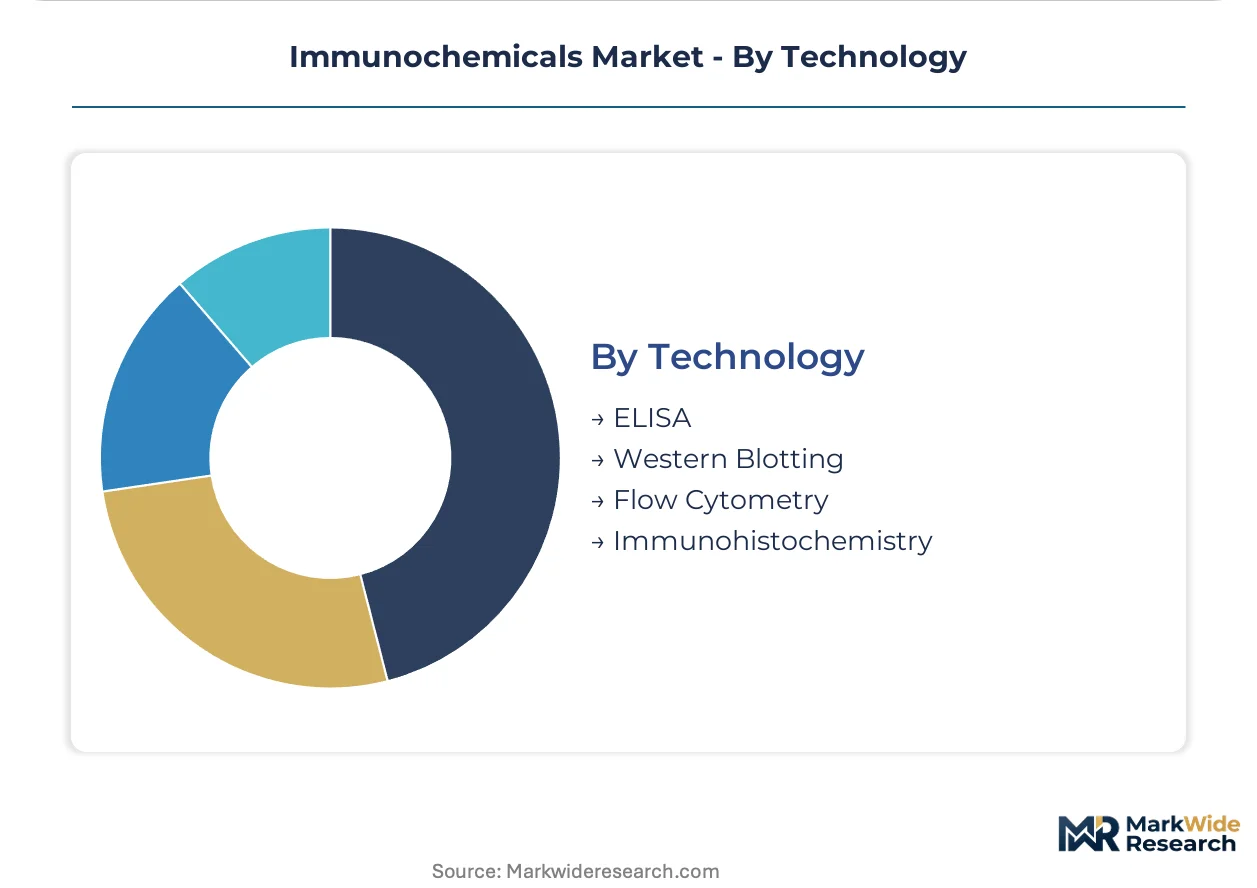
- ELISA:Enzyme-linked immunosorbent assay platforms dominating clinical and research installed bases through standardized microplate formats. The technology retains cost advantages in single-analyte quantification despite sensitivity limitations that single-molecule arrays are now displacing in low-abundance biomarker applications.
- Flow Cytometry:Fluorescence-activated cell sorting and analysis enabling simultaneous multiparameter cell characterization. Immuno-oncology research workflows in pharmaceutical R&D pipelines are expanding reagent demand fastest here, pulling specialized detection antibodies and fluorochrome conjugates into high-complexity panels.
- Western Blotting:Protein separation and immunodetection for molecular weight-specific target confirmation.
- Immunohistochemistry:Tissue-section-based protein localization for diagnostic pathology and research.
ELISA retains the broadest instrument footprint. Flow Cytometry is expanding most quickly as multiplexed analysis penetrates therapeutic development workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping immunochemicals manufacturing as producers migrate toward jurisdictions with streamlined biologics oversight. Cost-of-compliance gaps between the FDA and NMPA review pathways are accelerating facility investment decisions across Asia-Pacific.
United States
Hospital laboratory networks in Massachusetts and California are expanding automated immunoassay platform adoption. FDA CLIA enforcement maintains stringent analytical validation requirements that filter qualified suppliers from commodity traders. The Greater Boston biotechnology corridor concentrates demand for GMP-grade monoclonal antibody lots in companion diagnostic development.
Germany
Heidelberg's precision diagnostics cluster anchors specialized antibody procurement volumes for pharmaceutical co-development projects. EU IVDR Class C performance standards are accelerating replacement cycles for legacy reagent kits across university hospital networks. Munich-based contract research organizations are pulling detection reagents into immuno-oncology workflows at expanding scale.
China
NMPA's accelerated review pathway for innovative diagnostic reagents is opening procurement channels previously dominated by domestic suppliers. Local clinical evidence generation mandates are shaping foreign supplier entry strategies in Shanghai and Suzhou biotech zones. Yangtze River Delta manufacturing hubs are recalibrating global supply chains for recombinant protein production.
Japan
PMDA's harmonization with ICH guidelines is reducing registration friction for qualified immunochemical lots in pharmaceutical bioanalytical applications. METI funding programs support domestic bioproduction infrastructure in the Kanto region. Tokyo-Osaka therapeutic development corridors concentrate demand for femtomolar-sensitivity detection reagents.
United Kingdom
MHRA post-Brexit regulatory autonomy is creating parallel conformity assessment obligations for assay kit manufacturers. NHS procurement consolidation is compressing vendor relationships around qualified supplier status rather than unit cost optimization. The Cambridge-London life sciences corridor maintains specialized antibody demand for precision medicine research.
Immunochemicals Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue lyophilized reagent formats and point-of-care workflow integration. The vendor base stratifies across three maturity levels: integrated life sciences conglomerates with captive bioproduction infrastructure, mid-scale specialists with ISO 13485 certification depth, and research-grade suppliers facing IVDR documentation rebuilds. Dominant competitive moves include strategic partnerships for sample-to-answer workflow bundling and capacity expansion in temperature-controlled logistics networks.
Among US-based conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the integrated workflow automation archetype spanning sample preparation through detection. Merck KGaA, a German entity, occupies a position within the GMP-grade raw materials specialization tier. These three anchors represent distinct competitive vectors: captive bioproduction consistency, instrument-reagent bundling, and pharmaceutical manufacturing qualification depth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Merck KGaA |
| Agilent Technologies, Inc. |
| Bio-Rad Laboratories, Inc. |
| F. Hoffmann-La Roche Ltd |
| Becton, Dickinson and Company |
| Abcam plc |
| Bio-Techne Corporation |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical procurement committees with multi-year framework agreements dominate pricing power in GMP-grade immunochemicals, compressing spot-market premiums into narrow bands around qualified supplier contracts. This buyer concentration forces tiered pricing stratification across certification grades rather than brand premiums.
Pricing Analysis
Distributor margins absorb the primary pricing compression as cold-chain logistics costs escalate for cross-Atlantic antibody shipments. Three-tier pricing structure across GMP-certified, ISO 13485-qualified, and research-use-only levels separates pharmaceutical manufacturers from clinical laboratories from academic core facilities. Price differentiation hinges on lot-to-lot consistency documentation and IVDR conformity assessment depth. Margins are tightening in research-grade segments as synthetic peptide substitutes erode antibody specificity premiums.
Supply Chain Analysis
Single-source vulnerability sits with hybridoma cell line repositories concentrated in Massachusetts and California biotechnology corridors. Manufacturing gravity draws from Chinese recombinant protein hubs, German precision diagnostics clusters around Munich and Heidelberg, and Japanese bioproduction infrastructure in the Kanto region. Raw material dependencies rest on fetal bovine serum batches, fluorochrome conjugates, and GMP-grade buffer chemistries. Tariff exposure on temperature-controlled logistics creates margin fragility for heat-sensitive detection reagents. Distribution runs through qualified supplier networks with ISO 13485 certification rather than spot-market commodity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immunochemicals market compounds steadily as regulatory qualification barriers deepen supplier stickiness and extend replacement cycles for legacy reagent kits.
For Market Incumbents: To counter synthetic peptide substitution in research-use segments, deepen captive bioproduction of recombinant monoclonal antibodies through backward integration into hybridoma cell line banking. Anchor defensive positioning by expanding ISO 13485 auditor training partnerships to resolve certification queue bottlenecks delaying qualified lot releases. For New Entrants and Emerging Players: Launch via point-of-care lyophilized reagent formats targeting ambulatory testing infrastructure in China's Yangtze River Delta biotech zones. Penetrate the fastest-expanding white space in flow cytometry detection panels for immuno-oncology pharmaceutical R&D pipelines, bypassing saturated ELISA reagent commoditization. For Investors and Strategic Acquirers: Life sciences conglomerates with instrument-reagent bundling capabilities are the most active acquirer in this space. Target mid-scale ISO 13485-certified specialists with GMP-grade raw material depth and established university hospital procurement relationships. Watch for IVDR Class C recertification completion rates as the inflection signal distinguishing sustainable cash flow from documentation liability traps.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Class C Recertification Investment | EU conformity assessment obligations force technical documentation rebuilds for legacy assay kit portfolios. |
| Sample-to-Answer Workflow Integration | Microfluidic sample preparation convergence creates attach-rate opportunities for bundled reagent contracts in clinical laboratories. |
| Lyophilized Reagent Format Development | Ambient-stable formats capture point-of-care expansion in decentralized testing infrastructure. |
| Hybridoma Cell Line Banking Expansion | Captive cell line repositories reduce batch-to-batch variability overhead in GMP-grade monoclonal production. |
| China NMPA Local Clinical Evidence Generation | Domestic trial data mandates open procurement channels previously blocked to foreign immunochemical suppliers. |
Study Parameters
Direct dialogue with regulatory affairs directors at assay kit manufacturers, clinical laboratory procurement managers in German university hospital networks, pharmaceutical bioanalytical group leaders, and GMP-grade raw material sourcing executives grounded the qualitative foundation. Secondary validation drew from FDA CLIA guidance documents, EU IVDR technical documentation requirements, NMPA innovative diagnostic pathway filings, ISO 13485 certification databases, and trade data on temperature-controlled biologics logistics. Bottom-up reagent volume estimates and top-down market sizing triangulated across these inputs.
The analytical lens combined bottom-up segmentation modeling across product type, application, end user, and technology dimensions with top-down macro constraint validation. Modeled segments spanned antibodies, antigens, assay kits, and detection reagents by clinical diagnostic, drug development, research laboratory, and environmental testing applications. CAGRs derived from regression against instrument-installed base expansion, regulatory replacement cycle acceleration, and pharmaceutical pipeline immuno-oncology investment intensity. Single-molecule array platform adoption curves and flow cytometry panel complexity indices informed sensitivity thresholds.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IVDR auditor capacity constraints, hybridoma cell line instability events, or abrupt tariff escalation on cold-chain logistics. Forecasts reflect documented assumptions on regulatory harmonization gaps, certification queue durations, and synthetic substitution penetration rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Methanol Market
Chemicals
Global Pine Chemicals Market
Chemicals
Uranyl Carbonate Market
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
Barbituric Acid Market
Chemicals
Acetic Ether Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Lead Tetracetate Market
Chemicals
Europe Biguanide Market
Chemicals
Canada Methanol Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
Global Syringaldehyde Market
Chemicals
Ethylenediaminetetraacetic Acid Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Asia-Pacific Acetic Acid Market
Chemicals
Global Methylene Chloride Market