
 Louvre Windows Market | 2026-2036
Louvre Windows Market Size, Share, and Industry Trends Forecast 2026-2036
Louvre Windows Market Foresight
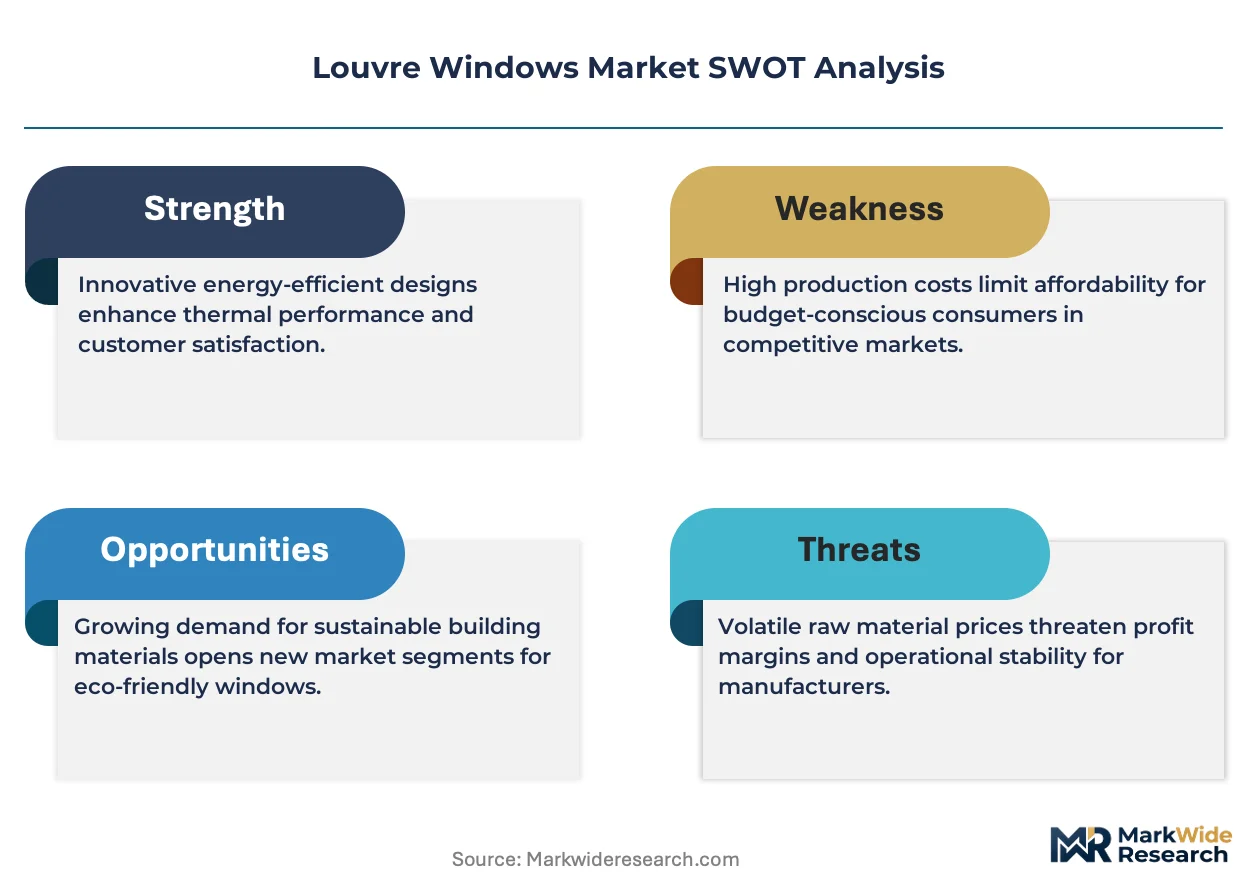
Multi-source procurement for aluminum extrusions and glazing hardware is decoupling from traditional single-source supply agreements in the louvre window industry. G.James Glass & Aluminium leverages captive float-glass capacity and extrusion presses across Queensland and Victoria to anchor its domestic supply position. Reynaers Aluminium competes through its European profile systems network, while Breezway specializes in powder-coated aluminum blade systems engineered for cyclone-rated coastal installations.
Louvre windows consist of parallel, horizontally mounted blades set within a frame, typically constructed from aluminum extrusions, tempered glass, or timber, with blade angles adjustable between zero and ninety degrees to modulate airflow, daylight penetration, and rain defense in commercial and residential envelopes. Aluminum profiles dominate specification volumes due to structural strength-to-weight ratios and anodizing compatibility, though glass blade variants command premium positioning in architectural facades where transparency and thermal performance converge. The commercial application segment sustains higher average project values, while renovation and retrofit installations represent the fastest-growing installation type as existing building energy upgrades accelerate across temperate climate zones.
Fenestration compliance with Australia's National Construction Code Section J energy efficiency provisions shapes product certification pathways, while the European Union's CE marking and REACH chemical compliance frameworks govern aluminum surface treatment and coating formulations for exports. In the United States, AAMA certification and local energy code adoptions such as California's Title 24 establish performance baselines for imported systems. Stakeholders must monitor evolving embodied carbon accounting rules and circularity mandates that threaten to recast material specification priorities across project pipelines.
Market Dynamics
Multi-source procurement for aluminum extrusions and glazing hardware is decoupling from traditional single-source supply agreements, reshaping competitive positioning across the louvre window industry as fabricators seek supply security and cost flexibility.
Growth Catalysts
- Australia's National Construction Code Section J:Tightening energy efficiency provisions are mandating higher-performance glazing systems, accelerating specification of thermally broken aluminum frames and low-emissivity glass blades in commercial developments.
- Passive cooling architecture:Subtropical climate design across Queensland and New South Wales prioritizes operable louvre systems for natural ventilation, driving renovation volumes in existing building envelopes.
- Embodied carbon accounting:Emerging circularity mandates and lifecycle assessment frameworks are recasting material specification priorities toward recycled aluminum content and low-carbon glass production.
Market Restraints
- Aluminum price volatility:LME aluminum futures and energy-intensive smelting costs create margin compression for extrusion-dependent fabricators without captive supply.
- Coastal cyclone ratings:Australian Standards AS 2047 and AS 1170.2 impose stringent structural testing requirements that limit supplier participation in high-wind regions.
- Fixed glazing substitution:Curtain wall systems with integrated mechanical ventilation are displacing operable louvre specifications in premium commercial towers.
Strategic Opportunities
- Retrofit installation channel:Existing building energy upgrades across temperate Australian climate zones represent underpenetrated demand for blade replacement and frame conversion kits.
- Smart building convergence:Integration of automated louvre actuation with building management systems and rain sensors opens premium positioning in institutional and healthcare verticals.
- Southeast Asian commercial development:Natural ventilation specifications in Singapore, Malaysia, and Indonesian office towers are expanding export volumes for cyclone-rated coastal systems.
Industry Challenges
- Certification timeline compression:Australia's National Construction Code adoption cycles and state-level variations create compliance lag for new product introductions.
- Skilled installation labor:Qualified glazing contractors capable of achieving weatherproofing and acoustic performance thresholds remain concentrated in metropolitan Queensland and New South Wales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Louvre Windows Market |
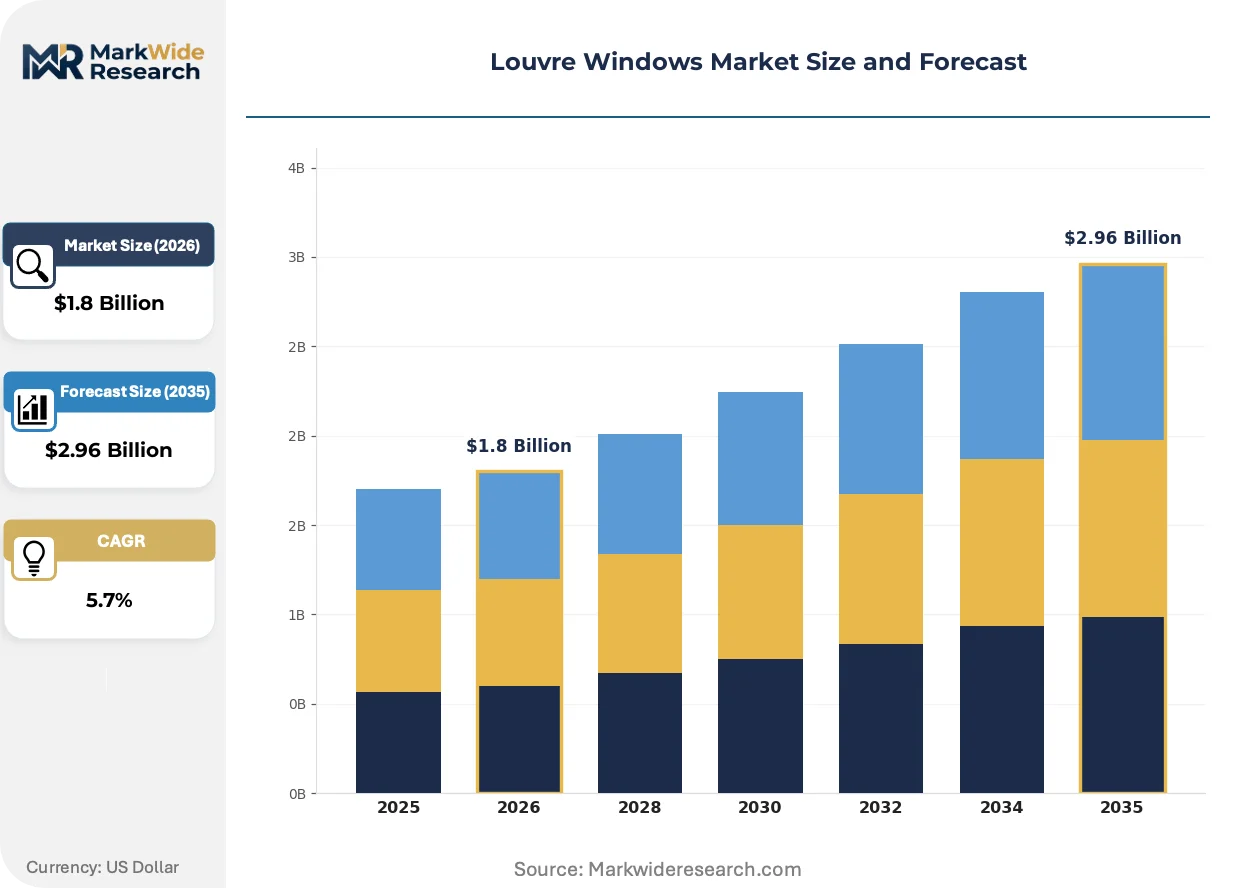
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Glass, PVC, Timber Application: Residential, Commercial, Industrial, Architectural Installation Type: New Construction, Renovation, Retrofit, DIY Design Style: Modern, Traditional, Contemporary, Eco-Friendly |
| Companies Covered | G.James Glass & Aluminium, SEPALUMIC, Schüco, Fieger Lamellenfenster GmbH, COLT, Reynaers Aluminium, PROFILS SYSTEMES, YKK AP, Breezway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Louvre Windows Market Shifts & Advancements
Automation and sensor integration are transforming louvre windows from passive ventilation elements into active building envelope components, while regulatory pressure on embodied carbon is recasting material selection criteria across specification pipelines.
Automated louvre actuation systems with integrated rain sensors and wind-speed monitors are integrating with BACnet and Modbus building management protocols. Commercial office developers in Brisbane and Sydney are specifying these systems for facade zones requiring dynamic environmental response. This convergence is integrating louvre windows into holistic envelope strategies that compress commissioning timelines and reduce mechanical HVAC redundancy.
The European Union's CE marking and REACH chemical compliance frameworks are governing aluminum surface treatment and coating formulations for export-oriented Australian manufacturers. Industrial consequences include reformulation of powder coating chemistries and anodizing bath management to eliminate hexavalent chromium and restricted phthalates. Australian fabricators targeting European project work are responding by establishing dual-certified production lines with segregated finishing workflows.
Project bundling through facade system integrators is consolidating procurement authority away from standalone window contractors. Commercial developers in Melbourne and Perth are awarding turnkey envelope contracts that subsume louvre specification within broader curtain wall packages. This channel consolidation is most visible in premium mixed-use towers where single-source accountability reduces interface risk between operable and fixed glazing zones.
Louvre Windows Market Segmentation
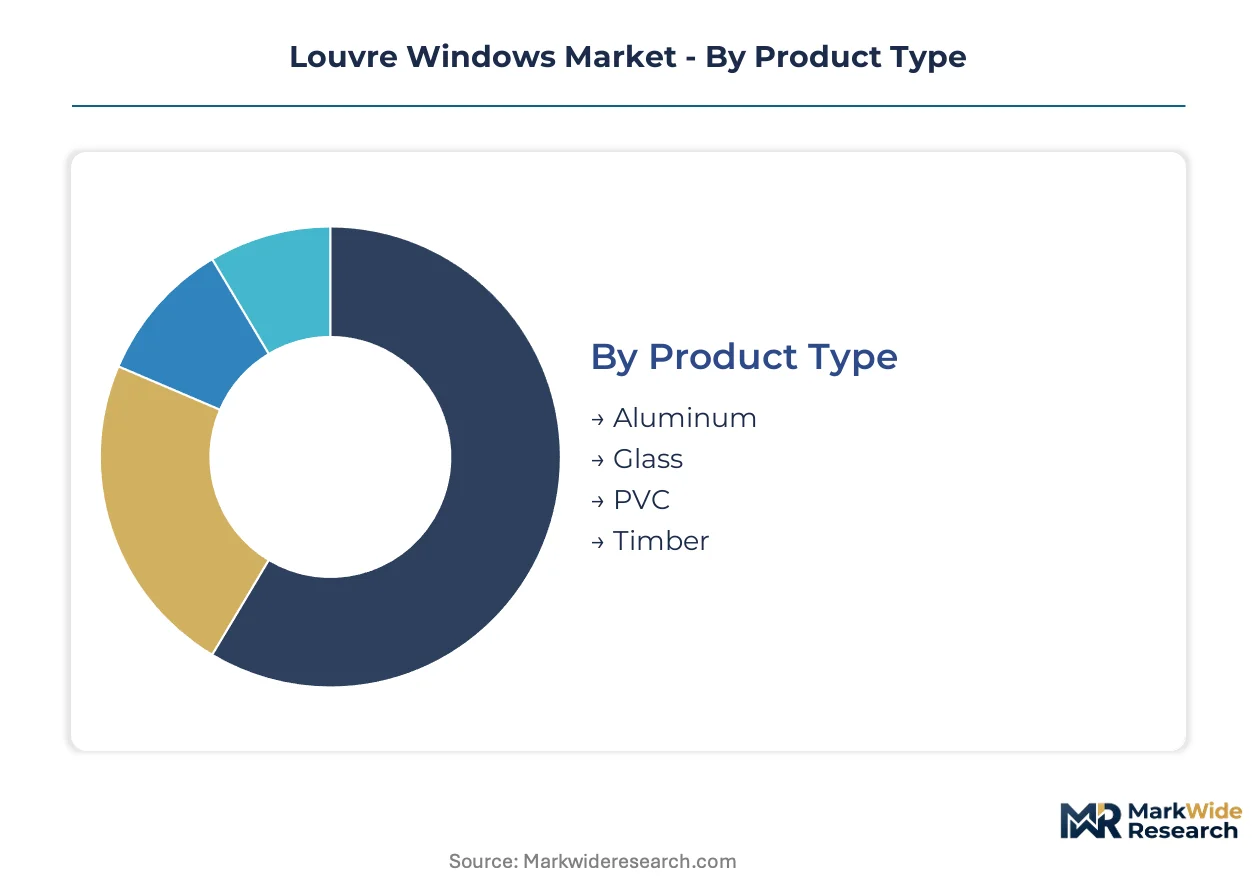
Louvre window procurement decisions cascade through material performance, building typology, installation logistics, and aesthetic positioning. Specification authority varies sharply across these dimensions, with architects driving material selection while contractors control installation channel economics.
Product Type:
Structural load requirements and coastal exposure ratings dominate material specification, creating divergent cost-performance tradeoffs across extrusion-dependent categories.
- Aluminum:Extruded aluminum profiles deliver superior strength-to-weight ratios and anodizing compatibility for cyclone-rated coastal installations. Queensland and New South Wales commercial developments specify thermally broken variants to satisfy National Construction Code Section J energy efficiency provisions.
- Glass:Tempered glass blades command premium positioning in architectural facades where transparency and thermal performance converge. Singapore and Malaysian office towers drive specification volumes for low-emissivity coated variants integrated with automated actuation systems.
- PVC:Polyvinyl chloride frames offer cost-competitive moisture resistance for residential renovation channels in temperate climate zones with moderate wind loading.
- Timber:Hardwood and engineered timber variants satisfy heritage overlay requirements and biophilic design specifications in premium residential segments.
Volume sits with Aluminum; growth tilts toward Glass.
Application:
Project scale and performance certification thresholds segment demand across building typologies with diverging procurement authority structures.
- Commercial:Office towers and institutional buildings sustain higher average project values through facade-integrated natural ventilation systems. Brisbane and Sydney developers specify automated louvre banks with BACnet-connected rain sensors and wind-speed monitors.
- Residential:Single-family and multi-family housing drives volume through subtropical climate design prioritizing operable systems for passive cooling. Queensland renovation activity concentrates demand for blade replacement kits in existing envelopes.
- Industrial:Warehousing and manufacturing facilities prioritize high-airflow configurations with minimal maintenance requirements for ventilation-dominant envelopes.
- Architectural:Signature buildings and cultural institutions commission custom-engineered systems with non-standard blade geometries and specialized surface finishes.
Commercial captures value concentration; Residential expands most quickly.
Installation Type:
Channel economics and skilled labor availability shape competitive positioning across project delivery modes with diverging margin profiles.
- New Construction:Greenfield developments enable integrated envelope design with coordinated structural support and weatherproofing interfaces. Melbourne and Perth mixed-use towers bundle louvre specification within turnkey curtain wall contracts.
- Renovation:Existing building energy upgrades across Australian temperate climate zones drive demand for frame conversion kits and blade replacement systems. National Construction Code tightening accelerates specification of thermally improved variants.
- Retrofit:Deep energy retrofits in commercial building stocks require structural assessment and custom engineering for load-bearing capacity verification.
- DIY:Standardized dimension products serve residential owner-installer segments through hardware retail channels with simplified weatherstripping and operation hardware.
New Construction anchors current volume; Renovation gains share fastest.
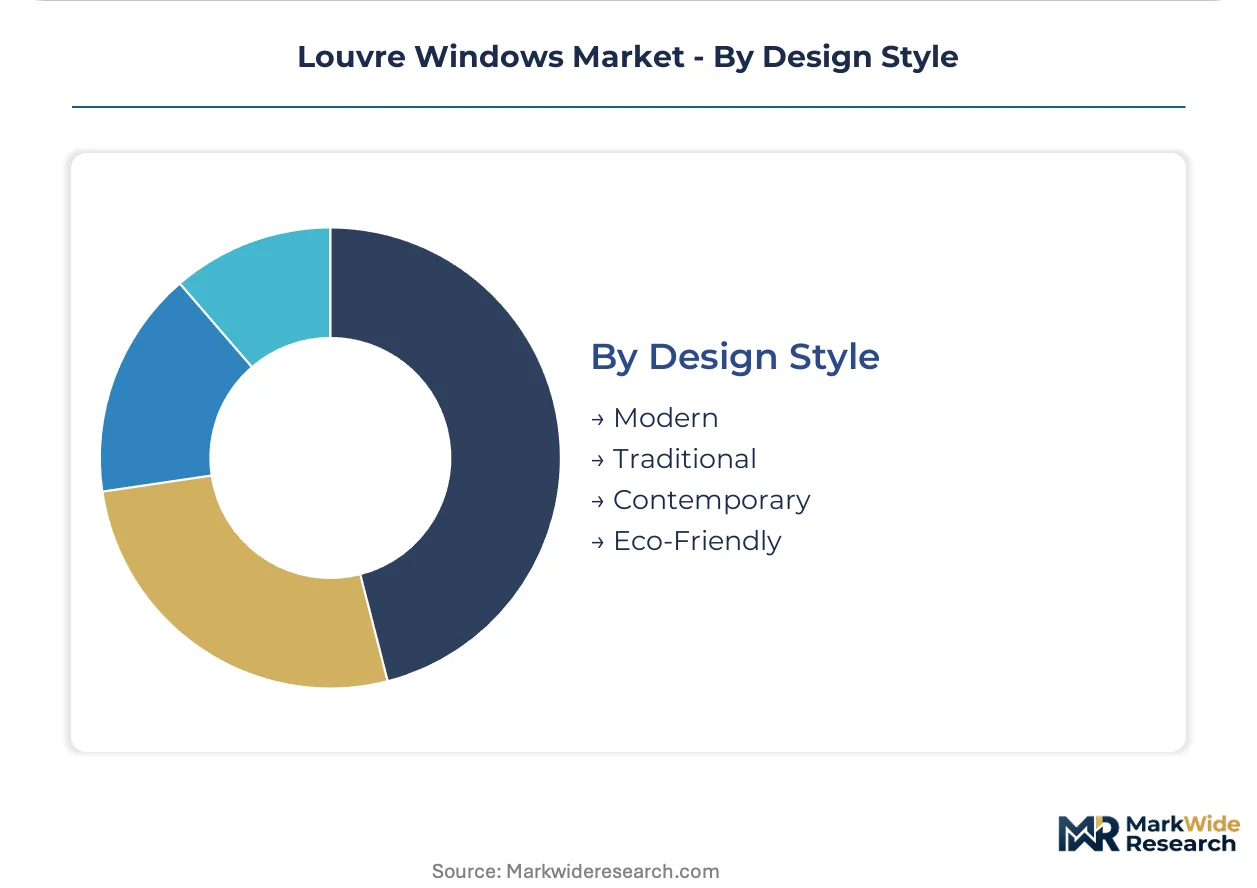
Design Style:
Aesthetic positioning and sustainability signaling segment demand across project types with diverging client priorities and certification requirements.
- Modern:Minimalist profiles with concealed hardware and matte anodized finishes dominate contemporary commercial and residential specifications. Clean sightlines satisfy architectural facade integration requirements.
- Eco-Friendly:Recycled aluminum content and low-carbon glass production address emerging embodied carbon accounting mandates. Circular material specifications respond to lifecycle assessment frameworks in European export markets.
- Traditional:Heritage-appropriate proportions and surface textures satisfy conservation overlay requirements in established residential precincts.
- Contemporary:Hybrid aesthetics blending modern performance with contextual references serve infill developments in transitioning urban neighborhoods.
Modern holds specification dominance; Eco-Friendly climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelting capacity in Queensland and bauxite refining clusters in Western Australia anchor the Asia-Pacific louvre window supply base. Fabricators concentrate near coastal extrusion facilities to minimize logistics costs for architectural glazing projects.
Australia
Subtropical climate design across Queensland and New South Wales drives specification of operable louvre systems for passive cooling in commercial and residential envelopes. The National Construction Code Section J tightening mandates thermally broken aluminum frames and low-emissivity glazing in new developments. Brisbane and Sydney fabricators cluster near captive float-glass capacity and extrusion presses to serve renovation volumes in existing building stocks.
Singapore
Natural ventilation specifications in premium office towers and institutional buildings sustain demand for automated louvre banks with building management system integration. The Building and Construction Authority Green Mark certification incentivizes facade-integrated environmental controls. Marina Bay and Jurong East commercial developments specify low-emissivity glass blade variants for thermal performance compliance.
Malaysia
Iskandar Malaysia and Kuala Lumpur commercial corridors expand procurement volumes for cyclone-rated coastal systems as high-rise development accelerates. The Construction Industry Development Board Malaysia governs material certification and installer licensing for weatherproofing performance. Johor Bahru fabricators serve cross-border project demand from Singapore developers seeking cost-competitive supply.
Indonesia
Jakarta and Surabaya office tower construction prioritizes natural ventilation to reduce mechanical cooling loads in tropical climates. The national building code SNI establishes structural and energy efficiency baselines for glazing systems. Bekasi industrial zones host aluminum extrusion facilities supplying fabrication workshops across the Greater Jakarta metropolitan area.
Germany
Energy-efficient building renovation programs and passive house standards drive specification of thermally optimized louvre systems in commercial retrofits. The Federal Ministry for Economic Affairs and Climate Action oversees funding mechanisms for envelope energy upgrades. Stuttgart and Munich architectural practices specify automated actuation systems with BACnet integration for institutional clients.
Louvre Windows Market Competitive Landscape
Strategic partnerships between facade system integrators and aluminum extruders dominate the current landscape as procurement authority consolidates toward turnkey envelope contractors. The vendor base separates into three tiers: multinational profile system suppliers with certification networks, regional fabricators with captive glass capacity, and specialized coastal-system engineers with cyclone-rating expertise. Two strategic archetypes occupy distinct positions: vertically integrated manufacturers controlling upstream extrusion and downstream installation channels, and technology-focused specialists concentrating on automated actuation and sensor integration. Geographic expansion into Southeast Asian commercial corridors and portfolio diversification into smart building convergence represent the dominant competitive moves.
Among Australia-based fabricators, G.James Glass & Aluminium and Breezway occupy positions reflecting different strategic archetypes. G.James exemplifies the vertically integrated model with captive float-glass and extrusion assets across Queensland and Victoria. Breezway represents the coastal-system specialist archetype, engineered for cyclone-rated installations. European profile system suppliers including Reynaers Aluminium and Schüco anchor the multinational tier through CE-marked product ranges and REACH-compliant surface treatment workflows serving export-oriented project specifications.
| Leading Market Players |
|---|
| G.James Glass & Aluminium |
| SEPALUMIC |
| Schüco |
| Fieger Lamellenfenster GmbH |
| COLT |
| Reynaers Aluminium |
| PROFILS SYSTEMES |
| YKK AP |
| Breezway |
| Others |
Supply & Pricing Matrix
Facade system integrators in Australian commercial towers command project-level pricing authority through bundled envelope contracts that subsume louvre specification within turnkey curtain wall packages. This procurement concentration rewards suppliers with captive extrusion capacity and dual-certified production lines, while squeezing margins for fabricators dependent on spot-market aluminum sourcing.
Pricing Analysis
Warranty bundling separates premium-tier suppliers offering cyclone-rating certification with automated actuation integration from unbundled economy providers serving residential renovation channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—AS 2047 cyclone-rated systems with BACnet connectivity command substantial premiums over basic powder-coated residential variants. Cost compression in the standard tier is intensifying because aluminum extrusion fabricators without captive float-glass capacity face margin pressure from Queensland-based vertically integrated competitors. Price sensitivity concentrates in residential renovation channels where owner-installers compare blade replacement kits through hardware retail, while institutional healthcare buyers prioritize performance certification over unit economics.
Supply Chain Analysis
Regional distribution centers in Brisbane and Sydney operate hub-and-spoke patterns radiating to Queensland and New South Wales installation contractors, with secondary nodes serving Melbourne and Perth mixed-use tower projects. Supply concentrates in Australia, China, and Germany—Australian fabricators draw from domestic bauxite refining clusters in Western Australia and captive float-glass capacity in Queensland, while European profile system suppliers anchor premium specification through CE-marked extrusion networks. Raw material dependencies rest on LME aluminum ingot, tempered glass substrates, and powder-coating chemistries reformulated for REACH compliance. Single-source vulnerability threatens fabricators lacking multi-source procurement for glazing hardware, as traditional supply agreements decouple amid energy-intensive smelting cost volatility. Distribution runs through facade system integrators consolidating procurement authority away from standalone window contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's National Construction Code Section J tightening functions as a cost-of-compliance moat, elevating thermally broken aluminum frames and low-emissivity glazing from optional upgrades to mandatory specifications that filter out uncertified competitors.
For Market Incumbents: Lock in cyclone-rating certification maintenance through AS 2047 and AS 1170.2 testing protocol investments that emerging entrants cannot replicate without capital-intensive coastal exposure validation. Defend position by deepening backward integration into captive float-glass production and extrusion press capacity across Queensland and Victoria, neutralizing aluminum price volatility exposure that threatens margin-dependent competitors. Channel control through facade system integrator partnerships secures specification authority in premium commercial towers where project bundling consolidates procurement. For New Entrants and Emerging Players: E-commerce direct-to-contractor platforms offer lowest-friction entry into residential renovation channels where standardized dimension products bypass complex facade integration requirements. Target existing building energy upgrade segments in temperate Australian climate zones—retrofit installation of blade replacement kits and frame conversion systems faces less entrenched incumbent presence than new construction bundled within curtain wall contracts. Digital specification tools enabling owner-installer self-service configuration accelerate penetration of hardware retail channels concentrated in metropolitan Queensland and New South Wales. For Investors and Strategic Acquirers: The window for entry favors coastal-system specialists with cyclone-rated engineering capabilities and automated actuation integration expertise, as Southeast Asian commercial corridor expansion sustains export demand for premium facade-integrated environmental controls. Long-term viability hinges on positioning for smart building convergence where BACnet-connected louvre banks compress commissioning timelines and reduce mechanical HVAC redundancy in institutional and healthcare verticals. Monitor embodied carbon accounting mandate adoption across European export markets as the inflection signal—recycled aluminum content and low-carbon glass production capabilities will recast acquisition premiums for dual-certified production line operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Extrusion | Queensland-based float-glass and extrusion press ownership neutralizes aluminum price volatility exposure for fabricators. |
| Dual-Certification Production Line Establishment | Segregated REACH-compliant finishing workflows unlock European export market access for Australian manufacturers. |
| Automated Actuation System Development | BACnet and Modbus protocol integration positions louvre systems within smart building convergence in Brisbane and Sydney towers. |
| Retrofit Channel Infrastructure Buildout | Blade replacement kit distribution through hardware retail captures accelerating existing building energy upgrade volumes. |
| Southeast Asian Export Partnership | Singapore Green Mark certification alignment expands specification authority in Marina Bay and Jurong East commercial developments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with facade system integrators, glazing contractors, aluminum extrusion plant managers, and commercial development procurement leads across Queensland, New South Wales, Victoria, and Western Australia. Secondary validation drew from Australian Building Codes Board documentation, National Construction Code adoption records, Australian Standards AS 2047 and AS 1170.2 testing protocols, and Building and Construction Authority Singapore Green Mark certification databases. Bottom-up project pipeline analysis triangulated against top-down construction spend forecasts to establish volume baselines.
Data-stream reconciliation across fabrication capacity surveys, import-export customs classifications for aluminum extrusions and tempered glass, and commercial building permit filings shaped the analytical framework across the analysis window. Segmentation modeling captured material type, application typology, installation channel, and design style dimensions, with additional granularity for climate-zone specification patterns across subtropical and temperate Australian regions. CAGRs derived from trend extrapolation of National Construction Code adoption cycles and renovation activity acceleration in existing building stocks, cross-referenced against Southeast Asian commercial development pipeline disclosures.
The model holds under continued National Construction Code Section J tightening and stable aluminum smelting energy costs; deviation in embodied carbon accounting mandate acceleration or LME aluminum futures volatility would shift specification priorities and margin structures across the projection horizon. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Bulletin Board Market
Homecare and Decor
US Mattress Bases Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
Bookends Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Builders and Cabinet Hardware Market
Homecare and Decor
USA Bed Pillow Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Smart Vase Market
Homecare and Decor
Pillow Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
ASEAN UPVC Doors and Windows Market