
 Composite Doors and Windows Market | 2026-2036
Composite Doors and Windows Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Doors and Windows Market Analysis
Multi-source procurement of glass fiber and resin intermediates is expanding across the composite doors and windows supply base. Andersen Corporation leverages captive pultrusion capacity to control fiberglass composite quality from raw fiber through finished sash. Pella Corporation anchors its position through advanced glazing integration that sustains premium pricing in the replacement segment. JELD-WEN competes on manufacturing scale, operating multiple extrusion and pressing lines that serve both residential new construction and renovation channels.
Composite doors and windows are engineered building envelope products combining thermoset or thermoplastic matrices with reinforcing fibers to achieve structural rigidity, thermal insulation, and moisture resistance superior to conventional timber or hollow vinyl units. Pultrusion and resin transfer molding produce profiles with consistent dimensional stability across temperature cycles, serving the primary purpose of reducing building energy loss while extending maintenance intervals. Fiberglass composite windows command the highest performance tier in cold-climate residential applications where thermal bridging constraints are tightest. PVC composite products occupy the volume-driven replacement segment, with margin pools concentrated in custom color and hardware upgrade configurations.
F-Gas Regulation and REACH compliance in Europe, alongside EPA energy efficiency guidelines in the United States, mandate lower U-values and reduced embodied carbon in fenestration products, directly steering R&D budgets toward bio-based resins and recycled fiber content. The EU Green Deal's building renovation wave requirements and California's Title 24 energy standards both tighten thermal performance thresholds, filtering market access toward suppliers with certified testing laboratory relationships. Stakeholders must monitor regulatory divergence between North American and European thermal performance metrics when allocating product development resources across regional manufacturing footprints.
Market Dynamics
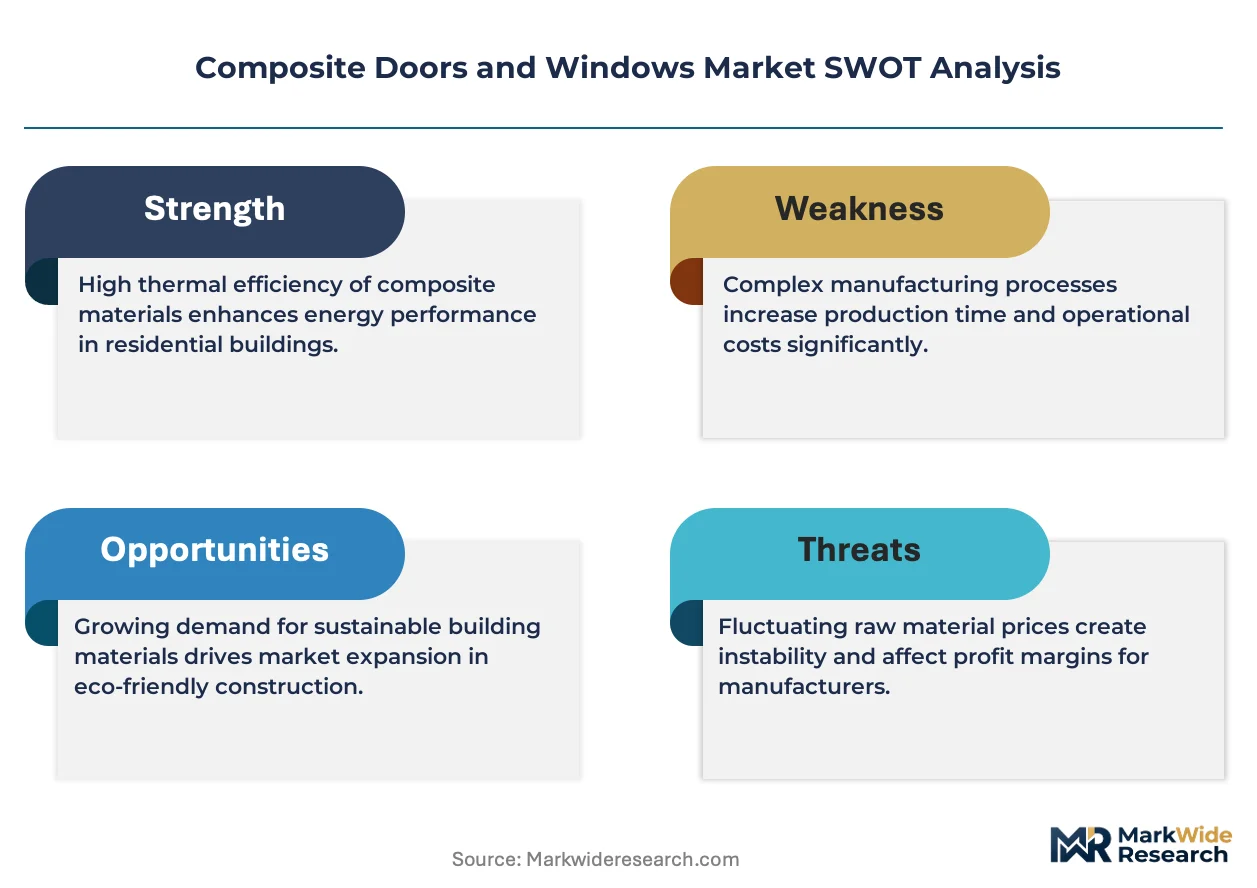
EU Green Deal thermal performance mandates are compressing specification cycles for fenestration products, forcing suppliers to requalify entire product lines against tightening U-value thresholds while simultaneously managing resin and fiber input cost volatility.
Growth Catalysts
- EU Green Deal renovation wave:Mandatory building envelope upgrades across Germany, France, and Italy are accelerating replacement demand for certified low-U-value composite windows.
- Pultrusion automation:Continuous fiber placement technology is reducing profile manufacturing variance, enabling tighter thermal bridging tolerances for cold-climate residential specifications.
- Suburban housing cluster density:North American replacement contractors are standardizing PVC composite window packages for tract-home renovation projects at scale.
Market Restraints
- Epoxy and vinyl ester resin cost volatility:Petrochemical feedstock price swings compress margin predictability for thermoset composite manufacturers.
- Glass fiber supply concentration:Three Asian producers control over 60% of E-glass roving supply, creating geographic concentration risk for Western pultrusion operators.
- Timber-aluminum hybrid substitution:Premium residential architects in Scandinavia and Austria continue specifying wood-clad aluminum for heritage-sensitive renovations.
Strategic Opportunities
- India affordable housing mandate:The Pradhan Mantri Awas Yojana urban housing targets create volume demand for cost-optimized PVC composite window systems.
- Retrofit glazing integration:Vacuum-insulated glass converging with pultruded fiberglass frames enables single-pane replacement without full sash removal.
- Direct-to-developer digital specification:Building information modeling platforms are disintermediating traditional distributor channels for mid-rise residential projects.
Industry Challenges
- Passive house certification timeline:Third-party thermal modeling and blower-door testing extends product launch cycles by 8-14 months for European market entry.
- Multi-material recycling infrastructure:Separating thermoset matrices from embedded glass fibers at end-of-life lacks scaled industrial processing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Doors and Windows Market |
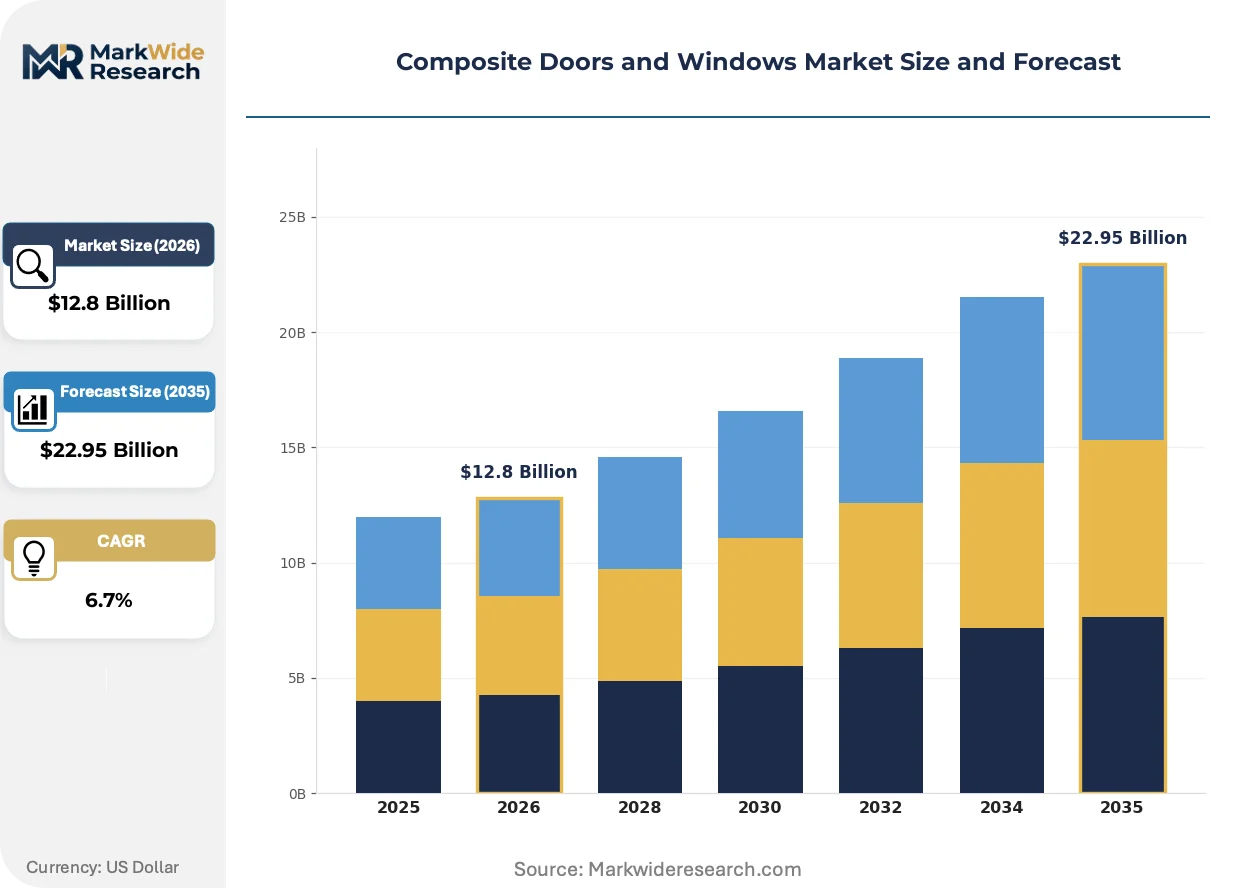
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Entrance Doors, Patio Doors, Windows, Bi-Folding Doors Material: Wood Composite, PVC Composite, Aluminum Composite, Fiberglass Composite End User: Residential, Commercial, Industrial, Retail Installation Type: New Construction, Replacement, Renovation, Retrofit |
| Companies Covered | Andersen Corporation, Pella Corporation, JELD-WEN, Masonite International, Schüco International, Veka AG, Rehau, Dortek Ltd, Special-Lite Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Doors and Windows Market Emerging Trajectories
Bio-based resin formulations and automated quality sensing are compressing the performance gap between premium fiberglass and volume PVC segments while regulatory testing burdens intensify.
Pultruded basalt fiber reinforcement is absorbing specification share from traditional E-glass in high-humidity coastal applications. Florida and Gulf Coast residential developers are adopting basalt-composite door frames for corrosion resistance. The material shift is absorbing margin pressure from glass fiber price volatility by reducing resin content requirements per linear meter.
REACH SVHC candidate list expansion is forcing reformulation of legacy phthalate plasticizers in PVC composite profiles. ECHA substance evaluation is driving substitution costs for compounders serving the replacement window segment. German and French fabricators are accelerating bio-based plasticizer qualification to maintain CE marking continuity.
Renovation contractors are consolidating purchasing through regional buying cooperatives, displacing traditional two-step distribution. Independent installers across Texas, Arizona, and Colorado are pooling volume for direct mill negotiation. The channel restructuring is most visible in suburban Sun Belt markets where replacement demand exceeds new construction by three-to-one.
Composite Doors and Windows Market Segmentation
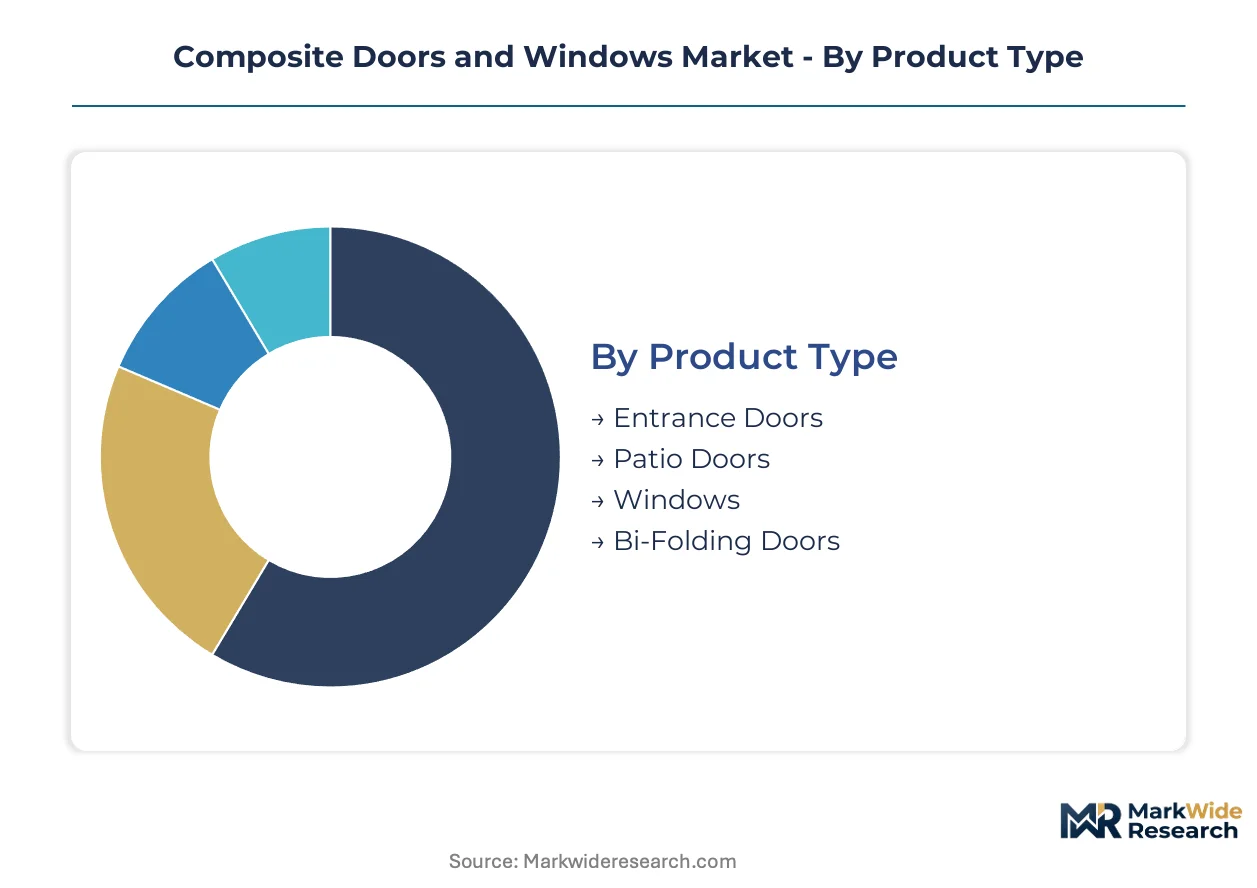
Composite doors and windows segment across material chemistry, product architecture, and installation context. Each axis carries distinct margin profiles and regulatory qualification burdens that shape supplier resource allocation.
Product Type:
Product architecture determines thermal bridging complexity and hardware integration requirements.
- Entrance Doors:Fiberglass-reinforced thermoset matrices dominate cold-climate specifications for structural rigidity and thermal performance. German, French, and United Kingdom residential developers specify these units to meet EU Green Deal thermal performance rules. REACH compliance and F-Gas Regulation alignment add qualification overhead for European market entry.
- Windows:Pultruded profiles with multi-chamber designs achieve the lowest U-values in the product range. PVC composite windows absorb volume demand in North American suburban housing clusters and East Asian replacement cycles. Vacuum-insulated glass integration is compressing frame thermal bridging tolerances.
- Patio Doors:Multi-panel sliding systems with composite frames balance thermal performance against hardware load capacity.
- Bi-Folding Doors:Hinge-intensive configurations demand high dimensional stability across temperature cycles to prevent operational binding.
Mature deployment sits with Windows. Newer deployment is concentrated in Bi-Folding Doors.
Material:
Matrix chemistry and fiber reinforcement type segment the market across performance tiers and cost structures.
- Fiberglass Composite:E-glass or basalt fiber in thermoset matrices delivers the highest strength-to-weight ratio and thermal stability. Basalt fiber reinforcement is absorbing specification share in Florida and Gulf Coast coastal applications for corrosion resistance. Pultrusion automation is reducing manufacturing variance for cold-climate residential specifications.
- PVC Composite:Calcium carbonate or wood flour filled thermoplastic profiles dominate replacement volume with lower raw material cost exposure. REACH SVHC candidate list expansion is forcing reformulation of legacy phthalate plasticizers. Bio-based plasticizer qualification is accelerating among German and French fabricators.
- Wood Composite:Wood flour or fiber in thermoplastic or thermoset binders serves heritage-sensitive renovations where timber aesthetics are mandated.
- Aluminum Composite:Thermally broken aluminum-clad systems bridge composite cores for premium architectural specifications.
Volume concentration sits with PVC Composite. Performance premium capture is concentrated in Fiberglass Composite.
End User:
Customer type determines specification authority, batch size, and service intensity.
- Residential:Single-family and multi-family housing drives replacement cycles and new construction specification. India Pradhan Mantri Awas Yojana urban housing targets are creating volume demand for cost-optimized PVC composite window systems. Direct-to-developer digital specification through building information modeling platforms is disintermediating traditional distributor channels.
- Commercial:Mid-rise office and hospitality projects require certified thermal modeling and blower-door testing for Passive house or equivalent standards.
- Industrial:Facility envelope upgrades prioritize durability and maintenance interval extension over thermal performance optimization.
- Retail:Storefront and showroom applications demand rapid lead times and custom color configurations.
Replacement volume sits with Residential. Specification complexity is climbing fastest in Commercial.
Installation Type:
Installation context determines product sizing, anchoring hardware, and regulatory compliance pathway.
- Replacement:Retrofit of existing openings without structural modification dominates North American suburban housing cluster demand. Regional buying cooperatives among Texas, Arizona, and Colorado contractors are consolidating purchasing volume for direct mill negotiation. Custom color and hardware upgrade configurations concentrate margin pools.
- New Construction:Rough opening integration allows optimized thermal bridging design from project inception. EU Green Deal renovation wave requirements are accelerating certified low-U-value composite window demand across Germany, France, and Italy.
- Renovation:Building envelope upgrades with partial structural modification require flexible sizing and custom fabrication.
- Retrofit:Single-pane replacement without full sash removal is enabled by vacuum-insulated glass converging with pultruded fiberglass frames.
Volume scale sits with Replacement. Technical innovation is concentrating in Retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-glass roving supply concentrates in Asian manufacturing clusters, yet specification authority for high-performance composite fenestration sits with European and North American building codes. Raw fiber availability and finished product qualification operate on separate geographic tracks.
United States
Suburban housing clusters across Texas, Arizona, and Colorado are consolidating replacement demand through regional buying cooperatives. EPA energy efficiency guidelines and California Title 24 standards tighten thermal performance thresholds for fenestration products. The Sun Belt corridor from Phoenix to Houston absorbs the highest volume of PVC composite window installations.
Germany
Residential developers specify fiberglass composite entrance doors to meet EU Green Deal thermal performance mandates. F-Gas Regulation and REACH compliance create qualification overhead for market entry. The Rhine-Ruhr industrial belt hosts fabricators accelerating bio-based plasticizer qualification to maintain CE marking continuity.
China
Three Asian producers control over sixty percent of E-glass roving supply for global pultrusion operators. GB standards and MIIT industrial policy shape domestic building materials certification. The Yangtze River Delta manufacturing corridor supplies fiber intermediates to Western composite profile producers.
India
The Pradhan Mantri Awas Yojana urban housing targets generate volume demand for cost-optimized PVC composite window systems. BIS certification requirements and state-level building codes filter product specifications. Maharashtra and Gujarat industrial zones are emerging as fabrication hubs for affordable housing envelope materials.
United Kingdom
Replacement cycles in suburban housing estates drive demand for certified low-U-value composite windows under tightening building regulations. The national building control system enforces thermal bridging constraints on renovation projects. The Southeast England construction corridor channels specification decisions for mid-rise residential developments.
Composite Doors and Windows Market Vendor Landscape
Global majors compete with regional champions across material chemistry and thermal performance tiers. The vendor base stratifies between captive pultrusion operators, glazing-integrated specialists, and scale-driven extrusion houses. Three archetypes dominate: fiber-to-finish vertical integrators, premium glazing partners, and volume manufacturing platforms. Consolidation pressure concentrates on M&A activity for regional distribution access and strategic partnerships for bio-based resin supply.
Among North American fabricators, Andersen Corporation exemplifies the captive production archetype through upstream fiber control. Pella Corporation occupies a position emphasizing glazing integration for premium replacement positioning. JELD-WEN represents scale-driven manufacturing serving dual residential channels. Schüco International and Veka AG anchor European specification authority through CE-marked system solutions. Masonite International, Rehau, and Dortek Ltd sit within specialized architectural and commercial envelope segments.
| Leading Market Players |
|---|
| Andersen Corporation |
| Pella Corporation |
| JELD-WEN |
| Masonite International |
| Schüco International |
| Veka AG |
| Rehau |
| Dortek Ltd |
| Special-Lite Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap fabricators across Germany and the United States anchor supply-side discipline through multi-generational capital stewardship, insulating pricing power from short-term resin volatility while resisting private-equity margin extraction that compresses aftermarket service investment.
Pricing Analysis
Warranty and installation-service bundling separates premium fiberglass composite suppliers from unbundled PVC volume players. Three-tier pricing structure across certified Passive House, standard CE-marked, and economy replacement tiers reflects thermal performance grade and testing laboratory relationships. Cost compression in the PVC replacement segment intensifies as regional buying cooperatives consolidate contractor purchasing volume. Residential replacement contractors exhibit highest price sensitivity, while commercial developers pursuing certification absorb premium positioning.
Supply Chain Analysis
E-glass roving supply rests on Chinese, Japanese, and South Korean specialty fiber producers controlling upstream pultrusion feedstock. Thermoset epoxy and vinyl ester resins draw from petrochemical complexes in the United States, Germany, and Belgium. Single-source vulnerability concentrates in Asian E-glass supply, exposing Western fabricators to logistics chokepoint risk. Distribution runs through regional buying cooperatives and traditional two-step distributor channels serving replacement contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as REACH SVHC compliance costs and thermal testing timelines force sub-scale compounders toward exit, creating acquisition opportunities for well-capitalized system houses.
For Market Incumbents: Anchor specification authority through captive pultrusion capacity and certified testing laboratory relationships. Backward integration into bio-based resin formulation insulates margin from petrochemical volatility. Defend against timber-aluminum hybrid substitution in heritage-sensitive Scandinavian renovations by accelerating bio-based plasticizer qualification. For New Entrants and Emerging Players: Capture volume demand in India's Pradhan Mantri Awas Yojana affordable housing mandate through cost-optimized PVC composite window systems. Target direct-to-developer digital specification channels in mid-rise residential projects across Texas and Arizona Sun Belt markets. Lead with vacuum-insulated glass integration for single-pane retrofit without full sash removal. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional fabricators with CE marking continuity and established testing laboratory relationships in Germany and France. Long-term viability centers on bio-based resin qualification progress and regional buying cooperative channel access. Watch ECHA substance evaluation timelines as inflection indicator for compounder restructuring velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Resin Qualification | REACH SVHC compliance secures CE marking continuity for German and French fabricators. |
| Pultrusion Automation Investment | Continuous fiber placement reduces manufacturing variance for cold-climate specifications. |
| Regional Buying Cooperative Partnership | Direct mill access displaces traditional distributor channels in Sun Belt replacement markets. |
| Vacuum-Insulated Glass Integration | Retrofit glazing enables single-pane replacement without structural modification. |
| Certified Testing Laboratory Relationship | Passive House thermal modeling and blower-door testing accelerates European market entry. |
Methodological Framework
Independent corroboration across plant managers at pultrusion facilities, procurement leads at residential developers, distribution channel partners, and technical R&D directors at resin compounders underwrites the qualitative findings. Secondary validation draws from customs and trade data, SEC 10-K filings, ECHA substance evaluation databases, and national building control authority certification records. Bottom-up volume triangulation against top-down construction spending data anchors market sizing.
Comparable-period anchoring to historical replacement cycles and new construction permitting data structures the forecast framework across the projection horizon. Segmentation models incorporate material chemistry, product architecture, installation context, and regional regulatory cluster dimensions. CAGRs derive from regression analysis of construction output, thermal performance mandate tightening velocity, and resin price elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to E-glass supply concentration events and REACH SVHC list expansion timing. Assumptions reflect documented regulatory trajectories and construction sector demand patterns. A small set of triggers—ECHA plasticizer substitution mandates, India BIS certification acceleration, and Sun Belt cooperative consolidation velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
Smart Vase Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
Asia-Pacific Interior Doors Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
Soundproof Door Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
Bamboo Panels Market
Homecare and Decor
Pillow Cases Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
Vinyl Wallpaper Market