
 Asia-Pacific Data Center Market | 2026-2036
Asia-Pacific Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Data Center Market Analysis
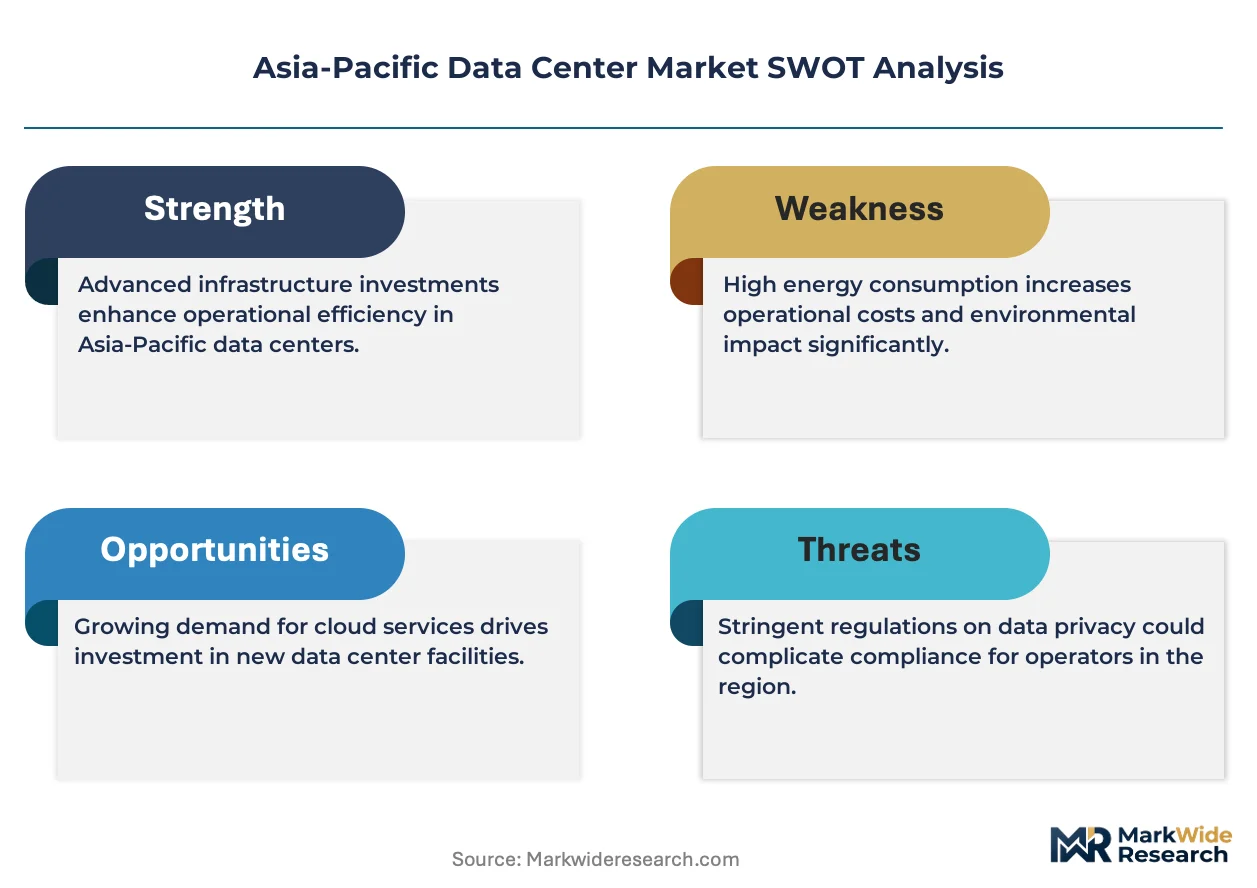
Singapore's moratorium-lifted capacity build-out is rewriting regional colocation economics. Equinix, Inc. leverages its interconnection platform density to sustain premium pricing in constrained land markets. Amazon Web Services, Inc. anchors hyperscale demand through dedicated cloud regions in Tokyo, Sydney, and Mumbai. Huawei Cloud Computing Technologies Co., Ltd competes on sovereign cloud mandates across Southeast Asian governments.
Data centers are dedicated facilities housing computing, storage, and networking infrastructure with redundant power systems maintaining 99.999% uptime, serving as the physical backbone for enterprise IT, cloud services, and digital content delivery. Hyperscale deployment dominates capital allocation, with single-campus projects exceeding 100 megawatts of critical power. Colocation operators capture expanding margin pools as enterprises exit owned facilities. Edge infrastructure remains nascent but attracts specialized investment for latency-sensitive applications in manufacturing and autonomous systems.
TRAI's data localization directives in India, Australia's Critical Infrastructure Protection Act, and Singapore's IMDA standards collectively raise compliance thresholds for cross-border operators. These frameworks shape facility design, certification requirements, and customer contracting structures across jurisdictions. Stakeholders must monitor evolving sovereign data rules and energy grid interconnection queues as primary determinants of project viability.
Market Dynamics
Hyperscale cloud providers are compressing construction timelines across Asia-Pacific, forcing colocation operators to pre-commit land and power years ahead of demand confirmation. This capital-frontloading dynamic is restructuring risk allocation between developers and anchor tenants.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Localized server and component production is reducing import dependency for facility builds. Domestic supply chain maturation accelerates deployment velocity in Mumbai and Chennai clusters.
- Submarine cable landings:Singapore's cable hub density creates natural interconnection gravity that pulls financial services and content delivery networks into proximate facilities. Latency arbitrage sustains premium absorption.
- AI training workloads:GPU-intensive applications are demanding 50-100 megawatt contiguous blocks that only purpose-built campuses can provision. This workload category is reshaping power density specifications across new builds.
Market Restraints
- Land scarcity in Singapore:The city-state's lifted moratorium has not expanded developable parcels, constraining greenfield options to brownfield expansions and vertical builds. Site competition intensifies cost structures.
- Grid interconnection queues:Utility approval timelines in Australia and Japan extend 18-36 months for multi-hundred-megawatt connections. Developer carry costs accumulate during regulatory limbo.
- Liquid cooling retrofit complexity:Legacy air-cooled facilities face stranded asset risk as thermal design power thresholds exceed 30 kilowatts per rack. Capital destruction looms for first-generation builds.
Strategic Opportunities
- Indonesia's emerging corridor:Batam and Jakarta offer submarine cable access with lower land and power costs than Singapore. Sovereign data requirements are pulling government and financial workloads domestically.
- Modular edge deployment:Prefabricated micro data centers are enabling manufacturing and port automation applications that hyperscale facilities cannot serve. Telco partnerships unlock last-mile distribution.
- Green hydrogen pilot programs:Japan's METI-funded demonstrations and Australia's renewable hydrogen export ambitions are creating off-grid power alternatives for remote facilities. Early positioning secures regulatory favor.
Industry Challenges
- Specialized construction labor shortage:Critical power and cooling system installation expertise concentrates in Singapore, Sydney, and Tokyo. Regional project pipelines exceed qualified contractor capacity.
- Cross-border data flow compliance:TRAI's localization directives, Australia's Critical Infrastructure Protection Act, and Singapore's IMDA standards impose conflicting operational requirements. Multi-jurisdiction operators face architectural fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Data Center Market |
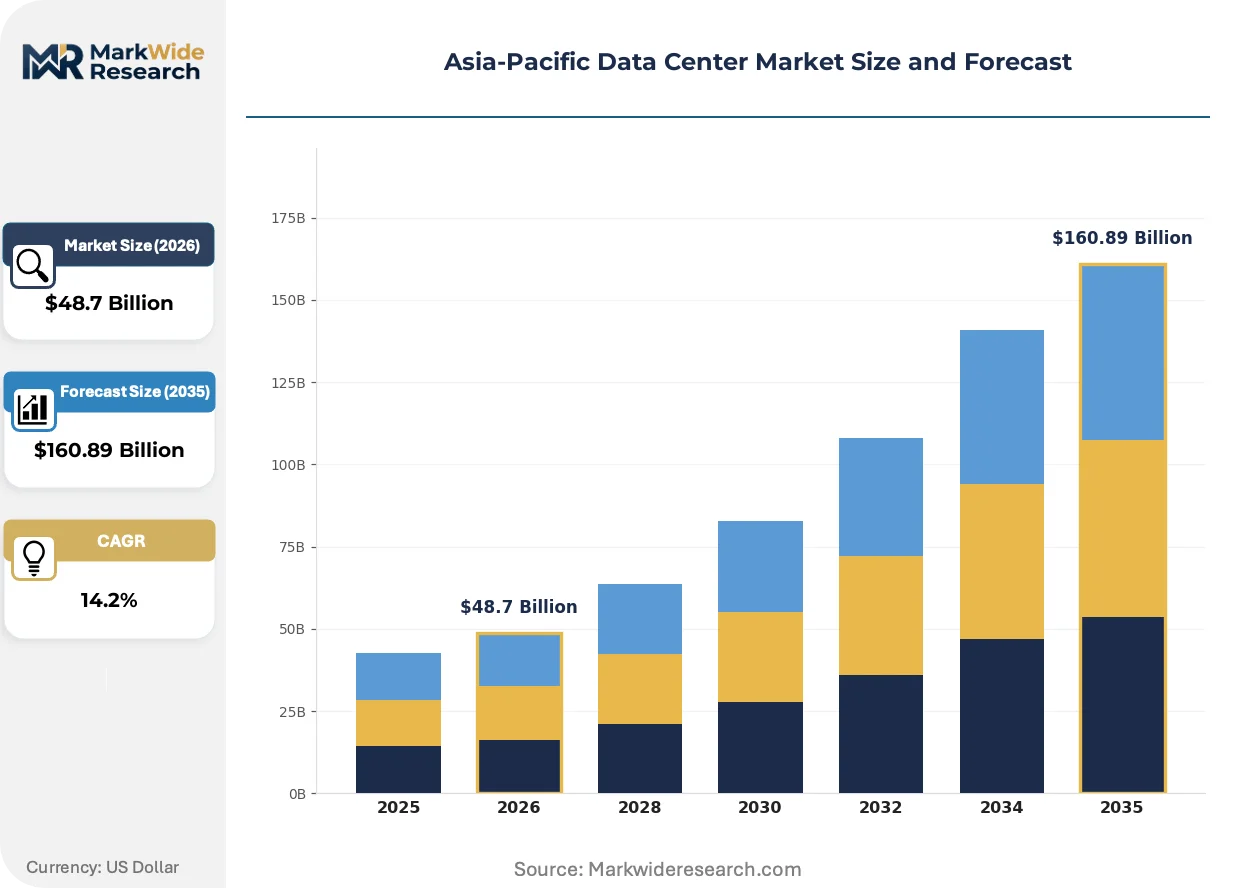
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hyperscale, Colocation, Enterprise, Edge Technology: Virtualization, Cloud Computing, Serverless Computing, Containerization End User: IT & Telecom, BFSI, Healthcare, Retail Deployment: On-premises, Cloud, Hybrid, Managed |
| Companies Covered | Equinix, Inc., Digital Realty Trust, Inc., Amazon Web Services, Inc., Huawei Cloud Computing Technologies Co., Ltd, AirTrunk Operating Pty Ltd, NTT Ltd., ST Telemedia Global Data Centres, NEXTDC, SUNeVision, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Data Center Market Emerging Trajectories
Cooling architecture is undergoing fundamental reinvention as thermal loads from AI accelerators break legacy design assumptions. Infrastructure software is decoupling from hardware, enabling multi-vendor orchestration. Sustainability metrics are hardening into procurement prerequisites rather than marketing differentiators.
Immersion cooling is hybridizing air and liquid thermal management through phase-change dielectric fluids that capture heat directly at the chip package. Hyperscale operators in Singapore and Sydney are piloting two-phase systems for 100+ kilowatt racks. The technology is compressing facility footprint requirements by eliminating raised-floor mechanical infrastructure.
Australia's Critical Infrastructure Protection Act mandates security baseline standards for data center operators handling designated critical datasets. Compliance certification now gates participation in government and financial verticals. Facilities in Sydney and Melbourne are restructuring physical access controls and supply chain vetting to satisfy mandatory audit cycles.
Enterprise procurement of colocation services is consolidating under centralized real estate and sustainability functions that previously delegated to IT. Facility selection criteria now weight power usage effectiveness and renewable energy attribution above interconnection density. This behavioral shift is most visible among European-headquartered multinationals expanding Asia-Pacific footprints.
Asia-Pacific Data Center Market Segmentation
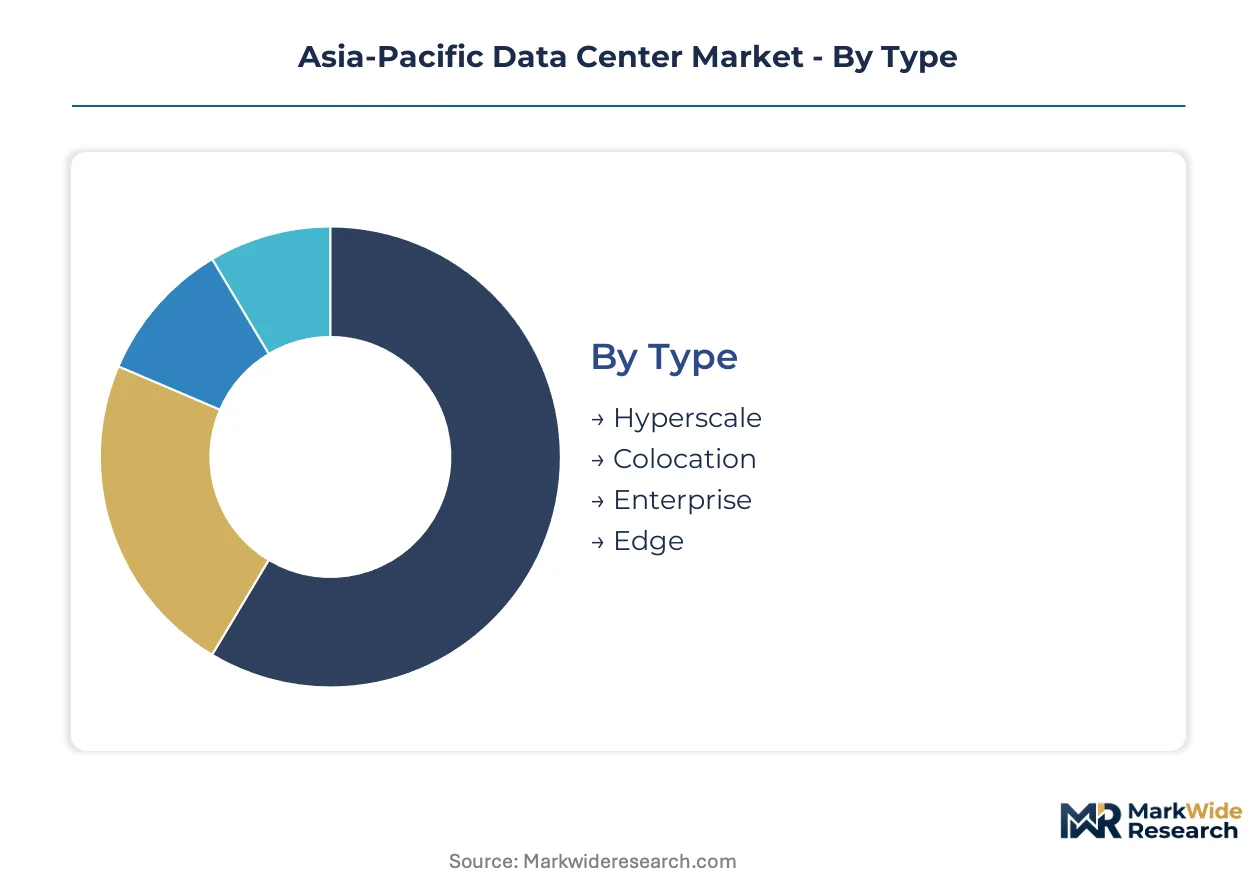
Segmentation in the Asia-Pacific data center market reveals divergent capital allocation strategies across facility types and deployment models. Understanding these divisions clarifies where hyperscale operators, enterprise IT departments, and sovereign cloud mandates concentrate procurement decisions.
Type:
Facility scale determines power procurement methods, construction timelines, and tenant mix across the use-case spectrum.
- Hyperscale:Single-tenant campuses exceeding 100 megawatts of critical power serve cloud providers and AI training workloads. Singapore, Tokyo, and Mumbai host the densest concentrations as submarine cable landings and regulatory clarity anchor investment.
- Colocation:Multi-tenant facilities lease rack, cage, or suite configurations to enterprises exiting owned infrastructure. Operators in Sydney and Singapore capture premium pricing through interconnection density and cross-connect ecosystems.
- Enterprise:Single-organization facilities retain dedicated control over security architecture and compliance workflows. Banking and defense sectors in India and Australia sustain this category despite migration pressure to third-party facilities.
- Edge:Distributed micro facilities positioned within 10 milliseconds of end-users enable manufacturing automation and autonomous vehicle processing. Indonesia and Thailand attract pilot deployments for port and logistics applications.
Established volume favors Hyperscale; emerging adoption favors Edge.
Technology:
Abstraction layers reshape how compute resources map to physical infrastructure, with cost tier determining deployment prevalence.
- Virtualization:Hypervisor-based server consolidation maximizes hardware utilization in legacy enterprise environments. Financial services in Hong Kong and Singapore maintain substantial VMware footprints during gradual cloud migration.
- Cloud Computing:On-demand resource pools from AWS, Azure, and regional providers dominate new capacity absorption. IMDA-certified facilities in Singapore and IRAP-protected sites in Australia satisfy sovereign workload requirements.
- Serverless Computing:Event-driven execution models eliminate infrastructure management overhead for variable workloads. Fintech developers in Bangalore and Jakarta leverage this tier for payment processing spikes.
- Containerization:Kubernetes-orchestrated microservices accelerate deployment velocity across DevOps pipelines. Telco edge sites in Japan and South Korea standardize on container runtimes for network function virtualization.
Containerization climbs the fastest among developer-centric organizations; virtualization retains the largest installed base.
End User:
Vertical-specific compliance and latency requirements fragment demand across customer types with diverging margin profiles.
- IT & Telecom:Carriers and cloud providers consume the majority of new power capacity. NTT and Singtel anchor demand in Tokyo and Singapore through integrated network-data center offerings.
- BFSI:Banks and insurers drive requirements for physical security, audit trails, and regulatory certification. Australia's Critical Infrastructure Protection Act and India's RBI data localization rules shape facility selection.
- Healthcare:Hospital systems and health insurers process sensitive patient data under strict jurisdiction controls. Australia's My Health Record and Singapore's HIBP compliance frameworks govern architecture decisions.
- Retail:E-commerce platforms and omnichannel operators prioritize latency for transaction processing. Flash sales and seasonal demand spikes favor hybrid deployment models across Southeast Asian markets.
BFSI commands premium pricing for certified facilities; retail expands most quickly as digital commerce penetration deepens.
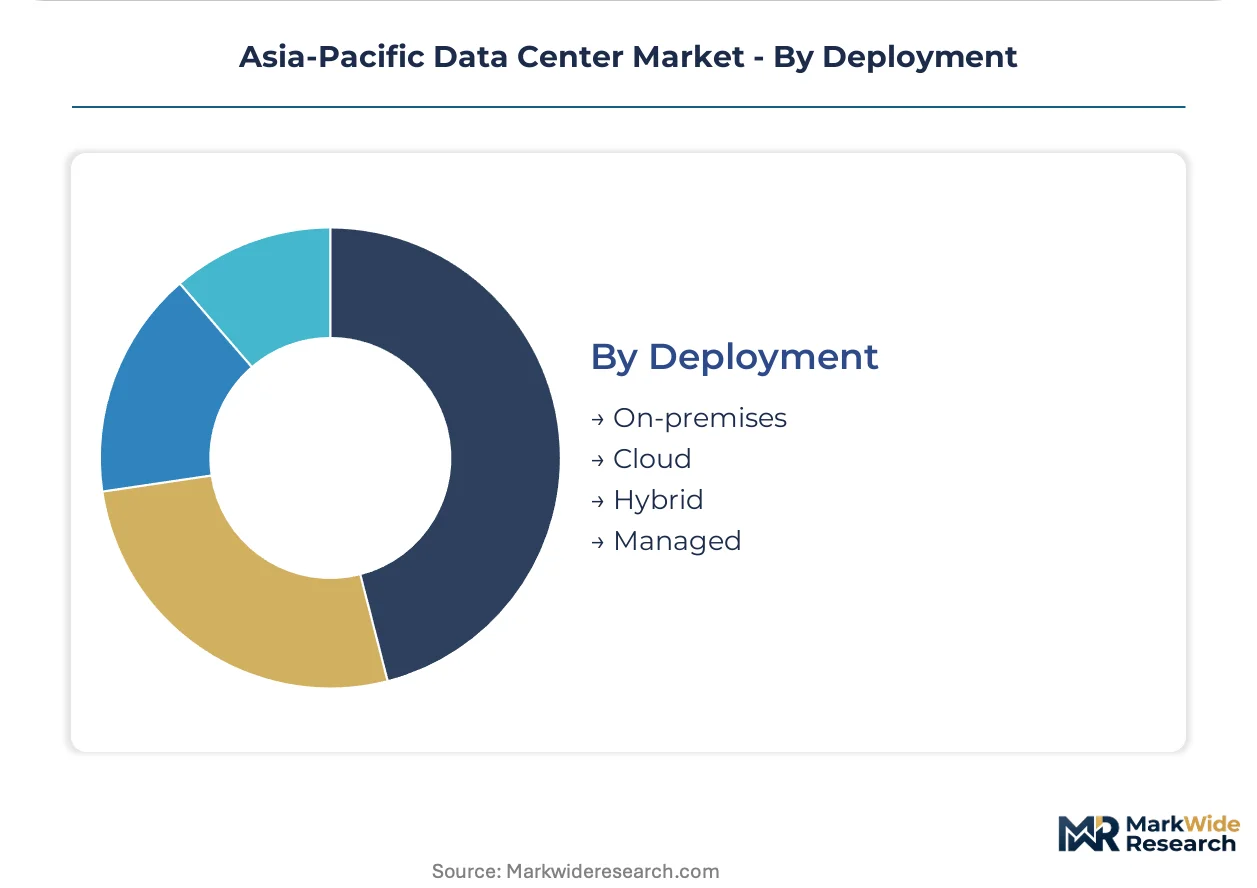
Deployment:
Control-location tradeoffs segment procurement patterns across maturity stages of cloud adoption.
- On-premises:Fully owned facilities persist where data sovereignty or ultra-low latency mandates override cost considerations. Defense and intelligence agencies in Australia and India maintain classified processing environments.
- Cloud:Public cloud consumption concentrates in AWS, Azure, and Alibaba Cloud regions. Mumbai, Sydney, and Singapore serve as primary availability zones for regional service delivery.
- Hybrid:Interconnected on-premises and cloud environments enable workload portability and disaster recovery. Financial institutions in Hong Kong and Singapore architect active-active configurations across colocation and public cloud.
- Managed:Outsourced infrastructure operations reduce staffing requirements for mid-market enterprises. Service providers in Malaysia and Thailand capture this segment through bundled network and compute offerings.
Cloud holds dominant share; hybrid gains share fastest as enterprises balance sovereignty with scalability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore absorbs premium colocation demand through submarine cable density, while India and Indonesia compete on land and power cost arbitrage. Sovereign data mandates fragment procurement patterns across jurisdictions.
Singapore
Financial services and content delivery networks cluster around cable landing stations for latency arbitrage. IMDA standards govern facility certification and operational compliance. The lifted moratorium constrains greenfield development to brownfield expansions and vertical builds in existing industrial zones.
India
Hyperscale cloud providers and AI training workloads drive campus-scale power commitments. TRAI's data localization directives mandate domestic storage for sensitive categories. Mumbai and Chennai clusters benefit from PLI scheme localization of server and component production.
Japan
GPU-intensive applications reshape power density specifications for new hyperscale facilities. METI-funded green hydrogen demonstrations create off-grid alternatives for remote deployments. Tokyo anchors demand through integrated network-data center offerings from incumbent carriers.
Australia
The Critical Infrastructure Protection Act mandates security baseline standards for operators handling designated datasets. Grid interconnection queues extend 18-36 months for multi-hundred-megawatt connections. Sydney and Melbourne facilities restructure physical access controls to satisfy mandatory audit cycles.
Indonesia
Batam and Jakarta offer submarine cable access with lower land and power costs than regional hubs. Sovereign data requirements pull government and financial workloads domestically. Telco partnerships unlock last-mile distribution for modular edge deployments in port and logistics corridors.
Asia-Pacific Data Center Market Vendor Landscape
Capability concentration sits with specialized interconnection platforms; scale advantage sits with hyperscale cloud operators with captive demand. The market structures around three tiers: global colocation platforms, sovereign cloud specialists, and carrier-integrated operators. Consolidation pressure runs through land-banked expansions and anchor tenant pre-commitments. Strategic partnerships with submarine cable consortiums and utility providers determine queue position.
Within the interconnection platform tier, Equinix, Inc. and Digital Realty Trust, Inc. represent archetypes of premium-positioned operators leveraging density for pricing power. Amazon Web Services, Inc. anchors the hyperscale vector through dedicated cloud region build-outs. Huawei Cloud Computing Technologies Co., Ltd occupies a position responding to sovereign cloud mandates across Southeast Asian government procurement.
| Leading Market Players |
|---|
| Equinix, Inc. |
| Digital Realty Trust, Inc. |
| Amazon Web Services, Inc. |
| Huawei Cloud Computing Technologies Co., Ltd |
| AirTrunk Operating Pty Ltd |
| NTT Ltd. |
| ST Telemedia Global Data Centres |
| NEXTDC |
| SUNeVision |
| Others |
Supply Flow & Price Mechanics
Server and cooling component manufacturing concentrates in China, Taiwan, and South Korea, concentrating margin capture with integrated OEMs and forcing downstream operators into long-term offtake negotiations for critical power infrastructure. This upstream consolidation reshapes how colocation providers structure tenant contracts across Singapore, Sydney, and Mumbai.
Pricing Analysis
Long-term power purchase agreements anchor hyperscale pricing, with 10-15 year offtake contracts locking in base load rates that insulate against grid volatility. Colocation operators differentiate through interconnection density and IMDA certification tier rather than commodity rack rates. Pricing pressure stems from land scarcity in Singapore compressing returns on brownfield expansions. Financial services buyers exhibit lowest price sensitivity, prioritizing latency and audit compliance over per-kilowatt costs.
Supply Chain Analysis
Upstream feedstock for critical power systems draws from China, Germany, and the United States, with diesel generators, switchgear, and uninterruptible power supply units crossing multiple tariff jurisdictions. Liquid cooling components and GPU server racks hinge on Taiwanese semiconductor foundry output and Korean memory fabrication. Single-source vulnerability concentrates in precision cooling equipment where European and Japanese suppliers dominate. Distribution runs through EPC contractors with regional project pipelines exceeding qualified installation capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI training workloads are compressing construction timelines and forcing capital-frontloading decisions years ahead of demand confirmation, creating a high-growth disruption where facility power density specifications obsolete legacy air-cooled assets.
For Market Incumbents: Entrench interconnection platform density in Singapore and Sydney through pre-committed land banking ahead of anchor tenant demand confirmation. Defend against modular edge entrants by integrating telco partnerships for last-mile distribution. Prioritize liquid cooling certification investments to avoid stranded asset risk as thermal design power thresholds exceed 30 kilowatts per rack. For New Entrants and Emerging Players: Pursue Indonesia's Batam-Jakarta corridor where submarine cable access meets lower land and power costs than regional hubs. Target sovereign cloud mandates across Southeast Asian government procurement as the most penetrable segment. Differentiate through prefabricated micro data center deployments for manufacturing automation applications that hyperscale facilities cannot serve. For Investors and Strategic Acquirers: Capital is best deployed toward land-banked developers with secured grid interconnection queue positions in Australia and Japan. Long-term viability centers on facilities capable of 50-100 megawatt contiguous blocks for GPU-intensive workloads. Watch green hydrogen pilot program outcomes as the inflection indicator for off-grid power alternatives in remote deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Land Banking Pre-Commitment | Secures developable parcels in Singapore's constrained industrial zones ahead of competitor anchor tenant capture. |
| Liquid Cooling Retrofit Program | Eliminates stranded asset risk for legacy facilities as AI workloads exceed air-cooled thermal thresholds. |
| Telco Edge Partnership | Unlocks last-mile distribution for modular micro data centers in Indonesian port and logistics corridors. |
| Green Hydrogen Pilot Positioning | Secures regulatory favor through METI-funded demonstrations and Australia's renewable hydrogen export infrastructure. |
| IMDA Certification Investment | Gates participation in Singapore government and financial verticals through mandatory security baseline compliance. |
Methodological Framework
Desk research of hyperscaler capex disclosures, submarine cable landing databases, and utility interconnection queue records preceded structured interviews with data center development executives, critical power system procurement leads, and cloud provider real estate strategists. Secondary validation drew from IMDA facility certification registries, TRAI localization directive filings, and Australia's Critical Infrastructure Protection Act compliance audits. Bottom-up project pipeline aggregation triangulated against top-down regional capacity forecasts.
Assumptions held grid interconnection timelines and sovereign data localization rules fixed across the analysis window, while AI workload power density specifications and green hydrogen cost curves were varied as sensitivity inputs. The quantitative framework modeled facility type, deployment model, and end-user vertical segmentation alongside power procurement method and cooling architecture tiers. CAGRs derived from capacity absorption rates weighted by submarine cable landing proximity and regulatory clarity indices.
Sensitivities concentrate around utility approval timeline extensions and evolving TRAI localization scope expansions. Forecasts reflect assumptions on hyperscale pre-commitment patterns and PLI scheme localization velocity. Material shifts in Australia's Critical Infrastructure Protection Act security baseline requirements or Singapore's IMDA certification standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Japan Data Center Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
Chicago Data Center Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Server Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
New Zealand Data Center Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Russia Data Center Construction Market