
 Global Brand Management Software Market | 2026-2036
Global Brand Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Brand Management Software Market Foresight
The gap between premium enterprise suites and commodity point solutions is restructuring competitive dynamics in brand management software. Adobe leverages its creative cloud ecosystem to anchor high-end workflows for global enterprises. Bynder specializes in mid-market digital asset management with strong channel control across European agencies. Brandfolder competes on interface simplicity and rapid deployment for distributed brand teams.
Brand management software comprises integrated platforms that govern digital asset repositories, brand guideline enforcement, creative workflow orchestration, and multi-channel campaign distribution through centralized cloud architectures. These systems enforce version control, metadata tagging, and access permissions to preserve brand consistency across internal teams and external partners. Cloud-based deployment leads solution offerings due to scalability demands from remote marketing operations, while digital asset management captures the largest margin pool as the foundational layer enterprises deploy first. Analytics and reporting represents the fastest-expanding segment as CMOs demand closed-loop measurement linking brand activity to revenue outcomes.
The EU AI Act and GDPR shape product development trajectories for vendors serving European enterprises, requiring automated consent tracking and algorithmic transparency in content personalization engines. The SEC's marketing disclosure rules and HIPAA data handling constraints influence how U.S.-based financial institutions and healthcare-adjacent brands configure access controls within these platforms. Stakeholders must weigh the trade-off between consolidating onto full-stack suites versus maintaining best-of-breed architectures as regulatory complexity intensifies across jurisdictions.
Market Dynamics
Multi-channel brand execution complexity is compressing procurement cycles as consumer goods enterprises abandon fragmented point solutions for unified cloud suites. The EU AI Act and GDPR compliance mandates are forcing vendors to embed governance layers directly into core architectures, reshaping R&D allocation across the competitive landscape.
Growth Catalysts
- GDPR consent automation:European enterprises require embedded data lineage tracking for personalized content engines, driving replacement demand for legacy asset repositories lacking native compliance modules.
- Remote marketing operations:Distributed creative teams across Germany, India, and the United States need centralized version control and real-time collaboration infrastructure.
- Closed-loop revenue attribution:CMOs at consumer goods firms now mandate analytics linking brand activity to sales outcomes, accelerating investment in measurement layers.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dependency for storage and compute creates vulnerability to regional outages and cross-border data transfer restrictions.
- EU AI Act algorithmic transparency:Automated content personalization engines face mandatory explainability requirements that increase development overhead and extend deployment timelines.
- Best-of-breed integration tax:Enterprises maintaining fragmented tool stacks encounter escalating middleware costs and API maintenance burden as regulatory complexity multiplies.
Strategic Opportunities
- India's digital acceleration:Mid-market enterprises in Mumbai and Bangalore are consolidating onto first-generation brand management platforms, creating whitespace for localized deployment models.
- Healthcare-adjacent verticals:HIPAA-compliant workflow configurations open penetration into pharmaceutical marketing operations currently underserved by generic solutions.
- AI-generated asset governance:Convergence of generative models with rights management systems enables automated clearance workflows for synthetic media.
Industry Challenges
- MarTech stack integration friction:Brand management platforms must reconcile with entrenched CRM, e-commerce, and marketing automation systems without disrupting live campaigns.
- Cross-functional talent scarcity:Organizations struggle to hire professionals fluent in both creative operations and data governance protocols required for platform administration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Brand Management Software Market |
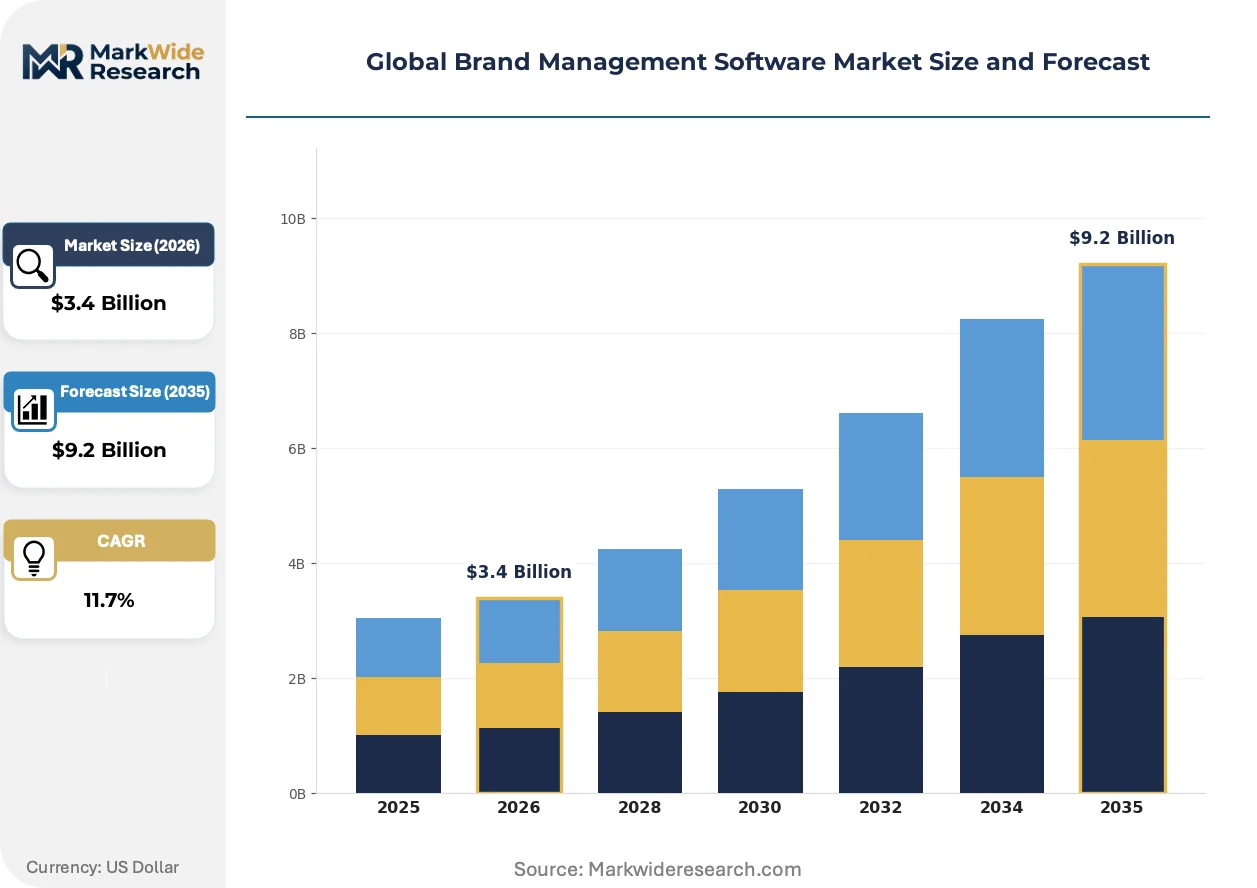
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $9.2 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Private Cloud Solution Offering: Digital Asset Management, Content Creation, Campaign Management, Analytics & Reporting, Social Media Management End User Industry: Consumer Goods Companies, Media & Entertainment Firms, Hospitality Chains, Financial Institutions, Telecommunications Providers Pricing Model: Subscription-Based, Perpetual License, Freemium, Usage-Based, Tiered Pricing |
| Companies Covered | Adobe, Bynder, Brandfolder, Brandwatch, Sprinklr, Frontify, Oracle, IBM, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Brand Management Software Market Shifts & Advancements
Generative content engines and embedded compliance automation are reconfiguring how enterprises govern brand consistency across distributed operations. Vendors are racing to integrate these capabilities before procurement cycles lock in alternative architectures.
Embedded AI content generation is expanding into core creative workflows within brand management suites. Marketing teams at consumer goods enterprises now generate variant assets for multi-channel campaigns directly within governed repositories. This compression of production and compliance steps is collapsing traditional handoffs between creative agencies and brand teams.
The EU AI Act's algorithmic transparency mandates are forcing vendors to build explainability dashboards for automated personalization engines. Systems must now document decision pathways for content recommendations served to European consumers. Financial services marketing operations face the steepest retrofit burden as they reconcile SEC disclosure rules with emerging AI governance requirements.
Enterprise buying committees are consolidating vendor relationships to reduce integration overhead and compliance audit surface area. Mid-market agencies that previously stitched together point solutions now prioritize full-stack suites with native GDPR and HIPAA configurations. This concentration dynamic is most visible in Germany, where procurement teams weight regulatory readiness above feature breadth in evaluation criteria.
Global Brand Management Software Market Segmentation
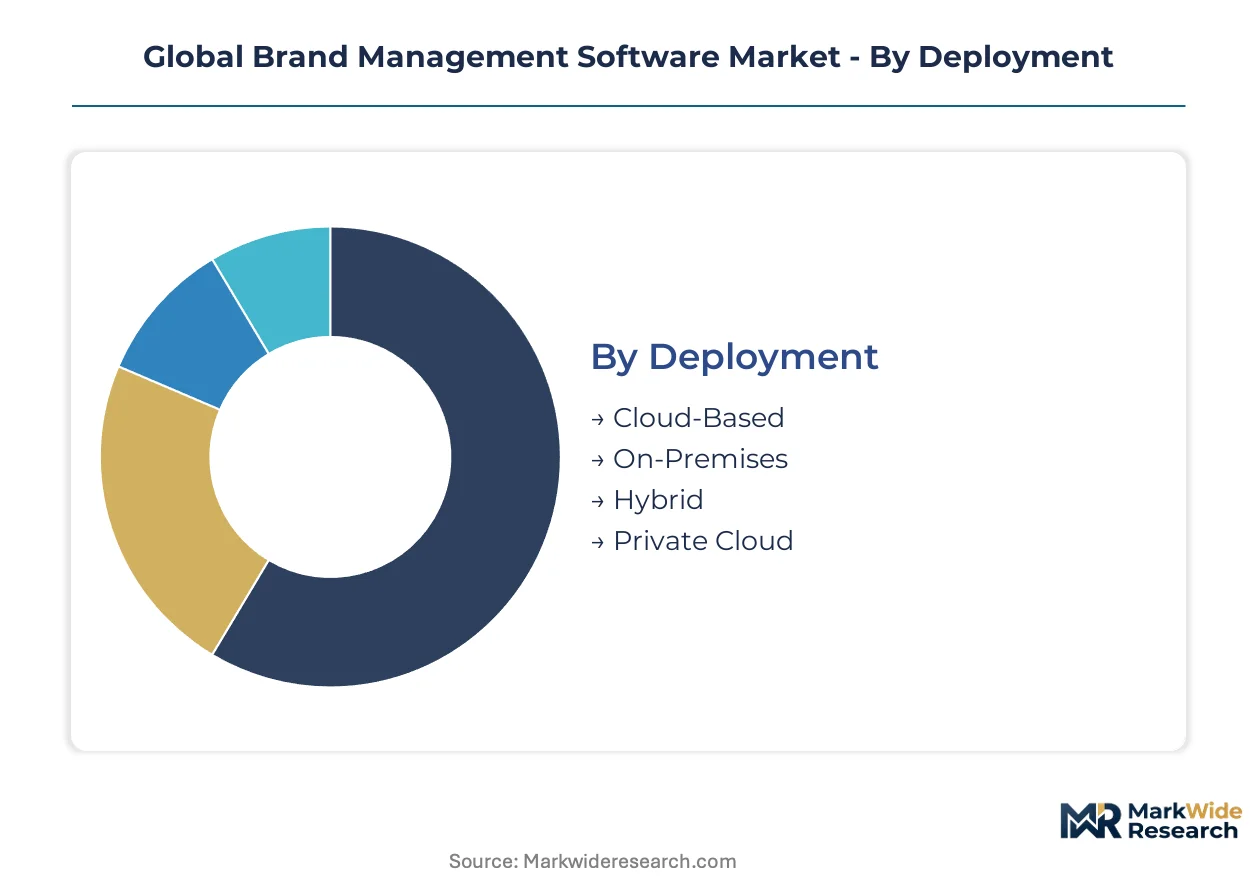
Segmentation in brand management software reveals how deployment architectures, solution bundles, and pricing mechanics align with divergent compliance burdens and operational scale requirements across enterprise buyers.
Deployment:
Cloud-based deployments carry lighter certification overhead for most jurisdictions, while on-premises and private cloud configurations trigger stricter data residency audits under GDPR, HIPAA, and SEC rules.
- Cloud-Based:Multi-tenant architectures with automatic scaling support distributed marketing teams across Germany, India, and the United States. Consumer goods enterprises favor this model for rapid multi-channel rollout without infrastructure capital expenditure. Demand concentrates where remote creative collaboration is mandatory.
- On-Premises:Self-hosted installations within enterprise data centers satisfy financial institutions and healthcare-adjacent brands facing HIPAA data handling constraints and SEC marketing disclosure rules. Procurement cycles run longer due to security validation requirements.
- Hybrid:Split architectures keep sensitive assets on-premises while pushing campaign distribution to cloud edge nodes. Telecommunications providers adopt this for customer data segregation.
- Private Cloud:Single-tenant dedicated environments hosted by hyperscalers or managed service providers. Hospitality chains with franchise networks deploy this for brand guideline enforcement without shared infrastructure risk.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid.
Solution Offering:
Margin concentration varies sharply across solution layers, with foundational repositories commanding higher retention rates than workflow tools.
- Digital Asset Management:Centralized repositories governing version control, metadata tagging, and access permissions form the foundational layer enterprises deploy first. Consumer goods companies in the United States prioritize these systems for multi-channel brand execution. This segment captures the largest margin pool.
- Analytics & Reporting:Closed-loop measurement engines linking brand activity to revenue outcomes. CMOs at consumer goods firms now mandate these capabilities, driving replacement of legacy reporting stacks. This segment is expanding most quickly.
- Content Creation:Embedded creative tools with template libraries and brand guideline enforcement. European agencies favor these for EU AI Act algorithmic transparency compliance.
- Campaign Management:Multi-channel orchestration platforms coordinating distribution across digital, print, and experiential touchpoints. Media and entertainment firms dominate adoption.
- Social Media Management:Publishing and monitoring tools with native compliance logging for regulated industries. Financial institutions deploy these for SEC disclosure tracking.
Highest retention rates: Digital Asset Management. Steepest expansion trajectory: Analytics & Reporting.
End User Industry:
Industry verticals diverge in procurement priorities, with regulated sectors weighting audit trails above feature velocity.
- Consumer Goods Companies:Multi-brand portfolios with distributed marketing operations across continents. These buyers prioritize unified cloud suites over fragmented point solutions to compress procurement cycles.
- Financial Institutions:Banks, insurers, and asset managers operating under SEC marketing disclosure rules and strict data governance protocols. HIPAA-adjacent configurations open penetration into healthcare marketing.
- Media & Entertainment Firms:Content studios and broadcasters managing high-velocity creative production with rights clearance complexity. Generative asset governance is reshaping their platform requirements.
- Hospitality Chains:Franchise and corporate-owned property networks requiring localized brand adaptation with centralized control. Mumbai and Bangalore operations are consolidating onto first-generation platforms.
- Telecommunications Providers:Subscriber-facing marketing at scale with strict customer data segmentation. These buyers favor hybrid deployments for regulatory flexibility.
Dominant procurement volume: Consumer Goods Companies. Fastest platform refresh cycles: Financial Institutions.
Pricing Model:
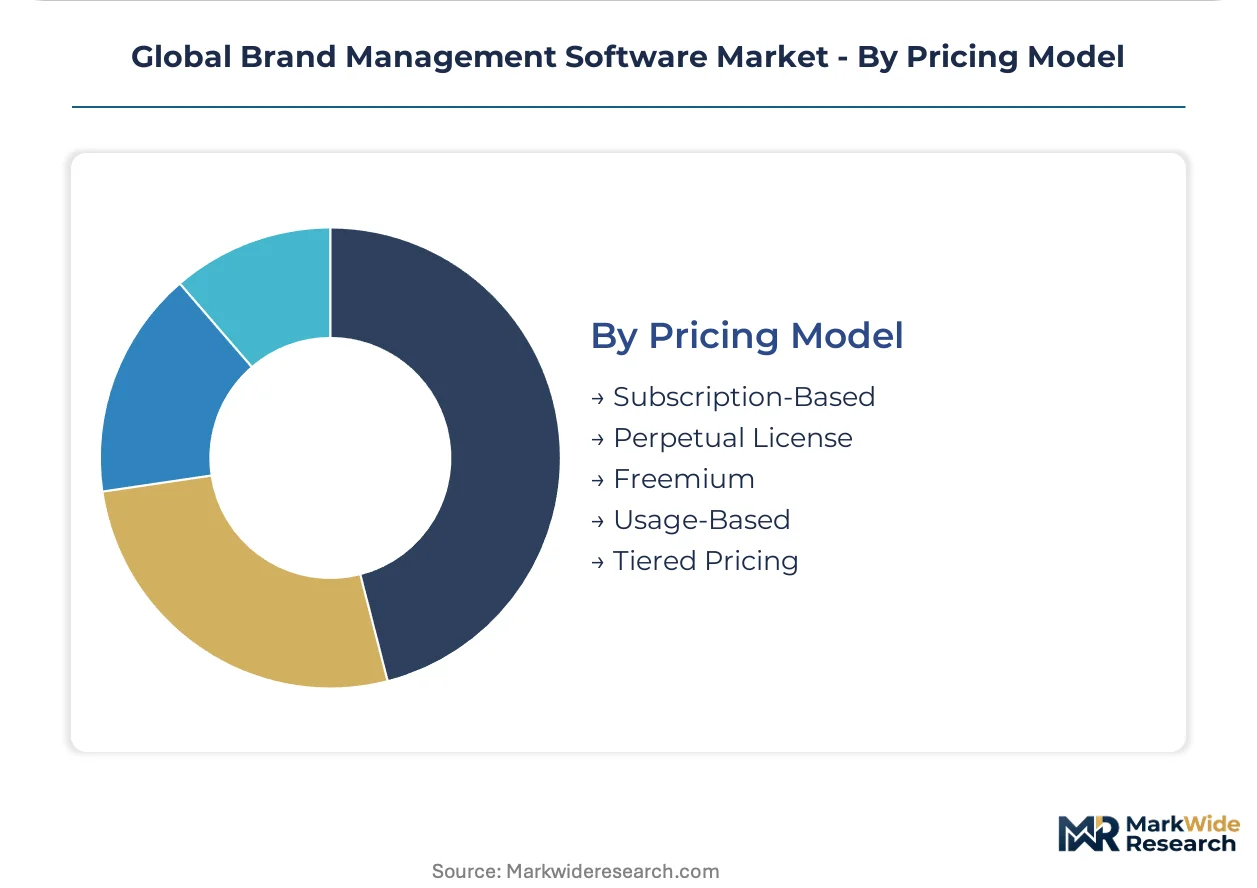
Revenue predictability and customer lifetime value hinge on how pricing mechanics align with usage patterns and procurement governance.
- Subscription-Based:Recurring annual or multi-year contracts with tiered feature access. Mid-market agencies in Germany prioritize this for predictable budgeting and regulatory audit simplicity.
- Perpetual License:One-time purchase with maintenance fees, favored by enterprises with capital expenditure preference and long depreciation schedules. On-premises deployments correlate with this model.
- Usage-Based:Metered billing tied to storage consumption, API calls, or campaign volumes. Telecommunications providers and hospitality chains with seasonal demand spikes favor this for cost elasticity.
- Freemium:Limited-feature entry tier converting to paid plans. Small creative agencies and startup consumer brands use this for initial brand guideline deployment.
- Tiered Pricing:Explicit stratification across premium, standard, and economy capability levels. Procurement teams weight regulatory readiness above feature breadth in evaluation criteria under this model.
Most common structure: Subscription-Based. Fastest-growing mechanic: Usage-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the densest concentration of brand management software engineering talent, with enterprise procurement committees in Manhattan and London driving cross-border standardization of vendor evaluation criteria.
United States
Consumer goods enterprises in Chicago and Cincinnati consolidate fragmented marketing stacks onto unified cloud suites. SEC marketing disclosure rules force financial institutions in Manhattan to embed audit trails directly into creative workflows. Procurement teams at CPG headquarters in Minneapolis prioritize closed-loop revenue attribution capabilities.
Germany
Mid-market agencies in Berlin and Hamburg abandon point solutions for full-stack suites with native GDPR configurations. EU AI Act algorithmic transparency mandates reshape R&D allocation for vendors serving Düsseldorf-based industrial marketing operations. Bavarian automotive suppliers deploy hybrid architectures for customer data segregation.
India
Mumbai and Bangalore enterprises consolidate onto first-generation brand management platforms as digital acceleration compresses procurement cycles. RBI data localization guidelines influence cloud deployment decisions for financial services marketing in Mumbai. Hospitality chains in Delhi-NCR adopt private cloud configurations for franchise network control.
United Kingdom
London media agencies integrate generative content engines into governed repositories for multi-channel campaign production. FCA conduct rules extend to marketing material approval workflows, requiring embedded compliance automation. Manchester-based retail brands prioritize rapid deployment models for distributed brand teams.
Japan
Tokyo consumer electronics firms demand analytics layers linking brand activity to revenue outcomes across APAC markets. METI guidelines on AI governance influence product development trajectories for vendors serving Osaka-based creative agencies. Nagoya automotive marketing operations favor subscription-based pricing for predictable budgeting.
Global Brand Management Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance-readiness and creative ecosystem integration. The vendor base stratifies into three tiers: full-stack suites with embedded governance, specialized digital asset management platforms, and lightweight deployment tools for mid-market agencies. Consolidation pressure intensifies as procurement committees reduce integration overhead. M&A activity targets compliance-automation capabilities, while strategic partnerships bridge creative cloud ecosystems with enterprise resource planning systems.
Within the creative cloud ecosystem tier, Adobe anchors high-end workflows for global enterprises through integrated design and governance capabilities. Bynder occupies a position among European-focused specialists emphasizing channel control across agency networks. Brandfolder exemplifies the rapid-deployment archetype for distributed brand teams prioritizing interface simplicity.
| Leading Market Players |
|---|
| Adobe |
| Bynder |
| Brandfolder |
| Brandwatch |
| Sprinklr |
| Frontify |
| Oracle |
| IBM |
| SAP |
| Others |
Supply & Pricing Matrix
Cloud infrastructure spot pricing indices and hyperscaler storage rate benchmarks cascade through brand management software supply chains, compressing margins for mid-tier vendors while concentrating pricing power among integrated suite providers serving GDPR-bound European enterprises and HIPAA-constrained U.S. healthcare marketers.
Pricing Analysis
Value-based pricing anchored to closed-loop revenue attribution outcomes dominates enterprise procurement committees, with CMOs at consumer goods firms paying premiums for analytics layers linking brand activity to sales results. Three-tier pricing structure across premium, standard, and economy levels separates full-stack governance suites from point solutions, with certification-grade GDPR and HIPAA configurations commanding substantial markups. Pricing pressure stems from hyperscaler commoditization of storage and compute, eroding infrastructure margins. Mid-market agencies in Germany exhibit highest price sensitivity, while financial institutions in Manhattan prioritize audit-trail completeness over cost.
Supply Chain Analysis
Reverse-logistics flows for deprecated on-premises hardware and expired license tokens create secondary markets for brand management software assets, with refurbished perpetual licenses circulating among budget-constrained hospitality chains. Engineering talent concentrates in the United States, Germany, and India, with San Francisco anchoring creative cloud development and Bangalore housing rapid-deployment specialists. Core dependencies include hyperscaler compute infrastructure, open-source rendering engines, and proprietary AI model weights. Single-source vulnerability to AWS, Azure, or GCP regional outages threatens multi-channel campaign continuity. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brand management software represents a consolidation play as EU AI Act compliance costs and integration complexity force sub-scale vendors toward exit or acquisition. Procurement committee consolidation onto full-stack suites accelerates attrition among point-solution providers lacking embedded governance.
For Market Incumbents: Extend compliance-automation capabilities into generative content workflows before procurement cycles lock in alternative architectures. Acquire distressed mid-market DAM specialists in Germany to capture GDPR-native customer bases. Vertical integration into AI model training infrastructure defends against hyperscaler dependency. For New Entrants and Emerging Players: Launch via usage-based pricing models targeting Mumbai and Bangalore mid-market enterprises consolidating onto first-generation platforms. White-space exists in HIPAA-compliant workflow configurations for pharmaceutical marketing operations currently underserved by generic solutions. Channel partnerships with healthcare-focused systems integrators accelerate trust-building. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-automation specialists with EU AI Act-ready explainability dashboards in Germany and the United Kingdom. Long-term viability hinges on embedded governance differentiation rather than interface novelty. Monitor SEC marketing disclosure rule enforcement intensity as inflection indicator for U.S. financial services vertical penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies DAM, analytics, and compliance layers into single-vendor relationships for CPG procurement committees. |
| Acquisition of Specialist Firm | Captures GDPR-native customer bases and algorithmic transparency capabilities required by EU AI Act. |
| Strategic Partnership | Bridges creative cloud ecosystems with ERP systems to reduce MarTech stack integration friction. |
| Geographic Expansion | Establishes localized deployment models in Mumbai and Bangalore for India's digital acceleration. |
| Product Launch | Introduces AI-generated asset governance modules for synthetic media clearance in media and entertainment. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents formed the secondary backbone, supplemented by trade data from software industry associations and compliance certification databases. Primary interviews with CMOs, IT procurement officers, platform engineers, and channel partners validated deployment trends and pricing mechanics. Bottom-up sizing of vendor revenue streams and top-down triangulation against enterprise software spending patterns produced convergent estimates.
Historical trendline analysis of cloud migration patterns and compliance-driven replacement cycles informed projection frameworks across the analysis window. Segmentation dimensions modeled include deployment architecture, solution layer, end-user industry vertical, and regional adoption pattern. CAGRs derived from logistic diffusion curves for governance technology adoption, with inputs from marketing operations headcount growth and regulatory enforcement intensity trajectories.
Regulatory enforcement delays, hyperscaler pricing volatility, and generative AI capability breakthroughs are the dominant revision risks to forecast assumptions. Practitioners should monitor EU AI Act implementation timelines and SEC marketing disclosure rule updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Camera Tracking Software Market
Software & Services
PCB CAD Software Market
Software & Services
Fire Software Market
Software & Services
PAC Programming Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Global Android Kiosk Software Market
Software & Services
PCB Design Software Market
Software & Services
Technology CAD Software Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Stock Control Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Kennel Management Software Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Personal Budgeting Software Market
Software & Services
Commissioning Software Market