
 Inventory Management Software Market | 2026-2036
Inventory Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Inventory Management Software Market Analysis
Artificial intelligence is decoupling inventory optimization from legacy rule-based replenishment. SAP Inventory Management leverages deep ERP integration to sustain platform stickiness across multinational manufacturers. Zoho Inventory anchors its position among mid-market retailers through aggressive freemium-to-paid conversion paths. Cin7 competes aggressively in the omnichannel segment where warehouse and POS unification commands premium pricing.
Inventory management software coordinates stock levels, order fulfillment, and demand signals through algorithmic replenishment engines that process SKU velocity, lead-time variability, and safety-stock thresholds in real time. Its primary commercial purpose is to minimize carrying costs while preventing stockouts across distributed fulfillment networks. Cloud-based Solutions dominate new deployments because subscription economics shift capital expenditure to operational budgets and enable faster multi-location rollouts. Real-time Tracking functions as the highest-margin feature set as RFID and IoT sensor integration commands implementation premiums. On-premise Software retains footholds among defense contractors and financial institutions where data sovereignty requirements override cloud agility.
The EU CSRD and GDPR shape European procurement by mandating auditable supply chain data lineage and restricting cross-border data residency. The US FDA enforces track-and-trace requirements for pharmaceutical distributors that elevate software validation standards. India's BIS cloud security guidelines and China's GB standards for data localization fragment deployment architectures across Asia-Pacific. Stakeholders must evaluate whether regional compliance modules or configurable policy engines offer superior total cost of ownership as regulatory divergence accelerates.
Market Dynamics
Algorithmic replenishment engines are compressing decision cycles from weeks to hours, forcing legacy ERP architectures to absorb real-time data streams or lose platform relevance among multinational distributors.
Growth Catalysts
- EU CSRD traceability mandates:The Corporate Sustainability Reporting Directive compels auditable supply chain disclosures across European manufacturing, accelerating procurement of inventory platforms with embedded carbon accounting modules.
- Third-party logistics cloud migration:3PL providers are abandoning on-premise warehouse management systems for SaaS-native inventory stacks that enable faster multi-tenant onboarding and geographic expansion.
- RFID sensor cost deflation:Passive tag prices have fallen below the threshold for item-level tracking in apparel and electronics retail, expanding addressable market for real-time visibility software.
Market Restraints
- Data residency fragmentation:China's GB standards for data localization, India's BIS cloud security guidelines, and EU GDPR restrictions force vendors to maintain region-segregated infrastructure, elevating operational complexity.
- Legacy ERP entrenchment:SAP and Oracle systems anchor procurement workflows at Fortune 500 manufacturers, creating switching costs that delay SaaS replacement cycles by 18-36 months.
- Integration labor scarcity:Shortages of supply chain engineers fluent in EDI, API orchestration, and warehouse control systems constrain deployment velocity for mid-market rollouts.
Strategic Opportunities
- Pharmaceutical track-and-trace:US FDA DSCSA serialization deadlines are elevating software validation standards, creating premium pricing power for vendors with 21 CFR Part 11 compliance modules.
- AI-forecasting convergence:Machine learning demand-sensing layered atop RFID inventory streams is electrifying replenishment accuracy in fast-fashion retail, compressing safety-stock buffers by 30-40%.
- SME channel expansion:Freemium-to-paid conversion paths among mid-market retailers represent underpenetrated whitespace as vendors replicate Zoho's land-and-expand playbook.
Industry Challenges
- Warehouse automation integration:Synchronizing inventory software with AMR fleets and robotic picking systems requires proprietary middleware that fragments vendor ecosystems and extends implementation timelines.
- Multi-channel data reconciliation:Unifying POS, marketplace, and direct-to-consumer order streams into single SKU-level visibility remains technically arduous, particularly for omnichannel retailers with disparate legacy point-of-sale architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inventory Management Software Market |
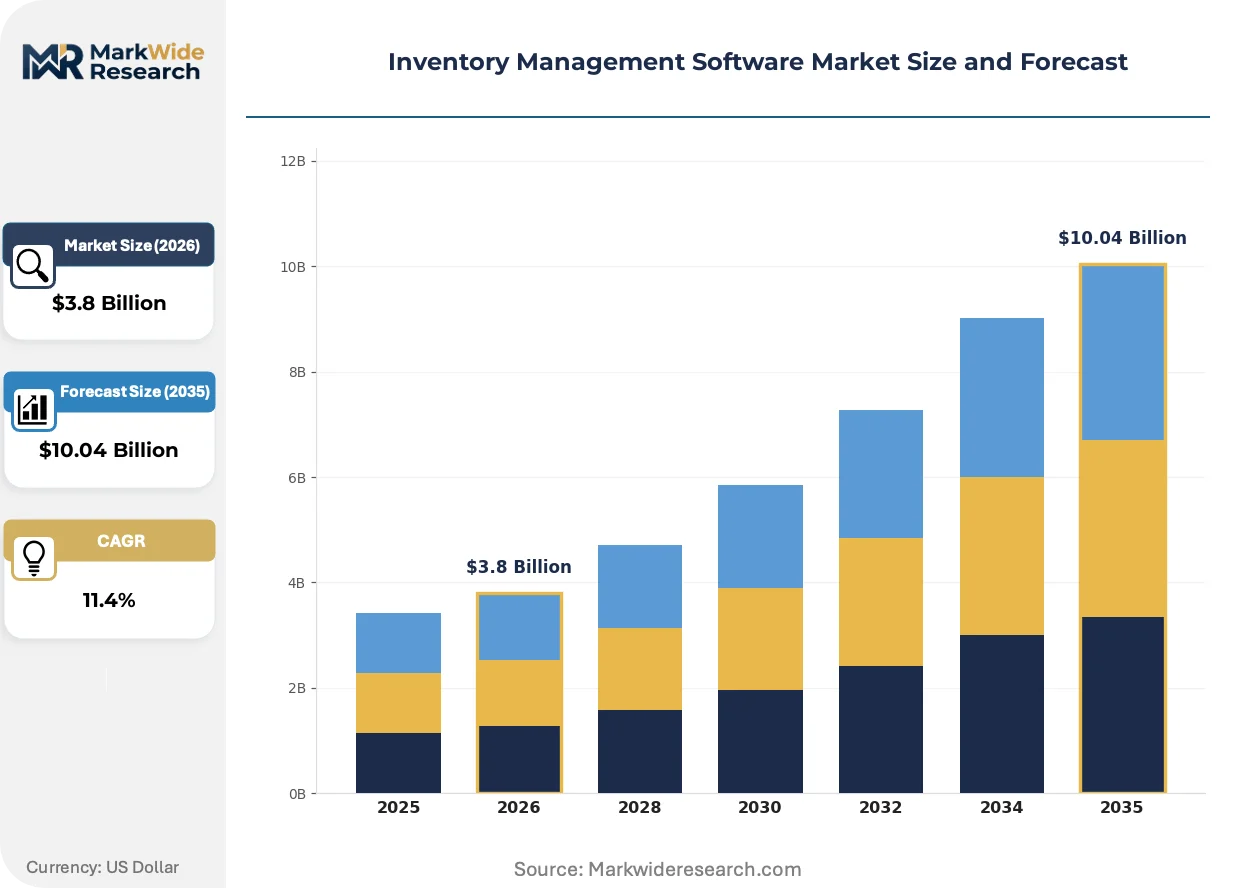
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premise Software, Hybrid Systems, Mobile Applications End User: Retailers, Wholesalers, Manufacturers, E-commerce Platforms Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises Feature Set: Real-time Tracking, Barcoding Systems, Reporting Tools, Demand Forecasting |
| Companies Covered | Cin7, SAP Inventory Management, GOIS (Good Order Inventory Systems), Odoo Inventory, Lightspeed Retail, Zoho Inventory, NetSuite Inventory, Digit, QuickBooks Commerce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inventory Management Software Market Emerging Trajectories
Digital twin architectures are displacing static safety-stock models, enabling dynamic simulation of supply network disruptions before inventory positions harden into commitments.
Generative AI copilots are electrifying demand planning workflows by translating natural language queries into SKU-level forecast adjustments, compressing analyst cycle times from days to minutes. Consumer electronics and automotive suppliers are piloting these interfaces at scale, though data hygiene requirements limit deployment among distributors with fragmented master data repositories. The structural consequence is a bifurcation between AI-native platforms and legacy vendors bolting conversational interfaces onto brittle rule-based engines.
The EU AI Act's risk classification framework is elevating compliance documentation burdens for inventory algorithms that autonomously trigger purchase orders or production schedules. Vendors must now maintain technical files proving human oversight mechanisms, traceability logs, and bias mitigation protocols. German automotive suppliers and French pharmaceutical distributors are absorbing these costs earliest, while US-based SaaS providers face competitive friction entering European procurement cycles without pre-certified modules.
Outcome-based contracts are displacing seat-license pricing as large retailers negotiate vendor compensation tied to measurable working-capital improvements. Third-party logistics providers in the Netherlands and grocery chains in the United Kingdom are pioneering gain-share arrangements where software fees scale with inventory-turn gains. This compresses upfront SaaS margins while extending customer lifetime value for platforms that demonstrably reduce safety-stock buffers.
Inventory Management Software Market Segmentation
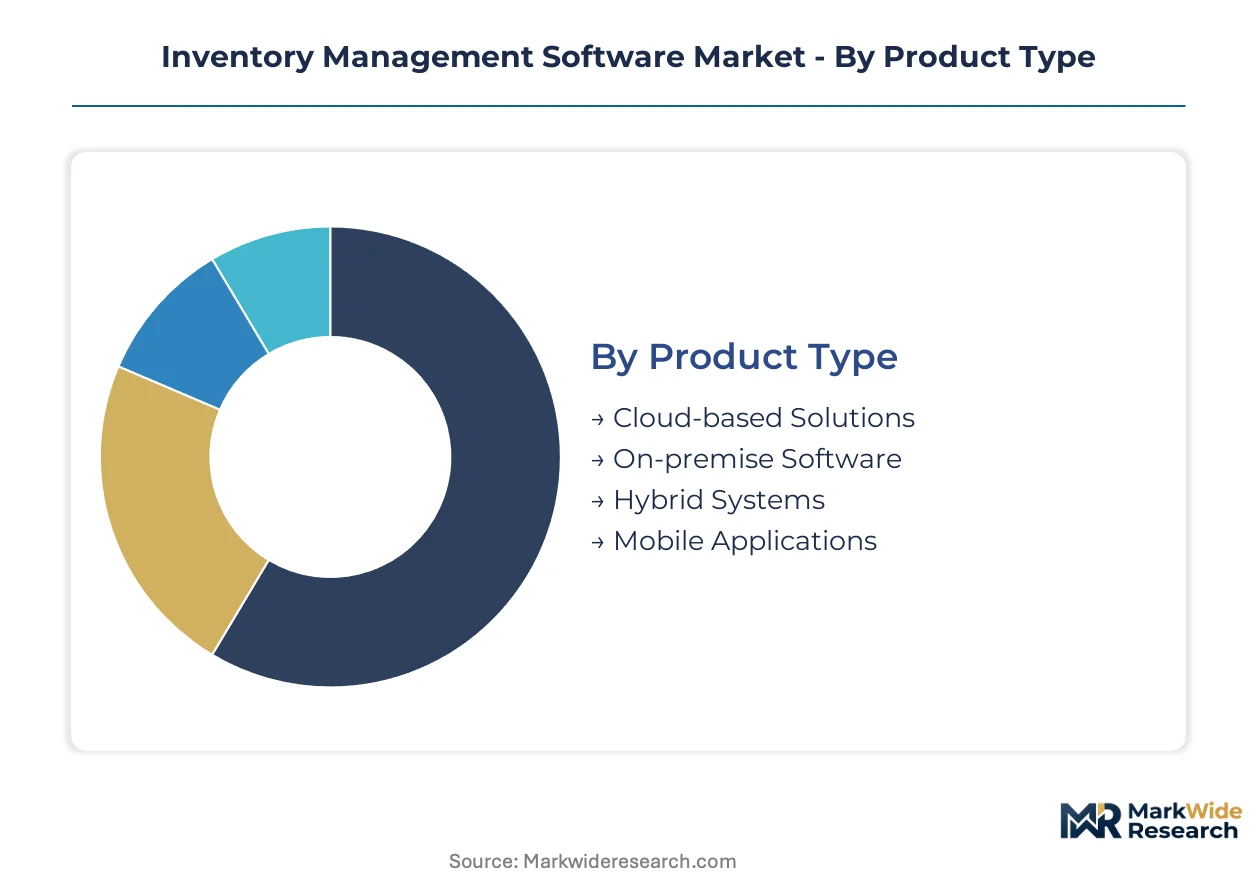
Segmentation in inventory management software reveals how procurement priorities diverge between cost-sensitive mid-market buyers and compliance-heavy enterprises. Deployment architecture and feature depth determine pricing power, while end-use verticals dictate integration complexity and sales cycle length.
Product Type:
Cloud-based Solutions dominate new procurement volumes, though On-premise Software retains premium pricing in regulated verticals.
- Cloud-based Solutions:Multi-tenant SaaS architectures enable subscription economics that shift capital expenditure to operational budgets. Demand concentrates among third-party logistics providers in the Netherlands and Germany's industrial corridor, where rapid multi-location rollouts override data sovereignty concerns.
- On-premise Software:Perpetual-license deployments with localized data residency satisfy defense contractors and pharmaceutical distributors facing FDA validation requirements. German automotive suppliers and French pharmaceutical distributors absorb elevated implementation costs to maintain audit trail control.
- Hybrid Systems:Split architectures partition sensitive master data on-premise while pushing transactional workloads to cloud edge nodes.
- Mobile Applications:Native iOS and Android clients extend warehouse floor visibility through barcode scanning and RFID tag reads.
Today's leader: Cloud-based Solutions. Tomorrow's challenger: Hybrid Systems.
End User:
Retailers and E-commerce Platforms drive feature innovation, while Manufacturers and Wholesalers anchor contract value.
- Retailers:Omnichannel order orchestration demands unified visibility across POS, marketplace, and direct-to-consumer streams. Fast-fashion retailers in the United Kingdom compress safety-stock buffers by layering machine learning atop RFID inventory streams.
- E-commerce Platforms:Direct-to-consumer fulfillment networks require real-time SKU velocity tracking across distributed micro-fulfillment centers. Demand concentrates in urban logistics clusters where same-day delivery SLAs mandate sub-hour replenishment decisions.
- Wholesalers:Bulk distribution workflows prioritize EDI integration and vendor-managed inventory modules over consumer-facing interfaces.
- Manufacturers:Production scheduling integration with MRP systems elevates platform stickiness through deep ERP coupling.
E-commerce Platforms are climbing the fastest as same-day delivery mandates proliferate.
Deployment Model:
Public Cloud captures volume, but Private Cloud commands margin in European procurement cycles.
- Public Cloud:Shared infrastructure delivers lowest per-seat economics for mid-market retailers with standardized workflows. India's BIS cloud security guidelines and China's GB standards for data localization fragment deployment architectures, forcing vendors to maintain region-segregated instances.
- Private Cloud:Single-tenant environments satisfy EU GDPR restrictions and CSRD traceability mandates for auditable supply chain data lineage. German automotive suppliers and French pharmaceutical distributors absorb premium pricing for dedicated infrastructure.
- Hybrid Cloud:Burst capacity configurations handle seasonal demand spikes without permanent over-provisioning.
- On-premises:Air-gapped installations persist in defense and financial institutions where data sovereignty overrides cloud agility.
Private Cloud is gaining share fastest as regulatory divergence accelerates.
Feature Set:
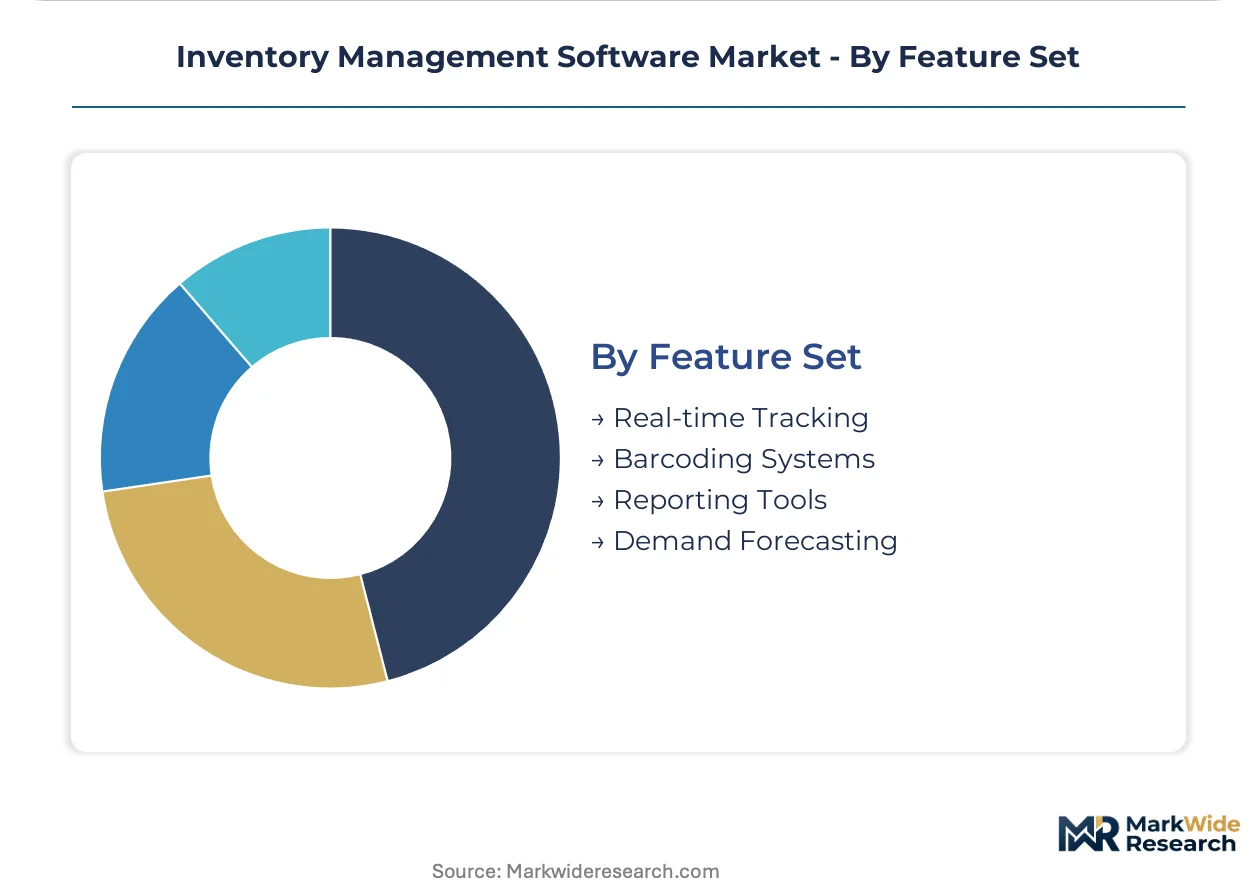
Real-time Tracking and Demand Forecasting command implementation premiums, while Barcoding Systems and Reporting Tools commoditize.
- Real-time Tracking:RFID and IoT sensor integration enables item-level visibility with sub-minute latency. Passive tag price deflation below the threshold for apparel and electronics retail expands addressable market for sensor-enabled software stacks.
- Demand Forecasting:Machine learning algorithms process external signals—weather, social sentiment, macro indicators—to compress analyst cycle times. Consumer electronics and automotive suppliers pilot generative AI copilots that translate natural language queries into SKU-level adjustments.
- Barcoding Systems:Linear and 2D symbology support remains table stakes for warehouse receiving and shipping workflows.
- Reporting Tools:Pre-built dashboards and custom query builders satisfy audit documentation requirements without predictive capability.
Demand Forecasting is expanding most quickly as AI-forecasting convergence electrifies replenishment accuracy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor anchors procurement concentration for inventory management platforms, with automotive suppliers and pharmaceutical distributors driving demand for CSRD-compliant traceability modules.
Germany
Automotive suppliers in Baden-Württemberg and Bavaria absorb premium pricing for private-cloud deployments that satisfy CSRD audit requirements. The EU AI Act's risk classification framework elevates compliance documentation burdens for algorithms triggering autonomous purchase orders. Stuttgart and Munich clusters concentrate demand for ERP-integrated inventory stacks with embedded carbon accounting.
United States
Third-party logistics providers abandon on-premise warehouse systems for SaaS-native stacks enabling faster multi-tenant onboarding. FDA DSCSA serialization deadlines elevate software validation standards for pharmaceutical distributors. Chicago and Dallas logistics hubs pilot outcome-based contracts tied to measurable working-capital improvements.
United Kingdom
Fast-fashion retailers compress safety-stock buffers by layering machine learning atop RFID inventory streams. GDPR restrictions and post-Brexit data residency requirements sustain demand for hybrid deployment architectures. London and Manchester omnichannel operators struggle with POS unification across disparate legacy point-of-sale systems.
China
GB standards for data localization force vendors to maintain region-segregated infrastructure, elevating operational complexity for multinational rollouts. E-commerce platforms in the Yangtze River Delta require real-time SKU velocity tracking across distributed micro-fulfillment centers. Shenzhen and Hangzhou logistics clusters mandate sub-hour replenishment decisions for same-day delivery SLAs.
India
BIS cloud security guidelines fragment deployment architectures alongside data residency requirements for financial institutions. Mid-market retailers replicate freemium-to-paid conversion paths pioneered by SaaS-native vendors. Mumbai and Bangalore industrial corridors concentrate demand for mobile-first warehouse visibility through native iOS and Android clients.
Inventory Management Software Market Vendor Landscape
Platform consolidation dominates the current landscape as deep ERP integration creates switching costs that delay SaaS replacement cycles by 18-36 months. The vendor base stratifies across three tiers: enterprise suites with multinational manufacturing footprints, mid-market SaaS specialists with aggressive land-and-expand playbooks, and verticalized omnichannel operators commanding premium pricing for warehouse-POS unification. Dominant competitive moves include M&A activity targeting RFID sensor integration capabilities and strategic partnerships with third-party logistics providers seeking geographic expansion.
Within the enterprise suite tier, SAP Inventory Management and NetSuite Inventory exemplify platforms sustaining stickiness through deep ERP coupling across multinational manufacturers. Zoho Inventory anchors the mid-market SaaS vector with aggressive freemium-to-paid conversion paths that replicate successful land-and-expand playbooks among retailers. Cin7 occupies a specialized position in the omnichannel segment where real-time visibility across warehouse and POS systems commands implementation premiums.
| Leading Market Players |
|---|
| Cin7 |
| SAP Inventory Management |
| GOIS (Good Order Inventory Systems) |
| Odoo Inventory |
| Lightspeed Retail |
| Zoho Inventory |
| NetSuite Inventory |
| Digit |
| QuickBooks Commerce |
| Others |
Supply Flow & Price Mechanics
Fortune 500 manufacturers anchored in SAP and Oracle procurement workflows command subscription-tier pricing power through deep ERP integration requirements. SaaS-native vendors absorb margin compression to penetrate mid-market retailers where freemium conversion economics dominate procurement decisions.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and RFID sensor manufacturers shapes vendor margin structures across deployment tiers. Three-tier pricing structure across enterprise, professional, and starter levels differentiates by integration depth, API call volume, and compliance certification grade. Pricing pressure stems from aggressive land-and-expand tactics among mid-market specialists. Mid-market retailers exhibit highest price sensitivity, while pharmaceutical distributors absorb premiums for FDA-validated modules.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure mandate multi-region qualification across AWS, Microsoft Azure, and Google Cloud Platform instances. Software development concentrates in the United States, India, and Ireland, with customer success operations distributed across Eastern Europe and Southeast Asia. The supply chain draws from open-source machine learning frameworks, proprietary RFID hardware, and hyperscaler compute resources. Single-source vulnerability in specialized warehouse control system middleware elevates implementation risk. Distribution runs through direct enterprise sales, value-added resellers, and third-party logistics provider partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as procurement shifts toward CSRD-compliant traceability modules and AI-validated forecasting engines over commodity inventory tracking.
For Market Incumbents: Deepen vertical integration into RFID sensor middleware and warehouse robotics orchestration layers to defend against cloud-native challengers. Fortify ERP coupling through carbon accounting module development as EU CSRD mandates harden switching costs. Prioritize certification investment for FDA 21 CFR Part 11 and EU AI Act risk classification frameworks.
For New Entrants and Emerging Players: AI-native demand forecasting platforms offer the most penetrable wedge against legacy rule-based engines. Target fast-fashion retailers in the United Kingdom and omnichannel operators in Germany's industrial corridor where safety-stock compression mandates create urgency. Pursue channel partnerships with third-party logistics providers seeking geographic expansion.
For Investors and Strategic Acquirers: Private equity firms with software buyout experience are the most active acquirer in this space, consolidating mid-market SaaS specialists with proven freemium conversion mechanics. Long-term viability hinges on AI-forecasting differentiation and regulatory compliance module depth. Watch for inflection in outcome-based contract adoption as large retailers negotiate gain-share arrangements.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP coupling with SAP and Oracle systems sustains renewal rates among multinational manufacturers. |
| Acquisition of Specialist Firm | RFID sensor middleware targets compress implementation timelines for warehouse automation rollouts. |
| Strategic Partnership | Third-party logistics provider alliances accelerate multi-tenant onboarding across European distribution networks. |
| Product Launch | Generative AI copilots for demand planning electrify analyst productivity in consumer electronics procurement. |
| Geographic Expansion | Region-segregated cloud instances satisfy China's GB standards and India's BIS guidelines for data residency. |
Methodological Framework
Multiple input streams — structured interviews with supply chain executives and IT procurement officers, secondary validation through SEC filings and hyperscaler capex disclosures, and deployment data from warehouse automation integrators — were reconciled to construct segment-level demand estimates. Primary fieldwork encompassed CTOs at third-party logistics providers, platform engineers at RFID hardware vendors, and integration specialists at ERP implementation consultancies. Bottom-up sizing of cloud subscription revenue and top-down cross-check against enterprise software spending patterns ensured triangulation integrity.
Data-stream reconciliation across deployment model, organization size, vertical industry, and regional adoption pattern informed the analytical framework over the projection horizon. CAGRs were derived from logistic diffusion curves fitted to SaaS penetration benchmarks and regulatory mandate timelines. Forecast inputs incorporated EU CSRD compliance deadlines, FDA DSCSA serialization phases, and RFID sensor cost deflation trajectories.
The model holds under steady regulatory enforcement and cloud infrastructure availability; deviation in data localization enforcement intensity or hyperscaler pricing volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Online Survey Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Exploration and Production (E&P) Software Market
Software & Services
Embedded Software Market
Software & Services
Global Retail Execution Software Market
Software & Services
Global Localization Software Market
Software & Services
Multi-Cloud SDN Market
Software & Services
Retail Space Planning Software Market
Software & Services
Automotive Operating Systems Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Global Polling Software Market
Software & Services
Global Text to Speech (TTS) Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Marketing Automation Software Market
Software & Services
Animation Design Software Market
Software & Services
Data Center Backup and Recovery Software Market