
 Freight Management Software Market | 2026-2036
Freight Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Freight Management Software Market Foresight
Logistics software engineering talent is rotating toward cloud-native architectures and API-first platform design, tightening the labor pool for legacy on-premise system maintenance. SAP SE leverages its embedded ERP footprint to anchor multimodal freight workflows inside enterprise procurement systems. Oracle Corporation competes through database-layer integration that sustains real-time visibility across carrier networks. Blue Yonder differentiates via AI-driven demand sensing that extends inventory positioning into transportation planning.
Freight management software encompasses planning, execution, and settlement systems that coordinate cargo movement across road, rail, ocean, and air modes, typically operating through EDI, API, or telematics connections to carriers and customs platforms. Cloud-based deployment is capturing the fastest expansion as shippers abandon capital-intensive server infrastructure for subscription models with automatic regulatory updates. Transportation management solutions dominate value capture among solution offerings, though cargo monitoring is gaining traction in cold chain logistics where temperature excursions trigger automated claims workflows.
The EU Green Deal and its delegated acts on transport emissions reporting are forcing European operators to retrofit legacy systems with carbon accounting modules, while the US EPA tailpipe standards and FAA drone integration rules reshape last-mile compliance requirements. ISO 14083 on greenhouse gas quantification in transport chains is becoming a de facto tender precondition for multinational shippers. Stakeholders must decide whether to build emissions compliance natively or partner with specialized carbon data vendors before regulatory thresholds harden into contract terms.
Market Dynamics
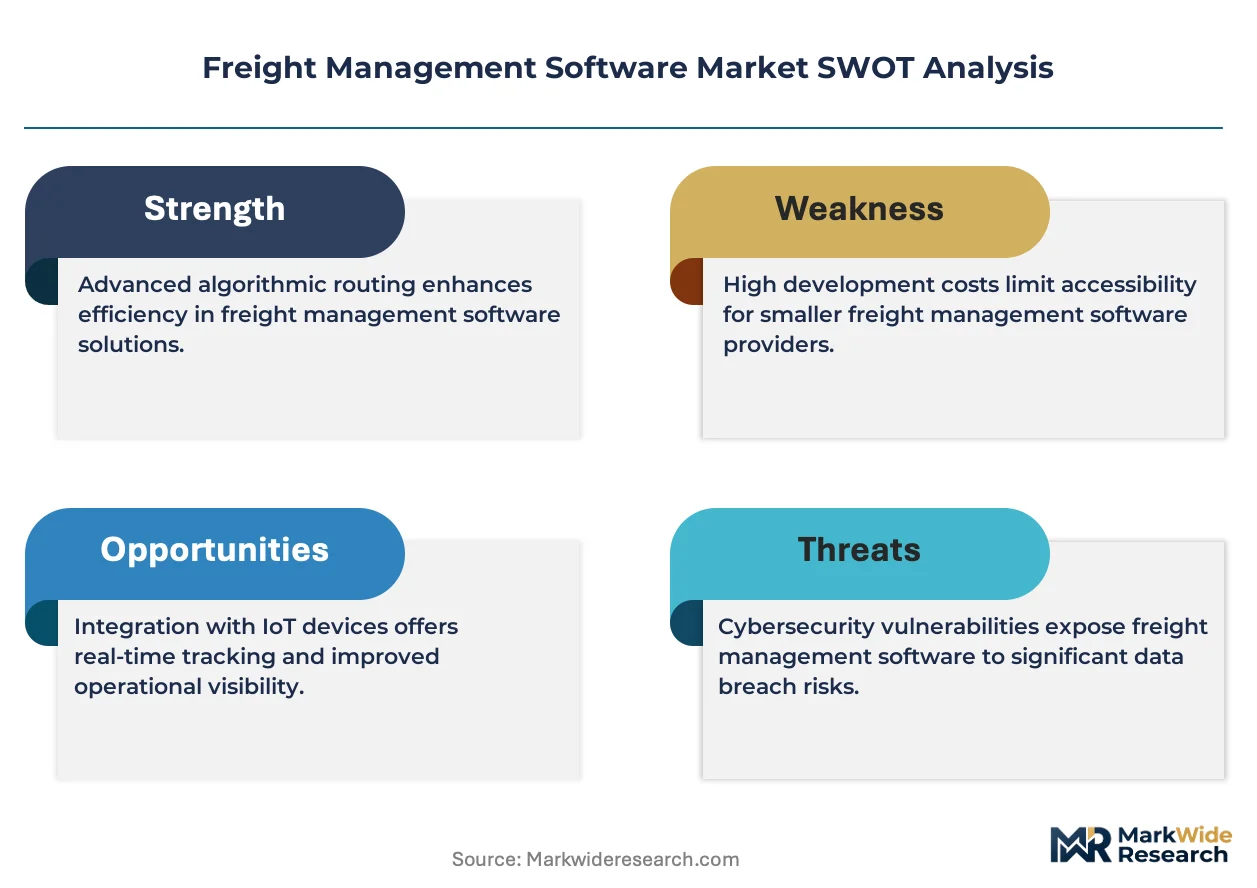
Cloud-native architectures are displacing monolithic on-premise freight systems as shippers prioritize API-first interoperability over legacy EDI infrastructure. The EU Green Deal's emissions reporting mandates are forcing carbon accounting retrofits across European logistics networks.
Growth Catalysts
- ISO 14083 Standardization:Multinational shippers in Germany now require greenhouse gas quantification as a tender precondition, accelerating platform upgrades across retail supply chains.
- Cold Chain Expansion:Pharmaceutical distributors in the United States are deploying temperature-monitoring modules that trigger automated claims workflows during cargo excursions.
- API-First Integration:Real-time carrier connectivity through standardized interfaces is compressing booking-to-settlement cycles for mid-market freight operators.
Market Restraints
- Legacy System Entrenchment:Capital-intensive server infrastructure in European road freight creates switching friction for family-owned carriers with thin IT budgets.
- Talent Pool Compression:Cloud-native engineering scarcity is inflating implementation costs for SAP-integrated multimodal deployments.
- Data Sovereignty Fragmentation:Divergent cross-border data localization rules between Germany, France, and the United States complicate single-tenant cloud architectures.
Strategic Opportunities
- Domestic Network Rebuilding:United States shippers are consolidating regional distribution hubs, creating demand for transportation management systems with dynamic routing.
- Drone Last-Mile Integration:FAA unmanned aircraft rules are opening airspace corridors for automated delivery platforms in suburban logistics.
- Carbon Data Partnerships:Specialized emissions vendors offer faster compliance paths than native builds as EU delegated acts harden into contract terms.
Industry Challenges
- Embedded ERP Complexity:Oracle database-layer integrations require specialized talent that commands premium rates and extends deployment timelines.
- EDI-to-API Migration Friction:Hybrid connectivity stacks create error-handling overhead during carrier onboarding for multimodal operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freight Management Software Market |
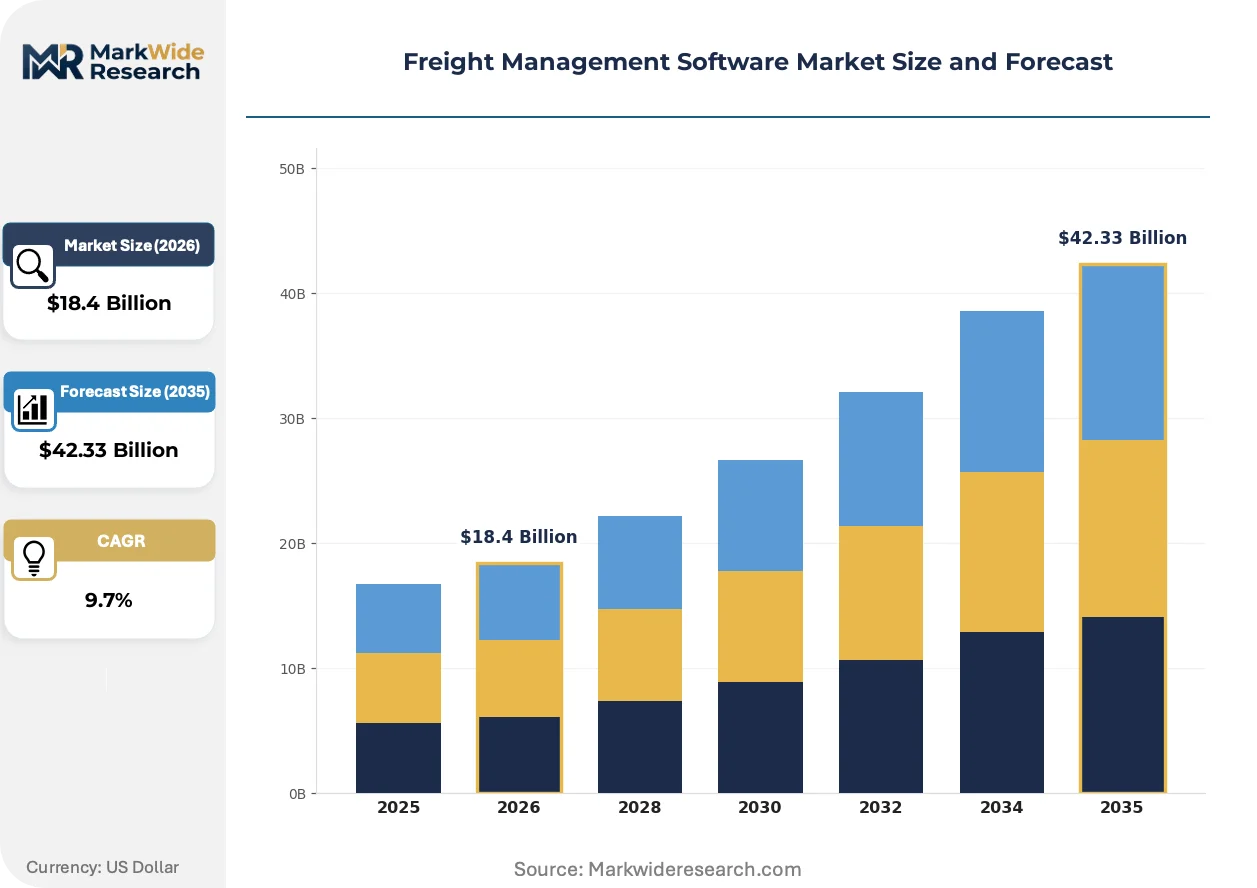
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $42.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Offering: Transportation Management, Warehouse Management, Fleet Tracking, Route Optimization, Freight Audit, Cargo Monitoring Application: Third-Party Logistics, Postal Services, Cold Chain Logistics, E-Commerce Fulfillment, Reverse Logistics End User: Freight Forwarders, Shipping Lines, Courier Companies, Retail Supply Chains |
| Companies Covered | SAP SE, Oracle Corporation, Blue Yonder, Descartes Systems Group, Manhattan Associates, MercuryGate, Freightos, Shipwell, Transporeon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freight Management Software Market Shifts & Advancements
Artificial intelligence is compressing planning horizons from days to hours as demand sensing capabilities merge with transportation execution. Platform vendors are racing to embed predictive analytics that anticipate disruption before cargo moves.
Machine learning algorithms for demand sensing are displacing static inventory positioning models in retail supply chains. German grocery distributors now recalculate safety stock thresholds every four hours based on weather and promotional signals. This capability is compressing the competitive gap between integrated ERP suites and standalone transportation management vendors.
The EU Green Deal's delegated acts on transport emissions reporting are mandating granular carbon accounting across multimodal chains. Logistics operators in France and Germany must retrofit legacy platforms with MRV-compliant modules or risk tender disqualification. Cold chain specialists face the steepest compliance costs due to temperature-controlled energy intensity.
Shippers are unbundling freight procurement from annual contracts toward spot-market algorithms with dynamic pricing. United States e-commerce fulfillment networks now source capacity through auction platforms rather than dedicated carrier relationships. Food and beverage distributors show the highest adoption velocity as seasonal volume spikes strain committed capacity agreements.
Freight Management Software Market Segmentation
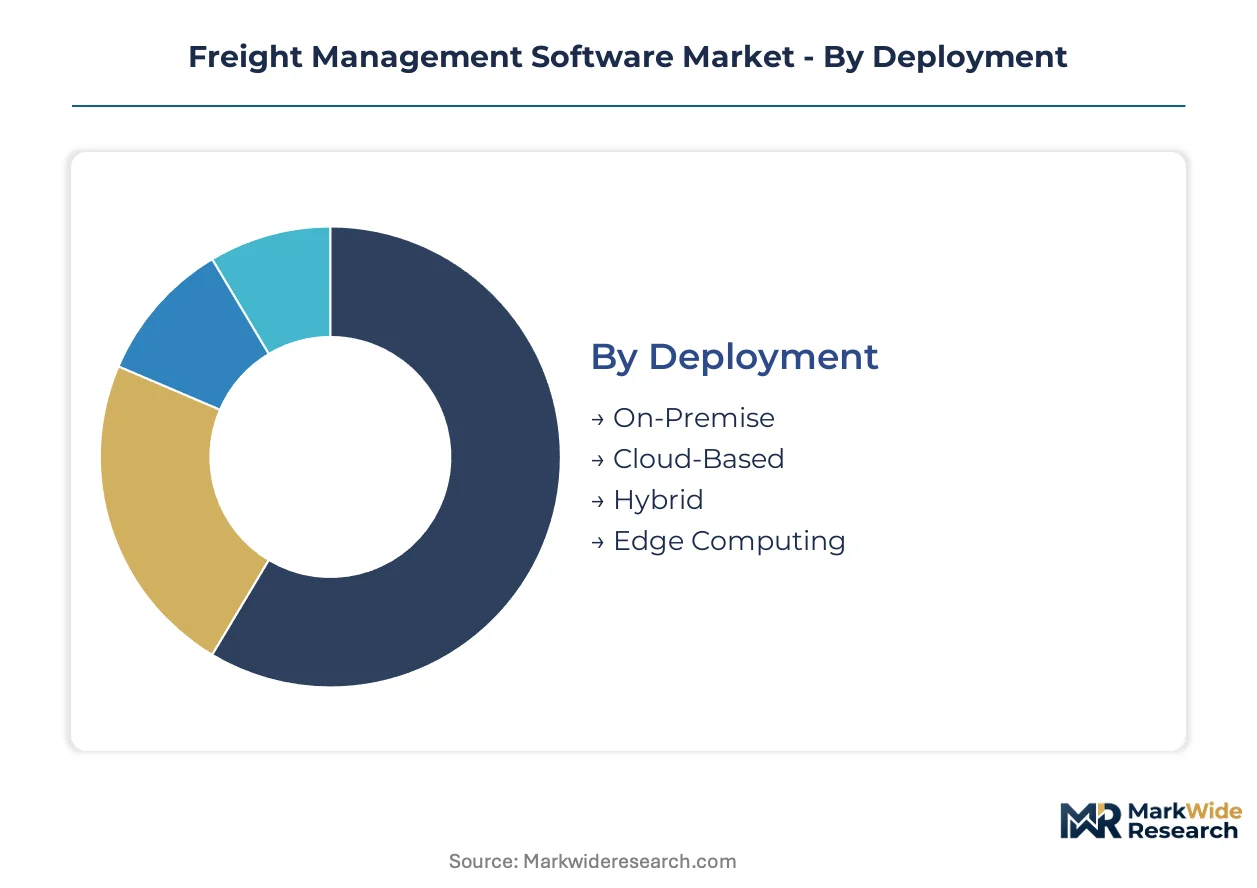
Freight management software segments fracture along technical architecture, functional depth, and operational use case. Procurement decisions hinge on integration complexity, regulatory exposure, and network scale rather than feature checklists alone.
Deployment:
Cloud-based platforms face substitution pressure from hybrid architectures as data sovereignty rules harden across jurisdictions.
- Cloud-Based:Multi-tenant SaaS architectures deliver automatic regulatory updates and elastic compute scaling. German retail supply chains favor this model to satisfy EU Green Deal reporting mandates without capital expenditure. Subscription economics displace server ownership for mid-market operators.
- On-Premise:Single-tenant installations behind corporate firewalls persist where customs data or defense-adjacent cargo requires air-gapped security. Family-owned European road carriers retain these systems due to thin IT budgets and switching friction.
- Hybrid:Split workloads between private infrastructure and public cloud balance latency-sensitive routing with centralized analytics. Maritime shippers deploy edge nodes for vessel connectivity while anchoring financial settlement onshore.
- Edge Computing:Distributed processing at port gates and warehouse docks enables real-time decisioning without round-trip latency to central servers. Cold chain operators embed temperature analytics directly in reefer unit controllers.
Cloud-based retains volume leadership; edge computing holds the steepest expansion curve.
Solution Offering:
Cost tier stratification separates enterprise-integrated suites from point solutions serving narrow operational pain points.
- Transportation Management:Core planning, execution, and settlement modules coordinate multimodal freight flows through EDI and API carrier connections. United States shippers rebuilding domestic distribution networks drive demand for dynamic routing capabilities. SAP and Oracle anchor these workflows inside procurement systems.
- Cargo Monitoring:Sensor-fed visibility platforms track location, temperature, and shock events across in-transit inventory. Pharmaceutical distributors in the United States deploy automated claims triggers when excursions breach protocol. Cold chain energy intensity elevates compliance costs for this module.
- Warehouse Management:Yard management and dock scheduling extensions bridge transportation execution with inventory positioning. E-commerce fulfillment networks require these capabilities for same-day dispatch windows.
- Fleet Tracking:Telematics aggregation from onboard diagnostics and GPS transponders supports driver behavior scoring and predictive maintenance. Courier companies standardize on these tools for last-mile density optimization.
- Route Optimization:Algorithmic sequencing of delivery stops minimizes fuel consumption and service window violations. Food and beverage distributors adopt these modules to manage seasonal volume spikes.
- Freight Audit:Automated invoice validation against contracted rates and service levels captures payment discrepancies. Third-party logistics providers white-label these capabilities to shipper clients.
Transportation management commands the largest installed base; cargo monitoring is climbing the fastest as cold chain compliance tightens.
Application:
Customer type concentration shapes feature roadmaps as vendors prioritize workflow depth over horizontal breadth.
- Third-Party Logistics:Multi-client orchestration platforms require tenant isolation and configurable business rules across divergent shipper requirements. These operators aggregate spot-market capacity through auction algorithms rather than dedicated carrier contracts.
- Cold Chain Logistics:Temperature-controlled networks demand continuous monitoring with automated documentation for regulatory audits. Energy intensity in refrigerated transport elevates carbon accounting costs under ISO 14083.
- E-Commerce Fulfillment:High-velocity parcel networks prioritize real-time inventory visibility and dynamic carrier selection. United States suburban corridors drive adoption of drone-ready last-mile platforms under evolving FAA rules.
- Postal Services:Universal service obligations and regulatory pricing constraints shape procurement toward cost-control automation. National operators modernize legacy manifesting systems through API-first overlays.
- Reverse Logistics:Returns processing and refurbishment coordination require distinct workflows from forward distribution. Retail supply chains in Germany invest here to support circular economy mandates.
Third-party logistics anchors revenue concentration; cold chain logistics shows the sharpest growth inflection.
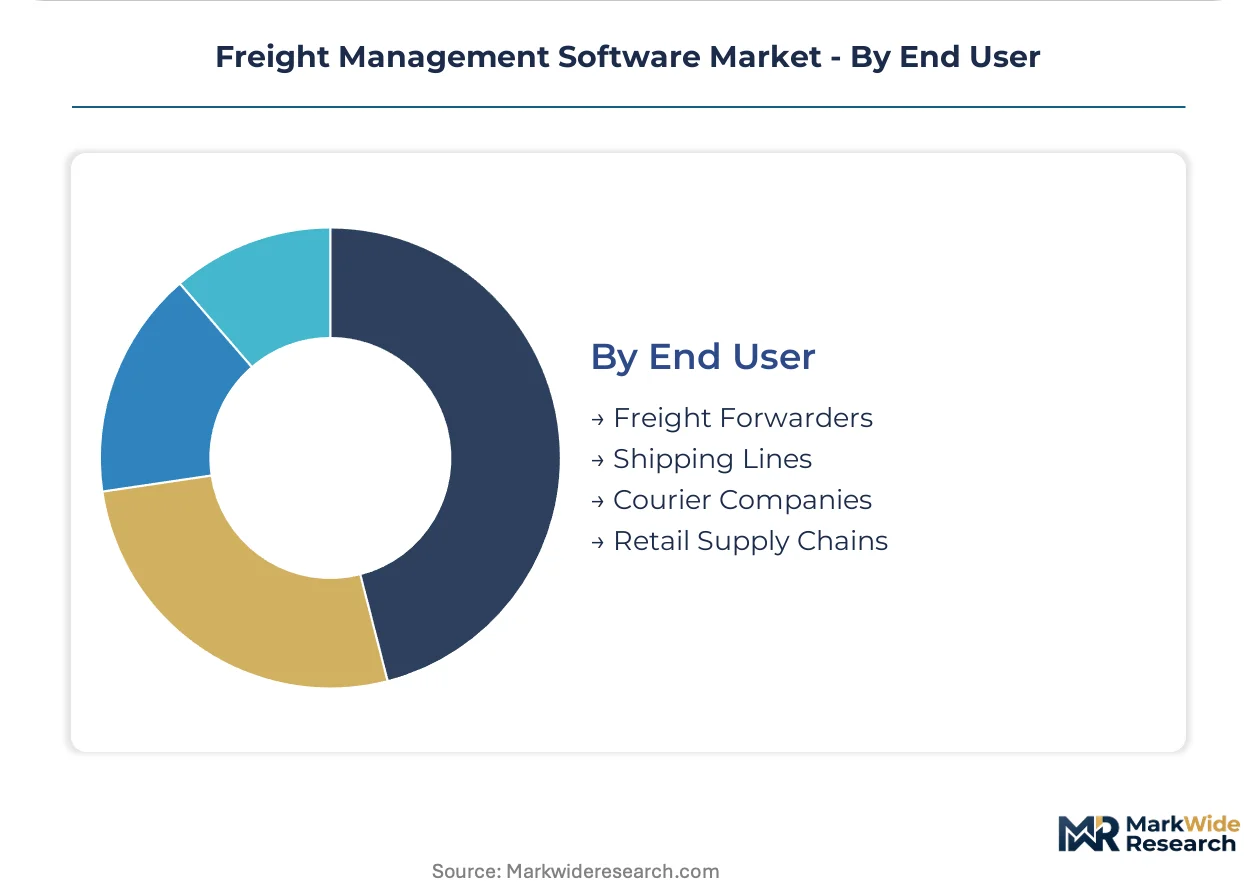
End User:
Supply concentration among integrated carriers versus fragmented forwarders determines platform customization requirements.
- Freight Forwarders:Non-asset-based intermediaries rely on software for carrier procurement, documentation, and exception management. These operators face margin compression as shippers unbundle procurement toward direct digital marketplaces.
- Retail Supply Chains:Omnichannel distributors require unified visibility across owned fleets, contracted carriers, and drop-ship networks. German grocery recalculates safety stock thresholds every four hours using demand sensing integration.
- Shipping Lines:Ocean carriers prioritize vessel scheduling, container yard optimization, and intermodal handoff coordination. These users drive API standardization through industry consortiums.
- Courier Companies:Parcel networks optimize density through dynamic route building and crowd-sourced capacity injection. FAA unmanned aircraft rulemaking opens automated delivery corridors for suburban deployment.
Freight forwarders retain the broadest addressable base; retail supply chains are expanding most quickly as inventory positioning merges with transportation planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retailers deploy cloud-native freight platforms for EU Green Deal compliance, while United States shippers prioritize domestic network consolidation. Chinese operators face divergent pressures from dual carbon targets and cross-border data localization rules.
United States
E-commerce fulfillment networks drive demand for dynamic routing and drone-ready last-mile platforms. FAA unmanned aircraft rulemaking opens suburban airspace corridors for automated delivery. Distribution clusters in Dallas-Fort Worth and Chicago's inland port complex anchor domestic hub rebuilding.
Germany
Retail supply chains recalculate safety stock thresholds every four hours using demand sensing integration. KBA enforces emissions reporting retrofits for road freight operators under EU delegated acts. The Rhine-Ruhr logistics corridor concentrates multimodal platform adoption among grocery distributors.
China
Port operators deploy edge computing nodes for vessel connectivity while anchoring financial settlement onshore. MEE dual carbon goals tighten greenhouse gas quantification requirements for international shipping. The Yangtze River Delta cluster leads API-first carrier integration for export manufacturers.
France
Cold chain specialists face steep compliance costs from ISO 14083 tender preconditions in pharmaceutical distribution. ANSM and CNIL jointly regulate health data flows in temperature-controlled logistics. The Île-de-France region concentrates multimodal freight software investment for Paris basin distribution.
India
Third-party logistics providers aggregate spot-market capacity through auction algorithms rather than dedicated carrier contracts. DGFT trade facilitation rules accelerate customs platform integration for freight forwarders. The Mumbai-Pune logistics corridor drives cloud adoption among non-asset-based intermediaries.
Freight Management Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with ERP-embedded suites competing against standalone transportation management vendors. The upper tier anchors multimodal workflows inside enterprise procurement systems, while specialists differentiate through AI-driven demand sensing or cold chain monitoring. Two dominant competitive moves shape positioning: carbon data partnerships for EU compliance acceleration, and API-first interoperability investments that compress booking-to-settlement cycles.
Within the integrated suite tier, SAP SE and Oracle Corporation occupy positions that leverage database-layer and ERP-embedded architectures respectively. Blue Yonder exemplifies the AI-native specialist archetype, anchoring predictive analytics capabilities that merge inventory positioning with transportation execution. These three entities collectively represent the competitive tension between horizontal platform breadth and vertical workflow depth.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Blue Yonder |
| Descartes Systems Group |
| Manhattan Associates |
| MercuryGate |
| Freightos |
| Shipwell |
| Transporeon |
| Others |
Supply & Pricing Matrix
Multi-tenant SaaS infrastructure economics compress marginal delivery costs below on-premise alternatives, concentrating platform supply among hyperscaler-backed vendors while subscription pricing floors reset around compliance module bundling. This scale dynamic concentrates procurement leverage with German retail chains and United States e-commerce networks that negotiate volume-tiered SaaS contracts incorporating automatic EU Green Deal update cycles.
Pricing Analysis
Contract structures stratify across annual enterprise subscriptions, usage-based transactional tiers, and project-based implementation fees for legacy migration engagements. Price differentiation separates embedded ERP suites with multimodal workflow integration from standalone cargo monitoring point solutions serving cold chain specialists. Cost compression in mid-market SaaS tiers intensifies as Oracle and SAP bundle carbon accounting modules into base platform offerings. Third-party logistics providers exhibit highest price sensitivity due to thin margins and multi-client cost allocation complexity, while pharmaceutical distributors show lowest sensitivity given excursion-triggered claims automation value.
Supply Chain Analysis
United States and Germany anchor cloud-native platform engineering capacity, with India supplying integration specialist talent pools for API-first carrier connectivity projects. Software development draws from open-source middleware libraries, hyperscaler compute infrastructure, and specialized emissions data vendor feeds. Single-source vulnerability concentrates in carbon accounting module providers facing EU delegated act compliance deadlines. Distribution runs through direct enterprise sales organizations for integrated suites and channel partner networks for mid-market standalone deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native freight management platforms face high-growth disruption as API-first architectures displace legacy EDI infrastructure and EU emissions reporting mandates force compliance module adoption across European logistics networks.
For Market Incumbents: Consolidate carbon data partnerships before EU delegated acts harden into mandatory contract terms, locking out late entrants from German retail supply chain tenders. Acquire specialized cold chain monitoring vendors to extend platform depth against Blue Yonder's AI-native demand sensing integration. Anchor multimodal workflows deeper inside SAP and Oracle procurement systems to raise switching costs for enterprise shippers rebuilding domestic United States distribution networks.
For New Entrants and Emerging Players: ISO 14083 fast-track certification offers the most penetrable entry path for emissions compliance specialists targeting French pharmaceutical distributors facing ANSM audit requirements. White-label cargo monitoring modules for United States third-party logistics providers aggregating spot-market capacity through auction algorithms. Pursue edge computing node deployment for maritime shippers in China's Yangtze River Delta seeking vessel connectivity without onshore data round-trips.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API-first interoperability specialists over monolithic suite vendors as carrier connectivity standardization compresses booking-to-settlement cycles. Long-term viability concentrates in platforms embedding predictive analytics that merge inventory positioning with transportation execution. Monitor FAA unmanned aircraft rulemaking progress as the signal indicating drone-ready last-mile platform valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Data Partnership Formation | Accelerates EU Green Deal compliance for German road freight operators facing KBA enforcement deadlines. |
| API-First Platform Integration | Compresses carrier onboarding cycles for United States mid-market freight operators replacing EDI stacks. |
| Edge Computing Node Deployment | Enables real-time reefer temperature analytics for cold chain operators without central server latency. |
| Acquisition of Demand Sensing Specialist | Merges inventory positioning with transportation planning for German grocery distributors recalculating safety stock. |
| Drone-Ready Last-Mile Development | Positions platforms for FAA unmanned aircraft corridor access in United States suburban logistics networks. |
Research Methodology
Operator-level perspectives from logistics technology officers, transportation procurement directors, carrier integration specialists, and cold chain compliance managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation drawing from SEC software vendor filings, EU delegated act regulatory repositories, and customs platform integration documentation. Bottom-up deployment model sizing triangulated against top-down enterprise IT spending pattern analysis across the analysis window.
Sensitivity analysis tested forecast robustness across cloud adoption velocity scenarios and regulatory enforcement timing variations throughout the projection horizon. Segmentation modeling incorporated deployment architecture, solution offering depth, application use case, and end-user concentration dimensions alongside regional adoption pattern differentiation. CAGRs derived from elasticity-adjusted enterprise software spending correlations and freight volume growth coefficients, with specific inputs including API standardization consortium timelines and ISO 14083 tender precondition penetration rates.
Underlying assumptions cover sustained hyperscaler infrastructure cost curves and EU emissions reporting enforcement continuity, with deviation risk concentrated in cross-border data localization rule fragmentation and legacy EDI migration friction. Forecasts reflect these documented conditions with revision triggers tied to material shifts in FAA unmanned aircraft regulatory finalization or carbon accounting vendor consolidation events. Recalibration cycles align with material shifts in carrier API adoption rates and EU delegated act implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Bridge Analysis Software Market
Software & Services
Global Linux Operating System Market
Software & Services
SMS Marketing Software Market
Software & Services
Global Android Kiosk Software Market
Software & Services
Mainframe Software Market
Software & Services
Global Retail Execution Software Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
US Enterprise Legal Management Software Market
Software & Services
Global Neural Network Software Market
Software & Services
Global CMMS Software Market
Software & Services
Product Optimization Software Market
Software & Services
Petcare Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Advanced Product Quality Planning (APQP) Software Market
Software & Services
Cloud Testing and ASQ Software Market