
 Global Data Masking Market | 2026-2036
Global Data Masking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Masking Market Foresight
The gap between static and dynamic data masking architectures is narrowing as enterprises demand real-time obfuscation for cloud-native pipelines. Microsoft Corporation leverages its Azure ecosystem to embed masking directly into data governance workflows. Delphix Corporation anchors its position through programmable data infrastructure that unifies masking with virtualized test environments. IBM Corporation differentiates via mainframe-optimized masking engines that sustain legacy financial system compliance.
Data masking refers to the irreversible transformation of sensitive data elements into structurally similar but non-authentic values, preserving referential integrity while nullifying re-identification risk through techniques such as substitution, shuffling, and format-preserving encryption. Its primary commercial purpose is enabling secure data utilization across development, analytics, and third-party sharing contexts without exposing personally identifiable information or protected health records. Cloud deployment now leads solution type adoption as enterprises migrate analytics workloads, though hybrid configurations capture expanding margin pools where data residency requirements fragment infrastructure. Static masking retains maturity in batch-oriented testing environments, while dynamic masking and tokenization represent the fastest-expanding solution categories as real-time application integration becomes standard.
FDA 21 CFR Part 11, HIPAA Security Rule, and GDPR Article 32 collectively mandate technical safeguards that directly shape data masking procurement specifications across healthcare, financial services, and cross-border data processing operations. The EU AI Act adds emerging compliance obligations for training data anonymization, forcing vendors to certify irreversibility guarantees. Stakeholders must monitor how divergent national data localization statutes reshape deployment architecture requirements and whether format-preserving techniques satisfy emerging cryptographic standards for privacy-enhancing technologies.
Market Dynamics
Cloud-native data pipelines are compressing the latency window between raw data ingestion and masked output, forcing vendors to embed obfuscation directly into streaming architectures rather than bolt it on as a post-processing layer. This structural shift privileges platforms that can operate within Kubernetes-orchestrated environments without performance degradation.
Growth Catalysts
- GDPR Article 32:Mandated technical safeguards for personal data processing compel European financial institutions to deploy irreversible masking before any cross-border analytics transfer.
- Healthcare digitization:HIPAA Security Rule enforcement against ransomware exposure drives US hospital systems to mask patient records in all non-production environments.
- Tokenization standards:PCI DSS 4.0 requirements for primary account number protection accelerate replacement of encryption-heavy legacy architectures in payment processing.
Market Restraints
- Compute cost volatility:Format-preserving encryption algorithms consume 3-7x the CPU cycles of simple substitution, creating unpredictable cloud spend spikes during peak masking workloads.
- Vendor concentration:Three hyperscale cloud providers dominate compliant infrastructure certification, limiting negotiation leverage for mid-market enterprises in Germany and France.
- Legacy mainframe friction:COBOL-based core banking systems resist dynamic masking integration without expensive middleware layers that erode ROI timelines.
Strategic Opportunities
- India's data localization mandate:RBI directives requiring domestic storage of financial records create captive demand for sovereign-cloud masking deployments that foreign vendors cannot easily serve.
- Synthetic data convergence:Generative adversarial networks paired with differential privacy enable entirely artificial dataset creation, displacing traditional masking in AI training pipelines.
- API-first distribution:Masking-as-a-service endpoints allow independent software vendors to embed compliance without building in-house cryptographic expertise.
Industry Challenges
- Cryptographic talent scarcity:Enterprises struggle to hire engineers fluent in both format-preserving encryption and legacy database schema architecture.
- EU AI Act certification timelines:Vendors face 12-18 month validation cycles for irreversibility guarantees, delaying product releases and freezing procurement decisions.
- Cross-cloud policy synchronization:Hybrid deployments fragment masking rule enforcement, creating compliance gaps when data traverses AWS, Azure, and private data centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Masking Market |
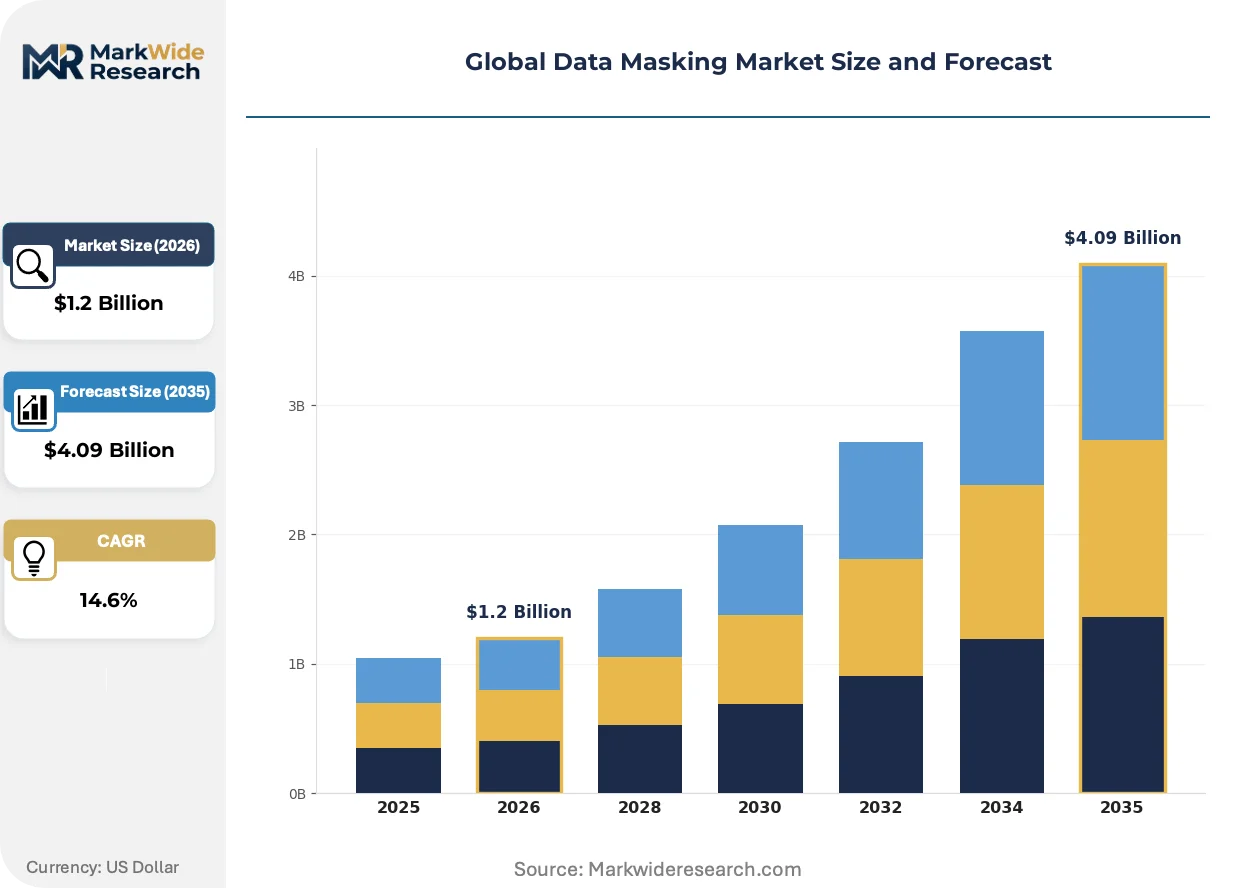
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $4.09 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Virtualized Environments Solution Type: Static Masking, Dynamic Masking, Tokenization, Encryption, Format Preserving Masking Application: Data Analytics, Software Testing, Customer Data Protection, Risk Management, Regulatory Compliance Industry Vertical: BFSI, Information Technology, Telecommunications, Government, Education |
| Companies Covered | Microsoft Corporation, Delphix Corporation, IBM Corporation, Imperva Inc., Micro Focus, Informatica, SAP SE, Protegrity, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Masking Market Shifts & Advancements
Deterministic masking techniques are yielding to probabilistic approaches that withstand re-identification attacks while preserving more analytical utility. This transition reshapes vendor R&D priorities and buyer evaluation criteria simultaneously.
Homomorphic encryption is migrating from academic proof-of-concept to production analytics environments. Healthcare consortiums in Switzerland and the Netherlands pilot privacy-preserving computation on masked genomic datasets. The technology is migrating from batch-oriented research clusters to real-time clinical decision support systems, compressing the acceptable latency threshold from hours to sub-second response times.
The EU AI Act's training data anonymization requirements took effect in February 2025. Vendors must now certify that masking irreversibility withstands linkage attacks by motivated adversaries with auxiliary datasets. German automotive manufacturers and French healthcare AI developers face the steepest compliance curves, driving procurement of third-party cryptographic audit services.
Buyer evaluation criteria now weight masking performance overhead as heavily as security guarantees. Financial services procurement teams in Singapore and the United Kingdom demand sub-5% latency penalties for dynamic masking in high-frequency trading environments. This pressure forces vendors to optimize at the kernel level rather than relying on application-layer abstraction.
Global Data Masking Market Segmentation
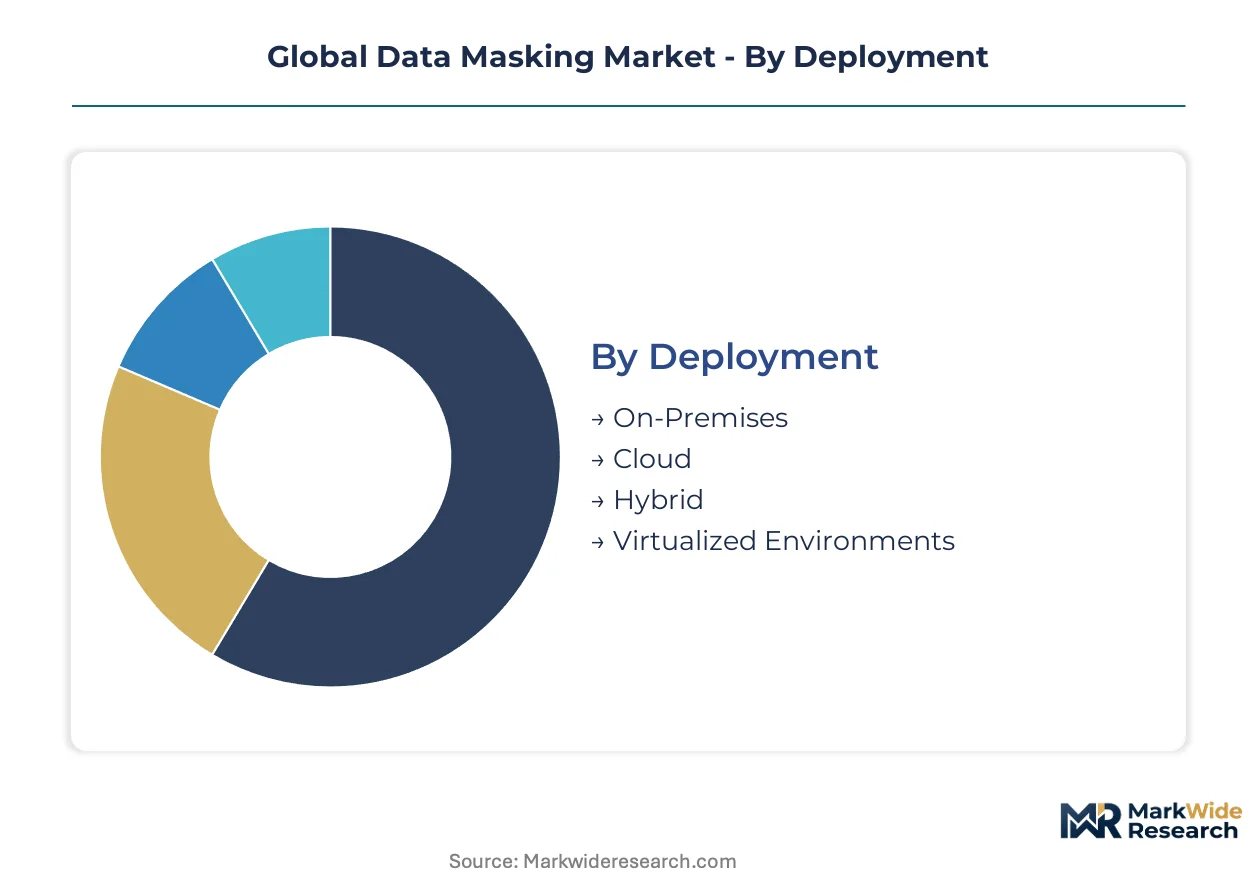
Segmentation reveals how procurement cycles diverge across deployment architectures and compliance use cases. Buyers weight irreversibility guarantees differently depending on whether data streams through cloud-native pipelines or legacy batch systems. Understanding these velocity differences sharpens vendor positioning and R&D resource allocation.
Deployment:
Cloud deployments refresh on quarterly cycles as DevOps teams iterate masking policies, while on-premises installations linger for 3-5 year refresh windows.
- Cloud:Kubernetes-native masking services process streaming data with sub-second latency. Financial services firms in Singapore and the United Kingdom demand sub-5% performance overhead for high-frequency trading environments.
- Hybrid:Split architectures enforce residency rules where sensitive data remains on-premises while analytics workloads shift to public infrastructure. German automotive manufacturers deploy hybrid stacks to satisfy GDPR Article 32 cross-border transfer constraints.
- On-Premises:Air-gapped installations persist in defense and classified government facilities where network segmentation is mandatory.
- Virtualized Environments:Container-agnostic masking layers abstract physical infrastructure from policy enforcement.
On-premises dominates installed base. Cloud is where expansion concentrates.
Solution Type:
Static masking commands premium pricing for irreversibility certification, while dynamic masking spreads through volume-based SaaS tiers.
- Dynamic Masking:Real-time obfuscation intercepts queries at the database protocol layer without persisting transformed values. Healthcare systems in the United States deploy dynamic masking to satisfy HIPAA Security Rule requirements for production environment access controls.
- Tokenization:Vaultless and vault-based schemes replace sensitive elements with non-sensitive equivalents. PCI DSS 4.0 mandates accelerate tokenization replacement of encryption-heavy legacy payment architectures.
- Static Masking:Batch transformation creates sanitized datasets for non-production testing.
- Encryption:Format-preserving algorithms retain data type and length for legacy system compatibility.
- Format Preserving Masking:Character-level substitution maintains referential integrity across relational schemas.
Static masking anchors legacy testing budgets. Dynamic masking and tokenization are climbing the fastest.
Application:
Regulatory compliance applications carry the longest sales cycles due to audit validation requirements, while software testing deployments close faster.
- Regulatory Compliance:EU AI Act anonymization mandates and FDA 21 CFR Part 11 technical safeguards drive procurement of certified irreversibility platforms. Vendors face 12-18 month validation timelines for cryptographic guarantees.
- Data Analytics:Privacy-preserving computation on masked datasets enables cross-organizational research without data pooling. Swiss healthcare consortiums pilot homomorphic encryption on genomic data.
- Software Testing:Production-data replication into development environments requires systematic PII neutralization.
- Customer Data Protection:Contact center and CRM masking prevents insider exposure of financial and health records.
- Risk Management:Quantified exposure modeling depends on realistic but non-authentic data distributions.
Software testing represents the largest volume segment. Regulatory compliance is gaining share fastest.
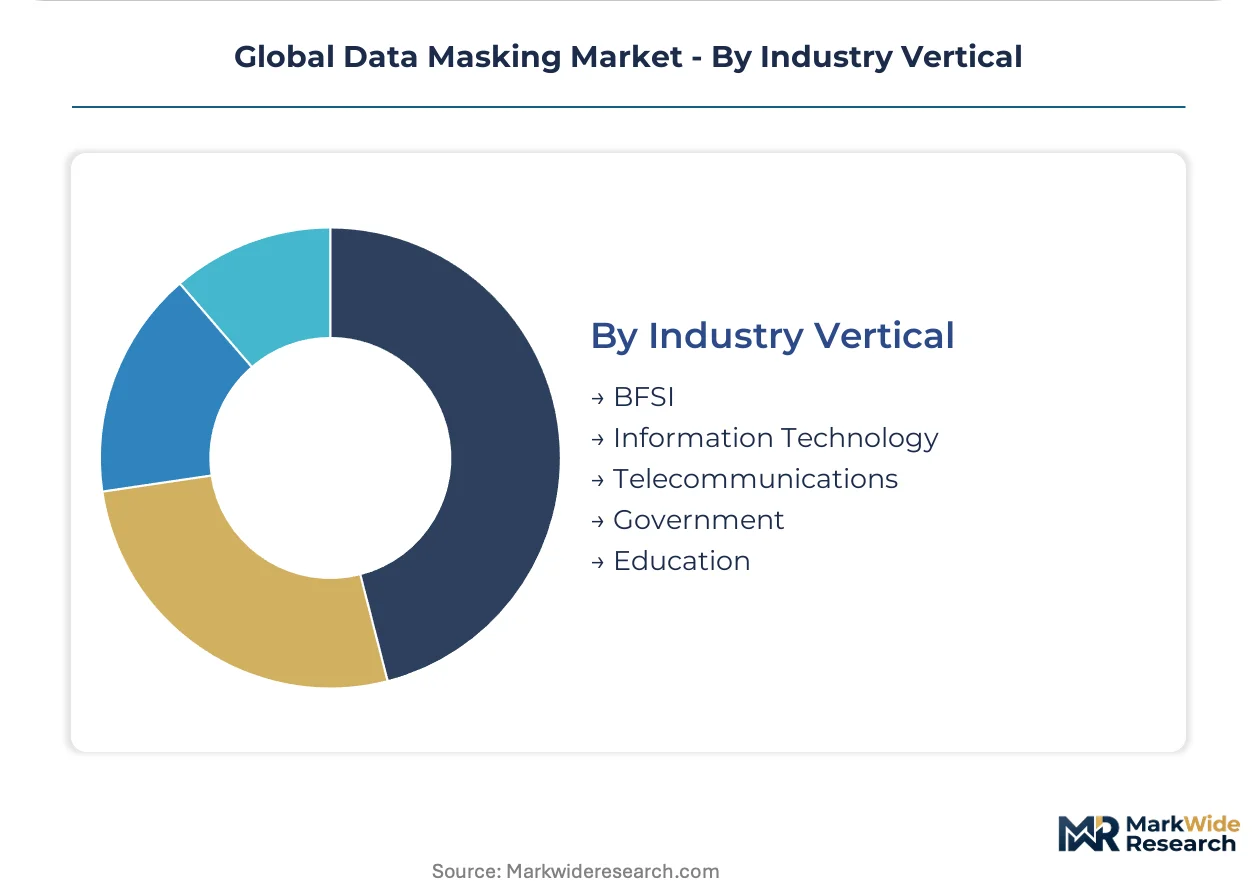
Industry Vertical:
BFSI procurement teams evaluate masking vendors against sovereign-cloud certification requirements, while education buyers prioritize cost efficiency over advanced features.
- BFSI:RBI data localization directives in India create captive demand for domestic masking infrastructure that foreign hyperscalers cannot easily serve. Core banking modernization drives replacement of COBOL-era static masking with API-first dynamic solutions.
- Information Technology:SaaS providers embed masking-as-a-service endpoints to offer compliance without building in-house cryptographic expertise.
- Telecommunications:Subscriber data retention mandates require long-term masking for analytics while preserving lawful intercept capabilities.
- Government:Classified and unclassified network separation demands air-gapped static masking with hardware security module integration.
- Education:Student information system vendors deploy lightweight masking for FERPA compliance in cloud-hosted learning management platforms.
BFSI dominates installed base. Information Technology is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports data masking solutions to financial institutions across Southeast Asia and the Middle East, while the United States ships enterprise-grade platforms to European banks modernizing core systems. Germany and Singapore serve as regional compliance hubs, translating regulatory mandates into procurement specifications for neighboring markets.
United States
HIPAA Security Rule enforcement against ransomware exposure drives hospital systems to mask patient records in all non-production environments. The FDA's 21 CFR Part 11 technical safeguard mandates shape procurement specifications for pharmaceutical data pipelines. Healthcare AI developers in Boston and San Francisco deploy dynamic masking to satisfy emerging training data anonymization requirements.
Germany
GDPR Article 32 compels financial institutions to deploy irreversible masking before any cross-border analytics transfer. The EU AI Act's February 2025 anonymization deadlines force automotive manufacturers and healthcare AI developers to procure third-party cryptographic audit services. Industrial software clusters in Munich and Stuttgart integrate masking into smart manufacturing data lakes.
India
RBI data localization directives requiring domestic storage of financial records create captive demand for sovereign-cloud masking deployments. The country's national IT regulator pushes financial institutions toward API-first dynamic solutions as core banking modernization accelerates. Technology corridors in Bangalore and Hyderabad host domestic vendors building compliant infrastructure for regional banks.
Singapore
Monetary Authority of Singapore guidelines for cloud risk management drive financial services procurement teams to demand sub-5% latency penalties for dynamic masking in high-frequency trading environments. The country's data protection authority enforces strict cross-border transfer rules for fintech data. Trading infrastructure in the central business district embeds real-time obfuscation directly into streaming architectures.
Switzerland
Swissmedic and the national data protection authority jointly oversee healthcare data anonymization standards that exceed baseline EU requirements. Healthcare consortiums pilot homomorphic encryption on masked genomic datasets for privacy-preserving clinical research. Precision medicine clusters in Basel and Zurich compress latency thresholds from hours to sub-second response times for real-time decision support.
Global Data Masking Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment architectures, with hyperscale cloud providers leveraging infrastructure certification dominance against vendors offering programmable data infrastructure. The market structure tilts toward consolidation at the infrastructure layer while fragmenting across application-specific tooling. Three archetypes dominate: ecosystem-embedded platforms, virtualized test environment specialists, and mainframe-optimized engine providers. Competitive moves center on API-first distribution partnerships and synthetic data convergence through generative adversarial network integration.
Among ecosystem-embedded platforms, Microsoft Corporation exemplifies the channel-control archetype through Azure-native governance workflow integration. Delphix Corporation occupies a position within the programmable infrastructure tier, unifying masking with virtualized test environments. IBM Corporation anchors the legacy system specialist segment, sustaining mainframe-optimized engines for financial services compliance. These three represent distinct strategic postures rather than direct substitution competitors.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Delphix Corporation |
| IBM Corporation |
| Imperva Inc. |
| Micro Focus |
| Informatica |
| SAP SE |
| Protegrity |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Hyperscale cloud infrastructure concentration in the United States, Germany, and India concentrates margin pools at the platform orchestration layer rather than the masking engine itself. Buyers in financial services and healthcare absorb premium pricing for certified irreversibility guarantees while mid-market enterprises face compressed SaaS tiers without sovereign-cloud validation.
Pricing Analysis
Current-generation Kubernetes-native dynamic masking commands subscription premiums against prior-generation static batch tools and emerging next-generation homomorphic encryption suites. Three-tier pricing structure across premium certification-grade, standard enterprise, and economy developer tiers reflects GDPR Article 32 compliance depth and performance overhead guarantees. Pricing pressure stems from format-preserving encryption's 3-7x CPU cycle consumption driving cloud spend unpredictability. Healthcare systems exhibit highest price sensitivity due to constrained IT budgets, while BFSI procurement teams prioritize certification over cost.
Supply Chain Analysis
Extended payment terms from hyperscale cloud providers and supply-chain finance facilities from regional sovereign-cloud operators shape vendor cash flow dynamics. Software development concentrates in the United States, Germany, and India, with cryptographic talent pipelines drawing from Israeli and Swiss academic clusters. Raw material dependencies span HSM hardware from Thales/Gemalto, open-source cryptographic libraries, and specialized FPGA acceleration cards. Single-source vulnerability concentrates around three hyperscale infrastructure certification bodies. Distribution runs through API-first SaaS marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineers fluent in both format-preserving encryption and legacy COBOL schema architecture command scarcity premiums, constraining vendor scaling velocity and inflating implementation timelines for mainframe modernization projects.
For Market Incumbents: Build certification moats around EU AI Act irreversibility validation and RBI sovereign-cloud accreditation. Deepen upstream control over HSM hardware partnerships to secure cryptographic supply chains. Counter synthetic data displacement threats by integrating generative adversarial network capabilities into existing masking platforms. For New Entrants and Emerging Players: Establish a beachhead in India's captive sovereign-cloud masking demand created by RBI data localization mandates. Target mid-market German automotive manufacturers facing compressed EU AI Act compliance timelines. Pursue API-first distribution partnerships with SaaS providers lacking in-house cryptographic expertise. For Investors and Strategic Acquirers: Capital is best deployed toward programmable data infrastructure specialists unifying masking with virtualized test environments, positioned for long-term viability as DevOps automation converges with compliance tooling. Monitor homomorphic encryption latency compression below sub-second thresholds as the inflection signal for next-generation platform displacement.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Delays product releases by 12-18 months but locks out non-compliant competitors from German and French procurement cycles. |
| Sovereign-Cloud Partnership | RBI mandates create captive revenue streams inaccessible to foreign hyperscalers serving Indian financial institutions. |
| Homomorphic Encryption Integration | Swiss healthcare consortiums pilot sub-second genomic analytics, compressing acceptable latency thresholds for clinical decision support. |
| Synthetic Data Convergence | Generative adversarial networks with differential privacy displace traditional masking in AI training pipelines across Boston and San Francisco developers. |
| API-First Distribution Expansion | Masking-as-a-service endpoints allow SaaS vendors to embed compliance without building in-house cryptographic expertise. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, hyperscaler capex disclosures, and regulatory certification databases. Primary interviews engaged CISOs at BFSI institutions, data governance officers at healthcare systems, DevOps platform engineers, and procurement leads at German automotive manufacturers. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA GDPR implementation reports, and RBI circulars on data localization. Bottom-up deployment counts triangulate against top-down addressable market sizing.
Forecast inputs span deployment architecture evolution, solution type migration velocity, and vertical procurement cycle compression. Segmentation dimensions modeled include cloud-native versus legacy infrastructure, dynamic versus static masking adoption curves, BFSI versus healthcare compliance intensity, and regional regulatory framework divergence. CAGRs derive from fitted growth curves against historical procurement velocity benchmarks. Industry-specific inputs incorporate EU AI Act certification timeline delays and format-preserving encryption performance overhead trajectories.
Sensitivities concentrate around EU AI Act enforcement variance, sovereign-cloud mandate expansion beyond India, and homomorphic encryption latency breakthroughs. Forecasts embed assumptions regarding cryptographic talent pipeline expansion and hyperscale infrastructure certification continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Asia-Pacific Extended Detection and Response Market
Security Software
Public Cloud Management and Security Services Market
Security Software
Hardware Encryption Market
Security Software
Global Data Protection As a Service (Dpaas) Market
Security Software
Automotive Endpoint Authentication Market
Security Software
Global Secure Access Service Edge Market
Security Software
AI in Security Market
Security Software
Application Control Software Market
Security Software
Global Mobile Identification Market
Security Software
Mobile Identity Management Market
Security Software
Global Log Management Market
Security Software
Asia-Pacific Encryption Software Market
Security Software
DNS Protection Software Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
Global Data Loss Prevention Software Market
Security Software
Video Intercom Devices and Equipment Market