
 Asia-Pacific Encryption Software Market | 2026-2036
Asia-Pacific Encryption Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Encryption Software Market Analytics
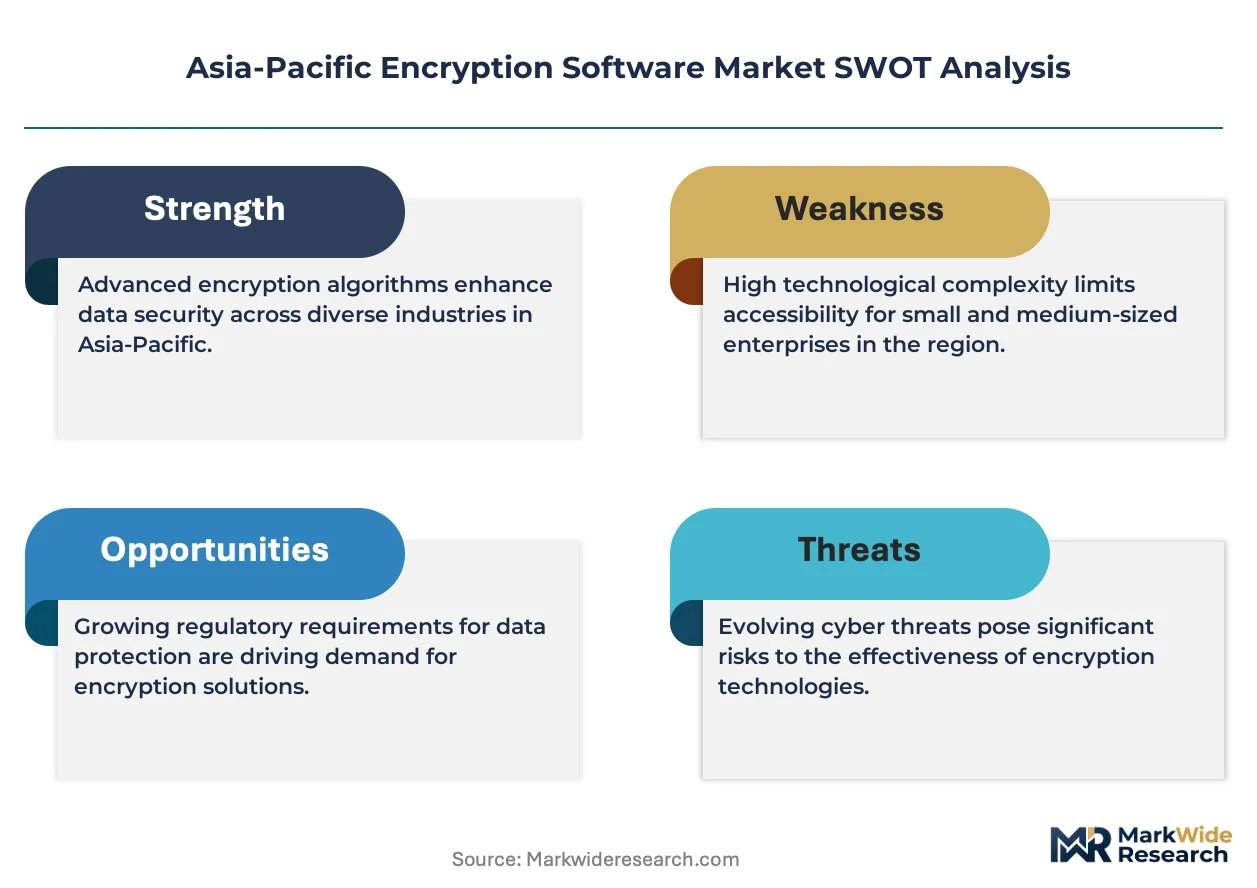
China's Cryptography Law is rebalancing the cost-of-entry calculus for foreign encryption vendors seeking commercial licenses. IBM leverages its quantum-safe cryptography portfolio to anchor enterprise contracts across Japanese financial institutions. Microsoft sustains cloud-native encryption dominance through Azure integration with Australia's government cloud frameworks. Sophos competes on mid-market endpoint encryption with bundled managed detection and response services.
Encryption software encompasses cryptographic algorithms, key management infrastructure, and access control protocols that transform readable data into ciphertext using standards such as AES-256 and RSA-4096, serving to protect confidentiality, integrity, and non-repudiation across digital transactions and stored records. Cloud-based deployment leads revenue contribution as enterprises migrate sensitive workloads to distributed infrastructure, while database encryption represents the fastest-growing product type due to regulatory pressure on structured financial and health records. Communication encryption occupies mature margin pools in mature economies, whereas disk encryption shows commoditization pressure from operating-system native tools.
India's BIS certification requirements, Australia's ASD Essential Eight framework, and Japan's JIS standards collectively shape product specifications and procurement eligibility across the region. Compliance timelines from these bodies are compressing vendor development cycles and elevating audit costs for market participants. Stakeholders must monitor evolving cross-border data flow restrictions and quantum computing threat timelines to align R&D roadmaps with regulatory and technological inflection points.
Market Dynamics
Cross-border data sovereignty mandates are compressing vendor development cycles across the Asia-Pacific Encryption Software Market, forcing rapid certification alignment with divergent national cryptography regimes.
Growth Catalysts
- India's Digital Personal Data Protection Act:Mandatory encryption for sensitive personal data is compelling financial institutions and health networks to upgrade legacy protection layers, creating immediate procurement windows for certified solutions.
- Quantum-safe migration urgency:Japanese financial institutions are accelerating post-quantum cryptography pilots ahead of NIST standard finalization, establishing early-mover infrastructure commitments.
- Australia's critical infrastructure designation:ASD Essential Eight compliance deadlines for energy and telecommunications operators are mandating database and communication encryption at scale.
Market Restraints
- License fragmentation under China's Cryptography Law:Commercial encryption product approval timelines extend 18-24 months for foreign vendors, creating asymmetric market access against domestic suppliers.
- Skilled cryptographer scarcity:Implementation of hardware security module integration and key management infrastructure requires specialized talent concentrated in Bangalore, Singapore, and Tokyo metro areas.
- Native OS encryption commoditization:Windows BitLocker and macOS FileVault are displacing standalone disk encryption purchases in mid-market enterprise segments.
Strategic Opportunities
- Vietnam and Philippines financial digitization:Central bank real-time payment system rollouts are creating greenfield encryption requirements for transaction integrity and non-repudiation.
- Homomorphic encryption convergence with confidential computing:Cloud service providers are piloting privacy-preserving analytics for healthcare and BFSI workloads without decryption exposure.
- South Korea's K-ISMS certification expansion:Mandatory encryption for cloud service providers under amended information security management standards is opening government and enterprise procurement channels.
Industry Challenges
- Multi-jurisdiction key escrow requirements:China's commercial encryption regulations and India's data localization mandates create conflicting key custody architectures for regional enterprises.
- Legacy mainframe integration complexity:Southeast Asian banks running COBOL-based core banking systems face prohibitive costs for modern cryptographic API retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Encryption Software Market |
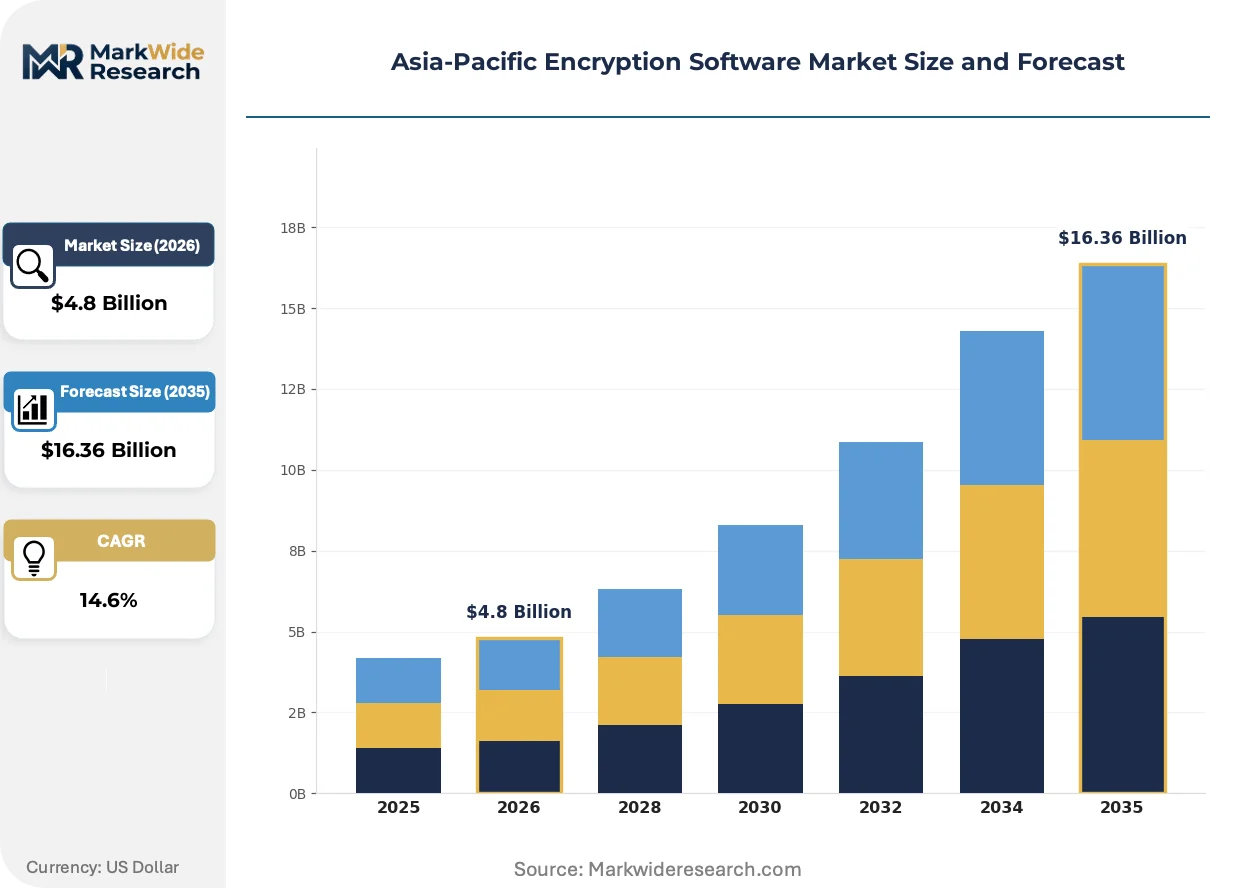
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Service End User: Healthcare, BFSI, Government, IT & Telecom Product Type: File Encryption, Disk Encryption, Database Encryption, Communication Encryption Solution: Encryption Management, Key Management, Tokenization, Data Masking |
| Companies Covered | IBM, Microsoft, Thales, Sophos, Trend Micro, Check Point Software Technologies, Broadcom, Dell Technologies, Cisco Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Encryption Software Market Evolving Landscape
Zero-trust architecture adoption is redistributing encryption deployment patterns from perimeter-focused to data-centric protection models, reshaping vendor competitive positioning across the Asia-Pacific Encryption Software Market.
Confidential computing with hardware-based trusted execution environments is decentralizing key management authority from centralized HSM appliances to distributed cloud nodes. Major Australian government cloud frameworks are mandating confidential computing for secret-classified workloads, compressing traditional encryption software margins while expanding attestation and key-derivation service attach rates.
Japan's amended Act on the Protection of Specially Designated Secrets is tightening encryption standards for defense contractors and critical infrastructure operators. METI guidance now requires AES-256 or equivalent for all classified data transmission, with compliance audits accelerating in Tokyo and Osaka industrial corridors. Vendors are responding with pre-certified solution bundles to compress procurement timelines.
Consumption patterns among Asia-Pacific enterprises are rotating from perpetual license procurement toward embedded encryption-as-a-service within cloud infrastructure contracts. Managed service providers in Singapore and Sydney are unbundling standalone encryption sales, instead integrating cryptographic functions into broader security operations center offerings. This shift is most visible in mid-market BFSI segments where CISOs prioritize operational simplicity over best-of-breed point solutions.
Asia-Pacific Encryption Software Market Segmentation
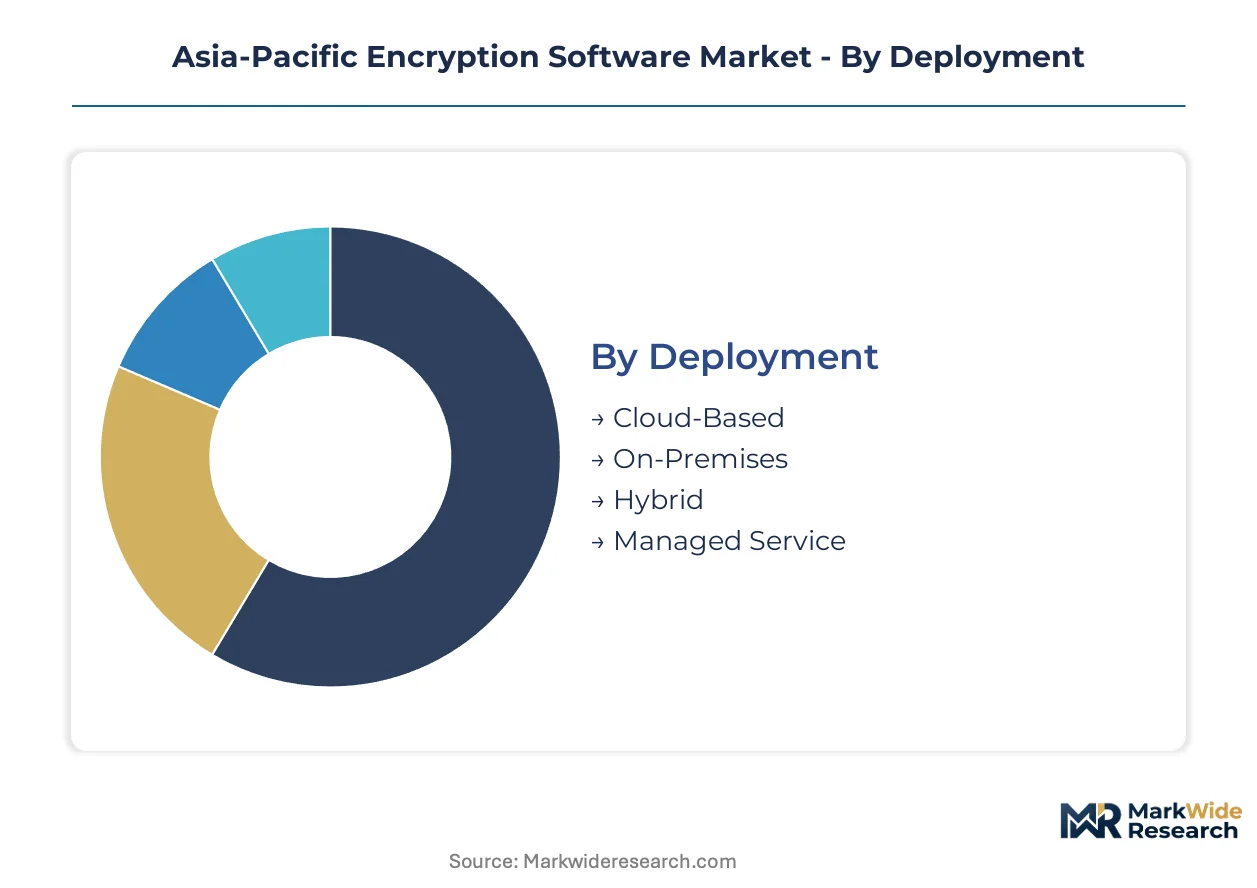
Encryption software procurement across Asia-Pacific diverges sharply by infrastructure maturity and regulatory pressure. Deployment choices reflect sovereignty mandates in China and India against cloud-first preferences in Australia and Singapore. Product specialization tracks sector-specific compliance deadlines, with database and communication encryption commanding premium positioning.
Deployment:
Standardization dominates at the infrastructure layer while customization intensifies at the policy and key management tiers across this category.
- Cloud-Based:Distributed infrastructure with native integration into hyperscaler platforms. Australian government cloud frameworks and Singapore's financial services sector are concentrating procurement here, driven by ASD Essential Eight compliance deadlines and MAS technology risk management guidelines.
- On-Premises:Dedicated hardware security module deployments with full key custody control. China's commercial encryption regulations and India's data localization mandates under the Digital Personal Data Protection Act are preserving demand in state-owned enterprises and defense contractors.
- Hybrid:Split workloads with sensitive data retained on-premises and analytics in cloud environments. Japanese manufacturers in Osaka and Nagoya industrial corridors favor this architecture for intellectual property protection.
- Managed Service:Outsourced encryption operations with service-level agreements covering key lifecycle management. Mid-market BFSI segments in Vietnam and the Philippines are adopting this to address skilled cryptographer scarcity.
Leading the category by volume: Cloud-Based. Expanding most quickly: Managed Service.
End User:
Regulatory stringency creates sharp tiering across customer types, with compliance timelines rather than budget cycles driving purchasing decisions.
- BFSI:Real-time payment system protection and cross-border transaction integrity. India's financial technology corridor and Australia's major banks are upgrading legacy protection layers ahead of RBI and APRA prudential standards.
- Government:Classified data transmission and critical infrastructure designation compliance. Japan's Act on the Protection of Specially Designated Secrets and Australia's Critical Infrastructure Act are mandating AES-256 or equivalent standards.
- Healthcare:Patient record confidentiality with structured data encryption requirements. India's health networks are responding to Digital Personal Data Protection Act mandatory encryption provisions.
- IT & Telecom:Network traffic protection and subscriber data privacy. South Korea's K-ISMS certification expansion is opening procurement channels for cloud service providers in this segment.
BFSI captures the largest absolute spend. Government procurement is climbing the fastest on classified workload mandates.
Product Type:
Maturity gradients separate commoditized perimeter tools from high-margin data-centric protection layers in this category.
- Database Encryption:Structured record protection with transparent data encryption and column-level granularity. Regulatory pressure on financial and health records in India and Australia is accelerating replacement of legacy access controls.
- Communication Encryption:In-transit data protection for email, messaging, and voice protocols. Mature margin pools in Japanese and Australian enterprise segments face compression from native platform integration.
- File Encryption:Document-level protection with policy-driven access controls. Professional services firms in Singapore and Hong Kong deploy this for client confidentiality.
- Disk Encryption:Full-volume encryption for endpoint and server storage. Windows BitLocker and macOS FileVault are displacing standalone purchases in mid-market segments across Southeast Asia.
Communication Encryption leads by installed base. Database Encryption shows the steepest expansion trajectory on compliance deadlines.
Solution:
Value capture migrates upward from raw cryptographic functions toward policy orchestration and lifecycle governance in this category.
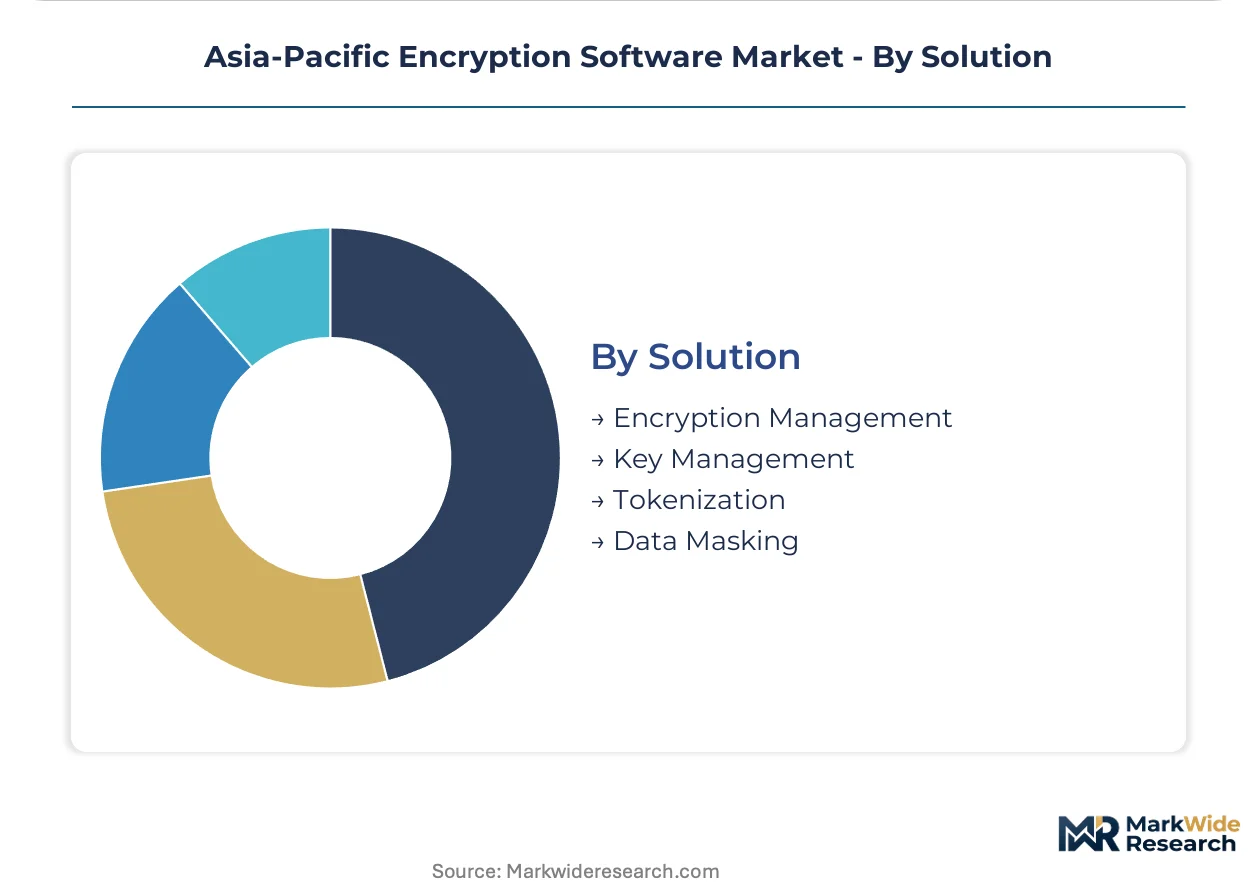
- Key Management:Centralized generation, distribution, and rotation of cryptographic keys with hardware security module integration. Tokyo and Bangalore metro areas concentrate implementation talent for this capability.
- Encryption Management:Policy definition and enforcement across heterogeneous encryption deployments. Australian energy and telecommunications operators under ASD Essential Eight deadlines are prioritizing unified visibility.
- Tokenization:Sensitive data substitution with non-sensitive equivalents preserving format and functionality. Payment processors in India's UPI ecosystem and Australia's NPP are deploying this for transaction integrity.
- Data Masking:Obfuscation of production data for non-production environments. Healthcare analytics platforms in Japan and South Korea use this for privacy-preserving research collaboration.
Key Management commands premium pricing. Tokenization is gaining share fastest on real-time payment system rollouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's financial technology corridor and Australia's critical infrastructure protection programs anchor encryption software concentration across the Asia-Pacific region, with compliance mandates compressing procurement timelines in both markets.
India
BFSI institutions and health networks are upgrading legacy protection layers ahead of RBI prudential standards. The Digital Personal Data Protection Act mandates encryption for sensitive personal data, creating immediate procurement windows. Bangalore and Mumbai financial technology clusters are driving demand for database and communication encryption solutions.
Australia
Energy and telecommunications operators face ASD Essential Eight compliance deadlines mandating database encryption at scale. The Critical Infrastructure Act tightens standards for designated sectors. Sydney and Melbourne enterprise corridors are prioritizing unified encryption management visibility across hybrid deployments.
Japan
Financial institutions are accelerating post-quantum cryptography pilots ahead of NIST standard finalization. METI guidance requires AES-256 or equivalent for classified data transmission under the amended Act on the Protection of Specially Designated Secrets. Tokyo and Osaka industrial corridors are deploying pre-certified solution bundles to compress procurement timelines.
China
State-owned enterprises and defense contractors preserve demand for on-premises hardware security module deployments with full key custody control. The Cryptography Law extends commercial encryption product approval timelines for foreign vendors. Beijing and Shanghai technology zones are concentrating domestic supplier procurement.
South Korea
Cloud service providers face mandatory encryption requirements under expanded K-ISMS certification standards. The amended information security management framework opens government and enterprise procurement channels. Seoul Capital Area data centers are piloting confidential computing integration with hardware-based trusted execution environments.
Asia-Pacific Encryption Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: hyperscale cloud platforms with native encryption integration, cybersecurity incumbents bundling encryption with broader security operations, and specialized cryptographic infrastructure providers. Dominant competitive moves include strategic partnerships with managed service providers and portfolio diversification into quantum-safe cryptography.
Within the cloud platform tier, Microsoft exemplifies native encryption integration through hyperscaler infrastructure, while IBM anchors enterprise positioning around quantum-safe cryptography portfolios. Among cybersecurity-focused providers, Sophos occupies a mid-market position bundling endpoint encryption with managed detection services. Thales represents specialized cryptographic infrastructure archetypes with hardware security module and key management concentration.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Thales |
| Sophos |
| Trend Micro |
| Check Point Software Technologies |
| Broadcom |
| Dell Technologies |
| Cisco Systems |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between quantum-ready and legacy encryption tiers manifests in pricing premiums of 40-60% for NIST-aligned post-quantum portfolios, while supply chains bifurcate between hardware security module manufacturers in China and software-centric key management providers in Singapore and Australia. This tier split concentrates procurement leverage with hyperscaler cloud platforms that bundle encryption into infrastructure contracts, compressing standalone vendor margins while elevating attestation service attach rates.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with 90-day certification timelines commanding 25-35% premiums over spot inventory from pre-certified solution bundles. Subscription-based SaaS tiers with embedded key management anchor enterprise contracts, while price differentiation rests on FIPS 140-2 certification grade and quantum-safe algorithm readiness. Pricing pressure stems from operating-system native encryption tools displacing standalone disk encryption purchases. Mid-market BFSI segments exhibit highest price sensitivity, whereas defense contractors and critical infrastructure operators show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Reverse-logistics flows for hardware security module refurbishment and key destruction services concentrate in Singapore and Tokyo metro areas, creating secondary margin pools for certified destruction providers. Component sourcing draws from semiconductor foundries in Taiwan, cryptographic chip designers in South Korea, and specialized HSM assembly in China. Single-source vulnerability runs through Taiwan-based secure element manufacturing. Distribution feeds from direct vendor-to-enterprise sales for large deployments, with managed service providers in Sydney and Bangalore handling mid-market aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over hardware security module manufacturing and quantum-safe algorithm IP determines long-term margin capture. Players are pursuing backward integration into cryptographic chip design to secure supply and differentiate on certification timelines.
For Market Incumbents: Deepen hardware security module manufacturing partnerships in Taiwan and South Korea to secure chip supply against export restriction risks. Consolidate quantum-safe cryptography patent portfolios ahead of NIST standard finalization, while acquiring managed detection and response capabilities to bundle encryption with broader security operations and defend against pure-play cryptographic specialists. For New Entrants and Emerging Players: Managed service providers in Vietnam and the Philippines represent the most penetrable channel partner type for addressing skilled cryptographer scarcity through outsourced encryption operations. Target real-time payment system rollouts in Southeast Asian financial corridors with tokenization solutions for transaction integrity. Pursue K-ISMS certification alignment to access South Korean government and enterprise procurement channels. For Investors and Strategic Acquirers: Re-rating potential sits with specialized cryptographic infrastructure providers given quantum-safe migration urgency and certification backlog compression. Long-term viability centers on 5-10 year control of post-quantum algorithm IP and hardware security module manufacturing relationships. Monitor NIST standard finalization timelines and China's Cryptography Law enforcement patterns as inflection indicators for vendor market access and valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Safe Cryptography Portfolio Launch | Japanese financial institutions are accelerating pilots ahead of NIST standard finalization. |
| Hardware Security Module Manufacturing Scale-Up | Taiwan and South Korea foundries anchor supply for China's commercial encryption regulations. |
| Managed Detection and Response Bundling | Sophos competes in mid-market segments by integrating endpoint encryption with SOC services. |
| Confidential Computing Platform Integration | Australian government cloud frameworks mandate hardware-based trusted execution environments. |
| K-ISMS Certification Pathway Completion | South Korea's amended standards open government procurement for cloud service providers. |
Research Methodology
Document review covered regulatory filings from India's BIS, Australia's ASD, and Japan's METI, complemented by interviews with CISOs at BFSI institutions, encryption vendor product managers, and cloud platform security architects. Secondary validation drew from NIST post-quantum cryptography standardization documents, RBI prudential standards circulars, and APRA information security guidelines. Bottom-up triangulation across deployment models and end-user segments was cross-referenced with top-down market sizing from hyperscaler infrastructure disclosures and hardware security module shipment data.
Cross-reference between historical certification timeline patterns and expert panel input on quantum-safe migration urgency shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user regulatory stringency tier, product type maturity gradient, and solution value-capture level. CAGRs were derived from elasticity-adjusted demand curves reflecting compliance deadline clustering and technology replacement cycles. Forecast inputs incorporated BIS certification queue lengths and ASD Essential Eight compliance penetration rates.
Caveats apply where NIST post-quantum standard finalization delays, China's Cryptography Law enforcement intensification, or Taiwan semiconductor supply disruptions could materially shift the outlook. Practitioners should monitor cross-border data flow restriction announcements and quantum computing breakthrough disclosures for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Broadcast Censorship Solutions Market
Security Software
Extended Detection and Response Market
Security Software
Global Runtime Application Self-Protection Market
Security Software
Europe Anti-Money Laundering Software Market
Security Software
Global Secure Access Service Edge Market
Security Software
Single Sign-On Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
United States Lawful Interception Market
Security Software
Data Masking Technology Market
Security Software
Asia-Pacific Smart Doorbell Market
Security Software
POS Security Market
Security Software
Global Consumer Identity and Access Management Market
Security Software
Global Anti-Spam Software Market
Security Software
Global IMSI Catcher Market
Security Software
Employee Fraud Detection Market
Security Software
Embedded Security Market