
 Global Log Management Market | 2026-2036
Global Log Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Log Management Market Foresight
The gap between premium real-time analytics platforms and commodity log storage is restructuring procurement patterns across enterprise security teams. Splunk Inc. dominates high-throughput security information and event management with proprietary query languages and extensive partner ecosystems. Datadog Inc. competes on cloud-native observability integration, while Elasticsearch B.V. anchors open-source deployments with flexible indexing architectures.
Log management encompasses the systematic collection, indexing, storage, and analysis of machine-generated event data from servers, applications, and network devices, typically processing terabyte-scale daily volumes with retention policies spanning 90 days to seven years depending on regulatory requirements. Its primary purpose is enabling forensic investigation, operational diagnostics, and automated threat response across distributed IT environments. Cloud-based deployment is capturing the fastest expansion as organizations retire on-premises data lake investments, while compliance reporting within solution offerings commands premium pricing due to auditor-validated template libraries. Threat detection use cases lead security-focused spending, though operational troubleshooting retains steady renewal rates in telecom operator accounts.
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules are collectively extending mandatory log retention periods and demanding immutable audit trails for algorithmic decision systems. HIPAA and PCI-DSS in the United States impose comparable technical controls on healthcare and payment processing infrastructures. Stakeholders must evaluate whether their current ingestion architectures can scale to emerging quantum-resistant encryption standards without rewriting core parsing pipelines.
Market Dynamics
Cloud-native observability architectures are compressing procurement cycles as enterprises retire on-premises data lake investments, forcing vendors to restructure pricing around ingestion volume rather than perpetual licensing.
Growth Catalysts
- GDPR and EU AI Act mandates:Immutable audit trail requirements for algorithmic decision systems are extending mandatory log retention periods across financial services and healthcare infrastructures in Germany, France, and the Netherlands.
- Operational technology convergence:Industrial IoT deployments in manufacturing and energy are generating machine telemetry that demands unified security and operational log pipelines.
- SEC cybersecurity disclosure rules:Public companies in the United States face accelerated incident reporting timelines that require real-time log correlation and automated threat detection capabilities.
Market Restraints
- Storage cost volatility:Cloud object storage pricing fluctuations and egress fee structures create unpredictable total cost of ownership for high-volume retention scenarios exceeding 90 days.
- Parser standardization gaps:Proprietary log formats from legacy network equipment and custom applications require expensive manual parsing rule development before ingestion.
- Encryption upgrade cycles:Migration to quantum-resistant cryptographic standards threatens to invalidate existing indexing architectures without complete pipeline rewrites.
Strategic Opportunities
- India's digital public infrastructure:The country's expanding stack of identity, payment, and health registries creates demand for sovereign log analytics that keeps data within national boundaries.
- Federated query architectures:Edge-to-cloud log streaming combined with local preprocessing is rewriting cost structures for distributed retail and telecommunications footprints.
- Japan's operational technology security guidelines:METI-directed standards for critical infrastructure monitoring are mandating specialized log management for power generation and transportation systems.
Industry Challenges
- Observability engineer scarcity:Organizations struggle to hire personnel fluent in both security information and event management query languages and cloud-native instrumentation frameworks.
- Multi-year retention compliance:HIPAA and PCI-DSS mandates for seven-year log immutability conflict with cloud provider data lifecycle policies, forcing hybrid architecture complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Log Management Market |
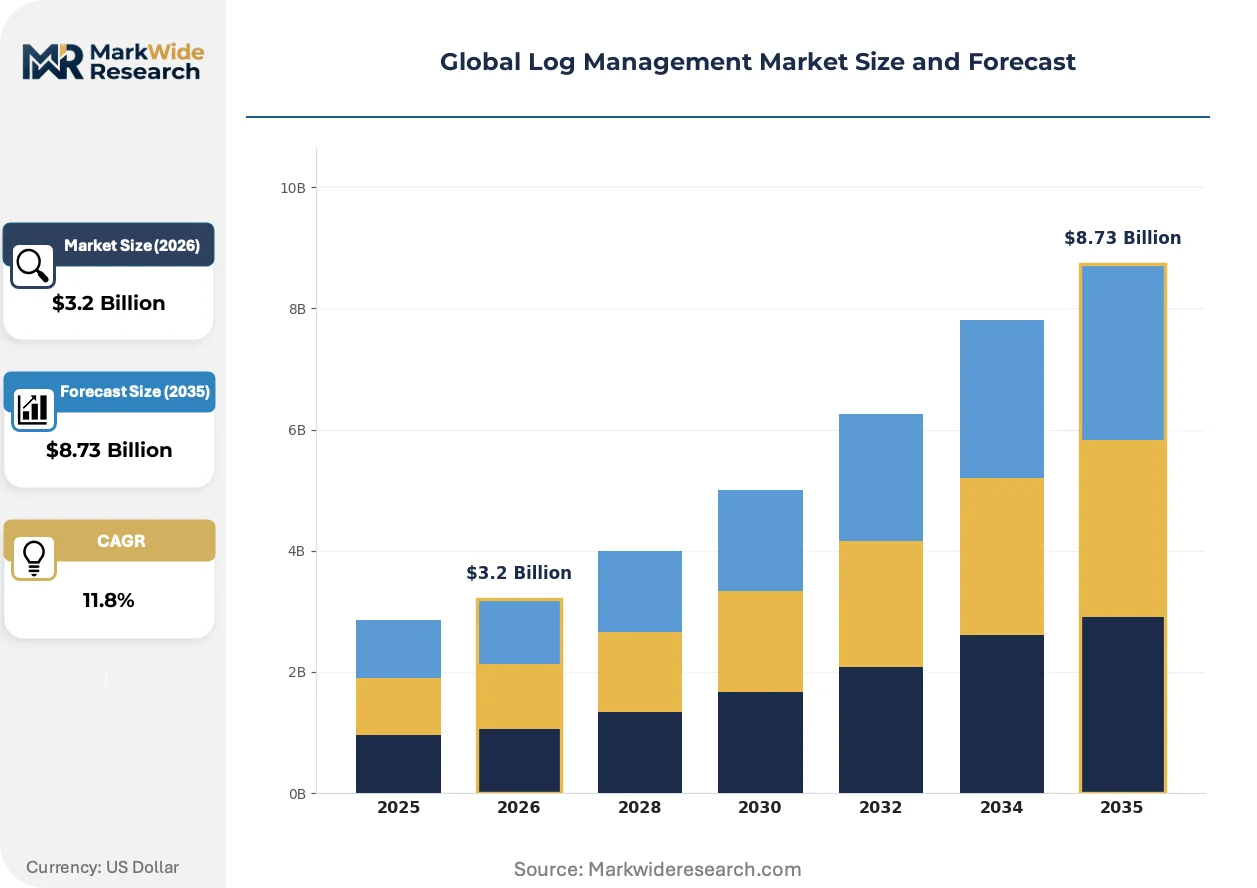
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $8.73 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Solution Offering: Log Collection, Data Analysis, Security Monitoring, Compliance Reporting, Alerting Use Case: Threat Detection, Operational Troubleshooting, Performance Monitoring, Compliance Auditing End User: Telecom Operators, Financial Institutions, IT Service Providers, Government Agencies |
| Companies Covered | Datadog Inc., LogRhythm Inc., Splunk Inc., Elasticsearch B.V., Micro Focus International, IBM Corporation, Rapid7 Inc., Sumo Logic Inc., SolarWinds Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Log Management Market Shifts & Advancements
OpenTelemetry instrumentation standards are dissolving vendor lock-in across application performance monitoring, enabling buyers to separate data collection from analytics platforms for the first time.
Vectorized query execution engines are rewriting performance economics for high-cardinality log analysis. Security operations centers in Fortune 500 enterprises are adopting these engines to achieve sub-second search across petabyte-scale archives without proprietary hardware. The compression is eliminating premium pricing tiers previously justified by query speed differentiation.
The EU AI Act's explainability requirements are forcing algorithmic decision systems to emit structured decision logs with full feature attribution. Financial institutions deploying credit scoring and fraud detection models in France and Germany are retrofitting pipelines to capture model inputs, weights, and outputs in immutable formats. Healthcare AI deployments across the Netherlands face comparable technical controls for diagnostic imaging workflows.
Consumption-based pricing for log analytics is displacing seat-based and node-based licensing across enterprise procurement. Chief information security officers in United States healthcare and United Kingdom financial services are negotiating annual commit contracts with burst allowances rather than fixed infrastructure sizing. The shift transfers operational risk from buyers to vendors while compressing switching costs.
Global Log Management Market Segmentation
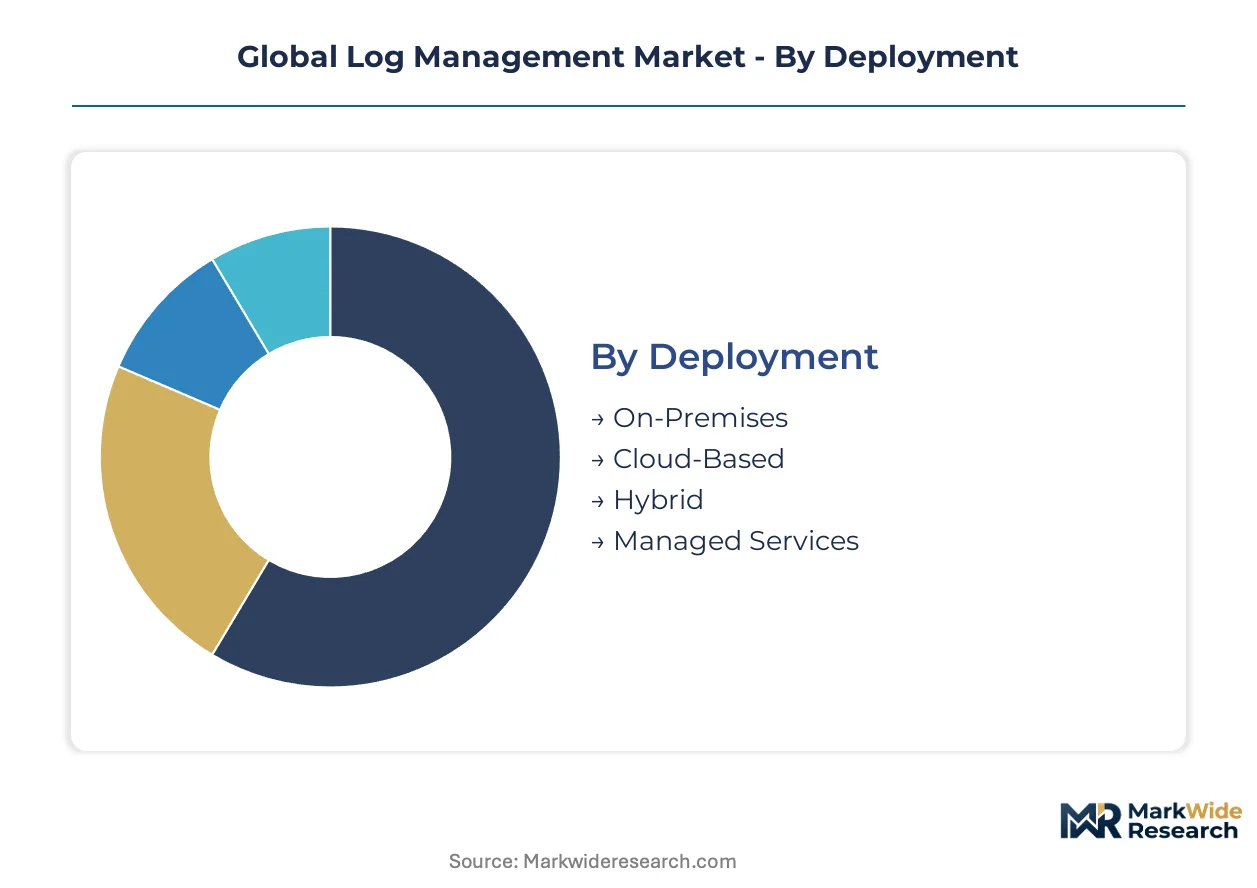
Log management procurement splits across infrastructure choices, functional modules, operational purposes, and buyer sophistication. Each segmentation axis reveals distinct upgrade cycles and vendor switching patterns that reshape competitive positioning.
Deployment:
Organizations retiring on-premises data lakes are triggering wholesale architecture replacements rather than incremental expansion.
- Cloud-Based:Cloud-native ingestion pipelines eliminate capital expenditure on storage hardware while transferring operational risk to vendors through consumption pricing. Demand concentrates among United States healthcare systems and United Kingdom financial services firms seeking HIPAA and GDPR-compliant elastic retention without infrastructure ownership burdens.
- Hybrid:Split architectures retain sensitive parsing workloads on-premises while archiving to cloud object stores for long-term immutability. German manufacturing conglomerates and French energy utilities favor this model to satisfy EU data sovereignty requirements without sacrificing cost efficiency at scale.
- On-Premises:Dedicated hardware deployments persist in classified government environments and air-gapped industrial control systems where network egress is prohibited.
- Managed Services:Outsourced security operations center integration appeals to mid-market enterprises lacking internal observability engineering expertise.
Cloud-based deployments sit at the top of the volume ranking, with hybrid architectures climbing the fastest as sovereignty constraints harden across European jurisdictions.
Solution Offering:
Functional module selection tracks buyer maturity, with advanced adopters unbundling collection from analytics while laggards demand integrated suites.
- Security Monitoring:Real-time correlation engines processing security information and event management workloads command premium pricing due to sub-second latency requirements and pre-built threat detection content. United States financial institutions under SEC cybersecurity disclosure mandates represent the most demanding buyer segment.
- Compliance Reporting:Auditor-validated template libraries for PCI-DSS, HIPAA, and EU AI Act documentation accelerate procurement cycles among risk-averse enterprises. German automotive suppliers and Dutch healthcare networks prioritize this capability to reduce external audit preparation costs.
- Log Collection:High-throughput ingestion agents with adaptive parsing rule generation address telemetry diversity in heterogeneous infrastructure estates.
- Data Analysis:Vectorized query execution and machine learning-powered anomaly detection differentiate platforms for forensic investigation workloads.
- Alerting:Multi-channel notification routing with escalation management integrates into existing incident response workflows.
Security monitoring commands the highest revenue per deployment, with compliance reporting gaining share fastest as regulatory enforcement intensifies across European and North American jurisdictions.
Use Case:
Primary application purpose determines retention policy design, query performance requirements, and integration depth with adjacent security tools.
- Threat Detection:Real-time streaming analytics with automated response orchestration requires petabyte-scale indexing and sub-second search latency. Japan's critical infrastructure operators under METI guidelines and United States Fortune 500 enterprises drive specification intensity in this segment.
- Compliance Auditing:Immutable write-once storage with cryptographic verification satisfies seven-year retention mandates in healthcare and payment processing. India's expanding digital public infrastructure creates sovereign demand for audit trail capabilities in identity and payment registries.
- Operational Troubleshooting:Root-cause analysis across distributed microservices emphasizes correlation between logs, metrics, and traces rather than pure search speed.
- Performance Monitoring:Application-centric telemetry aggregation supports service level objective tracking and capacity planning decisions.
Threat detection leads absolute spending, with compliance auditing expanding most quickly as algorithmic decision systems face EU AI Act explainability mandates.
End User:
Buyer organizational type shapes procurement authority, budget cycle timing, and vendor evaluation criteria more than technical requirements alone.
- Financial Institutions:Banks, insurers, and payment processors combine the strictest regulatory obligations with the highest telemetry volumes from algorithmic trading and real-time fraud detection. French and German institutions retrofitting credit scoring pipelines for EU AI Act compliance illustrate segment-specific demand intensity.
- Telecom Operators:Network equipment diversity and subscriber-scale data volumes create unique parsing complexity and multi-year retention requirements. Japanese and Indian operators upgrading operational technology monitoring capabilities represent concentrated opportunity.
- Government Agencies:Classified and unclassified deployments split between sovereign cloud mandates and commercial platform adoption depending on sensitivity classification.
- IT Service Providers:Multi-tenant platform requirements and white-label analytics capabilities differentiate procurement specifications from enterprise direct buyers.
Financial institutions anchor segment revenue, with telecom operators showing the steepest expansion trajectory as 5G and industrial IoT deployments multiply telemetry sources.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Observability engineering talent clusters in Germany, the United States, and India are anchoring regional deployment patterns for log management infrastructure. These concentrations align with data sovereignty mandates and cloud-native migration timelines across financial services and industrial sectors.
United States
SEC cybersecurity disclosure rules and HIPAA audit mandates are extending retention requirements for healthcare systems and publicly traded firms. The Boston-Washington corridor hosts dense concentrations of security operations centers modernizing threat detection pipelines. Financial institutions in New York and Chicago are retrofitting algorithmic trading logs for immutable audit trails.
Germany
Industrial IT security spending on operational technology monitoring is accelerating in manufacturing strongholds. EU AI Act explainability requirements and GDPR enforcement are tightening data retention standards for automotive suppliers and energy utilities. The Ruhr industrial cluster and Bavarian manufacturing belt are deploying hybrid architectures to satisfy sovereignty constraints without sacrificing cloud economics.
India
The country's expanding digital public infrastructure is creating sovereign demand for log analytics across identity, payment, and health registries. RBI and SEBI guidelines for financial data localization are mandating domestic retention for banking and securities firms. Bangalore and Hyderabad technology corridors are building captive observability engineering capacity to support government cloud deployments.
Japan
METI-directed operational technology security guidelines are mandating specialized log management for power generation and transportation systems. Critical infrastructure operators in Tokyo and Osaka are upgrading monitoring capabilities to meet sub-second incident response requirements. Telecom operators expanding 5G industrial IoT footprints are generating machine telemetry that demands unified security and operational pipelines.
France
CNIL enforcement of GDPR algorithmic accountability is forcing financial institutions to emit structured decision logs for credit scoring and fraud detection models. Healthcare AI deployments for diagnostic imaging face comparable technical controls. The Paris-Saclay research cluster and Lyon banking hub are concentrating compliance engineering expertise for EU AI Act implementation.
Global Log Management Market Competitive Landscape
Capital-heavy platform vendors compete with asset-light integration specialists across the log management value chain. The vendor base splits between consolidated full-stack providers and fragmented point-solution developers serving specialized compliance niches. Three archetypes dominate: proprietary analytics engines with extensive partner ecosystems, open-source indexing platforms with commercial support arms, and cloud-native observability suites with consumption-based pricing. Strategic moves concentrate on ingestion volume pricing restructuring and federated query architecture development.
Within the proprietary analytics tier, Splunk Inc. and Datadog Inc. exemplify divergent approaches to enterprise capture. Splunk anchors high-throughput security information and event management deployments with established query language ecosystems. Datadog occupies a position emphasizing cloud-native instrumentation and elastic retention economics. Elasticsearch B.V. represents the open-source archetype, anchoring flexible indexing deployments across hybrid infrastructure estates. These three patterns illustrate how vendor positioning stratifies across buyer sophistication and deployment maturity.
| Leading Market Players |
|---|
| Datadog Inc. |
| LogRhythm Inc. |
| Splunk Inc. |
| Elasticsearch B.V. |
| Micro Focus International |
| IBM Corporation |
| Rapid7 Inc. |
| Sumo Logic Inc. |
| SolarWinds Corporation |
| Others |
Supply & Pricing Matrix
United States healthcare systems and United Kingdom financial services firms seeking HIPAA and GDPR-compliant elastic retention anchor demand for consumption-based contracts with burst allowances rather than fixed infrastructure sizing. This buyer concentration transfers operational risk to vendors while compressing switching costs and restructuring procurement patterns across enterprise security teams.
Pricing Analysis
Cloud-native observability architectures are compressing procurement cycles as enterprises retire on-premises data lake investments. Pricing stratifies across premium, standard, and economy tiers based on query performance guarantees and auditor-validated template libraries. Cost compression in the standard tier is intensifying because vectorized query execution engines are eliminating premium pricing tiers previously justified by speed differentiation. Mid-market enterprises lacking internal observability engineering expertise exhibit highest price sensitivity, while Fortune 500 security operations centers under SEC cybersecurity disclosure mandates show lowest sensitivity due to sub-second latency requirements.
Supply Chain Analysis
Hyperscaler cloud infrastructure supply rests on concentrated data center buildouts in the United States, Germany, and India. Compute instances, object storage, and edge caching nodes constitute the primary input dependencies. Single-source vulnerability in proprietary query language ecosystems threatens buyer switching flexibility. Distribution runs through direct vendor sales teams and systems integrators serving hybrid deployment architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in log management hinges on consumption pricing restructuring and federated query architecture development that reduces storage cost volatility for high-volume retention scenarios.
For Market Incumbents: Lock in enterprise relationships by embedding compliance reporting modules with auditor-validated template libraries for PCI-DSS, HIPAA, and EU AI Act documentation. Deepen upstream control over vectorized query execution engine development to defend against open-source indexing platform encroachment. Prioritize capacity addition in Germany and France to satisfy hardening EU data sovereignty requirements without sacrificing cloud economics. For New Entrants and Emerging Players: Begin with India's sovereign log analytics demand across identity, payment, and health registries where RBI and SEBI guidelines mandate domestic retention. Target Japanese critical infrastructure operators upgrading operational technology monitoring capabilities under METI-directed standards. Pursue channel partnerships with managed security service providers lacking internal observability engineering expertise. For Investors and Strategic Acquirers: Cloud-native observability suites with consumption-based pricing are the most active acquirer in this space, seeking ingestion pipeline specialists and adaptive parsing rule generation technologies. Five-to-ten year viability favors vendors with established query language ecosystems and extensive partner networks. Watch for quantum-resistant encryption standard announcements as pipeline rewrite inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Query Architecture Development | Edge-to-cloud log streaming rewrites cost structures for distributed retail and telecommunications footprints. |
| Platform Integration | OpenTelemetry instrumentation standards dissolve vendor lock-in across application performance monitoring deployments. |
| Acquisition of Specialist Firm | Parsing rule automation targets proprietary log format complexity in legacy network equipment estates. |
| Geographic Expansion | German manufacturing conglomerates favor hybrid architectures to satisfy EU data sovereignty requirements. |
| Strategic Partnership | Systems integrators embed compliance reporting modules to reduce external audit preparation costs. |
Research Methodology
Bottom-up observability deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with chief information security officers, observability engineers, platform procurement officers, and managed security service providers combine with secondary validation from SEC filings, hyperscaler capex disclosures, and regulatory enforcement databases. Triangulation across these sources anchors segmentation-level estimates.
Input-output matrices map ingestion volume growth to cloud infrastructure capacity expansion across deployment models, organization size tiers, vertical industries, integration complexity levels, and regional adoption patterns. CAGRs derive from regression analysis against historical telemetry volume trajectories and regulatory mandate implementation timelines. Quantum-resistant encryption migration schedules and EU AI Act explainability requirement rollouts constitute key forecast inputs.
Several conditions sit outside the modeled scope, including black-box algorithmic decision systems without structured logging capabilities and air-gapped industrial control systems prohibiting network egress. Forecasts reflect documented assumptions about retention policy enforcement consistency. Supply chain disruptions in hyperscaler data center construction and parser standardization gaps in legacy equipment warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Data Loss Prevention Market
Security Software
Security Software for Consumers Market
Security Software
Parental Monitoring Software Market
Security Software
Europe Smart Doorbell Market
Security Software
SSL Inspection Solution Market
Security Software
AI in Security Market
Security Software
Privileged Identity Management Market
Security Software
Device-Embedded Biometric Authentication Market
Security Software
Encryption Software Market
Security Software
Internet Filter Software Market
Security Software
Network Camera Market
Security Software
Employee Surveillance and Monitoring Software Market
Security Software
Encryption As A Service Market
Security Software
Digital Risk Protection Platform Market
Security Software
Video Intercom Devices Market
Security Software
Cloud Intrusion Protection Software Market