
 Data Quality Management Market | 2026-2036
Data Quality Management Market Size, Share, and Industry Trends Forecast 2026-2036
Data Quality Management Market Analysis
Cloud-native architectures are rebalancing total cost of ownership away from legacy on-premise data quality stacks. IBM leverages its hybrid cloud platform to anchor enterprise accounts seeking gradual migration paths. SAS Institute competes through deep statistical lineage capabilities that sustain pricing power in regulated industries. Palantir Technologies differentiates via ontology-driven data integration that positions its offerings for defense and intelligence adjacencies.
Data quality management encompasses the processes, tools, and governance frameworks that ensure accuracy, completeness, consistency, and timeliness of enterprise information assets, typically measured through error rates, duplicate detection thresholds, and freshness SLAs. Its primary purpose is to reduce decision risk and operational friction across downstream analytics and transactional systems. Cloud-based deployment leads in new bookings as organizations prioritize elastic scaling and reduced infrastructure overhead, while data monitoring represents the fastest-expanding solution category as real-time observability becomes standard. Compliance management applications command premium pricing due to audit trail requirements, though customer insights is narrowing the gap as personalization investments intensify.
The EU AI Act, GDPR, and SEC disclosure rules collectively mandate demonstrable data provenance, reshaping procurement criteria toward platforms with embedded governance. ISO 8000 data quality standards and industry-specific frameworks from HIPAA further segment vendor qualification thresholds. Stakeholders must weigh interoperability commitments against the risk of proprietary data models creating future switching costs.
Market Dynamics
AI governance mandates are compressing enterprise data quality timelines, forcing procurement teams to prioritize platforms with embedded lineage and audit capabilities over point solutions.
Growth Catalysts
- EU AI Act compliance deadlines:European enterprises must demonstrate data provenance for high-risk AI systems, accelerating replacement of manual governance workflows with automated quality infrastructure.
- Cloud migration acceleration:Financial services firms in the United States are retiring on-premise data warehouses, creating immediate demand for elastic data quality tooling that scales with analytics workloads.
- Real-time personalization investments:Retail and media companies require sub-second data freshness SLAs for recommendation engines, expanding the addressable market for streaming quality monitoring.
Market Restraints
- Specialized engineering talent scarcity:Data quality engineering roles command premium compensation in technology hubs, constraining vendor delivery capacity and customer implementation velocity.
- Legacy system entrenchment:Mainframe and on-premise data architectures in insurance and banking sectors resist API-based quality tooling integration, extending sales cycles.
- Proprietary data model lock-in:Vendor-specific ontologies and lineage formats create switching costs that deter multi-year platform commitments.
Strategic Opportunities
- Mid-market underpenetration:Organizations with 500-5,000 employees lack dedicated data governance functions, presenting an opening for automated, self-service quality platforms.
- Healthcare data interoperability:HIPAA-mandated patient data exchange requirements are creating demand for quality tooling that validates clinical data standards across disparate EHR systems.
- Edge computing convergence:IoT sensor networks and 5G infrastructure require distributed data quality validation at the network perimeter, beyond centralized cloud architectures.
Industry Challenges
- Cross-functional coordination gaps:Data quality initiatives require alignment between IT operations, legal compliance, and business analytics teams with misaligned incentive structures.
- Certification timeline compression:ISO 8000 and industry-specific data quality certifications demand extensive documentation that strains vendor professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Quality Management Market |
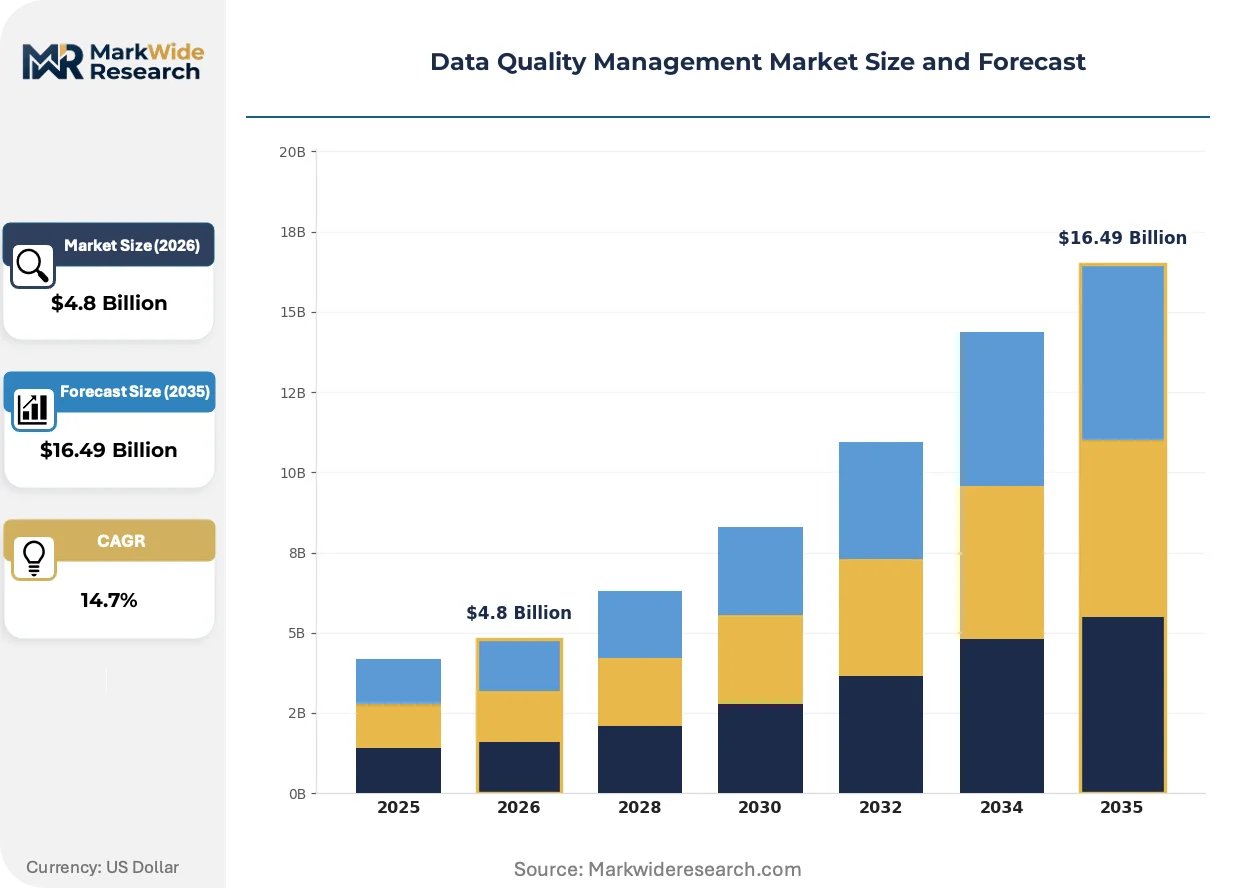
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.49 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Data Profiling, Data Cleansing, Data Enrichment, Data Monitoring Deployment: Cloud-Based, On-Premise, Hybrid, Managed Service End User: BFSI, Healthcare, Retail, Telecommunications Application: Compliance Management, Business Intelligence, Customer Insights, Operational Efficiency |
| Companies Covered | IBM, SAS Institute, Informatica, Alation, Collibra, Salesforce, Accenture, Palantir Technologies, Deloitte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Quality Management Market Emerging Trajectories
Automated data quality tooling is converging with observability platforms, collapsing the distinction between reactive monitoring and proactive governance. Vendors are racing to embed machine learning-driven anomaly detection into continuous integration pipelines.
Generative AI-assisted data profiling is rewriting how enterprises discover and classify sensitive information. Financial institutions and healthcare providers are deploying large language models to automate schema documentation and PII detection, compressing discovery timelines from weeks to hours. This capability is rewriting procurement criteria, as buyers now expect natural language interfaces for quality rule configuration.
The EU AI Act's risk classification framework is mandating technical documentation standards that cascade into data quality requirements. High-risk AI deployments must maintain complete data lineage records with version control, forcing vendors to retrofit audit trail capabilities into existing platforms. Healthcare and financial services verticals are responding by consolidating vendor relationships around platforms with pre-built compliance modules.
Enterprise buying committees are consolidating data quality procurement under centralized data platform teams, displacing fragmented departmental purchasing. Traditional IT procurement channels are losing influence as chief data officers assume direct vendor negotiation authority. This shift is most visible in the United States, where technology-forward enterprises have eliminated separate data quality RFP processes in favor of integrated data platform evaluations.
Data Quality Management Market Segmentation
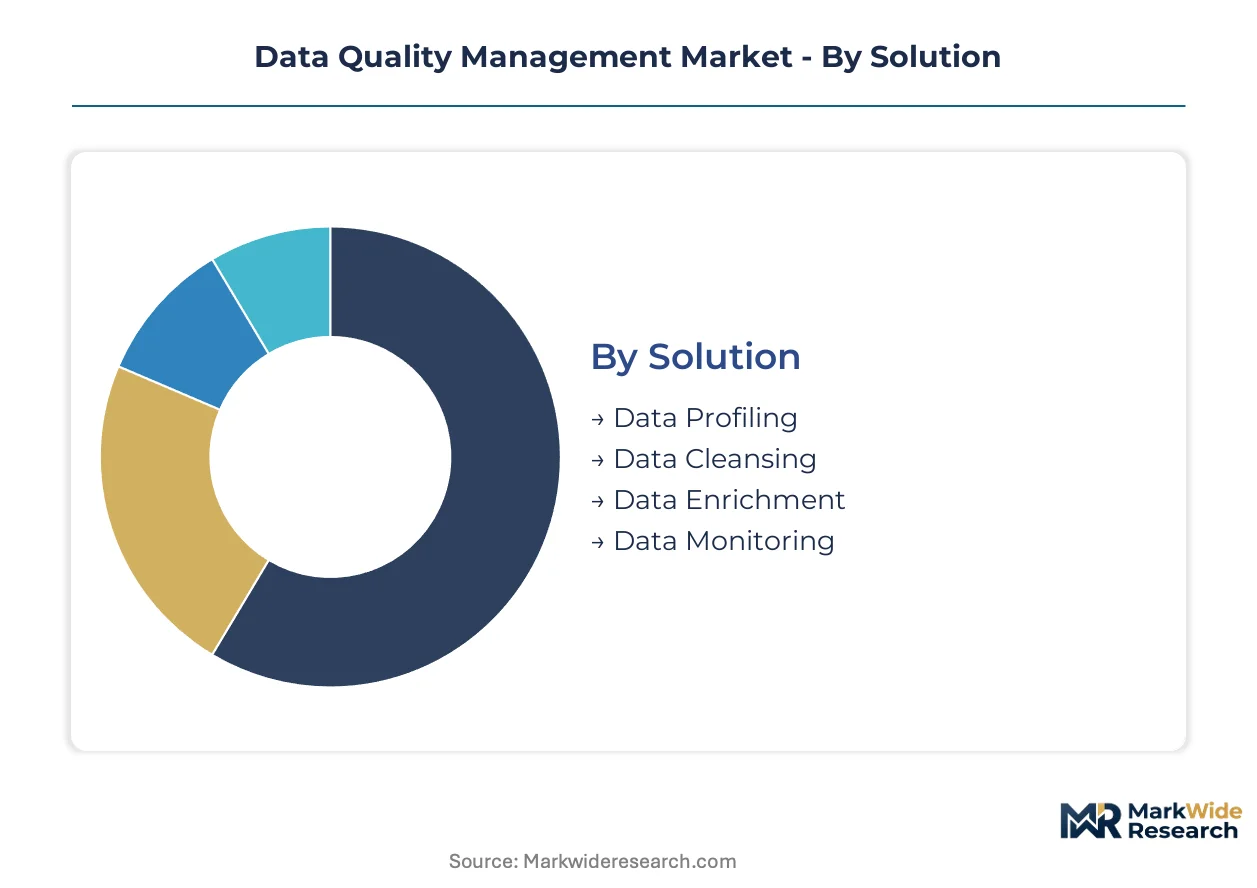
Data quality management procurement diverges sharply by technical architecture and organizational maturity. Solution buyers prioritize real-time capabilities over batch processing, while deployment choices reflect regulatory jurisdiction and legacy infrastructure burden.
Solution:
Technical sophistication determines pricing tiers and integration complexity across the solution stack.
- Data Monitoring:Continuous observability platforms ingest streaming data pipelines to detect schema drift and freshness violations in real time. Financial services firms in the United States deploy these tools to satisfy SEC disclosure rules for algorithmic trading systems.
- Data Cleansing:Automated deduplication and standardization engines correct record inconsistencies through probabilistic matching algorithms. Healthcare providers leverage these capabilities to reconcile patient identities across fragmented EHR systems under HIPAA interoperability mandates.
- Data Profiling:Statistical analysis tools catalog column distributions, null rates, and cardinality to establish baseline quality metrics.
- Data Enrichment:Third-party data append services augment internal records with external demographic, firmographic, or geospatial attributes.
Mature deployment sits with Data Cleansing. Newer deployment is concentrated in Data Monitoring.
Deployment:
Cost structure and control requirements shape infrastructure decisions across customer segments.
- Cloud-Based:Elastic compute resources scale quality workloads with analytics demand, eliminating capital expenditure for hardware procurement. Retail and media companies favor this model for personalization engines requiring sub-second data freshness SLAs.
- Hybrid:Split architectures retain sensitive data on-premise while pushing non-critical processing to cloud environments. BFSI institutions in regulated jurisdictions adopt this pattern to satisfy data residency requirements without sacrificing computational flexibility.
- On-Premise:Dedicated hardware installations persist in defense and intelligence sectors with air-gapped security requirements.
- Managed Service:Outsourced operations transfer staffing burden to vendor professional services organizations.
Established accounts favor On-Premise. Cloud-Based configurations are expanding most quickly among new adopters.
End User:
Industry-specific compliance regimes dictate feature prioritization and procurement authority.
- BFSI:Banking, insurance, and capital markets operations require audit-trail completeness for model risk management and stress testing documentation. EU AI Act deadlines are accelerating replacement of manual governance workflows with automated lineage systems in European institutions.
- Healthcare:Patient data exchange mandates under HIPAA and emerging FDA guidance on AI-enabled medical devices drive validation tooling for clinical data standards.
- Retail:Omnichannel personalization investments demand unified customer profiles with real-time inventory synchronization.
- Telecommunications:Network operations centers monitor subscriber data quality for churn prediction and 5G service provisioning.
BFSI captures the deepest penetration. Healthcare is climbing the fastest as interoperability mandates tighten.
Application:
Use case specificity determines integration patterns and success metrics for quality initiatives.
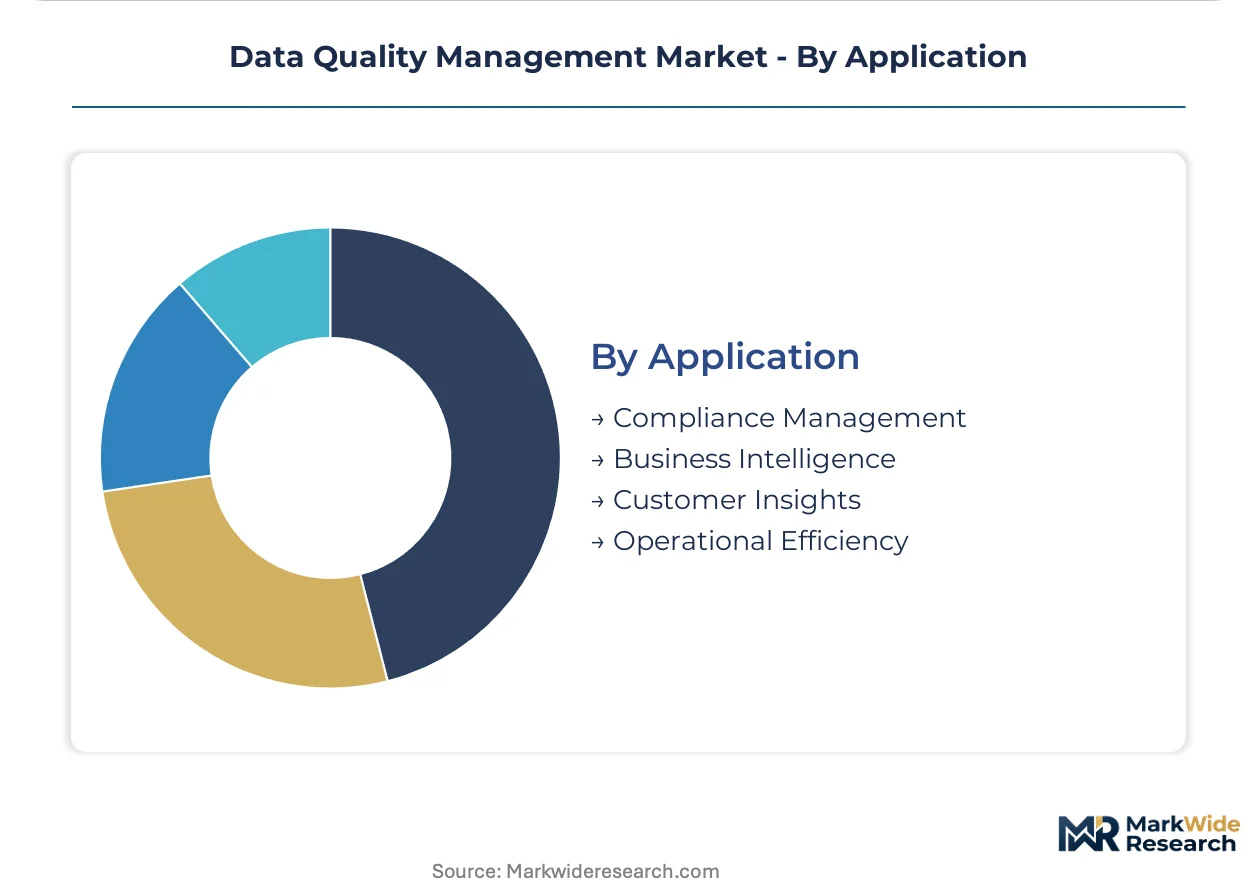
- Compliance Management:Audit trail generation and provenance documentation satisfy regulatory examination requirements. GDPR and EU AI Act technical documentation standards command premium pricing due to mandatory version control and lineage completeness.
- Customer Insights:Profile unification and preference resolution enable personalization at scale. Retailers narrowing the pricing gap against compliance applications as first-party data strategies intensify.
- Business Intelligence:Dashboard accuracy and metric consistency support executive decision-making.
- Operational Efficiency:Supply chain and process automation quality reduces manual exception handling.
Compliance Management dominates current spending. Customer Insights is gaining share fastest as marketing technology budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Dubai Internet City are concentrating data quality infrastructure investments as cloud providers establish regional compliance hubs.
United States
Financial services firms in New York and Chicago are retiring legacy data warehouses, creating immediate demand for elastic quality tooling. SEC disclosure rules for algorithmic trading systems mandate real-time data lineage documentation. The San Francisco Bay Area cluster hosts the highest density of AI governance platform development.
Germany
Automotive manufacturers in Stuttgart and Munich require sub-second data freshness for autonomous vehicle validation pipelines. EU AI Act compliance deadlines are accelerating replacement of manual governance workflows with automated quality infrastructure. Frankfurt's financial district anchors continental demand for audit-trail completeness systems.
United Kingdom
London-based investment banks are consolidating vendor relationships around platforms with pre-built compliance modules. GDPR technical documentation standards command premium pricing for provenance documentation capabilities. The Cambridge-Oxford corridor concentrates emerging AI safety research influencing procurement criteria.
India
Bengaluru and Hyderabad technology campuses are expanding delivery capacity for data quality engineering roles commanding premium compensation. RBI guidelines on model risk management are tightening data provenance requirements for lending algorithms. The Mumbai-Pune corridor hosts the fastest-growing managed services operations for global financial institutions.
Singapore
Wealth management firms in the Marina Bay financial district require unified customer profiles with real-time regulatory reporting synchronization. MAS technology risk management guidelines mandate demonstrable data lineage for AI-driven advisory systems. The one-north research cluster concentrates ASEAN headquarters for international data platform vendors.
Data Quality Management Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise software vendors holding concentrated positions in regulated industries while services firms capture implementation and managed service revenue. The vendor ecosystem organizes into three tiers: cloud-native platform providers with embedded governance, established analytics vendors retrofitting lineage capabilities, and professional services firms delivering compliance documentation. Consolidation pressure is intensifying through strategic partnerships between infrastructure providers and vertical specialists, alongside technology licensing arrangements that accelerate feature parity.
Within the cloud-native platform tier, IBM and Salesforce occupy positions anchoring enterprise accounts seeking gradual migration paths from legacy architectures. SAS Institute exemplifies the established analytics vendor archetype competing through deep statistical lineage capabilities. Palantir Technologies sits within the defense and intelligence adjacency segment where ontology-driven integration commands premium positioning.
| Leading Market Players |
|---|
| IBM |
| SAS Institute |
| Informatica |
| Alation |
| Collibra |
| Salesforce |
| Accenture |
| Palantir Technologies |
| Deloitte |
| Others |
Supply Flow & Price Mechanics
Financial services procurement committees in New York and London concentrate purchasing power for enterprise data quality platforms, anchoring value-based pricing models that tie subscription tiers to audit-trail completeness and lineage granularity. Cloud-native vendors extract premiums from these buyers by embedding EU AI Act compliance modules that compress certification timelines.
Pricing Analysis
Short lead-time deployments command 20-40% subscription premiums as EU AI Act deadlines compress procurement cycles. Three-tier pricing structure across premium, standard, and economy levels segments by lineage depth, with premium tiers offering real-time anomaly detection and automated schema documentation. Pricing pressure stems from open-source alternatives encroaching on data profiling and cleansing modules. Mid-market organizations with 500-5,000 employees exhibit highest price sensitivity due to constrained data governance budgets, while BFSI institutions in regulated jurisdictions show lowest sensitivity given mandatory compliance spend.
Supply Chain Analysis
Freight costs for on-premise hardware deployments remain negligible compared to cloud infrastructure provisioning, where data residency requirements fragment compute allocation across regional zones. Engineering talent supply concentrates in the United States, India, and Germany, with Bengaluru and Hyderabad campuses expanding delivery capacity for implementation services. Raw material dependencies include cloud compute credits, proprietary ontology libraries, and ISO 8000 certification documentation. Single-source vulnerability sits with specialized data quality engineers commanding premium compensation. Distribution runs through direct enterprise sales teams and hyperscaler marketplaces, with managed services increasingly delivered via vendor professional services organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data quality engineering talent scarcity props pricing power for vendors with certified implementation capacity, creating supply-constrained conditions that favor established platform providers with professional services depth.
For Market Incumbents: To counter open-source encroachment on core profiling and cleansing modules, IBM and SAS Institute should deepen backward integration into automated lineage generation technology while expanding certified engineering capacity in Bengaluru and Hyderabad to reduce delivery bottlenecks for EU AI Act compliance deadlines. For New Entrants and Emerging Players: Launch via self-service cloud platforms targeting mid-market organizations with 500-5,000 employees, where dedicated data governance functions remain underpenetrated. Healthcare data interoperability presents the most penetrable vertical, with HIPAA-mandated patient data exchange requirements creating demand for quality tooling that validates clinical data standards across fragmented EHR systems. For Investors and Strategic Acquirers: The window for entry favors cloud-native specialists with embedded AI governance capabilities. Long-term viability hinges on consolidation around platforms with pre-built compliance modules for EU AI Act and SEC disclosure rules. The signal to watch is enterprise buying committee consolidation under centralized data platform teams, which accelerates vendor rationalization and creates acquisition opportunities for orphaned point solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding lineage capabilities into existing analytics stacks displaces fragmented point solutions. |
| Strategic Partnership | Hyperscaler alliances accelerate distribution through AWS Marketplace and Azure marketplace channels. |
| Acquisition of Specialist Firm | Vertical-specific ontology providers in healthcare and defense segments command premium positioning. |
| Geographic Expansion | Frankfurt and Singapore hubs address EU AI Act and MAS technology risk management guidelines. |
| Product Launch | Generative AI-assisted data profiling compresses discovery timelines from weeks to hours for financial institutions. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents formed the secondary backbone, supplemented by customs data on software licensing flows. Primary interviews with chief data officers, IT procurement officers, platform engineers, and compliance leads at BFSI and healthcare institutions provided demand-side validation. Bottom-up and top-down triangulation reconciled vendor-reported bookings with enterprise technology spend surveys.
Bottom-up modeling aggregated individual solution bookings across data monitoring, cleansing, profiling, and enrichment categories, while top-down analysis calibrated against aggregate enterprise software spend. Segmentation dimensions included deployment model, organization size, vertical industry, and integration complexity. CAGRs derived from fitted growth curves incorporating cloud migration velocity and regulatory deadline impacts. Forecast inputs included EU AI Act implementation timelines and SEC disclosure rule adoption rates.
Regulatory deadline delays, cloud cost volatility, and talent availability constraints are the dominant revision risks. Forecasts reflect assumptions about compliance mandate enforcement intensity and enterprise cloud migration pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Global Telecommunication Equipment Cabinet and Racks Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Italy Data Center Construction Market
Data Center Infrastructure
Israel Data Center Rack Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Belgium Data Center Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
France Data Center Server Market