
 United Arab Emirates Data Center Physical Security Market | 2026-2036
United Arab Emirates Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Data Center Physical Security Market Insights
Hyperscale cloud operators is rotating procurement toward integrated biometric-video analytics platforms, displacing standalone CCTV contracts. Schneider Electric SE leverages its EcoStruxure architecture to anchor power-integrated security designs across Emirates-based facilities. Honeywell International Inc sustains competitive positioning through its Pro-Watch access control ecosystem, which dominates Dubai Internet City installations. Axis Communications AB specializes in edge-computing camera networks that reduce bandwidth loads for desert-region data centers.
United Arab Emirates Data Center Physical Security encompasses layered protection systems—ranging from biometric access control to perimeter intrusion detection—engineered to safeguard server infrastructure against unauthorized entry, environmental threats, and deliberate sabotage. These systems typically integrate IP-rated enclosures, redundant power supplies, and thermal-resistant sensors capable of operating at ambient temperatures exceeding 50°C in Gulf conditions. Surveillance Systems and Access Control represent the dominant solution segments, with margin pools concentrating in AI-enabled video analytics that reduce false alarm rates for 24/7 unmanned facilities. Biometric Systems within the technology dimension are capturing accelerated deployment schedules as palm-vein and facial recognition replace legacy card-based credentials in Tier III and Tier IV certified data halls.
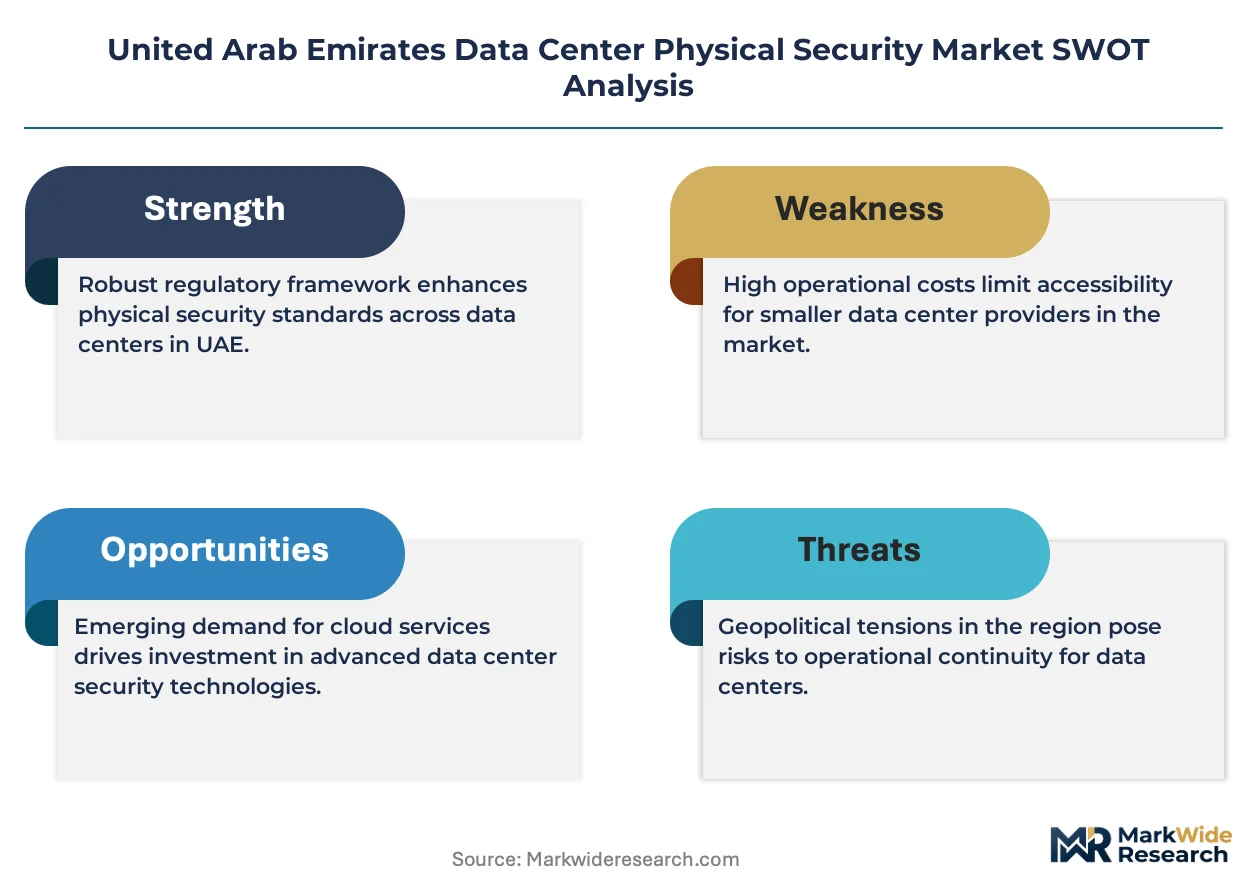
MOHAP and the UAE Cybersecurity Council enforce facility protection standards that mandate dual-authentication entry protocols and perimeter hardening for operators serving government and financial clients. BIS-equivalent conformity assessments and NESA compliance frameworks shape product certification requirements, effectively filtering non-compliant vendors from critical infrastructure tenders. Stakeholders must monitor evolving federal data sovereignty regulations that will likely expand physical audit obligations beyond current baseline specifications.
Market Dynamics
Hyperscale cloud operators in the Emirates are consolidating procurement around biometric-video fusion platforms, compressing vendor margins on standalone perimeter hardware while elevating systems integrators with AI-analytics capabilities.
Growth Catalysts
- MOHAP Facility Mandates:Healthcare data center operators must deploy dual-authentication entry protocols and hardened perimeter systems, creating mandatory upgrade cycles for existing Tier II facilities serving government clients.
- Al Dhafra Cluster Expansion:ADQ's gigawatt-scale data center concentration in Abu Dhabi's western region is generating concentrated demand for thermal-resistant sensor networks capable of operating above 50°C ambient conditions.
- Facial Recognition Maturation:Palm-vein and facial recognition systems are replacing card-based credentials in Tier III and Tier IV certified halls, accelerating replacement schedules for legacy access control infrastructure.
Market Restraints
- Specialized Engineering Talent Scarcity:Gulf-based facilities face acute shortages of certified security systems engineers capable of integrating multi-layered biometric platforms with building management systems.
- Import Dependency for Edge-Computing Hardware:Desert-rated thermal enclosures and redundant power supplies for security systems concentrate manufacturing in East Asian supply chains, exposing procurement to shipping volatility.
- NESA Compliance Friction:BIS-equivalent conformity assessments for critical infrastructure security products create 6-12 month certification timelines that filter non-compliant vendors from federal tenders.
Strategic Opportunities
- Ras Al Khaimah Emergence:The emirate's developing data center zone offers first-mover positioning for integrated security providers before hyperscale commitments lock in incumbent vendor relationships.
- AI-Video Analytics Convergence:Machine learning-enabled false alarm reduction is creating service revenue streams for systems integrators managing unmanned 24/7 facilities across Dubai's Jebel Ali corridor.
- Federal Data Sovereignty Expansion:Anticipated regulations extending physical audit obligations beyond current baselines will compel financial services operators to upgrade surveillance and access logging infrastructure.
Industry Challenges
- Tier IV Certification Timelines:Uptime Institute certification processes for concurrent maintainability create 18-24 month project delays that compress security subsystem installation windows.
- Legacy Building Management Integration:Retrofitting biometric access control into existing Dubai Internet City facilities requires custom protocol bridging that extends commissioning schedules and elevates integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Data Center Physical Security Market |
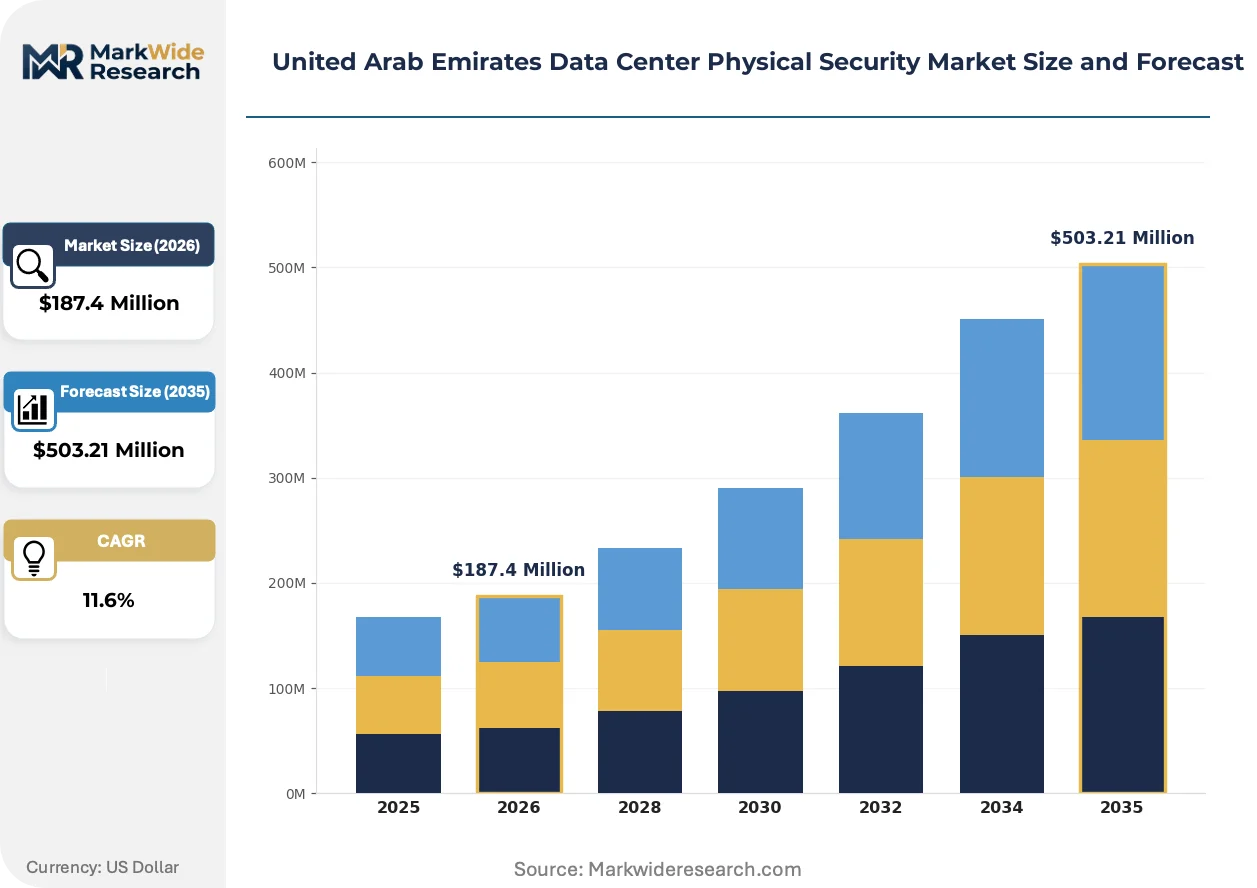
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Access Control, Surveillance Systems, Perimeter Security, Fire Protection End User: Telecommunications, BFSI, Government, IT Services Technology: Biometric Systems, CCTV, Motion Sensors, Alarm Systems Installation Type: New Installations, Upgrades, Maintenance Services, Retrofit Solutions |
| Companies Covered | Schneider Electric SE, Axis Communications AB, Honeywell International Inc, BIOS Middle East Group, Securitas Technology, Siemens AG, Bosch Sicherheitssysteme GmbH, Pacific Control Systems, Johnson Controls International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Data Center Physical Security Market Trends and Innovations
Biometric-video fusion architectures are compressing the addressable market for standalone perimeter hardware while elevating margin capture for AI-enabled analytics platforms. Three forces are actively restructuring competitive positioning.
Edge-computing camera networks with onboard video analytics is displacing centralized server-based processing architectures in bandwidth-constrained desert facilities. Cloud service providers operating Emirates-based hyperscale campuses are deploying these thermal-resistant units at perimeter fence lines and mantrap entry points. This displacement reduces fiber backhaul requirements while enabling real-time threat classification without latency penalties.
UAE Cybersecurity Council directives mandating perimeter hardening for critical infrastructure operators are compressing procurement cycles for government-facing data centers. Facility operators serving financial and healthcare verticals must now document dual-authentication protocols and intrusion detection coverage to maintain licensing eligibility. Tier III and Tier IV certified halls in Dubai's Jebel Ali Free Zone are accelerating guard force and biometric integration to satisfy audit requirements.
Cloud operators are consolidating vendor relationships around integrated security platforms rather than discrete subsystem procurement. Standalone CCTV and access control contracts are fragmenting as hyperscalers demand unified command-and-control dashboards spanning video, biometrics, and environmental monitoring. This consolidation is most visible among operators in Abu Dhabi's Al Dhafra Region data cluster, where single-source accountability is reducing subsystem integration risk.
United Arab Emirates Data Center Physical Security Market Segmentation
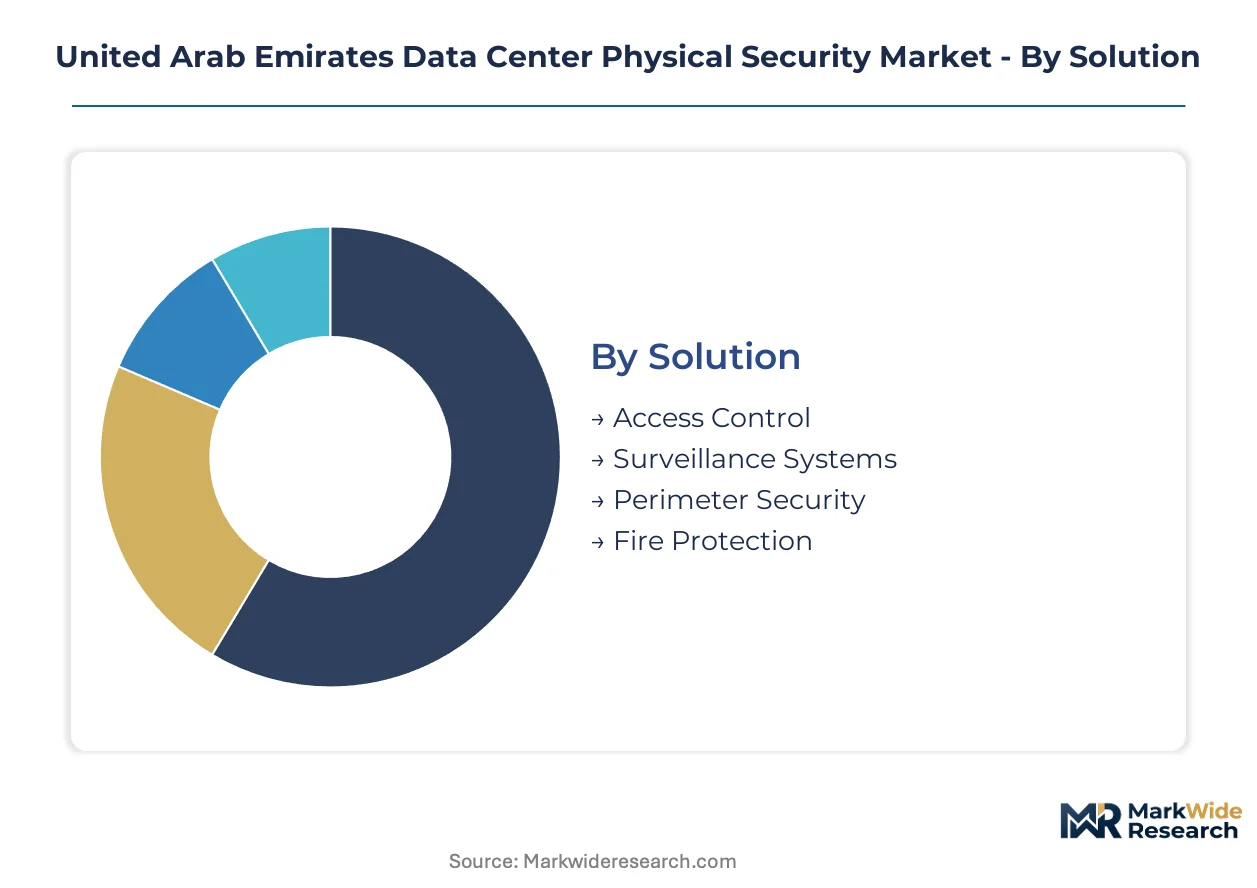
Physical security procurement in UAE data centers fragments across solution architecture, end-user compliance requirements, and technology maturity curves. Understanding segment boundaries reveals where hyperscale operators concentrate spending versus where legacy facility upgrades generate replacement demand.
Solution:
Access Control and Surveillance Systems concentrate procurement within domestic hyperscale campuses, while Perimeter Security and Fire Protection draw heavier export-linked engineering services from European and East Asian suppliers.
- Access Control:Biometric readers, card credential systems, and mantrap entry configurations form the core identity verification layer. Demand clusters in Dubai's Jebel Ali Free Zone and Abu Dhabi's Al Dhafra Region, driven by MOHAP dual-authentication mandates for healthcare data infrastructure.
- Surveillance Systems:IP camera networks, video management software, and edge-computing analytics platforms enable 24/7 unmanned monitoring. Procurement accelerates across Tier III and Tier IV facilities seeking AI-enabled false alarm reduction for desert-region bandwidth constraints.
- Perimeter Security:Fence intrusion detection, ground radar, and thermal imaging systems protect facility boundaries.
- Fire Protection:Clean agent suppression, early smoke detection, and compartmentalization systems safeguard server halls.
Surveillance Systems commands the established base. The steepest expansion runs through Access Control.
End User:
Telecommunications and BFSI operators drive premium-tier procurement with Tier IV certification requirements, while Government and IT Services segments balance compliance-driven upgrades against budget-constrained maintenance cycles.
- Telecommunications:Mobile network operators and fixed-line carriers operate mission-critical switching facilities requiring concurrent maintainability. Etisalat and du infrastructure investments in Dubai Internet City and Masdar City anchor demand for integrated biometric-video platforms.
- BFSI:Banks, insurance carriers, and payment processors face NESA compliance obligations and anticipated federal data sovereignty expansions. Physical audit mandates from the UAE Cybersecurity Council compel surveillance logging upgrades across Abu Dhabi Global Market and Dubai International Financial Centre facilities.
- Government:Federal and emirate-level data centers serving smart city initiatives and citizen services.
- IT Services:Colocation providers, managed hosting operators, and cloud resellers serving mid-market enterprise clients.
Telecommunications retains the largest installed base. BFSI climbs the fastest as regulatory timelines compress.
Technology:
Biometric Systems and CCTV represent capital-intensive procurement with domestic integration requirements, while Motion Sensors and Alarm Systems concentrate manufacturing supply in East Asian export hubs.
- Biometric Systems:Palm-vein recognition, facial authentication, and multi-factor credential readers replace legacy card-based access. Tier III and Tier IV halls across Dubai's Jebel Ali corridor accelerate deployment schedules as facial recognition maturation reduces false acceptance rates.
- CCTV:Fixed and PTZ camera networks with edge-computing analytics capability reduce centralized processing loads. Thermal-resistant IP-rated enclosures operate above 50°C ambient temperatures in Al Dhafra Region and Ras Al Khaimah developing zones.
- Motion Sensors:PIR, microwave, and dual-technology intrusion detection devices for perimeter and internal zone coverage.
- Alarm Systems:Centralized monitoring stations, duress signaling, and environmental alert integration.
CCTV holds the dominant share. Biometric Systems gains share fastest as card credential replacement accelerates.
Installation Type:
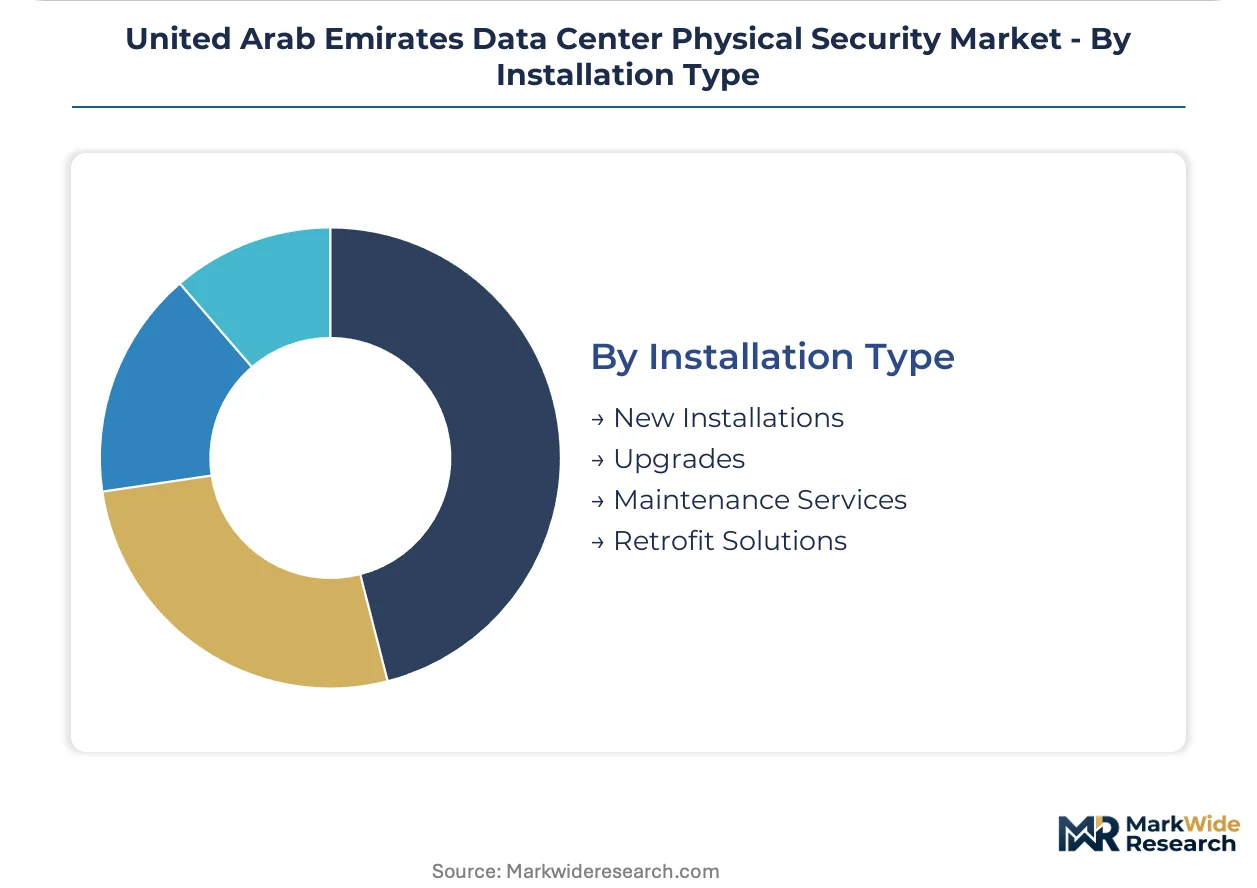
New Installations concentrate in greenfield hyperscale campuses with single-source accountability requirements, while Upgrades and Retrofit Solutions fragment across legacy facilities in Dubai Internet City and older free zone developments.
- New Installations:Integrated security subsystem deployment during data center construction phases. ADQ's Al Dhafra cluster and emerging Ras Al Khaimah zones generate concentrated demand for unified command-and-control platforms specified from ground-up facility design.
- Upgrades:Component-level replacement of legacy access control, surveillance, and perimeter systems. Existing Tier II facilities serving government clients execute mandatory MOHAP-driven upgrade cycles for dual-authentication compliance.
- Maintenance Services:Ongoing technical support, firmware updates, and preventive servicing contracts.
- Retrofit Solutions:Custom protocol bridging and building management system integration for older facilities.
New Installations anchors procurement volume. Retrofit Solutions expands most quickly as legacy building integration challenges multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering exports supply thermal-resistant sensor enclosures to UAE hyperscale campuses, while Japanese precision manufacturers deliver edge-computing camera networks for bandwidth-constrained desert facilities.
Dubai
Jebel Ali Free Zone concentration drives integrated biometric-video platform procurement for Tier III and Tier IV certified halls. MOHAP facility security mandates compel dual-authentication entry protocol upgrades across healthcare data infrastructure. Dubai Internet City legacy facilities generate retrofit demand for custom protocol bridging solutions.
Abu Dhabi
ADQ's Al Dhafra Region gigawatt-scale cluster creates concentrated demand for thermal-resistant perimeter systems operating above 50°C ambient conditions. UAE Cybersecurity Council directives mandate hardened perimeter documentation for government-facing operators. Masdar City smart infrastructure investments anchor integrated security subsystem deployment.
Sharjah
Developing industrial zones attract mid-market colocation providers seeking cost-optimized access control configurations. Federal data sovereignty anticipation drives preliminary surveillance logging infrastructure preparation. Sharjah Research Technology and Innovation Park emerging facilities test biometric-video fusion architectures.
Northern Emirates
Ras Al Khaimah's nascent data center zone offers first-mover positioning before hyperscale vendor relationships crystallize. Lower land and power costs attract cloud resellers requiring scaled-down perimeter protection relative to Dubai benchmarks. Fujairah's cable landing station proximity creates specialized submarine cable facility security requirements.
United Arab Emirates Data Center Physical Security Market Competitive Landscape
Listed leaders compete with private specialists across integrated platform versus standalone subsystem procurement. The vendor base stratifies between multinational conglomerates with building management system portfolios and regional systems integrators with localized compliance expertise. Three archetypes dominate: power-integrated security designers, biometric access control ecosystem providers, and edge-computing camera network specialists. Competitive moves concentrate on AI-analytics capability acquisition and thermal-resistant hardware certification acceleration.
Within the multinational conglomerate tier, Schneider Electric SE and Honeywell International Inc exemplify power-integrated and access control ecosystem approaches respectively. Axis Communications AB occupies a position among edge-computing camera network specialists. These three anchors represent divergent strategic vectors: EcoStruxure-architecture power integration, Pro-Watch ecosystem dominance in Dubai Internet City, and desert-optimized thermal-resistant sensor manufacturing.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Axis Communications AB |
| Honeywell International Inc |
| BIOS Middle East Group |
| Securitas Technology |
| Siemens AG |
| Bosch Sicherheitssysteme GmbH |
| Pacific Control Systems |
| Johnson Controls International |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with East Asian thermal enclosure manufacturers lock in supply access for UAE hyperscale operators while providing 12-18 month price visibility against shipping volatility. These arrangements concentrate procurement leverage among operators with multi-gigawatt deployment pipelines, compressing margins for smaller colocation providers forced into spot-market component sourcing.
Pricing Analysis
Next-generation biometric-video fusion platforms command 40-60% premiums over legacy standalone CCTV and card-credential systems. Three-tier pricing structure across premium, standard, and economy levels separates Tier IV-certified integrated platforms from Tier III mid-tier configurations and Tier II retrofit solutions. Pricing pressure stems from hyperscale consolidation around single-source accountability, squeezing subsystem specialists unable to deliver unified command-and-control dashboards. Government and BFSI buyers exhibit lowest price sensitivity due to NESA compliance mandates, while mid-market colocation operators in Sharjah and Northern Emirates drive hardest bargain negotiations.
Supply Chain Analysis
Strait of Hormuz transit underwrites critical logistics exposure for German-engineered thermal sensor enclosures and Japanese-manufactured edge-computing camera networks. Manufacturing concentrates in China, South Korea, and Taiwan for IP-rated desert enclosures, redundant power supplies, and biometric reader components. Raw material dependencies span rare-earth magnets for camera positioning systems, gallium arsenide for thermal imaging sensors, and specialized aluminum alloys for corrosion-resistant mounting hardware. Single-source vulnerability runs through Taiwanese semiconductor fabrication for video analytics processing chips. Distribution runs through Dubai-based systems integrators with NESA certification expertise, bypassing direct vendor relationships for federal tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric-video fusion maturation is disrupting procurement patterns faster than vendor consolidation can absorb, creating asymmetric opportunity windows before hyperscale relationships crystallize. MOHAP facility mandates and UAE Cybersecurity Council directives are compressing compliance timelines for operators serving government and healthcare verticals.
For Market Incumbents: Consolidate around AI-analytics capability acquisition to defend against standalone hardware margin compression. Deepen backward integration into thermal-resistant sensor manufacturing to reduce East Asian import dependency exposure. Lock in multi-year service contracts with ADQ's Al Dhafra cluster operators before certification timelines filter non-compliant competitors from federal tenders. For New Entrants and Emerging Players: Anchor in Ras Al Khaimah's nascent data center zone where first-mover positioning remains available before incumbent vendor relationships solidify. Target mid-market colocation providers seeking cost-optimized biometric configurations below Dubai hyperscale pricing benchmarks. Pursue white-label integration partnerships with established UAE systems integrators lacking proprietary AI-video analytics development. For Investors and Strategic Acquirers: Capital is best deployed toward regional systems integrators with localized NESA compliance expertise and established hyperscale relationships. Long-term viability hinges on differentiation through federal certification acceleration rather than hardware manufacturing scale. Monitor facial recognition false acceptance rate improvements as the signal indicating biometric replacement cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Video Analytics Acquisition | Machine learning-enabled false alarm reduction creates recurring service revenue streams for unmanned facility management. |
| Thermal-Resistant Hardware Certification | MOHAP and UAE Cybersecurity Council mandates filter non-compliant vendors from critical infrastructure tenders. |
| Ras Al Khaimah Geographic Expansion | Lower land and power costs attract cloud resellers before hyperscale vendor relationships crystallize. |
| Backward Integration into Sensor Manufacturing | In-house production of desert-rated enclosures reduces Strait of Hormuz logistics exposure and lead time volatility. |
| Unified Command-and-Control Platform Development | Single-source accountability requirements from ADQ's Al Dhafra cluster operators displace standalone subsystem procurement. |
Research Methodology
A standing panel of data center security directors, federal compliance officers, systems integration engineers, and hyperscale procurement leads provided ongoing calibration across the primary research phase. These practitioner inputs combined with secondary validation from UAE Cybersecurity Council directives, MOHAP facility protection standards, NESA compliance frameworks, and hyperscaler capex disclosures. Bottom-up segment sizing triangulated against top-down market aggregation from installation type, technology maturity, and end-user compliance requirements.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning solution architecture, end-user vertical, technology generation, and installation type alongside geographic deployment patterns within Dubai, Abu Dhabi, Sharjah, and Northern Emirates. CAGRs derived from fitted growth curves incorporating regulatory mandate timelines, hyperscale cluster expansion schedules, and biometric technology replacement cycles. Forecast inputs included thermal-resistant hardware certification timelines and AI-video analytics adoption rates.
Material uncertainties — federal data sovereignty regulation timing, Strait of Hormuz shipping disruptions, and NESA certification backlog fluctuations — sit outside the modeled envelope. Forecasts reflect assumptions regarding hyperscale consolidation trajectories and biometric technology maturation curves. Practitioners should keep alternative scenarios live as UAE Cybersecurity Council directive enforcement intensity and Al Dhafra cluster buildout pacing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
Nigeria Data Center Server Market
Data Center Infrastructure
Data Center Power Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
Denmark Data Center Physical Security Market
Data Center Infrastructure
Italy Data Center Construction Market
Data Center Infrastructure
Scientific Data Management System Market
Data Center Infrastructure
Europe Data Center Physical Security Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Data Center Equipment Market
Data Center Infrastructure
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market
Data Center Infrastructure
France Data Center Rack Market