
 Desmutting Agent Market | 2026-2036
Desmutting Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Desmutting Agent Market Outlook
Specialty chemical distribution is narrowing as regional distributors consolidate around technical service capabilities. Nippon Hyomen Kagaku leverages its surface-treatment heritage to dominate Japanese OEM supply chains. Coventya anchors European demand through REACH-compliant formulations and electroplating technical support. OKUNO Chemical Industries Co Ltd competes on manufacturing scale across liquid and powder desmutting portfolios.
Desmutting agents chemically remove oxide films, smut, and residual contaminants from metal substrates prior to plating or coating, typically operating in acidic or alkaline baths at controlled temperatures between 40°C and 80°C depending on substrate sensitivity. Their primary industrial purpose is ensuring adhesion integrity and surface uniformity in precision finishing operations. Organic agents lead in semiconductor processing applications where substrate damage tolerance is minimal, while inorganic agents sustain stronger positions in heavy-duty metal finishing for automotive and aerospace components. Liquid formulations capture the bulk of volume due to dosing precision and automation compatibility, though powder forms retain cost advantages in bulk industrial equipment treatment.
REACH in Europe and EPA effluent guidelines in the United States constrain permissible chemistries, pushing manufacturers toward biodegradable organic formulations and closed-loop bath management systems. China's MEE enforces stricter wastewater discharge standards for surface treatment facilities in the Yangtze River Delta, redirecting procurement toward compliant suppliers. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
Semiconductor fabrication expansion in East Asian manufacturing corridors is compressing qualification timelines for desmutting chemistries while tightening purity specifications. This demand surge forces formulators to reconcile high-volume supply with substrate-specific customization.
Growth Catalysts
- Chip fabrication scaling:Advanced packaging nodes below 7nm require residue-free surface preparation, pulling organic desmutting agents into South Korean and Taiwanese foundry supply chains.
- REACH-compliant formulation mandates:ECHA restrictions on chromium-based chemistries redirect European metal finishers toward biodegradable organic alternatives with documented environmental profiles.
- Closed-loop bath management:Automated dosing and real-time contamination monitoring extend bath life, reducing per-unit chemical consumption in high-volume automotive plating lines.
Market Restraints
- Fluorinated surfactant supply concentration:Japanese and German specialty chemical producers control critical PFAS-alternative feedstocks, exposing formulators to input cost volatility and allocation risk.
- Technical performance ceiling:Organic agents struggle to match inorganic formulations on heavy oxide removal rates for cast aluminum aerospace components, limiting substitution potential.
- MEE effluent enforcement lag:Inconsistent wastewater discharge monitoring across Chinese provincial jurisdictions creates uneven competitive pressure on compliance investment.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme subsidies for semiconductor and display fabrication attract greenfield investments requiring qualified surface treatment chemical suppliers.
- Copper-to-silver metallization pivot:Solar cell manufacturers adopting silver-alternative plating architectures need modified desmutting protocols, opening formulation development partnerships.
- Direct distributor technical service:Regional chemical distributors building in-house surface engineering expertise capture specification influence previously held by multinational formulators.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in acidic-alkaline bath chemistry and substrate compatibility grows harder to recruit as experienced practitioners retire.
- Dual qualification burden:Semiconductor fabs require 12-18 month validation cycles for new chemistries, locking suppliers into extended R&D commitments before revenue realization.
- Legacy equipment retrofit complexity:Powder-to-liquid formulation transitions demand tank and dosing system modifications that disrupt continuous production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desmutting Agent Market |
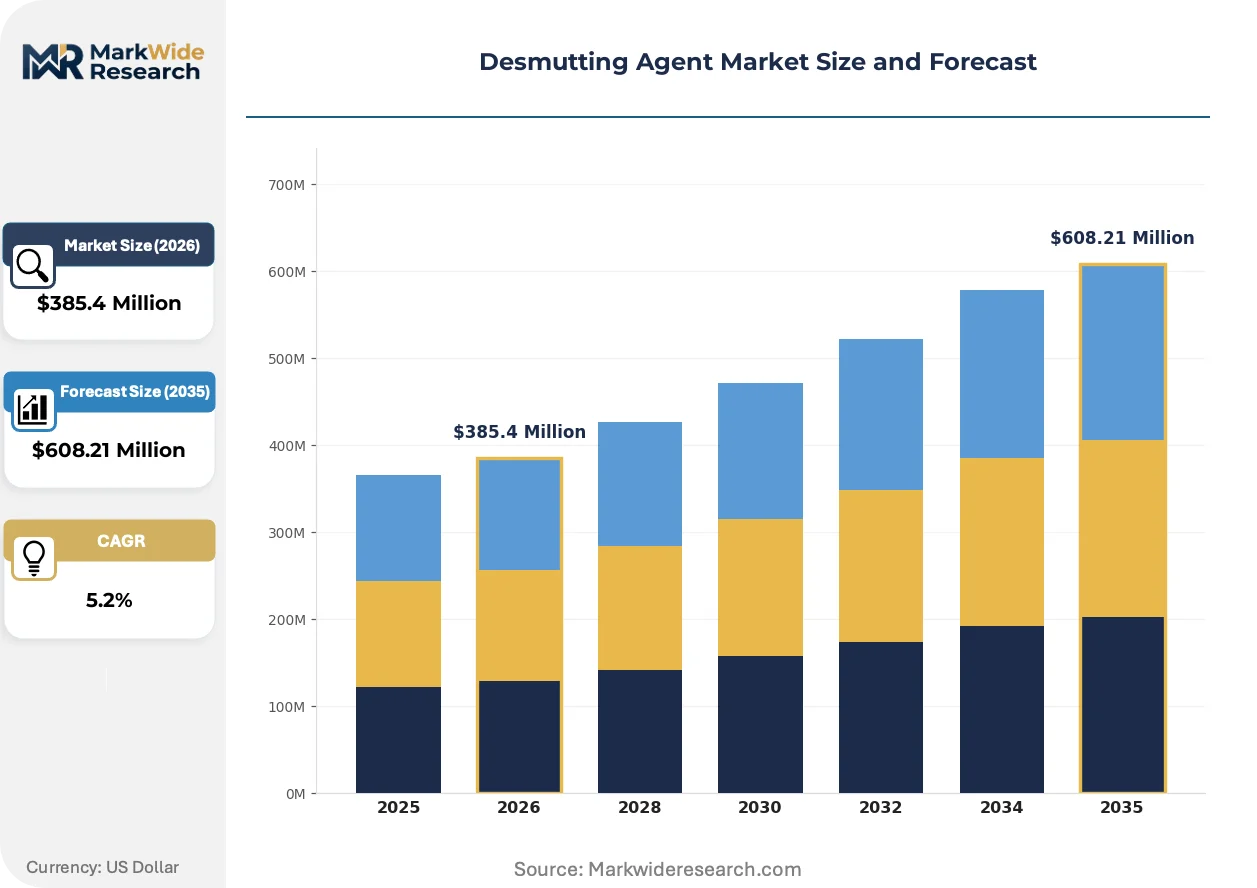
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Agents, Inorganic Agents, Synthetic Compounds, Natural Extracts Application: Electroplating, Metal Finishing, Semiconductor Processing, Surface Treatment End User: Aerospace, Automotive Manufacturers, Electronics, Industrial Equipment Form: Powder, Liquid, Gel, Granular |
| Companies Covered | Nippon Hyomen Kagaku, Coventya, METACHEM, Almax, CIS Pharma, OKUNO Chemical Industries Co Ltd, Shenzhen ODM Technology, SLS Chem and Tech, Tiny Chempro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desmutting Agent Market Strategic Shifts
Real-time process control and predictive bath chemistry management are displacing static formulation approaches. These capabilities compress variation in surface preparation outcomes while reducing waste generation.
Inline spectroscopic monitoring is digitizing bath composition tracking across semiconductor fabrication facilities. TSMC and Samsung Foundry operations deploy ultraviolet-visible absorbance sensors for instantaneous contaminant detection. This sensor integration enables automated replenishment triggers that stabilize process windows and reduce manual sampling labor.
REACH authorization requirements for boron compounds and certain acid salts force systematic substitution programs across European electroplating supply chains. Formulators invest in biodegradability testing infrastructure to secure SVHC exemptions. Automotive OEMs in Germany and Czech manufacturing clusters now specify cradle-to-gate environmental footprints in chemical procurement tenders.
Specification authority migrates from central procurement to site-level process engineering teams at major semiconductor fabs. Engineers demand batch-level traceability data and technical response guarantees, displacing volume-based purchasing agreements. This decentralization concentrates supplier selection power with individual fabrication facility managers in Hsinchu and Pyeongtaek.
Desmutting Agent Market Segmentation
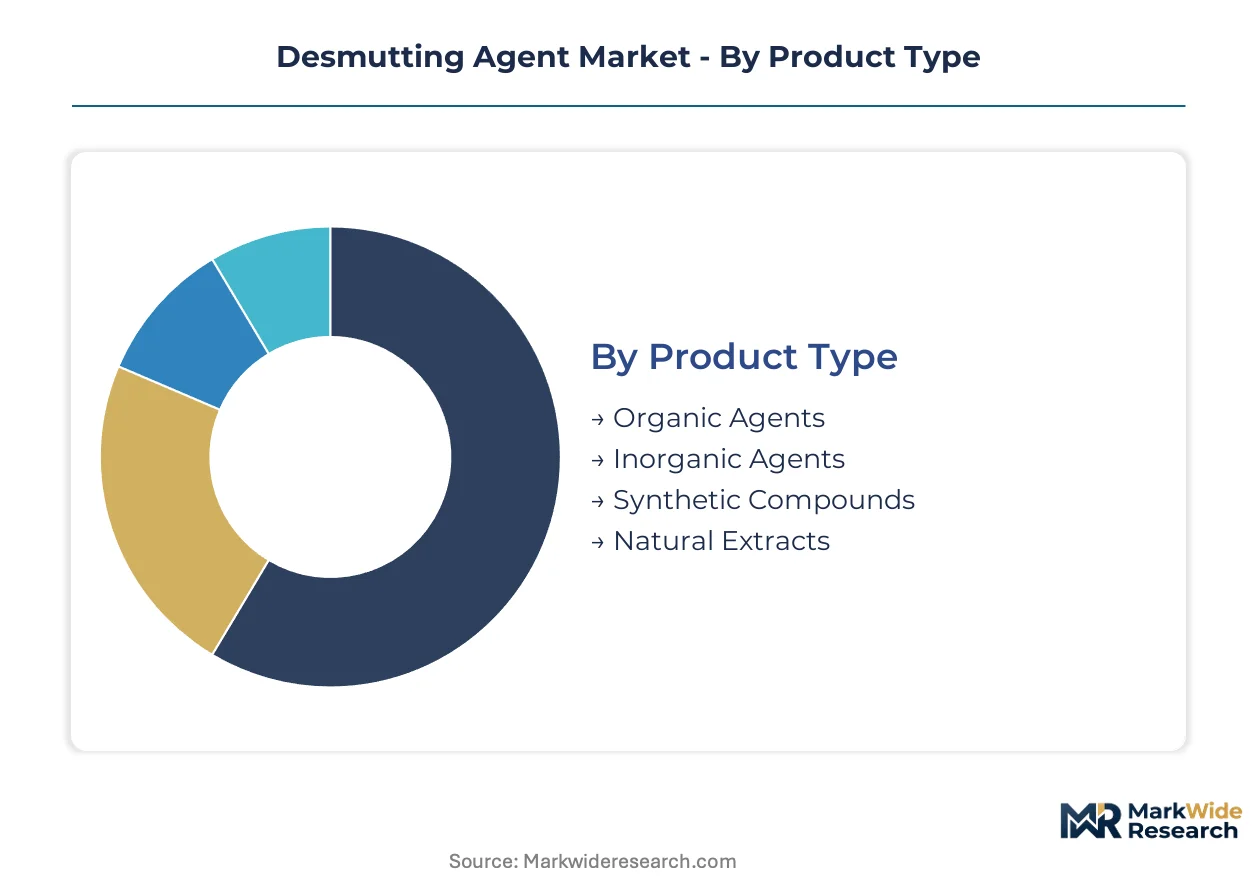
Desmutting agent procurement patterns diverge sharply across substrate sensitivity requirements and regulatory jurisdictions. Formulators must align product architectures with specific oxide removal intensity, effluent compliance burdens, and automation compatibility at the point of use.
Product Type:
Cost tier determines formulation chemistry selection, with premium organic agents commanding semiconductor fabs and economy inorganic variants sustaining heavy industrial metal finishing.
- Organic Agents:Biodegradable acid salt and surfactant complexes operate at reduced temperatures to protect delicate substrates. TSMC and Samsung Foundry specifications in Hsinchu and Pyeongtaek pull these formulations into advanced packaging nodes below 7nm where residue tolerance approaches zero.
- Inorganic Agents:Mineral acid and fluoride-based chemistries deliver aggressive oxide dissolution for cast aluminum and steel pretreatment. Aerospace component manufacturers in Toulouse and Hamburg specify these for heavy smut removal on investment-cast turbine housings where substrate damage risk is secondary to throughput.
- Synthetic Compounds:Engineered chelating agents balance performance with REACH-compliant degradation profiles.
- Natural Extracts:Bio-derived organic acids from citrus and tannin sources serve niche European electroplating shops seeking SVHC exemption documentation.
Organic agents command the established base in semiconductor corridors. The steepest expansion runs through synthetic compounds as formulators bridge performance and compliance demands.
Application:
Volume concentration tracks manufacturing process intensity, with semiconductor processing generating highest per-unit chemical consumption despite smaller batch sizes.
- Electroplating:Acidic desmutting baths precede nickel, chromium, and copper deposition across automotive and decorative finishing lines. German OEM plating operations in Wolfsburg and Stuttgart enforce closed-loop bath management to extend chemical life under REACH cost pressures.
- Metal Finishing:General-purpose surface preparation for coating adhesion spans industrial equipment, construction hardware, and consumer appliance manufacturing. Chinese Yangtze River Delta facilities face MEE effluent enforcement that redirects procurement toward compliant organic alternatives.
- Semiconductor Processing:Ultra-high-purity requirements drive specification authority to site-level process engineers.
- Surface Treatment:Pre-paint and pre-coating preparation for functional and decorative finishes.
Metal Finishing commands the established base by unit volume. The steepest expansion trajectory belongs to Semiconductor Processing as East Asian foundry capacity scales.
End User:
Customer type segmentation reveals divergent technical service expectations, with aerospace and semiconductor buyers demanding batch traceability that industrial equipment purchasers disregard.
- Electronics:Display panel and printed circuit board manufacturers in South Korea's Gumi and Icheon corridors require residue-free preparation for fine-pitch metallization. PLI scheme subsidies in India are pulling greenfield investments into Gujarat and Tamil Nadu that need qualified chemical suppliers.
- Automotive Manufacturers:High-volume plating lines for decorative trim and functional components specify liquid formulations compatible with automated dosing systems. Czech and Slovak assembly plants source through regional distributors with electroplating technical support capabilities.
- Aerospace:Nadcap-accredited finishers impose stringent qualification protocols.
- Industrial Equipment:Cost-sensitive bulk treatment operations favor powder formulations.
Automotive Manufacturers command the established base by chemical volume. The steepest expansion runs through Electronics as semiconductor and display fabrication migrates.
Form:
Supply concentration favors liquid production, with powder retaining relevance only where logistics costs outweigh automation benefits.
- Liquid:Precision dosing and real-time bath monitoring compatibility make this the default for automated semiconductor and automotive plating operations. Samsung Foundry and TSMC facilities deploy ultraviolet-visible absorbance sensors that require liquid formulation stability for instantaneous contaminant detection.
- Powder:Concentrated solid acids and salts reduce shipping weight for remote industrial equipment treatment facilities. Legacy tank infrastructure in Eastern European metal finishing shops resists conversion to liquid-compatible dosing systems.
- Gel:Viscous formulations for spot application and repair operations.
- Granular:Controlled-dissolution particles for batch tank preparation.
Liquid formulations command the established base across automated manufacturing. The steepest expansion runs through Gel formats as maintenance-repair-operations applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites European supply chain resilience for surface treatment chemicals, while the Kaohsiung-Taoyuan semiconductor corridor in Taiwan anchors East Asian demand concentration.
China
MEE effluent enforcement in the Yangtze River Delta redirects procurement toward REACH-compliant organic formulations. The country's dual carbon goals accelerate bath management system adoption. Suzhou and Wuxi plating clusters face wastewater discharge standard tightening that elevates supplier qualification barriers.
South Korea
Pyongtaek and Icheon foundry corridors pull ultra-high-purity organic desmutting agents into sub-7nm packaging nodes. The national industrial regulator enforces stricter chemical traceability for semiconductor supply chains. Samsung Foundry and SK Hynix operations in Gyeonggi Province compress supplier validation timelines to 12-14 months.
Germany
Automotive OEM plating lines in Wolfsburg and Stuttgart specify liquid formulations with automated dosing compatibility. ECHA REACH restrictions on chromium-based chemistries force systematic substitution programs. Bavarian and Baden-Württemberg electroplating clusters now require cradle-to-gate environmental footprint documentation in procurement tenders.
United States
EPA effluent guidelines constrain permissible chemistries across aerospace finishing operations in California and Texas. Nadcap-accredited suppliers in the Southwest face extended qualification protocols for defense subcontractor compliance. The Southeast automotive corridor favors regional distributors with technical service capabilities over multinational direct supply.
India
PLI scheme subsidies for semiconductor and display fabrication attract greenfield investments requiring qualified surface treatment suppliers. BIS standards for electroplating chemicals tighten import substitution pressures. Gujarat and Tamil Nadu electronics manufacturing clusters represent emerging specification battlegrounds as fabrication capacity scales.
Desmutting Agent Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with formulation IP. The supplier base organizes around three archetypes: Japanese surface-treatment heritage houses, European REACH-compliant formulators, and Chinese manufacturing-scale producers. Consolidation pressures concentrate around technical service capabilities rather than production volume. Dominant competitive moves include regional distributor partnerships and automated bath management system integration.
Within the heritage formulator tier, Nippon Hyomen Kagaku and OKUNO Chemical Industries Co Ltd occupy positions reflecting Japanese surface engineering lineage. Coventya represents the European REACH-compliance archetype with electroplating technical support infrastructure. Shenzhen ODM Technology anchors the manufacturing-scale tier serving automated dosing system compatibility requirements.
| Leading Market Players |
|---|
| Nippon Hyomen Kagaku |
| Coventya |
| METACHEM |
| Almax |
| CIS Pharma |
| OKUNO Chemical Industries Co Ltd |
| Shenzhen ODM Technology |
| SLS Chem and Tech |
| Tiny Chempro |
| Others |
Value Chain & Pricing Dynamics
Suzhou's electroplating cluster capacity expansion in the Yangtze River Delta compresses regional supply availability, concentrating pricing power with Japanese and German specialty chemical producers who control fluorinated surfactant feedstocks. MEE effluent enforcement elevates compliant organic formulation premiums while squeezing margin on legacy inorganic alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade organic agents from automotive liquid formulations and bulk industrial powder treatments. Certification tier—REACH-compliant versus standard-grade—drives price differentiation alongside volume scale for automated dosing system compatibility. Cost compression in economy powder segments intensifies as Chinese manufacturing-scale producers expand capacity. Semiconductor fabs exhibit lowest price sensitivity due to qualification lock-in, while industrial equipment purchasers prioritize per-kilogram cost above performance specifications.
Supply Chain Analysis
Fluorinated surfactant and chelating agent feedstocks draw from Japanese, German, and South Korean specialty chemical producers, creating upstream concentration around PFAS-alternative inputs. Critical dependencies include mineral acid suppliers, biodegradable surfactant feedstocks, and precision filtration equipment for semiconductor-grade formulation. Single-source vulnerability runs through Japanese producers of ultra-high-purity organic acids. Distribution runs through regional technical distributors with electroplating expertise rather than direct multinational supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor fabrication scaling below 7nm nodes disrupts qualification timelines and formulation specifications, creating acceleration windows for suppliers who compress validation cycles. REACH authorization requirements for boron compounds and acid salts force systematic substitution investments that favor early movers with biodegradability testing infrastructure.
For Market Incumbents: Insulate semiconductor supply positions through captive R&D partnerships with TSMC and Samsung Foundry process engineering teams. Backward integration into fluorinated surfactant alternatives reduces allocation risk from Japanese and German feedstock producers. Defensive patent filings around closed-loop bath management systems protect against regional distributor technical service encroachment.
For New Entrants and Emerging Players: Pursue PLI scheme-linked opportunities in Gujarat and Tamil Nadu electronics manufacturing corridors where qualified supplier scarcity creates specification windows. Target solar cell copper-to-silver metallization pivot applications requiring modified desmutting protocol development. Lead with direct technical service capabilities rather than volume-based pricing to displace established distributor relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulators with REACH-compliant biodegradability documentation and semiconductor fab qualification track records. Long-term viability hinges on automated bath management system integration capabilities rather than standalone chemical supply. Watch for ECHA SVHC list expansion announcements as inflection indicators for substitution-driven acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive fluorinated surfactant production insulates margin from Japanese and German allocation constraints. |
| Semiconductor Fab Qualification Partnership | Compressed 12-14 month validation timelines with Samsung Foundry and TSMC lock in specification authority. |
| REACH-Compliant Formulation Development | Biodegradability testing infrastructure secures SVHC exemptions ahead of ECHA authorization requirements. |
| Regional Distributor Technical Service Buildout | In-house surface engineering expertise displaces multinational formulator specification influence in Czech and Slovak automotive corridors. |
| Closed-Loop Bath Management System Integration | Automated dosing and real-time contamination monitoring extend chemical life under MEE effluent enforcement pressures. |
Study Parameters
Cross-validation between primary interviews with semiconductor process engineers, electroplating plant managers, and specialty chemical procurement leads anchors the qualitative findings. Secondary validation draws from ECHA REACH substance registrations, MEE wastewater discharge enforcement bulletins, and SEC filings from surface treatment chemical producers. Bottom-up triangulation across formulation chemist interviews and top-down calibration against customs trade data for desmutting agent categories ensures coverage integrity.
Calibration against semiconductor fab capacity buildout announcements and automotive OEM plating line automation disclosures refines volume assumptions across the projection horizon. Segmentation dimensions modeled include agent chemistry type, substrate sensitivity tier, formulation physical state, and regional regulatory cluster intensity. CAGRs derive from regression analysis of historical foundry chemical consumption patterns and forward-looking OEM specification migration timelines. Forecast inputs incorporate REACH authorization timeline probabilities and PLI scheme subsidy disbursement schedules.
Sensitivities concentrate around ECHA SVHC list expansion timing, MEE enforcement consistency across Chinese provincial jurisdictions, and fluorinated surfactant feedstock allocation disruptions. Forecasts embed assumptions regarding qualification timeline compression and substitution cost pass-through rates. Cross-checking against SEMI equipment spending forecasts and automotive production volume projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Cryogenic Column Market
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Defatting Systems Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Mass Transfer Trays Market