
 Turpentine Market | 2026-2036
Turpentine Market Size, Share, and Industry Trends Forecast 2026-2036
Turpentine Market Outlook
Buyer concentration among large coatings manufacturers is realigning procurement volumes toward integrated pine chemical suppliers. Kraton Corporation leverages its specialty chemicals portfolio to secure long-term solvent supply agreements with industrial buyers. Wuzhou Pine Chemicals Ltd. anchors its position through captive access to southern China's pine resin forests. Ingevity Corporation differentiates via bio-based product lines that target VOC-compliant formulations.
Turpentine is a volatile essential oil distilled from pine resin, composed primarily of alpha-pinene and beta-pinene terpenes, used as an industrial solvent and chemical intermediate. Steam distillation at controlled temperatures separates the oil from oleoresin, yielding fractions with specific boiling points tailored to adhesive and coating applications. Gum turpentine retains strong positions in traditional solvent markets where natural origin commands specification premiums, while synthetic turpentine competes on volume scale in cost-sensitive coating segments. The construction end-use industry channels the largest absolute demand as infrastructure spending drives paint and varnish consumption across residential and commercial projects.
EPA regulations under the Clean Air Act limit VOC emissions from architectural coatings, directly constraining formulation choices for turpentine-based products in the United States. REACH registration requirements in Europe mandate full toxicological profiling of pinene derivatives, raising compliance costs for exporters serving EU coating manufacturers. China's GB standards for industrial solvents, administered by SAMR, establish purity thresholds that filter small-scale producers from pharmaceutical-grade supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where specification premiums or compliance penalties will reshape competitive standing.
Market Dynamics
REACH compliance deadlines and EPA VOC thresholds are compressing formulation windows for coating manufacturers, forcing simultaneous reformulation of solvent bases and requalification of supply chains across multiple jurisdictions.
Growth Catalysts
- EU Green Deal solvent mandates:Bio-based feedstock quotas in architectural coatings are redirecting procurement toward gum turpentine derivatives that satisfy renewable content thresholds.
- Adhesive sector terpene resin expansion:Pressure-sensitive adhesive manufacturers are expanding alpha-pinene consumption for tackifier production in packaging and electronics bonding applications.
- Indonesian oleoresin harvest recovery:Improved tapping practices in Sumatran pine forests are restoring upstream raw material availability after weather-related supply disruptions.
Market Restraints
- Crude sulfate turpentine price volatility:Kraft pulping output fluctuations directly swing CST pricing, squeezing margin predictability for derivative processors.
- Guangxi province supply concentration:Over half of global gum turpentine originates from southern Chinese pine forests, creating single-point vulnerability to regional climate or policy shocks.
- Petroleum-derived hydrocarbon substitution:Mineral spirits and synthetic paraffinic solvents undercut natural terpenes on unit cost in commodity coating segments.
Strategic Opportunities
- Indian pharmaceutical-grade pinene:CDSCO registration pathways for chiral intermediates remain underexploited by incumbent suppliers focused on industrial solvent markets.
- Carbon border adjustment mechanism positioning:EU CBAM scope expansion creates first-mover advantage for producers with verified lifecycle emissions data on bio-based extraction.
- Direct-to-formulator digital channels:Specialty chemical marketplaces are bypassing traditional distributor tiers for mid-volume coating compounders seeking technical specification matching.
Industry Challenges
- Distillation technician scarcity:Fractionation expertise for terpene separation is retiring faster than vocational programs replace pipeline operators.
- Multi-jurisdiction REACH-SAMR parallel registration:Divergent toxicological data requirements between EU and Chinese regulators force redundant testing expenditures for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turpentine Market |
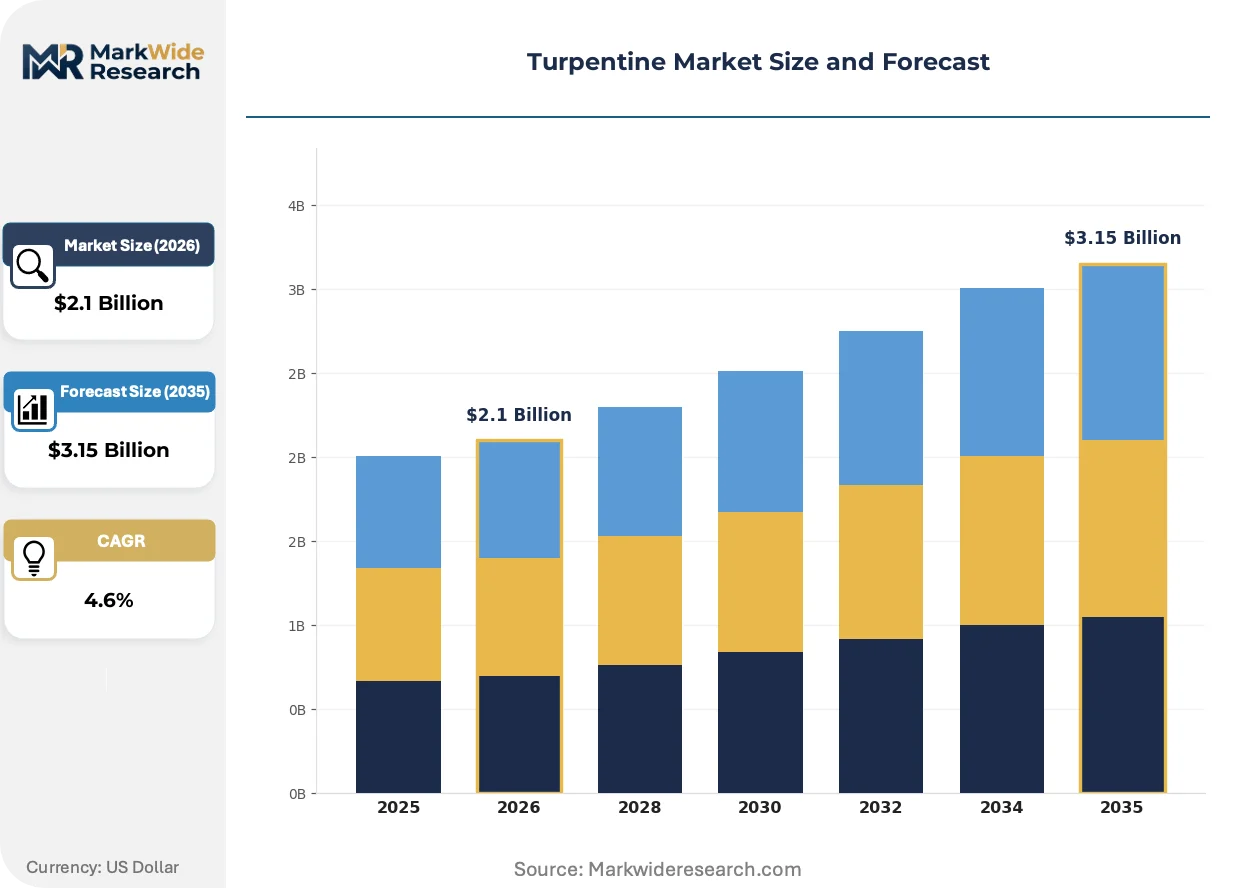
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectified Turpentine, Steam Distilled Turpentine, Gum Turpentine, Synthetic Turpentine Application: Paints, Varnishes, Adhesives, Coatings End Use Industry: Construction, Automotive, Woodworking, Pharmaceuticals Packaging Type: Drums, Cans, Bulk, Bottles |
| Companies Covered | Wuzhou Pine Chemicals Ltd., PT. Naval Overseas, Guilin Songquan Forest Chemical Co., Ltd., Pine Chemical Group, Forestar Chemical Co., Ltd., Deqing Yinlong Industrial Co., Ltd., DRT, Kraton Corporation, Ingevity Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turpentine Market Strategic Shifts
Fractionation technology advances and regulatory data requirements are rewriting competitive boundaries between natural and synthetic terpene suppliers. Three developments warrant particular attention.
Continuous catalytic isomerization of beta-pinene to myrcene is overtaking batch thermal cracking in fragrance intermediate production. German and Swiss flavor houses are retrofitting plants to handle the higher-throughput, lower-residue process. This technology compression is collapsing the historical premium between gum-derived and sulfate-derived pinene feedstocks in fine chemical applications.
REACH Annex XV dossier updates on respiratory sensitization are extending registration timelines for pinene oxide derivatives. ECHA's 2024 hazard classification revision forced several coating formulators to suspend specific adhesive product lines pending reformulation. Industrial buyers in the Netherlands and Belgium are now demanding pre-certified alternative terpenes before contract renewal.
Long-term offtake agreements with fixed-price escalators are displacing spot market purchasing among top-ten coatings manufacturers. North American architectural paint producers are locking three-year supply contracts directly with integrated forest chemical operators. This channel consolidation is most pronounced in the southeastern United States, where housing construction volatility makes raw material cost predictability a procurement priority.
Turpentine Market Segmentation
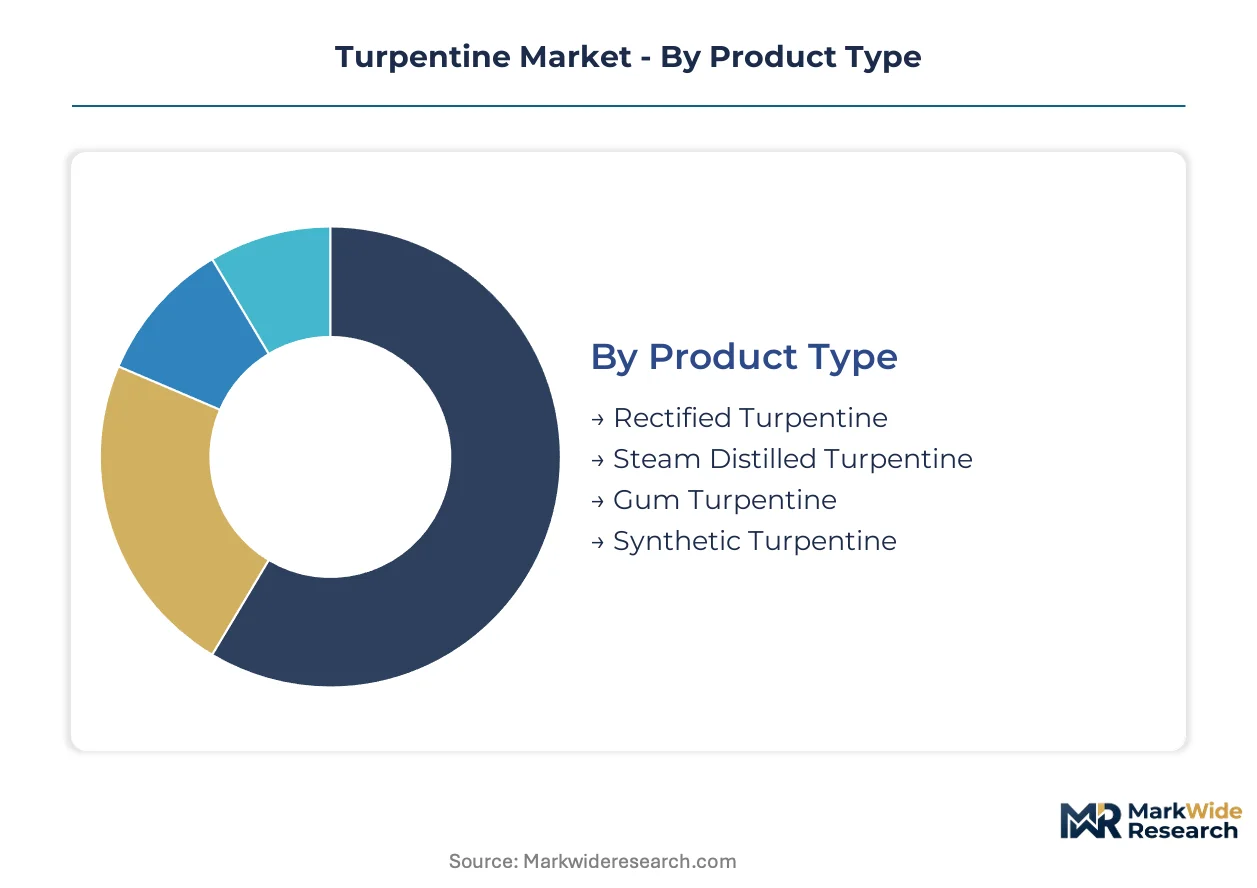
Product origin and distillation method determine specification premiums in turpentine procurement. Buyers in coatings and pharmaceuticals demand divergent purity thresholds, while packaging choices reflect volume scale and handling safety requirements across industrial supply chains.
Product Type:
Cost tiers separate specification buyers from volume purchasers in this category.
- Gum Turpentine:Extracted via steam distillation of pine oleoresin tapped from living trees, yielding alpha-pinene and beta-pinene fractions above 90% purity. Paint and varnish manufacturers in Germany and the Netherlands pay specification premiums for REACH-compliant bio-based certificates that satisfy EU Green Deal renewable content mandates.
- Synthetic Turpentine:Manufactured from petrochemical feedstocks through catalytic isomerization, offering batch-to-batch consistency at lower unit cost. Commodity coating producers in India and Indonesia prioritize this grade where formulation flexibility outweighs natural origin claims.
- Rectified Turpentine:Double-distilled to remove sulfur compounds and moisture, meeting pharmaceutical-grade purity standards for chiral intermediate synthesis.
- Steam Distilled Turpentine:Single-pass fractionation yielding industrial solvent specifications for adhesive and thinner applications.
Gum turpentine leads volumes today; synthetic turpentine is gaining share fastest.
Application:
End-use performance requirements dictate solvent selection across coating chemistries.
- Paints:Architectural and industrial formulations employ turpentine as a primary diluent for alkyd resins, with VOC compliance thresholds varying by jurisdiction. EPA limits under the Clean Air Act constrain permissible formulations in US residential coatings, while China's GB standards enforce purity minimums for interior applications.
- Adhesives:Pressure-sensitive and hot-melt systems utilize pinene derivatives as tackifier feedstocks, demanding specific terpene isomer ratios for bond strength optimization. Electronics packaging manufacturers in Japan and South Korea specify narrow distillation cuts for clean-room compatible bonding.
- Varnishes:Wood finishing applications favor gum-derived grades for drying time consistency and film clarity.
- Coatings:Protective and marine systems incorporate turpentine as a carrier solvent for corrosion inhibitors.
Paints dominate absolute consumption; adhesives show the steepest expansion trajectory.
End Use Industry:
Regulatory exposure and specification intensity vary sharply across buyer verticals.
- Construction:Residential and commercial building activity channels the largest solvent volumes through paint, varnish, and waterproofing applications. Infrastructure spending in China, India, and Indonesia directly scales turpentine procurement for site-ready coating systems.
- Pharmaceuticals:Chiral synthesis and fragrance intermediate production require pharmaceutical-grade pinene with documented impurity profiles. CDSCO registration pathways in India remain underexploited relative to industrial solvent markets.
- Automotive:Refinish coatings and assembly adhesives consume rectified grades for color matching and durability.
- Woodworking:Furniture and flooring manufacturers specify gum turpentine for traditional finish aesthetics and drying properties.
Construction leads volumes today; pharmaceuticals is climbing the fastest.
Packaging Type:
Volume scale and handling safety determine container selection across distribution channels.
- Bulk:Tanker and ISO-tank deliveries serve integrated coating manufacturers with continuous production lines, minimizing per-unit handling costs. Large formulators in the southeastern United States lock multi-year offtake agreements with fixed-price escalators to hedge construction sector volatility.
- Drums:200-liter steel containers balance portability with volume efficiency for mid-tier compounders and regional distributors.
- Cans:Smaller metal containers serve specialty adhesive producers and custom coating shops requiring precise batch control.
- Bottles:Glass and plastic vessels deliver laboratory and pilot-scale quantities for pharmaceutical R&D and quality testing.
Bulk leads volumes today; drums are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized distillation technicians in Guangxi province anchor upstream gum turpentine supply, while German and Dutch coatings formulators concentrate downstream demand for REACH-compliant bio-based solvents.
China
Guangxi province generates over half of global gum turpentine through oleoresin tapping operations in southern pine forests. SAMR-administered GB standards enforce purity thresholds that filter small-scale producers from pharmaceutical-grade supply chains. Wuzhou Pine Chemicals leverages captive forest access near the Vietnam border to secure raw material streams.
United States
Architectural coatings manufacturers in the Southeast lock multi-year supply contracts to hedge construction sector volatility. EPA Clean Air Act limits constrain VOC emissions from residential paint formulations. Kraton Corporation secures long-term solvent agreements with industrial buyers across the Gulf Coast chemical corridor.
Germany
Flavor houses in the Rhine-Ruhr region retrofit plants for continuous catalytic isomerization of beta-pinene to myrcene. ECHA's 2024 hazard classification revision forced coating formulators to suspend specific adhesive lines pending reformulation. Hamburg-based distributors demand pre-certified alternative terpenes before contract renewal.
India
CDSCO registration pathways for chiral pinene intermediates remain underexploited relative to industrial solvent markets. Construction activity in Maharashtra and Gujarat channels paint and varnish consumption through regional formulators. Deqing Yinlong Industrial positions through export relationships with Mumbai-based coatings compounders.
Indonesia
Improved tapping practices in Sumatran pine forests restore upstream raw material availability after weather disruptions. PT. Naval Overseas anchors supply relationships with Japanese electronics packaging manufacturers specifying narrow distillation cuts. Jakarta-based distributors consolidate procurement for domestic adhesive producers.
Turpentine Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Integrated forest chemical operators with captive resin access occupy the upstream extraction layer. Mid-scale fractionators serving regional coatings markets form a fragmented middle tier. Specialty chemical houses with bio-based product lines target VOC-compliant formulation niches. Capacity expansion and strategic partnerships dominate competitive moves as players secure long-term offtake agreements.
Within the integrated extraction tier, Wuzhou Pine Chemicals and Guilin Songquan Forest Chemical exemplify Chinese operators leveraging geographic proximity to Guangxi pine forests. Pine Chemical Group occupies a position among mid-scale fractionators serving Asian industrial markets. Kraton Corporation and Ingevity Corporation represent the specialty chemical archetype with differentiated bio-based portfolios targeting regulatory-compliant segments.
| Leading Market Players |
|---|
| Wuzhou Pine Chemicals Ltd. |
| PT. Naval Overseas |
| Guilin Songquan Forest Chemical Co., Ltd. |
| Pine Chemical Group |
| Forestar Chemical Co., Ltd. |
| Deqing Yinlong Industrial Co., Ltd. |
| DRT |
| Kraton Corporation |
| Ingevity Corporation |
| Others |
Value Chain & Pricing Dynamics
Fractionation technician scarcity in Guangxi province widens labor-cost differentials between southern Chinese extraction hubs and Southeast Asian competitors, compressing margin spreads between pharmaceutical-grade and industrial solvent tiers as vocational pipeline gaps persist.
Pricing Analysis
Long-term offtake contracts with fixed-price escalators dominate procurement for bulk buyers, while spot markets serve smaller compounders. Price differentiation rests on REACH certification status and volume scale, with EU-compliant bio-based certificates commanding premiums over commodity grades. Cost compression in synthetic turpentine is intensifying because petrochemical feedstock volatility undercuts natural terpene cost structures. Commodity coating producers in India and Indonesia exhibit highest price sensitivity; German and Dutch formulators purchasing REACH-compliant gum turpentine show lowest sensitivity due to regulatory lock-in.
Supply Chain Analysis
EU Green Deal domestic-content mandates for bio-based feedstocks are reshaping sourcing patterns toward verified sustainable extraction. Supply concentrates in China, Indonesia, and India, with Guangxi province alone generating over half of global gum turpentine. Raw material dependencies center on pine oleoresin harvests, sulfate pulping byproduct streams, and catalytic isomerization catalysts. Single-source vulnerability in southern Chinese pine forests creates structural supply risk. Distribution runs through integrated forest chemical operators directly to large coatings manufacturers, bypassing traditional distributor tiers for mid-volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU REACH compliance costs and EPA VOC thresholds in the United States create regulatory-cost differentials against Southeast Asian production bases with lower certification burdens.
For Market Incumbents: Hedge against crude sulfate turpentine price volatility by locking multi-year resin supply agreements with Guangxi tapping cooperatives. Deepen backward integration into Sumatran pine forest concessions to diversify climate-risk exposure beyond southern China. Prioritize carbon-border-adjustment readiness through lifecycle emissions verification to defend margin position against EU import cost shocks. For New Entrants and Emerging Players: Specialty chemical marketplaces offer the lowest-friction entry path for mid-volume coating compounders seeking technical specification matching. Target Indian pharmaceutical-grade pinene as the most penetrable white-space segment, where CDSCO registration pathways remain underexploited relative to industrial solvent saturation. Lead with direct-to-formulator digital channels rather than distributor-dependent legacy routes. For Investors and Strategic Acquirers: Integrated coatings manufacturers with captive solvent demand are the most active acquirer in this space, seeking upstream terpene security for VOC-compliant formulation pipelines. The viable acquisition window spans five to ten years as regulatory divergence between jurisdictions intensifies specification-premium capture. Monitor EU CBAM scope expansion as the critical inflection signal for bio-based extraction asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pine Forest Concessions | Captive oleoresin supply from Sumatran tapping operations reduces Guangxi concentration risk. |
| Long-term Supply Agreement with Fixed-price Escalators | Southeast US coatings manufacturers lock cost predictability against construction sector volatility. |
| Green Manufacturing Transition | Continuous catalytic isomerization retrofit cuts residue output for German flavor house compliance. |
| Joint Venture with Regional Distributor | Jakarta-based partnerships consolidate procurement for Indonesian adhesive producer networks. |
| Capacity Expansion in Pharmaceutical-grade Fractionation | Rectified turpentine output targets CDSCO-registered chiral intermediate demand in Maharashtra. |
Study Parameters
Direct dialogue with distillation plant managers, procurement leads at coatings manufacturers, distribution channel partners, and technical R&D directors in pine chemical operations grounded the qualitative foundation. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic sector reports, EPA Clean Air Act filing databases, and ECHA REACH registration dossiers. Bottom-up volume estimates from individual facility outputs triangulated against top-down demand-side consumption models across end-use industries.
Market size and growth trajectory outputs emerged from integrated segmentation modeling across product origin tiers, application categories, end-use verticals, and regional production hubs. CAGRs were derived through regression analysis of historical trade flows and forward projection of regulatory-driven formulation shifts. Key forecast inputs included kraft pulping capacity utilization rates as CST supply drivers and EU Green Deal implementation timelines for bio-based solvent mandates.
The model assumes a particular technology adoption path; alternative pathways for continuous catalytic isomerization versus batch thermal cracking would alter the competitive balance between gum-derived and sulfate-derived pinene feedstocks. Forecasts reflect documented assumptions regarding REACH-SAMR regulatory convergence timelines and climate resilience of Sumatran versus Guangxi pine harvests. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Flower Extract Market
Extracts
Agmatine Market
Extracts
Gum Turpentine Oil Market
Extracts
Nicotinic Acid Market
Extracts
Global Magnolia Bark Extract Market
Extracts
Cassia Extract Market
Extracts
Copaiba Essential Oil Market
Extracts
Frankincense Oil Market
Extracts
Global Marigold Flower Extract Market
Extracts
Palmarosa Oil Market
Extracts
Industrial Extractor Market
Extracts
Medicinal Plant Extracts Market
Extracts
Chlorophyll Extract Market
Extracts
Lemon Balm Extract Market
Extracts
Extracts and Distillates Market
Extracts
Functional Extract Market