
 North America Lactic Acid Market | 2026-2036
North America Lactic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lactic Acid Market Analytics
EPA bio-preferred procurement mandates are repositioning the competitive threshold for lactic acid suppliers seeking federal contracts. Corbion NV leverages its Nebraska fermentation complex to anchor North American supply security for food-grade and industrial grades alike. Cargill competes through backward integration into corn wet milling, capturing substrate cost advantages across the value chain. NatureWorks LLC specializes in polymer-grade lactic acid destined for Ingeo biopolymer production, occupying a differentiated tier above commodity suppliers.
Lactic acid is a chiral alpha-hydroxy acid produced via carbohydrate fermentation, typically achieving purity grades from 80% technical to 99%+ heat-stable for polymer synthesis, with the L-isomer dominating commercial output due to metabolic specificity of production organisms. Its primary purpose spans pH regulation in food systems, precursor supply for polylactic acid bioplastics, and active ingredient delivery in pharmaceutical formulations. The biodegradable plastics application leads structural expansion as packaging sector procurement shifts toward compostable alternatives, while food and beverage maintains the deepest margin pool through long-term supply contracts with institutional processors. Copolymer formulations are gaining fastest among product types as blend ratios tune thermal and mechanical properties for specific end uses.
The US EPA bio-preferred program and USDA biobased certification framework shape demand by creating procurement preference hierarchies for federal and institutional buyers, while FDA food additive regulations govern purity thresholds for ingestible applications. Health Canada and PMRA coordinate parallel standards for cross-border product registration, adding compliance layers for integrated North American suppliers. Stakeholders must monitor pending revisions to ASTM compostability standards and state-level extended producer responsibility laws that will determine which lactic acid-derived products qualify for premium environmental claims.
Market Dynamics
Fermentation substrate access in the US Midwest corn belt is concentrating processing capacity and reshaping competitive entry economics for new lactic acid producers. This geographic lock-in around corn wet milling infrastructure determines cost structures and supply security for polymer-grade output.
Growth Catalysts
- US EPA Bio-Preferred Program:Federal procurement mandates redirect institutional purchasing toward certified biobased feedstocks, creating guaranteed demand anchors for domestic fermentation capacity.
- Biodegradable Plastics Manufacturing:Packaging sector procurement is rotating toward compostable alternatives, pulling polymer-grade lactic acid volumes into blow-molding and thermoforming applications.
- Midwest Corn Belt Concentration:Proximity to glucose syrup and dextrose supply chains reduces logistics costs and substrate spoilage risk for fermentation operators.
Market Restraints
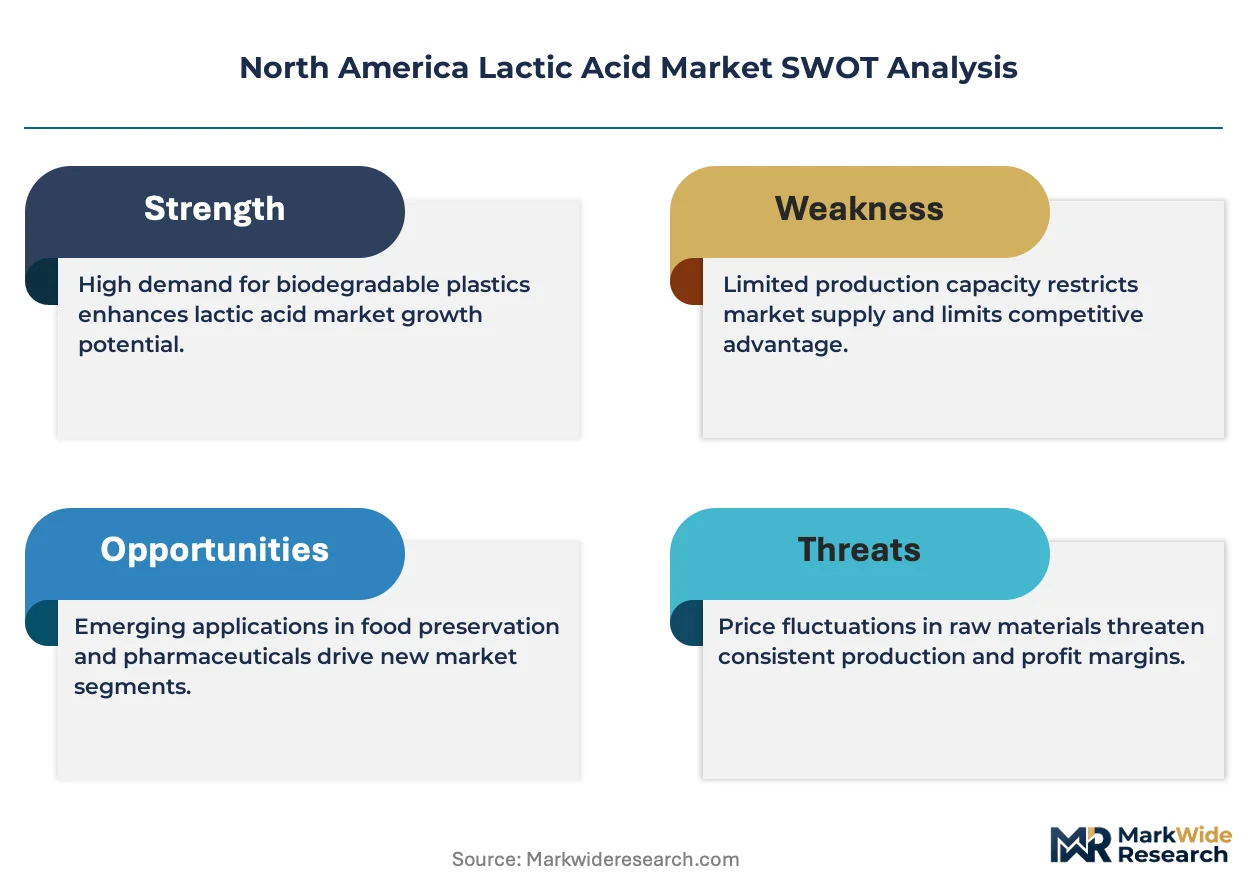
- Feedstock Price Volatility:Corn futures fluctuation transmits directly into lactic acid production economics, compressing margins during drought cycles or export demand surges.
- Polymer-Grade Purity Thresholds:Heat-stable 99%+ specifications for PLA precursor supply require capital-intensive purification trains that exclude smaller fermentation operators.
- Petrochemical Polypropylene Substitution:Fossil-based resins retain cost advantages at scale for non-compostable packaging applications, capping lactic acid penetration in price-sensitive segments.
Strategic Opportunities
- Canadian Federal Bioproducts Procurement:Health Canada and PMRA coordination on cross-border registration creates a secondary institutional demand pool with less saturated supplier competition.
- Copolymer Formulation R&D:Blend ratios tuning thermal and mechanical properties for specific end uses open premium pricing tiers above commodity PLA grades.
- State Extended Producer Responsibility Laws:Pending compostability certification requirements in California and New York will qualify lactic acid-derived products for environmental claim premiums.
Industry Challenges
- ASTM Compostability Certification Timelines:Multi-year testing protocols for D6400 and D6868 compliance delay product commercialization and tie up working capital.
- Fermentation Scale-Up Talent Scarcity:Industrial microbiology and downstream processing expertise concentrates at legacy operators, constraining new facility staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lactic Acid Market |
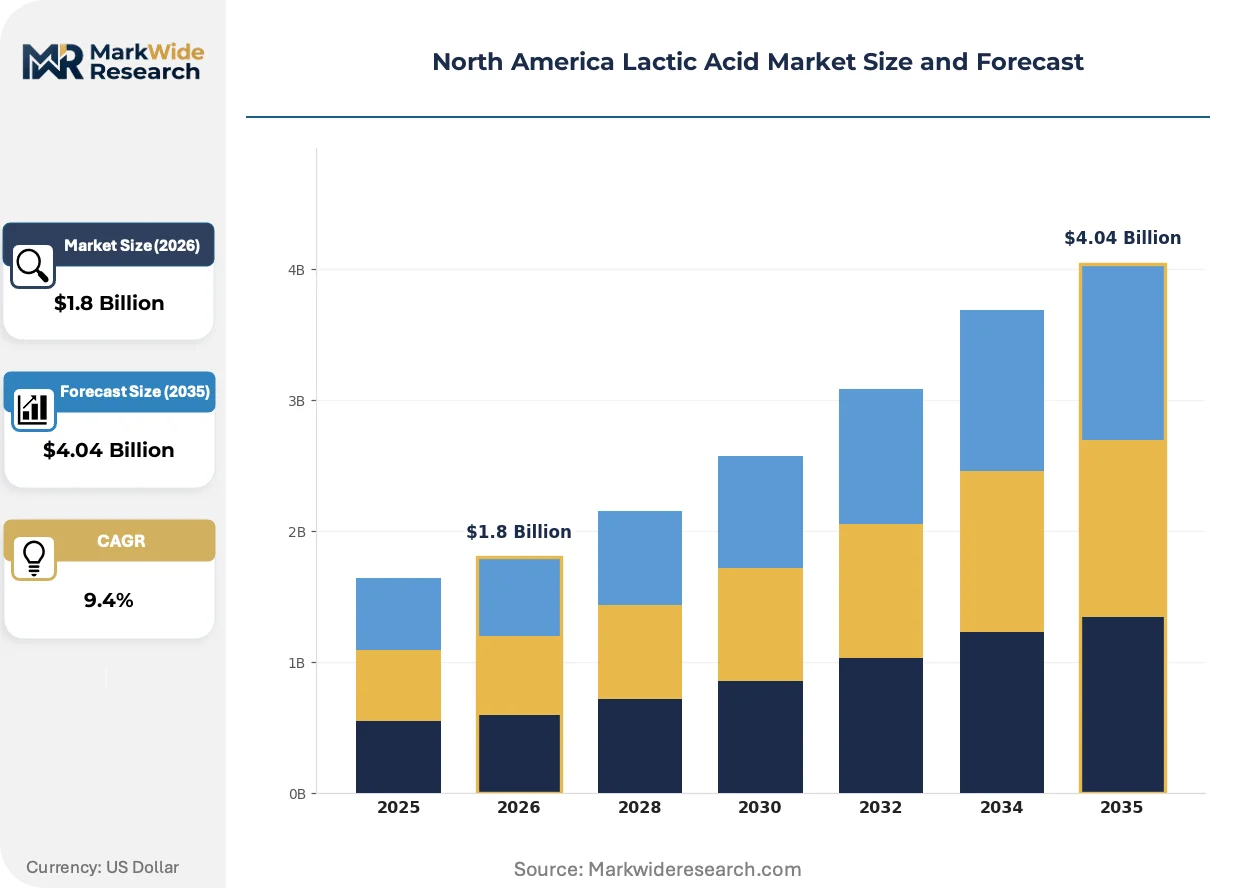
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hom polymer, Copolymer, Lactic Acid Derivatives, Amino Acid Application: Food & Beverage, Personal Care, Pharmaceuticals, Biodegradable Plastics End User: Food Industry, Cosmetic Manufacturers, Medical Device Companies, Packaging Sector Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Corbion NV, Cargill, Galactic, NatureWorks LLC, DuPont de Nemours Inc., Cellulac, Kemin Industries Inc., Jungbunzlauer Suisse AG, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lactic Acid Market Evolving Landscape
Continuous processing technologies and regulatory certification hierarchies are compressing batch fermentation economics while opening differentiated supply tiers for specialized polymer applications. These shifts favor capital-rich operators with captive substrate access.
Membrane filtration and simulated moving bed chromatography is absorbing purification workloads previously handled by crystallization and solvent extraction. PLA manufacturers are adopting these systems to meet heat-stable specifications for high-molecular-weight polymer production. This technology compression is raising the minimum viable scale for new fermentation entrants.
USDA Biobased Certification framework revisions are tightening measurement protocols for bio-content claims, forcing suppliers to document feedstock provenance through mass balance accounting. Food and beverage ingredient buyers are responding by auditing supplier fermentation records. This compliance intensification most affects technical-grade producers seeking to upgrade into ingestible applications.
Brand-led sustainable packaging commitments are compressing traditional resin procurement cycles, with CPG manufacturers requesting quarterly volume flexibilities rather than annual contracts. This demand volatility transmits back to lactic acid suppliers as offtake uncertainty. The phenomenon concentrates in California and Pacific Northwest markets where municipal composting infrastructure supports end-of-life claims.
North America Lactic Acid Market Segmentation
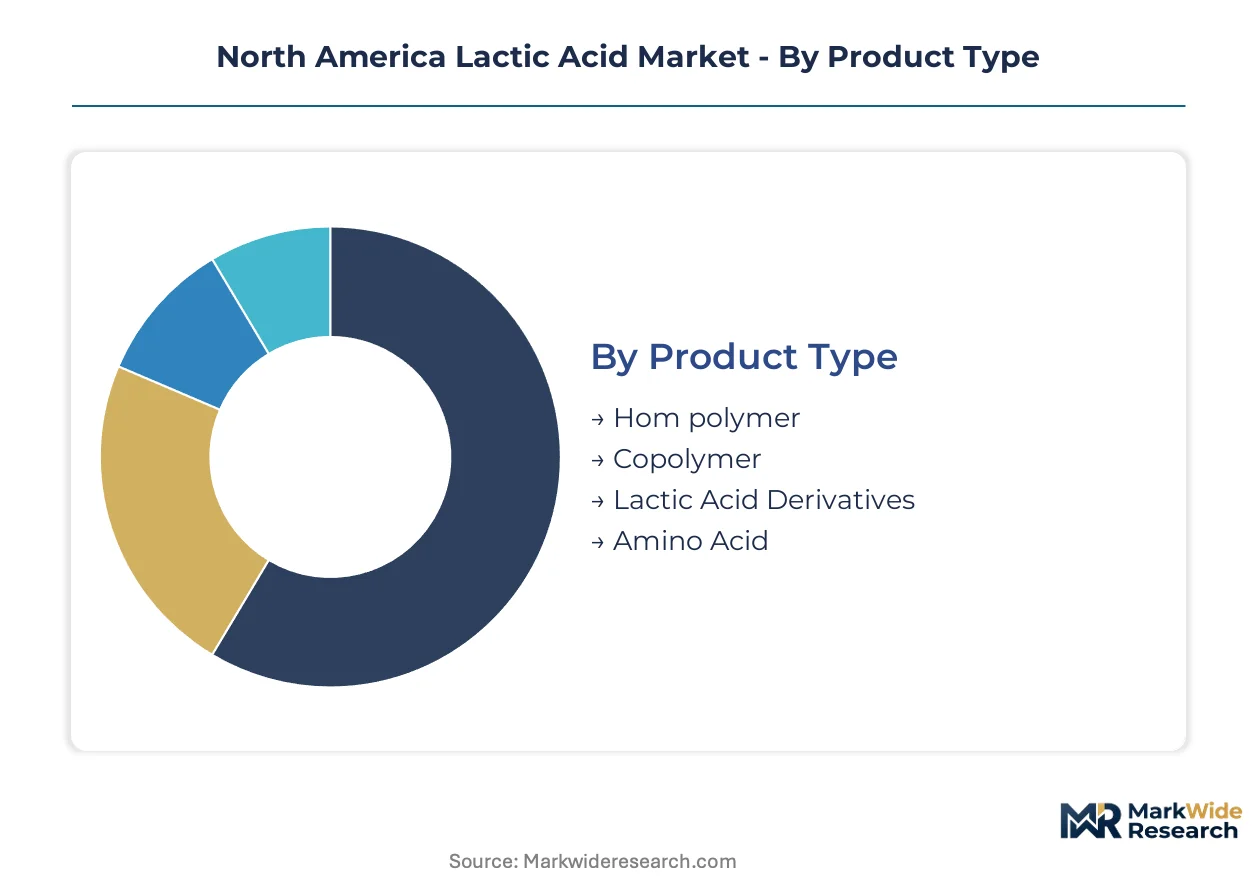
Lactic acid procurement patterns diverge sharply across purity grades and end-use specifications. Buyers segment supply contracts by fermentation scale, purification intensity, and regulatory certification tiers rather than commodity pricing alone.
Product Type:
Polymer-grade purity thresholds determine contract structures and supplier qualification timelines.
- Homopolymer:Linear PLA chains synthesized from high-purity L-lactic acid deliver crystallinity levels above 40% for thermoforming applications. Demand concentrates in Nebraska and Iowa blow-molding facilities serving CPG brands with compostable packaging mandates.
- Copolymer:Lactide copolymerization with glycolide or caprolactone tunes degradation rates and mechanical flexibility for medical sutures and agricultural films. California packaging converters specify these grades for extended shelf-life claims under ASTM D6400.
- Lactic Acid Derivatives:Esterified and oligomerized forms serve solvent and plasticizer applications in industrial coatings.
- Amino Acid:Fermentation coproduct streams from selected lactobacillus strains supply animal feed supplement markets.
Homopolymer leads on scale; copolymer leads on momentum.
Application:
Regulatory jurisdiction boundaries reshape volume allocation across state and federal procurement frameworks.
- Biodegradable Plastics:PLA precursor demand from thermoforming and fiber extrusion operations is climbing fastest in California and New York where municipal composting infrastructure validates end-of-life claims. FDA food-contact notifications and ASTM D6868 certification compress supplier qualification cycles to 18-24 months.
- Food & Beverage:pH regulation and preservative applications in institutional dairy and meat processing command the deepest contract pools through multi-year supply agreements with Midwest cooperatives.
- Pharmaceuticals:USP-grade material for parenteral formulations and excipient applications requires heat-stable 99.5%+ specifications.
- Personal Care:Alpha-hydroxy acid active ingredients in exfoliant formulations specify cosmetic-grade purity with heavy metal testing protocols.
Food & Beverage anchors contract value; biodegradable plastics is gaining share fastest.
End User:
Volume concentration and technical specification intensity segment buyer power across the value chain.
- Packaging Sector:Thermoformed food service items and flexible films specify polymer-grade lactic acid with molecular weight consistency above 100,000 Da. NatureWorks and TotalEnergies Corbion offtake agreements dominate this tier through captive fermentation capacity.
- Food Industry:Ingredient procurement from dairy processors and meat packers prioritizes 80-88% technical grade for pH adjustment and shelf-life extension.
- Medical Device Companies:Resorbable suture and implant manufacturers require GMP-certified lactide monomer with endotoxin testing.
- Cosmetic Manufacturers:Lactic acid esters for moisturizers and anti-aging serums demand cosmetic-grade certification with microbial limits.
Food Industry leads on scale; packaging sector leads on momentum.
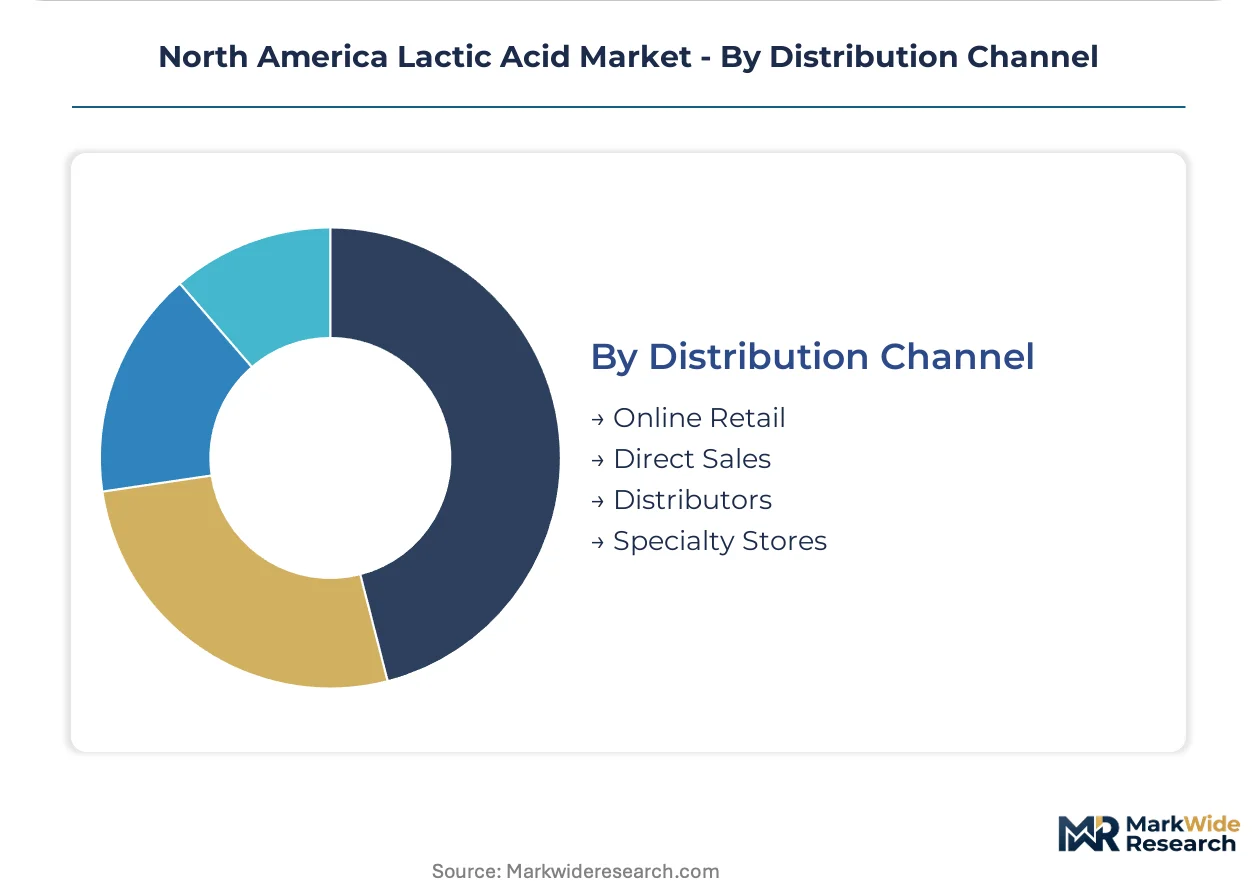
Distribution Channel:
Logistics configuration and buyer technical sophistication determine channel selection.
- Direct Sales:Polymer-grade volume contracts from PLA manufacturers and food processors bypass intermediaries to secure fermentation allocation and specification customization.
- Distributors:Technical-grade and food-grade material moves through chemical distribution networks serving regional compounders and ingredient blenders.
- Online Retail:Laboratory and small-batch cosmetic manufacturers procure reagent-grade material through specialty chemical platforms.
- Specialty Stores:Artisan food producers and craft cosmetic formulators source smaller volumes through regional ingredient suppliers.
Direct sales leads on scale; distributors leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American lactic acid industry traces its commercial scale to the 1990s when corn wet milling infrastructure in the US Midwest first enabled fermentation economics competitive with petrochemical routes.
United States
Midwest corn belt processors dominate substrate-access economics, with Nebraska and Iowa fermentation complexes supplying polymer-grade output to PLA manufacturers. EPA bio-preferred procurement mandates redirect federal purchasing toward certified biobased feedstocks, anchoring institutional demand. NatureWorks operates a Blair, Nebraska lactide facility converting lactic acid into Ingeo biopolymer resin.
Canada
Health Canada and PMRA coordinate cross-border registration standards that add compliance layers for integrated North American suppliers. Federal bioproducts procurement programs create a secondary institutional demand pool with less saturated supplier competition. Ontario and Quebec food processors import technical-grade material for pH regulation in dairy and meat applications.
Mexico
Packaging converters in the Mexico City Metro and Bajío Region specify imported polymer-grade lactic acid for thermoformed food service items serving export markets. USDA biobased certification requirements influence supplier qualification for cross-border ingredient sales. Jalisco's food processing cluster sources technical-grade material through distributors for preservative applications.
North America Lactic Acid Market Competitive Landscape
The competitive structure tilts toward substrate-integrated fermentation specialists with captive corn wet milling access. Three tiers separate commodity technical-grade suppliers from polymer-grade purification operators and captive biopolymer producers. Strategic differentiation runs through backward integration depth and regulatory certification breadth. Capacity expansion in Nebraska and partnership structures for Canadian market access represent dominant competitive moves.
Among fermentation specialists with Midwest infrastructure, Corbion NV and Cargill exemplify substrate-integrated archetypes, while NatureWorks LLC occupies a differentiated tier as a captive biopolymer producer. These three entities anchor supply security across food-grade, industrial-grade, and polymer-grade market segments respectively.
| Leading Market Players |
|---|
| Corbion NV |
| Cargill |
| Galactic |
| NatureWorks LLC |
| DuPont de Nemours Inc. |
| Cellulac |
| Kemin Industries Inc. |
| Jungbunzlauer Suisse AG |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Industrial microbiology talent concentration in the Nebraska-Iowa corridor feeds directly into pricing-tier spreads across polymer-grade and technical-grade lactic acid. Labor-cost differentials between captive fermentation specialists and toll processors widen the premium commanded for heat-stable 99%+ specifications.
Pricing Analysis
Contract-based long-term offtake agreements dominate polymer-grade procurement, while spot-market transactions govern technical-grade volumes. Price differentiation rests on fermentation scale and ASTM D6400 certification status, with uncertified material trading at steep discounts. Cost compression in technical-grade supply is intensifying because corn wet milling overcapacity in the Midwest compresses substrate conversion margins. Food and beverage processors exhibit the highest price sensitivity due to multi-year contract lock-ins, whereas medical device manufacturers absorb premiums for USP-grade material.
Supply Chain Analysis
Rail freight and bulk liquid tanker economics from the US Midwest corn belt determine delivered cost structures for lactic acid moving to California and New York packaging converters. Supply concentrates in the United States, with secondary fermentation capacity in Canada and import dependency in Mexico. Raw material flows draw from corn dextrose, glucose syrup, and lactose permeate streams. Single-source vulnerability around Nebraska-based fermentation complexes exposes buyers to localized weather disruptions. Distribution runs through direct sales for polymer-grade contracts and chemical distributors for technical-grade regional supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in North American lactic acid hinges on copolymer formulation premiums displacing commodity PLA pricing, while continuous processing technologies compress unit conversion costs.
For Market Incumbents: Deepen backward integration into corn wet milling to capture substrate margin pools currently leaking to toll processors. Expand Nebraska fermentation capacity to anchor polymer-grade supply security against emerging Canadian bioproducts procurement. Petrochemical polypropylene substitution threats intensify during oil price troughs, requiring certification investment to defend premium positioning. For New Entrants and Emerging Players: The price-point gap between polymer-grade and technical-grade lactic acid creates entry space for mid-purity fermentation operators serving California extended producer responsibility compliance markets. Target Canadian federal bioproducts procurement as the most penetrable institutional demand pool with less saturated supplier competition. Pursue copolymer formulation R&D partnerships with agricultural film manufacturers as the primary go-to-market angle. For Investors and Strategic Acquirers: Chemical conglomerates with existing fermentation infrastructure are the most active acquirer in this space, seeking biobased feedstock diversification. Long-term viability over a 5-10 year window favors substrate-integrated specialists with captive corn wet milling access. Monitor ASTM compostability certification backlogs as the critical inflection signal for premium product qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Wet Milling | Captures glucose syrup margin pools currently extracted by toll processors in Iowa. |
| Copolymer Formulation R&D Investment | Opens premium pricing tiers above commodity PLA through glycolide blend ratios. |
| ASTM D6400 Certification Acceleration | Qualifies products for California extended producer responsibility environmental claim premiums. |
| Canadian Federal Bioproducts Procurement Targeting | Accesses secondary institutional demand pool with less saturated supplier competition. |
| Continuous Processing Technology Adoption | Compresses batch fermentation economics through membrane filtration and simulated moving bed chromatography. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national regulatory jurisdiction. The research combines structured interviews with fermentation plant managers, PLA manufacturer procurement leads, chemical distribution channel partners, and USDA biobased certification auditors with secondary validation. Secondary sources include EPA bio-preferred procurement databases, USDA biobased product registry filings, Health Canada PMRA cross-border registration records, and SEC 10-K disclosures from publicly traded fermentation specialists. Bottom-up capacity modeling and top-down demand triangulation anchor volume estimates.
Granularity-level modeling disaggregates the North American lactic acid market across purity grade tiers, end-use applications, and regional production hub clusters. Segmentation dimensions include homopolymer versus copolymer product types, biodegradable plastics versus food and beverage versus pharmaceutical applications, and direct sales versus distributor channel structures. CAGRs were derived from trend extrapolation of historical fermentation capacity additions and projected PLA resin demand curves across the analysis window. Industry-specific forecast inputs incorporate corn futures price volatility assumptions and municipal composting infrastructure deployment timelines.
Caveats apply where corn price shocks, ASTM certification delays, or state-level extended producer responsibility law revisions could materially shift the outlook. Forecasts reflect documented assumptions about fermentation yield improvements and copolymer adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Precipitated Calcium Carbonate Market
Bulk Chemicals
Global Capric Acid Market
Bulk Chemicals
Foundry Coke Market
Bulk Chemicals
Benzyl Chloride Market
Bulk Chemicals
2-Ethyl Hexanol Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
Cellulose Powder Market
Bulk Chemicals
Ethylene Oxide Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
Sodium Silicate Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Isovaleryl Chloride Market