
 Global Crop Harvesting Robots Market | 2026-2036
Global Crop Harvesting Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Crop Harvesting Robots Market Analysis
Equipment leasing and robot-as-a-service models are narrowing the capital barrier that once favored only the largest farm operators. Deere & Company leverages its captive finance arm to bundle autonomous platforms with seasonal payment structures. AGCO Corporation competes through regionally distributed manufacturing that shortens delivery windows for European fruit cooperatives. FFRobotics specializes in gripper technologies for delicate produce, occupying a defensible niche in orchard automation where bruise rates determine contract viability.
Crop harvesting robots integrate computer vision, articulated manipulators, and mobile platforms to perform selective picking, cutting, or gathering of mature produce with minimal human intervention. These systems typically operate at sub-5-millimeter positional accuracy and incorporate spectral sensors to assess ripeness, replacing manual labor in repetitive, time-sensitive harvest windows. Autonomous harvesters command the largest revenue share among product types, though multi-crop solutions attract the fastest investment as growers seek to amortize capital across rotating seasonal programs. AI-based algorithms represent the most contested technology layer, where margin pools concentrate in proprietary training datasets rather than hardware fabrication.
The EPA governs pesticide application thresholds that determine whether robotic selective harvesting qualifies for reduced chemical use credits, while the EU F-Gas Regulation constrains refrigerant choices in post-harvest handling modules integrated with some harvester designs. Japan's METI subsidizes precision agriculture trials that include robotic harvesting in its Smart Agriculture pilot zones, creating a template that other ministries evaluate for export. Stakeholders must weigh whether to build in-house perception stacks or license them, as this decision locks in cost structures and update cadences for the operational lifespan of these machines.
Market Dynamics
Labor scarcity in specialty crop zones is compressing harvest windows and forcing capital deployment toward autonomous systems that operate continuously through narrow ripeness peaks. The EU Green Deal machinery mandates and California wage inflation create simultaneous regulatory and cost pressures that favor robotic substitution over seasonal migrant labor recruitment.
Growth Catalysts
- EU Green Deal electrification mandates:The Farm to Fork strategy accelerates manufacturer R&D toward battery-hybrid platforms, creating procurement preference for zero-emission harvesters in German and Dutch fruit cooperatives.
- California Central Valley labor economics:Specialty crop operators face wage inflation above 40% across five years, making robotic apple and strawberry pickers economically viable at smaller acreage thresholds.
- Japan METI Smart Agriculture pilots:Subsidized precision agriculture trials in pilot zones validate robotic harvesting protocols that ministries in South Korea and Taiwan evaluate for domestic adoption.
Market Restraints
- Lithium-ion battery supply concentration:Cell production concentrates in Chinese and South Korean facilities, exposing European and North American manufacturers to input cost volatility and export restriction risk.
- CE marking complexity for autonomous machinery:The Machinery Directive and emerging EU AI Act create overlapping conformity assessment requirements that extend product launch timelines by 8-14 months for articulated manipulator systems.
- Manual labor substitution limits in delicate crops:Table grape and soft-fruit harvesting still requires human tactile discrimination that robotic grippers cannot replicate at commercially viable bruise rates.
Strategic Opportunities
- Brazil citrus and coffee belt penetration:Mechanized harvesting remains under 15% in São Paulo and Minas Gerais orchards, creating first-mover advantage for multi-crop platforms adapted to tropical fruit geometries.
- Robot-as-a-service channel expansion:Leasing models with per-hectare pricing collapse capital barriers for mid-scale Italian and Spanish olive cooperatives previously excluded from autonomous equipment procurement.
- Computer vision and spectral sensor convergence:Integration of ripeness detection algorithms with real-time robotic control enables selective harvesting quality that commands premium pricing in export-oriented Chilean and New Zealand fruit sectors.
Industry Challenges
- Mechatronics and agronomy skill convergence:Field service technicians must diagnose hydraulic, electrical, and AI perception failures simultaneously, a competency combination scarce in rural labor markets.
- ISO 12100 and ISO 10218 safety certification timelines:Autonomous mobile manipulators require extensive risk assessment documentation that delays market entry, particularly for collaborative human-robot harvesting scenarios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Crop Harvesting Robots Market |
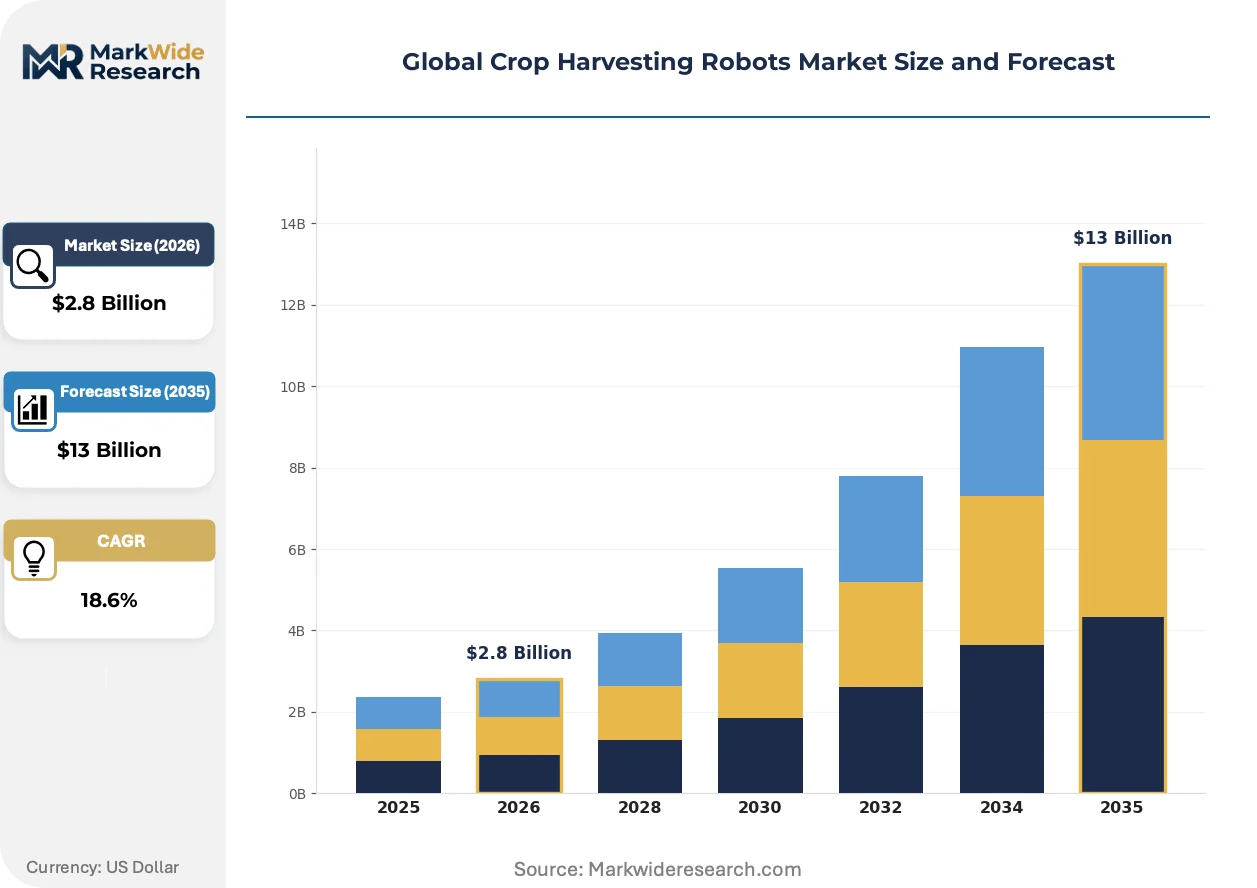
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Harvesters, Semi-Autonomous Machines, Specialized Equipment, Multi-Crop Solutions Technology: Computer Vision, AI-Based Algorithms, Machine Learning, Robotics End User: Farmers, Agricultural Enterprises, Cooperative Societies, Research Institutions Crop Type: Cereals, Fruits, Vegetables, Tubers |
| Companies Covered | Kubota Corporation, FFRobotics, Deere & Company, Harvest Automation, Clearpath Robotics Inc., AGCO Corporation, Yanmar Holdings Co. Ltd., Advanced Farms Technologies Inc., CNH Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Crop Harvesting Robots Market Emerging Trajectories
Selective harvesting algorithms are compressing the gap between robotic and human picking quality in orchard environments. Three parallel developments are reshaping how autonomous systems integrate into seasonal agricultural operations.
Deep learning-based ripeness classification is migrating from research-stage spectral imaging to commercial deployment in California almond and Washington apple operations. Large-scale permanent-crop growers now specify sub-millimeter positional accuracy and real-time bruise-rate feedback as standard procurement requirements. This capability compression is eroding the quality advantage that manual labor retained in high-value fruit segments.
The EU F-Gas Regulation constrains refrigerant choices in post-harvest modules integrated with harvester designs, forcing manufacturers toward CO2-based cooling systems. This compliance burden falls heaviest on European fruit cooperatives exporting to Middle Eastern markets where cold-chain integrity determines contract renewal. German and Italian equipment suppliers are accelerating modular designs that separate harvesting and cooling subsystems for independent certification.
Cooperative procurement consortia in Spain and Portugal are consolidating equipment orders to extract volume pricing and shared technical support from autonomous platform suppliers. This buyer concentration displaces the traditional dealer-network model where individual farms negotiated separate financing and service terms. The shift is most visible in Alentejo olive operations, where producer associations now specify multi-year fleet management contracts rather than discrete machine purchases.
Global Crop Harvesting Robots Market Segmentation
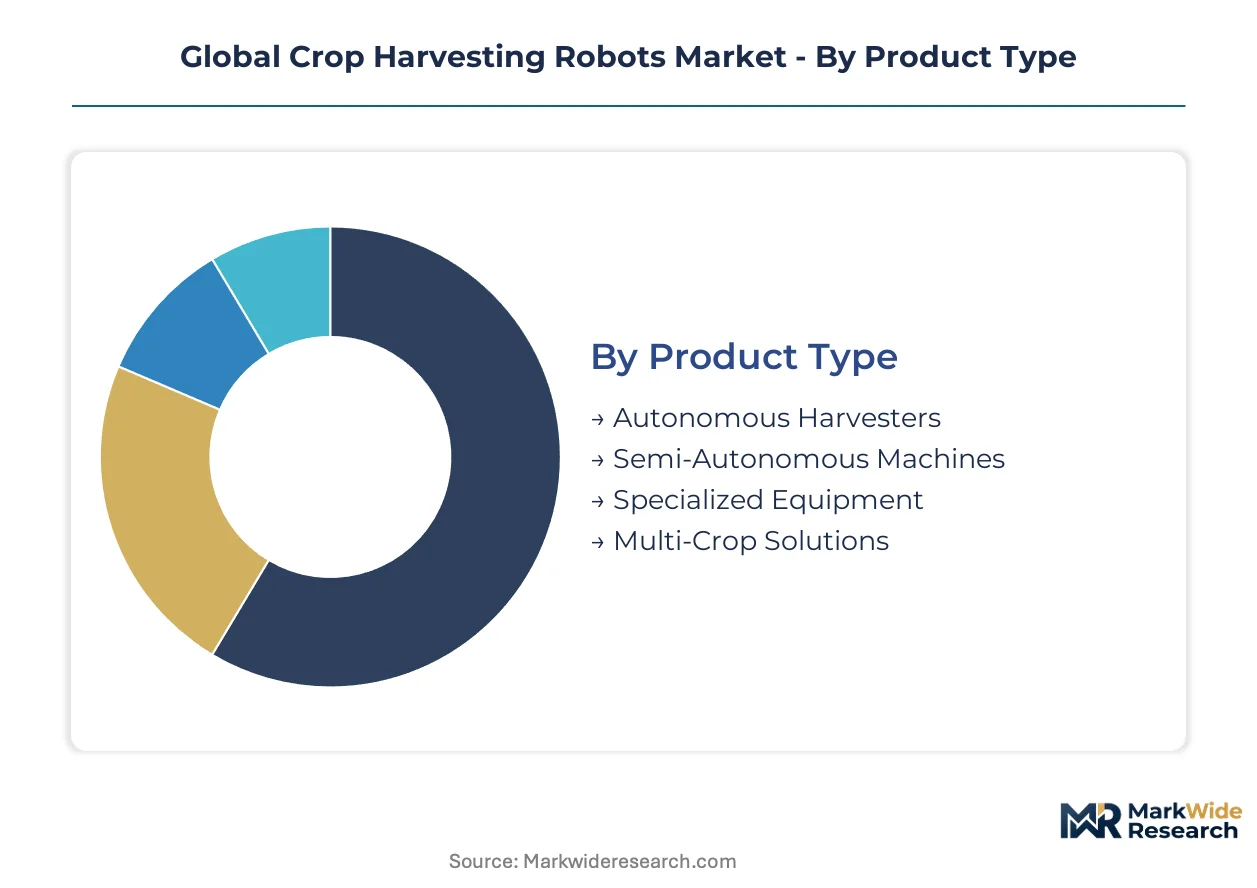
Segmentation in crop harvesting robotics reveals how technology specialization, end-user scale, and crop biology interact to determine equipment economics. Understanding these divides helps suppliers align R&D investment with procurement patterns that vary sharply across permanent-crop orchards versus row-crop fields.
Product Type:
Equipment configurations span fully autonomous platforms to human-augmented systems, with capital intensity and labor substitution depth determining adoption thresholds across farm scales.
- Autonomous Harvesters:These platforms integrate mobile bases with articulated manipulators and onboard perception stacks to execute complete harvest cycles without human operators. California almond growers and Washington apple cooperatives deploy these for continuous 20-hour operation through narrow ripeness windows where labor availability collapses. The dominant share belongs to Autonomous Harvesters, while Multi-Crop Solutions is closing the gap fastest.
- Semi-Autonomous Machines:Human operators supervise robotic subsystems for quality-critical tasks, reducing capital barriers for mid-scale Italian olive and Portuguese citrus farms. German fruit cooperatives favor this tier for phased automation transitions that preserve existing workforce relationships.
- Specialized Equipment:Single-crop platforms optimized for specific geometries—FFRobotics gripper systems for delicate tree fruits, root vegetable diggers with soil separation subsystems.
- Multi-Crop Solutions:Reconfigurable end-effectors and vision pipelines enable seasonal redeployment across rotating crop programs, amortizing capital across strawberry, lettuce, and brassica harvests.
Equipment choice tracks labor cost pressure intensity, with autonomous platforms concentrating where wage inflation exceeds mechanization payback thresholds.
Technology:
Technology layers separate into perception, decision, and actuation domains, with margin pools concentrating differentially across hardware versus software value capture.
- Computer Vision:Spectral and RGB imaging systems assess ripeness, detect defects, and guide manipulator positioning to sub-millimeter accuracy. Japanese METI pilot zones validate these protocols for export to South Korean and Taiwanese ministries evaluating domestic adoption templates.
- AI-Based Algorithms:Proprietary training datasets for ripeness classification and bruise prediction constitute the most contested intellectual property layer, locking in cost structures and update cadences for operational machine lifespans.
- Machine Learning:Field data feedback loops improve picking trajectories and grip force calibration across harvest seasons, with performance gains compounding for early-deployed fleets.
- Robotics:Mobile platform kinematics and manipulator hardware fabrication face margin compression from established industrial automation suppliers.
Software-defined capability gaps are expanding fastest, while hardware fabrication margins face commoditization pressure from cross-industrial automation vendors.
End User:
Procurement scale and financing access segment buyers into concentrated fleet operators versus distributed smallholders with divergent service model requirements.
- Farmers:Individual operators below 200 hectares rely on dealer networks and seasonal leasing for strawberry and lettuce robotic harvesters.
- Agricultural Enterprises:Large-scale permanent-crop operators in California's Central Valley and Alentejo olive zones specify multi-year fleet management contracts with integrated technical support.
- Cooperative Societies:Spanish and Portuguese producer associations consolidate equipment orders to extract volume pricing and shared field service coverage, displacing traditional individual farm negotiations.
- Research Institutions:Wageningen University and UC Davis pilot programs validate robotic protocols that manufacturers commercialize after field-scale demonstration.
Buyer concentration is shifting toward cooperative procurement, while enterprise-scale operators drive specification standards that cascade to smaller farm tiers.
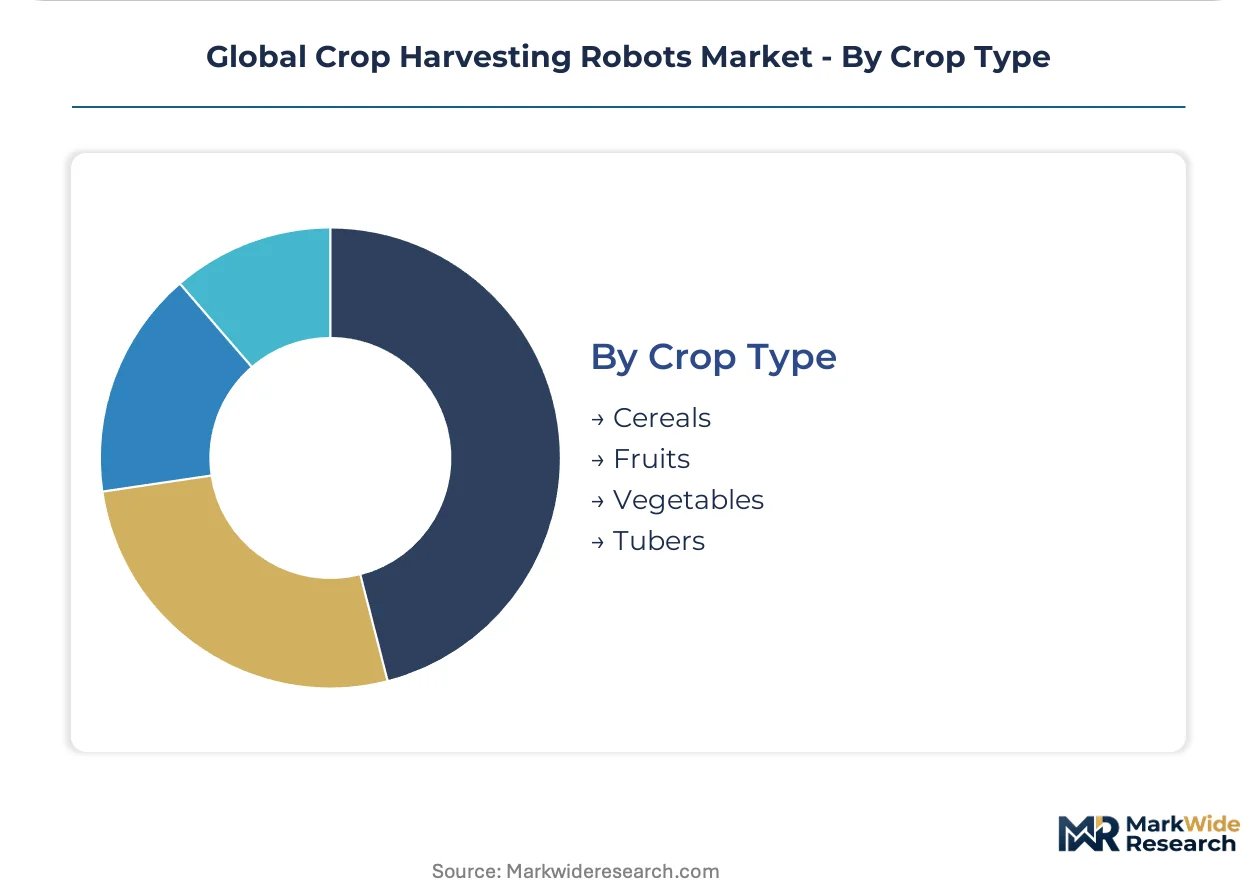
Crop Type:
Biological characteristics—structural rigidity, ripeness uniformity, and bruise sensitivity—determine robotic feasibility and equipment customization depth.
- Cereals:Combine harvester automation concentrates on path planning and yield mapping rather than selective picking, with commodity pricing limiting premium equipment penetration.
- Fruits:Apple, strawberry, and table grape operations face the steepest labor cost pressure, driving investment in gentle gripping and spectral ripeness detection where bruise rates determine contract viability.
- Vegetables:Lettuce and brassica harvesting employs cutting and gathering subsystems with less positional precision demand than tree fruits, enabling faster payback periods for mid-scale operators.
- Tubers:Potato and root vegetable systems integrate soil separation and damage minimization for underground extraction, with traction and digging force specifications dominating design priorities.
Fruit applications command the steepest technology investment, while cereal automation follows commodity equipment upgrade cycles with longer replacement horizons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale agricultural enterprises concentrate equipment procurement in jurisdictions combining steep labor cost pressure with supportive mechanization policy. Buyer archetypes span California almond cooperatives, Alentejo olive associations, and Japanese precision agriculture consortia.
United States
California's Central Valley specialty crop operators deploy autonomous harvesters for continuous 20-hour operation through narrow ripeness windows. EPA pesticide application thresholds determine whether robotic selective harvesting qualifies for reduced chemical use credits. Washington State apple cooperatives specify sub-millimeter positional accuracy as standard procurement requirements.
Germany
German fruit cooperatives favor semi-autonomous machines for phased automation transitions that preserve existing workforce relationships. EU F-Gas Regulation constrains refrigerant choices in post-harvest handling modules, forcing manufacturers toward CO2-based cooling systems. Bavarian equipment suppliers accelerate modular designs that separate harvesting and cooling subsystems for independent certification.
Japan
METI subsidizes precision agriculture trials in Smart Agriculture pilot zones that validate robotic harvesting protocols. Ministries in South Korea and Taiwan evaluate these templates for domestic adoption. Chubu region manufacturers supply perception stacks and articulated manipulators for export markets.
Brazil
Mechanized harvesting remains under 15% in São Paulo and Minas Gerais citrus and coffee orchards, creating first-mover advantage for multi-crop platforms. ANVISA regulates agricultural chemical residues that influence selective harvesting adoption. Sertaõ region coffee cooperatives test autonomous platforms adapted to tropical fruit geometries.
Spain
Alentejo olive operations consolidate equipment orders through producer associations specifying multi-year fleet management contracts. CE marking complexity for autonomous machinery extends product launch timelines by 8-14 months for articulated manipulator systems. Andalusian citrus cooperatives extract volume pricing and shared technical support through consolidated procurement.
Global Crop Harvesting Robots Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where captive finance arms and regional manufacturing networks determine market access. The vendor base separates into three strategic archetypes: diversified agricultural equipment conglomerates with integrated financing, robotics specialists focused on gripper and perception technologies, and regional machinery fabricators with crop-specific expertise. Dominant competitive moves include M&A to acquire computer vision capabilities and strategic partnerships to secure lithium-ion battery supply.
Within the diversified equipment tier, Deere & Company and Kubota Corporation anchor positions through captive finance bundling and distributed manufacturing networks. FFRobotics exemplifies the specialist archetype, occupying a defensible niche in orchard automation. AGCO Corporation sits within the regional-adaptation vector, competing through shortened delivery windows for European fruit cooperatives. These three represent the competitive spectrum from scale-driven platform provision to precision gripper engineering.
| Leading Market Players |
|---|
| Kubota Corporation |
| FFRobotics |
| Deere & Company |
| Harvest Automation |
| Clearpath Robotics Inc. |
| AGCO Corporation |
| Yanmar Holdings Co. Ltd. |
| Advanced Farms Technologies Inc. |
| CNH Industrial |
| Others |
Supply Flow & Price Mechanics
Lithium-ion battery supply concentration in Chinese and South Korean facilities determines both pricing tier spreads and supply chain shape for autonomous harvester manufacturers, exposing European and North American assemblers to input cost volatility that compresses margins across premium and standard equipment tiers.
Pricing Analysis
Cost-plus contracts with lithium cell indexation dominate equipment procurement, tying final harvester prices to commodity-linked benchmarks. Price differentiation stems from CE marking tier complexity and after-sales service bundling, with German fruit cooperatives paying premiums for integrated technical support. Cost compression in standard-tier platforms is intensifying due to Chinese battery export restrictions. Mid-scale Italian olive farms exhibit highest price sensitivity, while California almond enterprises accept premium positioning for continuous-operation guarantees.
Supply Chain Analysis
Upstream feedstock for robotic harvesters draws from Japanese precision sensor manufacturers, German hydraulic component fabricators, and Chinese lithium cell producers. Critical dependencies include rare-earth magnets for manipulator motors, spectral imaging sensors, and high-density battery packs. Single-source vulnerability concentrates in solid-state LiDAR modules sourced from select Chubu region suppliers. Distribution runs through regional equipment dealers transitioning to cooperative consortium direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
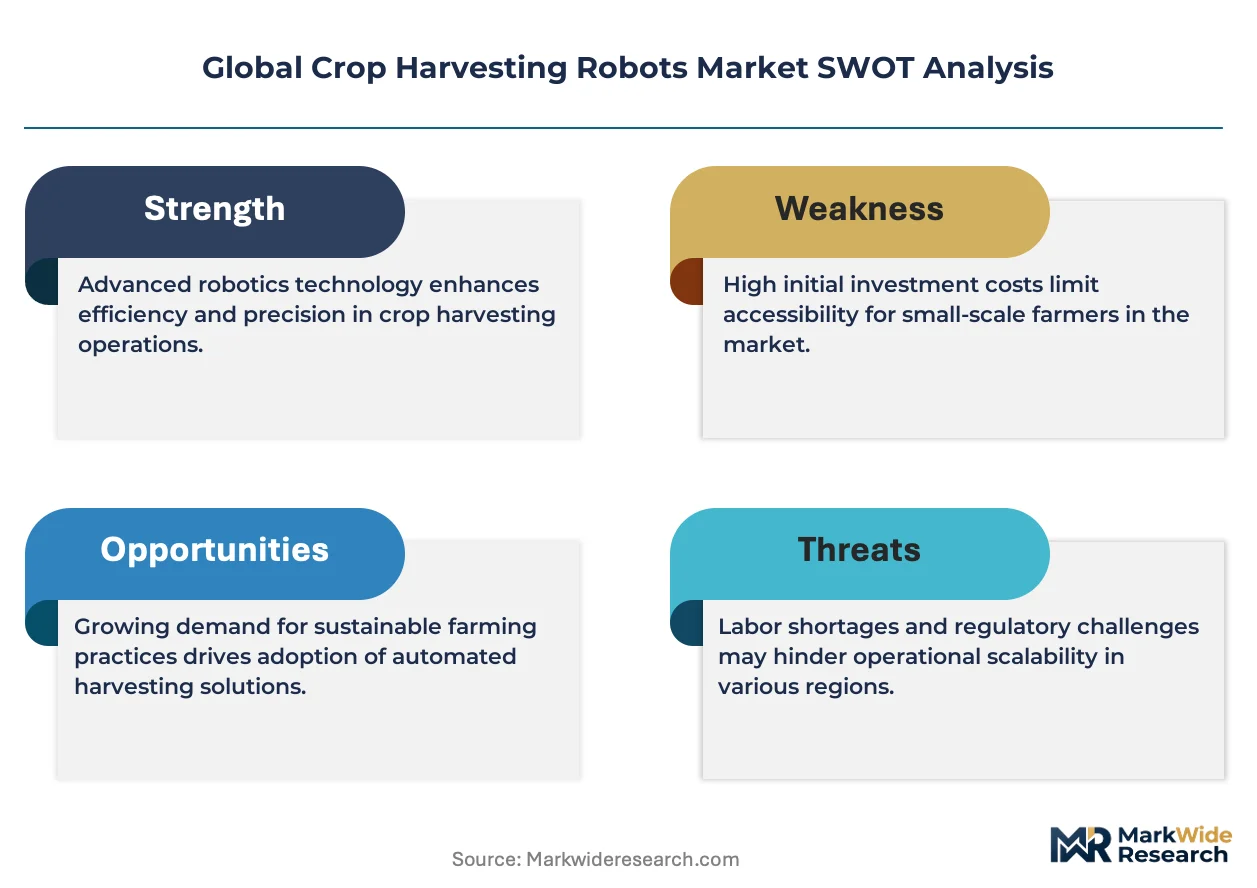
This market functions as a defensive-moat story where regulatory entrenchment in EU machinery certification creates switching costs that protect early-compliant manufacturers from late entrants.
For Market Incumbents: Build data-network moats through proprietary ripeness classification datasets that improve with fleet scale. Incumbent harvester manufacturers should deepen backward integration into perception stack development to offset emerging pure-play robotics entrants. CE marking complexity and ISO 10218 certification timelines serve as structural barriers that favor established players with documented safety systems. For New Entrants and Emerging Players: Build out white-space positions in Brazil's São Paulo citrus belt and Minas Gerais coffee zones where mechanization penetration remains below fifteen percent. New entrants should prioritize robot-as-a-service leasing models with per-hectare pricing to bypass capital barriers excluding mid-scale operators from equipment ownership. Cooperative procurement consortia in Alentejo olive operations represent the most penetrable buyer archetype. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward perception-software specialists with documented conformity assessment pathways. Long-term viability favors targets with captive training datasets and established field service networks in specialty crop regions. Watch METI subsidy renewal decisions as the signal indicating Asian precision agriculture commitment levels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Systems | Captive cell supply insulates German manufacturers from Chinese export restriction volatility. |
| Per-Hectare Service Contract Launch | Robot-as-a-service pricing collapses capital barriers for Spanish olive cooperatives. |
| CE Marking Fast-Track Investment | Accelerated conformity assessment compresses EU market entry timelines for articulated manipulators. |
| Spectral Sensor Partnership | Integration with Japanese perception stack suppliers enables sub-millimeter ripeness detection accuracy. |
| Brazilian Assembly Footprint | Regional manufacturing shortens delivery windows for São Paulo citrus belt first-mover positioning. |
Methodological Framework
A spread of perspectives from agricultural equipment procurement officers, cooperative consortium managers, robotic perception engineers, and field service technicians converged on the working assumptions. Primary interview data combined with secondary validation from EU Machinery Directive filings, EPA pesticide application databases, METI Smart Agriculture pilot reports, and customs trade records. Bottom-up equipment shipment tallies and top-down agricultural mechanization spend estimates were triangulated to anchor projections.
Demand-supply balance framing shaped the analytical approach across the projection horizon. Segmentation dimensions modeled include product autonomy tier, gripper technology type, end-user scale category, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and labor cost elasticity estimates. Forecast inputs incorporated California wage inflation trajectories and EU Green Deal electrification mandate compliance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese battery manufacturers or accelerated F-Gas Regulation enforcement would shift outcomes. Cross-checking against agricultural machinery association shipment data and national farm labor statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
India Tractor Market