
 Plastic Pipe Jointing and Welding Market | 2026-2036
Plastic Pipe Jointing and Welding Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Pipe Jointing and Welding Market Analytics
Equipment leasing and project-based financing is fragmenting competitive dynamics in plastic pipe jointing. McElroy Manufacturing anchors its position through captive manufacturing of fusion machines across North American rental channels. Georg Fischer Ltd. leverages its Swiss engineering heritage to dominate high-purity PP jointing for semiconductor fabs. RITMO S.p.A. specializes in portable electrofusion units that compete effectively in European municipal tenders.
Plastic pipe jointing and welding encompasses thermal and mechanical processes that create pressure-tight, structurally continuous bonds between thermoplastic segments, typically operating at temperatures between 200°C and 240°C for HDPE butt fusion and requiring precise heater plate surface roughness below 3.2 micrometers to ensure molecular interdiffusion. These techniques serve primarily to eliminate leakage paths in fluid conveyance systems while accommodating thermal expansion and ground movement. Heat fusion equipment commands the largest installed base among joining methods, though electrofusion represents the fastest-growing category as remote welding capability reduces labor certification burdens. Municipal water supply applications generate the most stable margin pools, while gas distribution jointing demands the highest certification barriers.
The US EPA's Lead and Copper Rule Revision drives replacement schedules that accelerate demand for certified fusion procedures in potable water networks. China's MEE enforces stricter leakage standards for polyethylene gas distribution pipelines, elevating requirements for traceable electrofusion records. India's BIS certification for HDPE pipe joints mandates third-party testing that filters out uncertified equipment suppliers. Stakeholders must monitor how digital welding traceability requirements propagate across national standards to anticipate capital allocation for compliance infrastructure.
Market Dynamics
Digital welding traceability mandates are forcing capital reallocation toward compliance infrastructure across the plastic pipe jointing value chain, compressing margins for equipment suppliers lacking integrated data-logging capabilities.
Growth Catalysts
- US EPA Lead and Copper Rule Revision:Replacement schedules for potable water networks accelerate certified fusion procedure adoption, creating sustained equipment demand across municipal utilities.
- HDPE irrigation networks:India's northern agricultural belt is replacing aging metal systems with polyethylene infrastructure, driving electrofusion unit procurement.
- China's GB standards:Tightening polyethylene pipeline integrity requirements elevate joint performance specifications, filtering non-compliant suppliers from state-backed projects.
Market Restraints
- Heater plate surface roughness tolerances:Precision requirements below 3.2 micrometers limit viable equipment suppliers to those with captive machining capabilities.
- Copper and brass fitting substitution:Metal alternatives retain preference in high-temperature industrial applications above polyethylene thermal limits.
- Electrofusion wire coil supply:Concentration of precision resistor manufacturing in East Asian foundries creates input vulnerability for European equipment assemblers.
Strategic Opportunities
- Remote welding capability:Electrofusion systems with reduced labor certification burdens penetrate Southeast Asian municipal tenders where skilled technician scarcity constrains project timelines.
- Semiconductor fab construction:High-purity polypropylene jointing demand rises with cleanroom infrastructure expansion, commanding premium pricing over standard municipal applications.
- Equipment-as-a-service models:North American rental channels fragment ownership economics, opening recurring revenue streams for fusion machine providers.
Industry Challenges
- Certified welder scarcity:Gas distribution jointing demands the highest certification barriers, creating bottlenecks in project execution timelines.
- Third-party testing infrastructure:India's BIS certification mandates strain laboratory capacity, extending equipment qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Pipe Jointing and Welding Market |
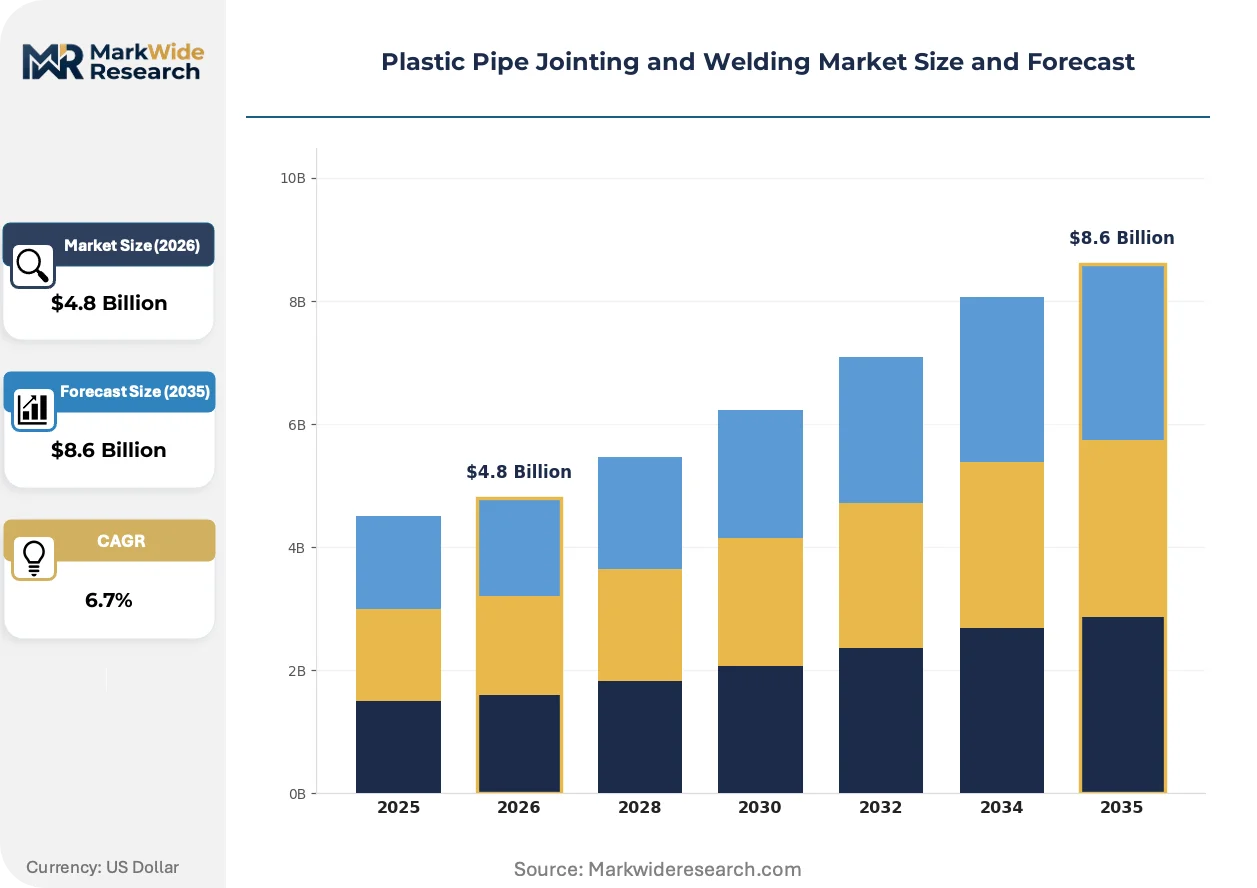
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, HDPE, PP, CPVC Joining Method: Heat Fusion, Solvent Welding, Mechanical Fittings, Electrofusion End User: Construction, Agriculture, Industrial, Municipal Application: Water Supply, Drainage, Irrigation, Gas Distribution |
| Companies Covered | RITMO S.p.A., Fusion Group Ltd., Georg Fischer Ltd., Asahi Yukizai Corporation, WIDOS Wilhelm Dommer Söhne GmbH, McElroy Manufacturing, Inc., Rothenberger AG, Caldertech, Dukane IAS, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Pipe Jointing and Welding Market Evolving Landscape
Automation and data integration are compressing the skill gap between certified and uncertified welding operations while fragmenting traditional equipment ownership models across municipal and industrial segments.
Electrofusion control systems with embedded barcode scanners and cloud-synced weld records are hybridizing quality assurance with project management workflows. Municipal contractors in Germany and the Netherlands adopt these units fastest. The technology is hybridizing equipment vendors into software service providers, capturing recurring revenue from previously transactional hardware sales.
China's MEE leakage standards for polyethylene gas distribution pipelines mandate traceable electrofusion records with GPS-tagged weld locations. Equipment suppliers must retrofit data-logging modules or exit state tender eligibility. Gas distribution operators in Sichuan and Shandong provinces face the steepest compliance timelines, accelerating replacement of legacy fusion machines.
Leasing arrangements now dominate capital acquisition for mid-sized contractors, displacing outright equipment purchases. Municipal water authorities in Australia and Canada pilot subscription-based fusion machine access with bundled maintenance and recertification. This model concentrates most visibly in Canada, where provincial infrastructure banks underwrite equipment financing for First Nations water system upgrades.
Plastic Pipe Jointing and Welding Market Segmentation
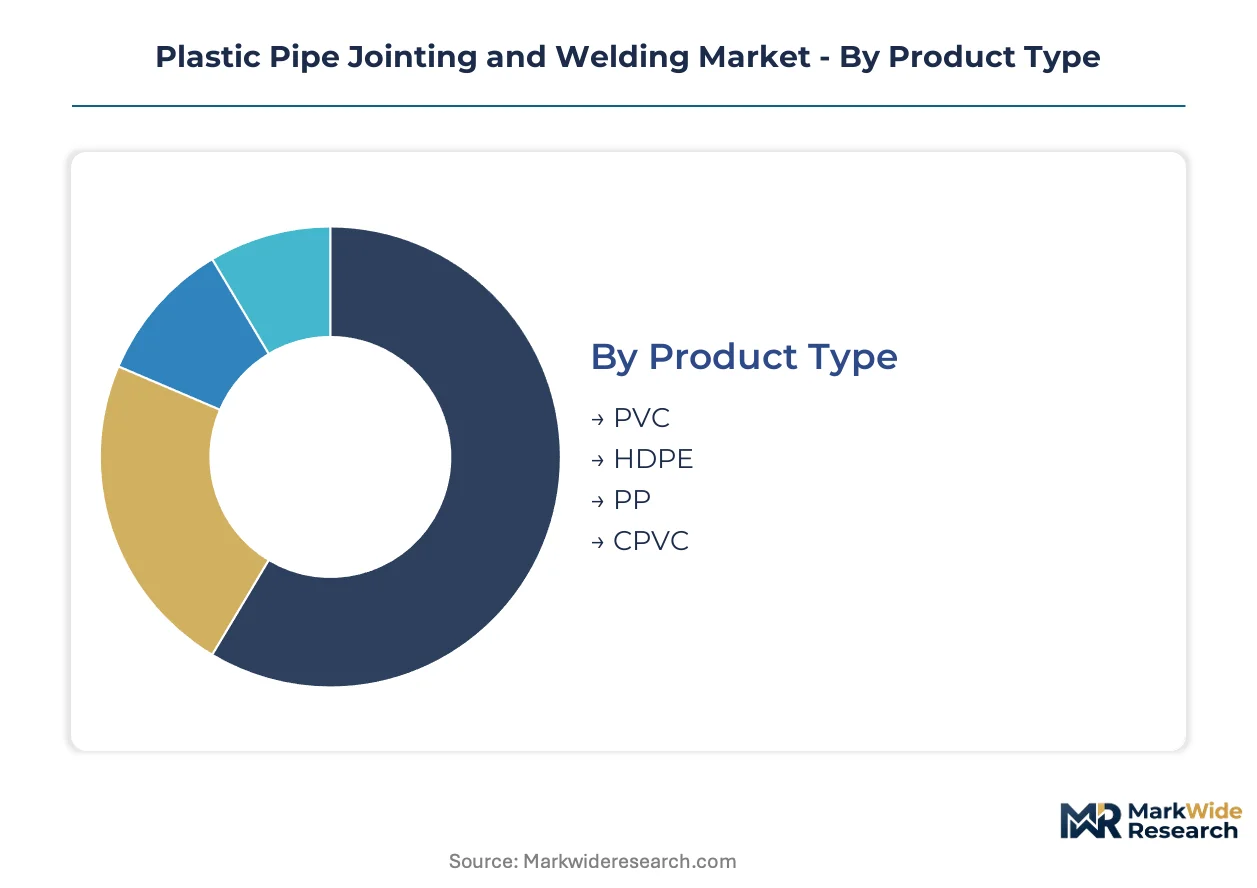
Segmentation in plastic pipe jointing reveals divergent service intensity profiles across material grades and joining technologies. Equipment lifecycle management, calibration frequency, and technician recertification obligations vary sharply between electrofusion systems and mechanical fitting approaches, reshaping vendor revenue models.
Product Type:
After-sales service intensity escalates with material thermal sensitivity and fusion parameter precision requirements, creating tiered support obligations that separate premium-grade system suppliers from commodity equipment vendors.
- HDPE:High-density polyethylene demands heater plate surface roughness below 3.2 micrometers for molecular interdiffusion, requiring precision machining capabilities and frequent plate resurfacing services. India's northern agricultural belt concentrates procurement for irrigation network replacement, with BIS certification mandates filtering uncertified suppliers from state tenders.
- PP:Polypropylene jointing for semiconductor cleanroom infrastructure commands premium pricing over standard municipal applications, with Swiss-engineered high-purity systems dominating fab construction in East Asian technology corridors. Traceable weld records with GPS tagging are becoming mandatory for state eligibility.
- PVC:Solvent welding dominates residential drainage applications where lower thermal precision reduces service intensity.
- CPVC:Chlorinated polyvinyl chloride serves elevated-temperature industrial fluid systems with specialized primer and cement formulations.
HDPE holds the largest share; momentum sits with PP as semiconductor fab construction accelerates.
Joining Method:
Capital deployment patterns fragment across ownership models, with subscription-based access displacing outright equipment purchases in municipal procurement.
- Electrofusion:Embedded barcode scanners and cloud-synced weld records hybridize quality assurance with project management workflows, capturing recurring software revenue from previously transactional hardware sales. Germany and the Netherlands adopt these units fastest among municipal contractors, while China's MEE leakage standards mandate retrofitting data-logging modules for state tender eligibility.
- Heat Fusion:Butt fusion equipment commands the largest installed base, operating at 200°C to 240°C for HDPE with heater plate surface roughness tolerances limiting viable suppliers to those with captive machining capabilities.
- Mechanical Fittings:Compression and flanged connections serve temporary installations and repair scenarios where thermal fusion is impractical.
- Solvent Welding:Chemical bonding dominates PVC applications in residential and light commercial construction with minimal equipment capital requirements.
Heat Fusion retains the largest installed base; Electrofusion is climbing the fastest as remote welding capability reduces labor certification burdens.
End User:
Certification barrier height determines vendor stickiness, with gas distribution and municipal water segments imposing qualification cycles that strain laboratory capacity.
- Municipal:Water supply applications generate the most stable margin pools, with Australia's infrastructure banks underwriting equipment financing for First Nations system upgrades through subscription-based fusion machine access.
- Agriculture:India's northern belt drives electrofusion unit procurement as HDPE irrigation networks replace aging metal systems, though certified welder scarcity constrains project timelines.
- Construction:Residential and commercial building contractors favor mechanical fittings and solvent welding for speed and lower skill requirements.
- Industrial:High-temperature applications above polyethylene thermal limits retain preference for copper and brass fitting alternatives.
Municipal holds the largest share; Agriculture is gaining share fastest as state-backed irrigation modernization accelerates.
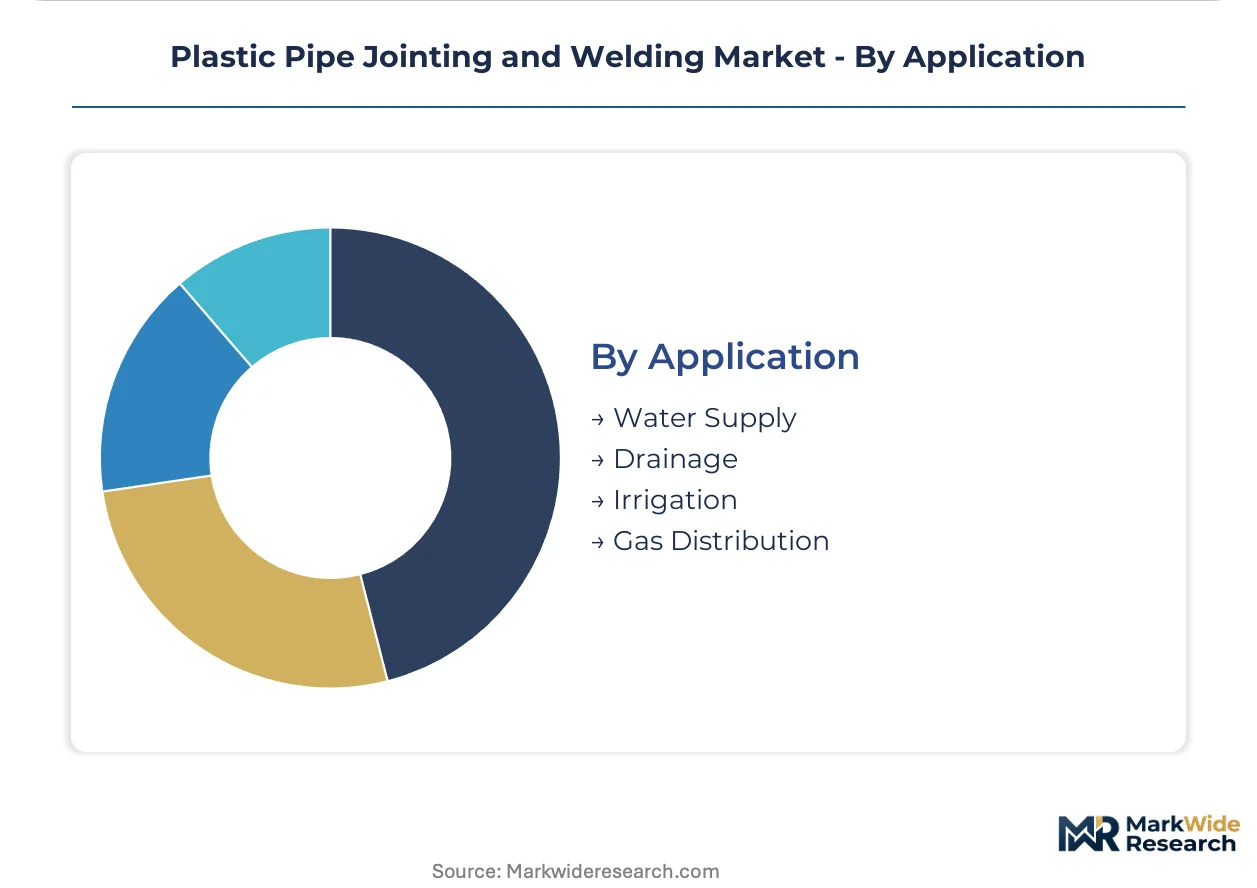
Application:
Leakage liability exposure and regulatory traceability mandates concentrate investment in gas distribution and potable water networks.
- Gas Distribution:China's MEE enforces strictest leakage standards for polyethylene pipelines, elevating requirements for traceable electrofusion records with GPS-tagged weld locations in Sichuan and Shandong provinces.
- Water Supply:The US EPA's Lead and Copper Rule Revision drives replacement schedules that accelerate demand for certified fusion procedures in potable water networks across municipal utilities.
- Irrigation:India's northern agricultural belt concentrates HDPE network deployment with third-party BIS certification filtering equipment suppliers.
- Drainage:Gravity-flow sewer applications tolerate lower joint precision, reducing equipment qualification barriers.
Water Supply holds the largest share; Gas Distribution commands the steepest expansion trajectory as digital traceability mandates propagate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in plastic pipe jointing equipment tilt toward net-importing jurisdictions with accelerating infrastructure replacement cycles. Export-oriented fabrication clusters in Germany, Switzerland, and the United States supply precision fusion machinery to Asia-Pacific municipal utilities confronting certified technician shortages.
United States
Municipal water authorities drive electrofusion procurement under EPA Lead and Copper Rule Revision timelines. State revolving funds prioritize certified fusion procedures for potable network replacement. Texas and California utilities concentrate demand for data-logging equipment that satisfies procurement traceability mandates.
China
MEE leakage standards for polyethylene gas pipelines mandate GPS-tagged weld records with retrofitted data-logging modules. Sichuan and Shandong provinces face compressed compliance timelines. Yangtze River Delta fabricators supply electrofusion control systems to state-backed municipal tenders.
Germany
Municipal contractors adopt barcode-integrated electrofusion units fastest among European markets. ECHA chemical compliance elevates material specifications for heater plate coatings. Ruhr Valley infrastructure banks underwrite subscription-based fusion machine access for mid-sized contractors.
India
BIS certification for HDPE pipe joints mandates third-party testing that filters uncertified equipment suppliers from state tenders. Punjab and Haryana agricultural belts replace aging metal irrigation systems with polyethylene networks. Certified welder scarcity constrains project execution timelines in northern procurement zones.
Canada
Provincial infrastructure banks finance equipment subscriptions for First Nations water system upgrades. Ontario and Alberta municipal authorities pilot bundled maintenance and recertification models. Cold-climate fusion protocols demand specialized heater plate calibration services that concentrate vendor support obligations.
Plastic Pipe Jointing and Welding Market Competitive Landscape
On the supply side, the industry is consolidating around three capability tiers differentiated by precision machining and software integration depth. Swiss and German engineering heritage anchors premium positioning for high-purity applications. North American rental channel penetration fragments ownership economics toward equipment-as-a-service models. Dominant competitive moves include captive manufacturing of fusion machines and strategic partnerships with municipal financing vehicles.
Within the precision-engineering tier, Georg Fischer Ltd. exemplifies Swiss-engineered high-purity positioning for semiconductor fab construction. McElroy Manufacturing, Inc. anchors North American rental channel penetration through captive production capabilities. RITMO S.p.A. occupies the portable electrofusion specialist position competing in European municipal tenders where remote welding capability reduces labor certification burdens.
| Leading Market Players |
|---|
| RITMO S.p.A. |
| Fusion Group Ltd. |
| Georg Fischer Ltd. |
| Asahi Yukizai Corporation |
| WIDOS Wilhelm Dommer Söhne GmbH |
| McElroy Manufacturing, Inc. |
| Rothenberger AG |
| Caldertech |
| Dukane IAS, LLC |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese electrofusion control system manufacturing is compressing margin structures for European equipment assemblers while simultaneously expanding pricing flexibility for municipal procurement authorities in Southeast Asia. Utilization rates below 70% in Yangtze River Delta fabrication clusters are forcing suppliers to absorb heater plate machining cost inflation rather than pass through to buyers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in plastic pipe jointing equipment. Price differentiation rests on certification grade (ISO 9001 versus BIS tier) and after-sales service bundling intensity. Cost compression in standard-grade electrofusion units is intensifying because of East Asian foundry overcapacity for precision resistor coils. Municipal water authorities exhibit lowest price sensitivity due to infrastructure bank financing availability, while mid-sized agricultural contractors in India demonstrate highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for electrofusion wire coil procurement. Geographic supply concentration centers on China for precision resistor manufacturing, Germany for heater plate machining equipment, and Switzerland for high-purity PP jointing systems. Raw material dependencies draw from specialty steel alloys for heater plates, copper winding wire for electrofusion coils, and ceramic coatings for surface finishing. Single-source vulnerability in East Asian foundry capacity for precision resistors creates input bottlenecks for European equipment assemblers. Distribution runs through rental channel partners in North America, direct municipal tender relationships in Europe, and state-backed procurement consortia in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across this market as digital welding traceability mandates splinter demand between integrated software-hardware providers and legacy equipment retrofitters. Municipal procurement workflows are fragmenting toward subscription-based access models that favor vendors with financing partnerships.
For Market Incumbents: Build switching-cost moats through embedded data-logging modules that lock municipal buyers into recurring software revenue streams. Deepen backward integration into heater plate machining capacity to defend margin position against Chinese fabrication cost advantages. Prioritize certification investment for China's MEE leakage standards and India's BIS mandates to filter emerging competitors from state tender eligibility. For New Entrants and Emerging Players: Pursue portable electrofusion specialization targeting Southeast Asian municipal tenders where skilled technician scarcity constrains project execution timelines. Target India's northern agricultural belt for HDPE irrigation network deployment with equipment-as-a-service financing models that circumvent upfront capital barriers for mid-sized contractors. Anchor go-to-market strategy through partnerships with provincial infrastructure banks underwriting subscription-based fusion machine access. For Investors and Strategic Acquirers: Capital is best deployed toward precision-machining specialists with captive heater plate production capabilities and existing software integration roadmaps. Long-term viability over the next decade hinges on compliance infrastructure ownership as digital traceability mandates propagate across national standards. Monitor electrofusion control system retrofitting velocity in Sichuan and Shandong provinces as the signal for China market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heater Plate Machining | Captive production of precision-machined heater plates with surface roughness below 3.2 micrometers defends margin structures against East Asian fabrication cost pressures. |
| Software-Enabled Data Logging Retrofit | Embedded barcode scanners and cloud-synced weld records hybridize equipment vendors into recurring revenue service providers for municipal traceability compliance. |
| Equipment-as-a-Service Financing Partnership | Subscription-based fusion machine access with bundled maintenance and recertification penetrates price-sensitive agricultural contractor segments in India. |
| Certification Investment for BIS and MEE Standards | Third-party testing infrastructure ownership filters uncertified competitors from state-backed tenders in India and China's gas distribution provinces. |
| Geographic Expansion into Southeast Asian Municipal Tenders | Remote welding capability reduces labor certification burdens in procurement zones confronting skilled technician scarcity. |
Research Methodology
Initial hypotheses were tested against primary input from municipal water authority procurement officers, fusion equipment maintenance directors, semiconductor fab construction project managers, and agricultural irrigation cooperative technical leads and refined through secondary validation. Primary fieldwork combined structured interviews with aftermarket service heads at rental channel operators and plant engineers at HDPE pipe extrusion facilities. Secondary sources drew from EPA Lead and Copper Rule Revision filings, China's MEE leakage standard enforcement records, India's BIS certification registries, and municipal infrastructure bank financing disclosures. Bottom-up equipment unit demand modeling was triangulated against top-down municipal capital expenditure projections.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework for volume and value outputs. Segmentation dimensions modeled encompassed material grade, joining technology, end-user industry, application type, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and infrastructure investment pipeline assessment. Industry-specific forecast inputs included certified welder scarcity indices in northern India and digital traceability mandate propagation timelines across China's provincial gas distribution networks.
Macroeconomic conditions sit as an overlay; deviation in infrastructure bank lending rates, agricultural commodity price cycles, or semiconductor capital expenditure sentiment would shift the trajectory for equipment procurement volumes. Forecasts reflect assumptions regarding regulatory enforcement continuity and certification standard harmonization velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
GCC PVC Pipes Market
Pipes and Tubes
FRP Pipes and Tanks Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Global Cured-In-Place Pipe Market
Pipes and Tubes
PVC Pipes Market
Pipes and Tubes
Industrial Draft Tube Crystallizer Market
Pipes and Tubes
GRE Pipes Market
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
India Process Piping Market
Pipes and Tubes
FRP Pipe Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market