
 Global Level Gauge Market | 2026-2036
Global Level Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Global Level Gauge Market Foresight
The gap between premium and commodity tiers is repositioning procurement patterns across industrial automation. Emerson Electric Co. leverages its Rosemount instrumentation platform to dominate high-accuracy radar applications in hazardous environments. ABB sustains competitive pressure through integrated digital twin offerings that bundle level sensing with asset management software. Endress+Hauser differentiates via its Heartbeat Technology diagnostics, which reduce unplanned downtime for process manufacturers.
A level gauge measures liquid or solid material height within vessels, tanks, or silos using mechanical, electronic, or electromagnetic principles, with typical accuracy ratings from ±1 mm to ±10 mm depending on technology class. Its primary purpose is enabling inventory control, process safety interlocks, and regulatory compliance in continuous or batch operations. Radar level gauges command the widest margin pools in oil refining applications where high-temperature hydrocarbon service demands corrosion-resistant waveguide designs. Ultrasonic variants occupy the fastest-expanding niche in municipal water treatment, driven by non-contact hygiene advantages and reduced maintenance cycles. Capacitance and float technologies retain entrenched positions in chemical processing, though their growth rates lag as facilities migrate toward microwave and laser-based alternatives.
ATEX directives from the European Commission, IECEx equipment certification schemes, and OSHA process safety management standards in the United States collectively elevate barrier-to-entry for uncertified suppliers while mandating redundant level monitoring in critical service. China's SAMR enforces GB standards for pressure-containing instruments that constrain import pathways for non-compliant hardware. Stakeholders must weigh certification portfolio breadth against regional manufacturing localization requirements when configuring their market entry and expansion priorities.
Market Dynamics
Refinery modernization mandates and ATEX compliance deadlines are compressing replacement cycles for mechanical float gauges across European chemical processing corridors, forcing capital allocation toward certified non-contact radar systems.
Growth Catalysts
- EU ATEX Directives:Hazardous area certification requirements mandate redundant level monitoring in hydrocarbon storage, accelerating gauge fleet upgrades at Rotterdam and Antwerp refining clusters.
- Industrial automation density:German process manufacturers deploy integrated level sensing within digital twin architectures to reduce unplanned downtime.
- Microwave radar migration:Corrosion-resistant waveguide designs displace capacitance probes in high-temperature sulfuric acid service.
Market Restraints
- Stainless steel input volatility:Waveguide fabrication depends on 316L and 317L alloy pricing, exposing margin pools to nickel market swings.
- Specialized sensor foundry concentration:High-frequency radar module production concentrates in South Korean and Japanese fabs, creating single-source vulnerability.
- Technical limitation in foam service:Ultrasonic and radar technologies suffer signal attenuation in heavy crude foam layers, preserving mechanical gauge incumbency.
Strategic Opportunities
- India municipal water infrastructure:Non-contact hygiene advantages position ultrasonic gauges for rapid deployment in Bangalore and Hyderabad treatment plant expansions.
- US OSHA process safety management:Redundant level interlock mandates create certified-system procurement pull at Gulf Coast petrochemical complexes.
- Edge-to-cloud convergence:Embedded AI diagnostics on radar transmitters enable predictive maintenance contracts displacing break-fix service models.
Industry Challenges
- IECEx certification timeline compression:Testing backlog at notified bodies delays product launches by 8-14 months.
- Legacy 4-20mA integration friction:Digital FOUNDATION Fieldbus and HART-IP protocols require gateway infrastructure at brownfield sites.
- RF engineering talent scarcity:80GHz radar design expertise concentrates among semiconductor veterans, constraining supplier expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Level Gauge Market |
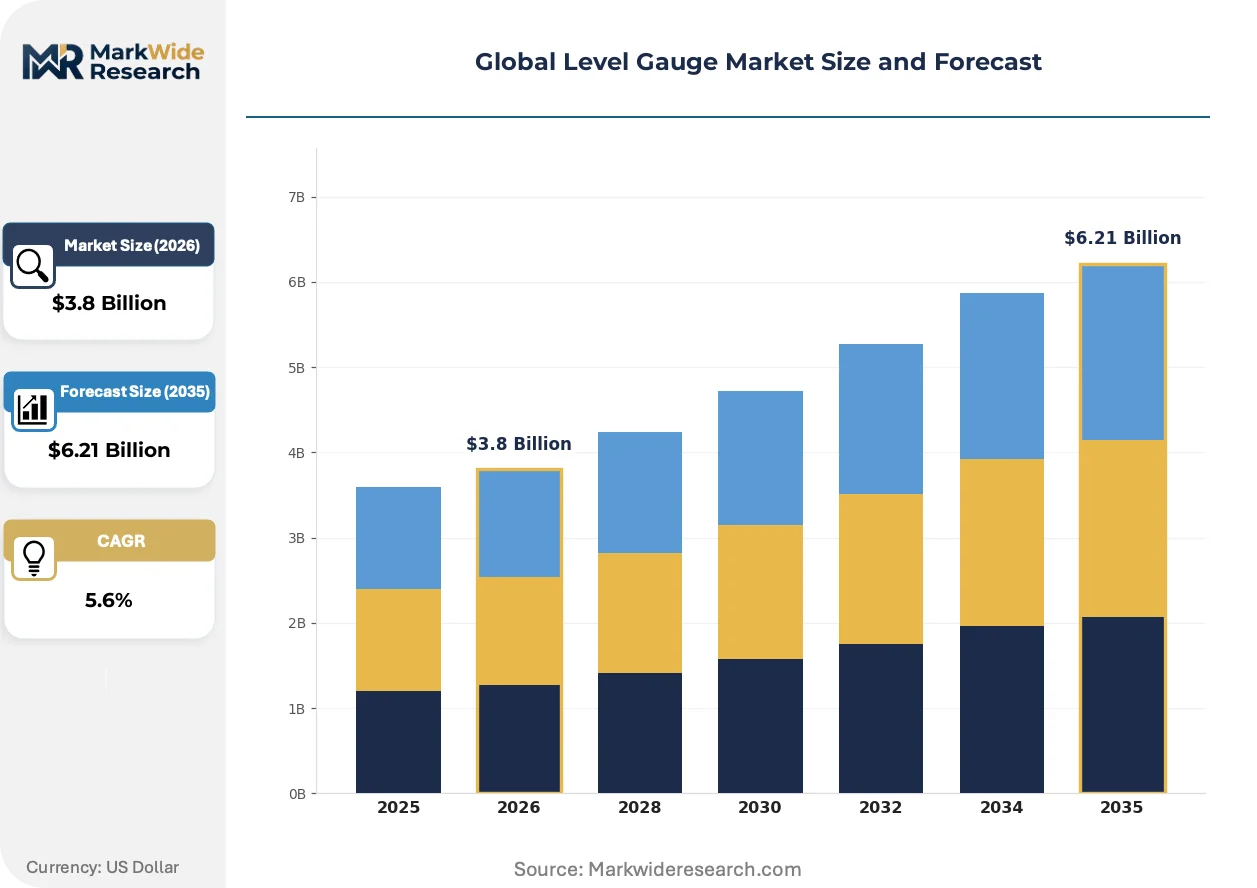
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Level Gauges, Ultrasonic Level Gauges, Capacitance Level Gauges, Float Level Gauges, Conductive Level Gauges Technology: Non-contact Measurement, Contact Measurement, Differential Pressure, Laser Level Gauging, Microwave Level Measurement Application: Chemical Processing, Oil Refining, Food & Beverage, Water Treatment, Power Generation End User: Petrochemical Plants, Municipal Water Facilities, Food Processing Units, Power Plants, Pulp & Paper Industries |
| Companies Covered | Emerson Electric Co., ABB, Siemens, Endress+Hauser, Honeywell International Inc., KROHNE, VEGA, Yokogawa Electric Corporation, AMETEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Level Gauge Market Shifts & Advancements
Sensor fusion architectures and embedded diagnostic intelligence are redefining how level instrumentation delivers value beyond raw measurement, compressing maintenance intervals and enabling outcome-based service relationships.
Frequency-modulated continuous-wave radar is automating level measurement in agitated tank applications where mechanical gauges previously required scheduled replacement. Pharmaceutical manufacturers in Switzerland and Germany adopt 120GHz units for bioreactor monitoring, eliminating probe fouling risks. This frequency migration is automating the shift from intrusive to non-contact architectures across sterile process environments.
REACH substance restrictions on perfluorinated compounds constrain sealing elastomer selection for submersible pressure transmitters. European gauge suppliers reformulate wetted materials to maintain chemical resistance without restricted fluoroelastomers. German chemical processors now specify material compliance certificates upstream of procurement decisions, filtering supplier pools.
Asset performance contracts now bundle hardware, calibration, and predictive analytics into single-line subscriptions. Municipal water utilities in the Netherlands and Denmark favor this arrangement over capital purchase models. Channel intermediaries in Northern Europe respond by building in-house metrology service capabilities rather than pure distribution margins.
Global Level Gauge Market Segmentation
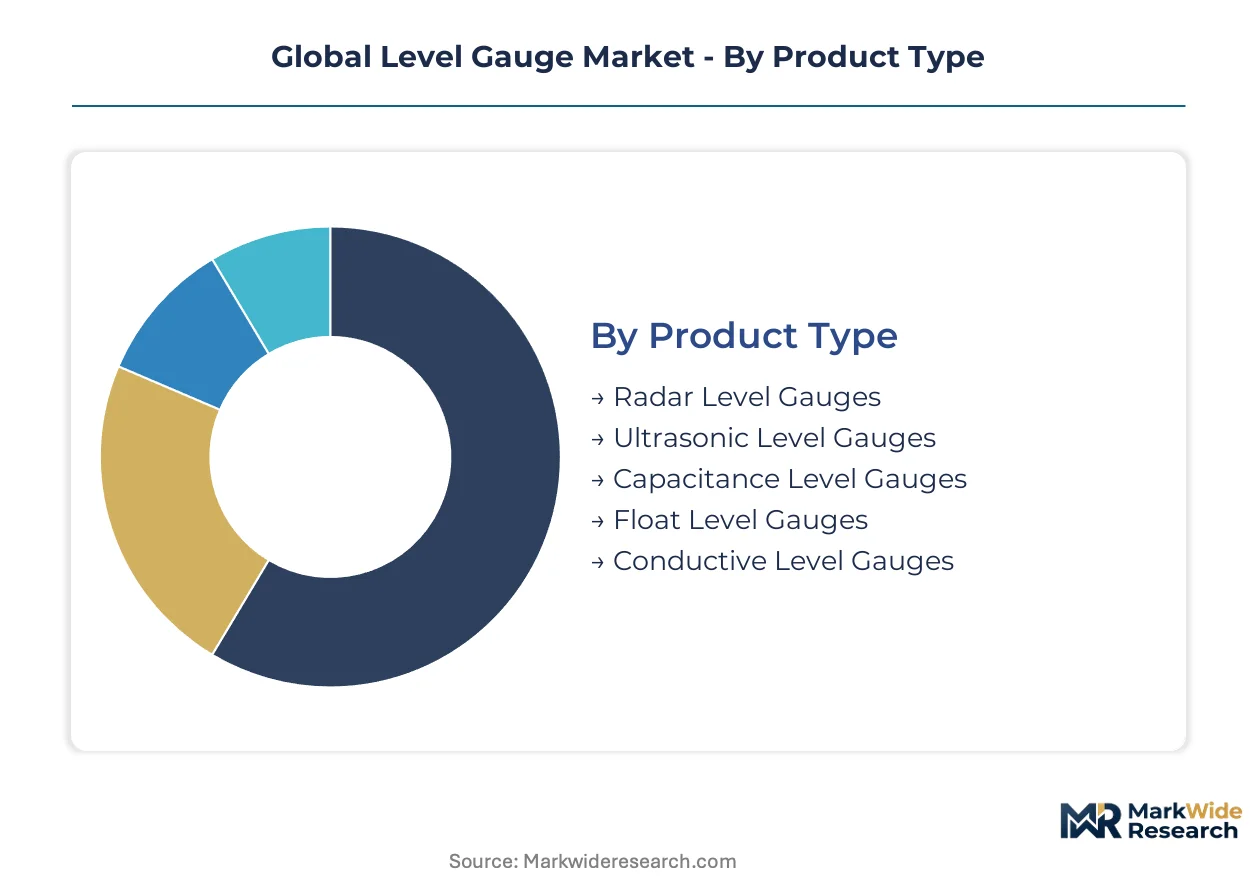
Level gauge procurement patterns diverge sharply across product architectures, measurement principles, and operational environments. Each segmentation axis reveals distinct margin structures, certification requirements, and replacement cycle dynamics that reshape supplier positioning strategies.
Product Type:
The customization-to-standardization spectrum stretches from application-engineered radar systems to commodity float mechanisms, with waveguide complexity and hazardous area certification driving tier boundaries.
- Radar Level Gauges:Frequency-modulated continuous-wave transmitters with corrosion-resistant waveguide assemblies dominate high-temperature hydrocarbon service. Refinery clusters in Rotterdam and Antwerp mandate ATEX-certified units for redundant tank monitoring, compressing replacement cycles for legacy mechanical alternatives.
- Ultrasonic Level Gauges:Piezoelectric transducer arrays emit acoustic pulses for non-contact measurement in hygiene-critical environments. Municipal water treatment expansions in Bangalore and Hyderabad favor these units for reduced maintenance cycles and contamination elimination.
- Capacitance Level Gauges:Dielectric-sensing probes retain entrenched positions in chemical processing despite microwave migration pressure.
- Float Level Gauges:Mechanical displacement devices face accelerated obsolescence from ATEX compliance deadlines across European corridors.
- Conductive Level Gauges:Electrode-based point-level detection serves conductive liquid applications with minimal electronics complexity.
Most installed capacity flows through radar level gauges. Expansion is steepest in ultrasonic variants.
Technology:
Cost tier stratification separates capital-intensive semiconductor-dependent architectures from mature electromechanical implementations.
- Non-contact Measurement:Radar and laser-based systems eliminate probe fouling risks through free-space signal propagation. Pharmaceutical bioreactor monitoring in Switzerland and Germany drives 120GHz frequency adoption for sterile process environments.
- Contact Measurement:Submersible pressure transmitters and capacitance probes deliver proven reliability in benign chemical service. REACH substance restrictions on perfluorinated compounds now constrain sealing elastomer selection, forcing material reformulation by European suppliers.
- Differential Pressure:Hydrostatic calculation via impulse line configurations persists in legacy tank farm infrastructure.
- Laser Level Gauging:Time-of-flight optical systems penetrate dusty silo environments where acoustic attenuation limits ultrasonic performance.
- Microwave Level Measurement:Guided-wave radar variants tolerate foam layer interference that defeats free-space alternatives in heavy crude storage.
Non-contact architectures command premium positioning. Contact measurement retains volume dominance in brownfield chemical processing.
Application:
Customer type concentration varies by operational criticality, with batch pharmaceutical operations demanding higher sensor density than continuous power generation.
- Chemical Processing:Corrosive media exposure and safety interlock mandates drive multi-technology redundancy. German facilities integrate level sensing within digital twin architectures to compress unplanned downtime.
- Oil Refining:High-temperature hydrocarbon service and ATEX compliance requirements specify waveguide-rated radar systems. Gulf Coast petrochemical complexes face OSHA process safety management mandates for redundant level monitoring.
- Food & Beverage:Hygiene regulations and CIP/SIP compatibility constrain material selection and sealing geometry.
- Water Treatment:Non-contact advantages position ultrasonic gauges for rapid deployment in municipal infrastructure expansion.
- Power Generation:Boiler drum level measurement demands fail-safe mechanical backup to electronic primary systems.
Chemical processing absorbs the deepest sensor penetration per vessel. Water treatment represents the fastest volume expansion trajectory.
End User:
Geographic procurement concentration clusters around regulatory enforcement intensity and industrial automation density.
- Petrochemical Plants:Integrated refining-petrochemical complexes in Rotterdam, Antwerp, and Houston deploy certified radar fleets under ATEX and OSHA parallel mandates. Redundant level interlocks protect high-inventory hydrocarbon storage.
- Municipal Water Facilities:Dutch and Danish utilities favor asset performance contracts bundling hardware, calibration, and predictive analytics over capital purchase models.
- Food Processing Units:Swiss and German pharmaceutical manufacturers specify 120GHz radar for bioreactor monitoring to eliminate probe fouling.
- Power Plants:Boiler feedwater and cooling tower applications balance electronic precision with mechanical backup requirements.
- Pulp & Paper Industries:Black liquor recovery boilers and chip silos present foam, dust, and chemical exposure challenges.
Petrochemical plants concentrate the highest unit value procurement. Municipal water facilities are expanding most quickly through subscription service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent concentrates in German industrial corridors and Japanese semiconductor hubs, anchoring high-frequency radar design capabilities. This workforce distribution shapes regional procurement patterns and certification specialization across the level gauge supply base.
Germany
Industrial automation density in chemical processing drives sustained demand for integrated level sensing systems. The country's national regulator enforces ATEX compliance deadlines that compress replacement cycles for mechanical float gauges. Refinery modernization programs in the North Rhine-Westphalia corridor accelerate certified non-contact radar procurement.
United States
OSHA process safety management mandates create procurement pull for redundant level monitoring at Gulf Coast petrochemical complexes. The Environmental Protection Agency coordinates with process safety regulators to enforce tank farm monitoring standards. Houston-area integrated refining-petrochemical complexes deploy certified radar fleets under parallel federal and state requirements.
China
SAMR-enforced GB standards for pressure-containing instruments constrain import pathways and elevate local certification requirements. The Ministry of Industry and Information Technology promotes domestic sensor manufacturing through industrial policy support. Yangtze River Delta chemical processors balance imported high-accuracy systems with locally certified alternatives.
India
Municipal water infrastructure expansion in Bangalore and Hyderabad positions ultrasonic gauges for rapid deployment. The Central Electricity Authority and Bureau of Indian Standards coordinate instrumentation standards for critical infrastructure. Western Maharashtra industrial corridors integrate level sensing within broader automation upgrades at process manufacturing facilities.
Netherlands
Rotterdam refining clusters mandate ATEX-certified redundant tank monitoring under EU hazardous area directives. The country's national environmental agency enforces strict emissions monitoring that elevates precision instrumentation requirements. Dutch municipal water utilities pioneer asset performance contracts bundling hardware, calibration, and predictive analytics.
Global Level Gauge Market Competitive Landscape
Top-tier vendors anchor premium-tier radar and integrated digital twin offerings, while mid-tier specialists occupy ultrasonic and capacitance niches. The vendor base stratifies across three tiers: diversified industrial conglomerates with instrumentation platforms, dedicated measurement specialists with vertical technology depth, and regional fabricators serving price-sensitive brownfield replacement demand. Two strategic archetypes dominate: certification portfolio aggregators capturing hazardous environment mandates, and service-integrated providers monetizing predictive maintenance contracts. Competitive moves concentrate on geographic certification expansion and outcome-based service model transitions.
Among diversified industrial conglomerates, Emerson Electric Co. and ABB exemplify platform-scale positioning, while Endress+Hauser represents dedicated measurement specialization. Emerson anchors high-accuracy radar applications through its Rosemount instrumentation lineage. ABB occupies a position emphasizing integrated digital twin architectures that bundle sensing with asset management software. Endress+Hauser exemplifies diagnostic differentiation through embedded intelligence offerings that reduce unplanned downtime.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| ABB |
| Siemens |
| Endress+Hauser |
| Honeywell International Inc. |
| KROHNE |
| VEGA |
| Yokogawa Electric Corporation |
| AMETEK |
| Others |
Supply & Pricing Matrix
EU ATEX directive compliance deadlines are compressing procurement timelines for certified radar systems, forcing suppliers to absorb expedited testing costs while buyers demand bundled service packages that shift revenue toward recurring contracts.
Pricing Analysis
The bundled-versus-unbundled service split now defines transaction structures across the level gauge market. Asset performance contracts bundling hardware, calibration, and predictive analytics are displacing capital purchase models among Dutch and Danish municipal utilities. Price differentiation centers on ATEX/IECEx certification tier and after-sales service integration. Cost compression in commodity float gauge tiers is intensifying as European facilities accelerate microwave radar migration. Municipal water facilities exhibit highest price sensitivity due to budget constraints, while Rotterdam and Antwerp refining clusters show lowest sensitivity given safety-critical mandates.
Supply Chain Analysis
RF engineering talent scarcity in German industrial corridors and Japanese semiconductor hubs constrains high-frequency radar module expansion. Waveguide fabrication draws from South Korean and Japanese foundries for 80GHz semiconductor components, while 316L and 317L stainless steel alloy supply rests on nickel market volatility. Single-source vulnerability in specialized sensor foundries creates structural risk. Distribution runs through authorized instrumentation distributors building in-house metrology capabilities rather than pure resale margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The level gauge market represents a late-cycle quality story as process manufacturers prioritize certified non-contact architectures over commodity mechanical alternatives, with ATEX compliance deadlines accelerating specification upgrades toward premium radar tiers.
For Market Incumbents: Cement certification portfolio breadth across ATEX, IECEx, and OSHA jurisdictions to defend against emerging Asian suppliers with narrower geographic coverage. Deepen backward integration into 80GHz radar semiconductor design to reduce South Korean and Japanese foundry dependency. Prioritize embedded AI diagnostics development to capture predictive maintenance contract expansion. For New Entrants and Emerging Players: Launch via asset performance contract models targeting Indian municipal water infrastructure in Bangalore and Hyderabad, where capital constraints favor subscription structures over upfront purchase. Exploit ultrasonic gauge white space in hygiene-critical food and beverage applications. Pursue partnership pathways with European channel intermediaries building service capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with dedicated measurement specialists possessing 120GHz frequency design expertise and Heartbeat Technology-class diagnostic platforms. Long-term viability favors vendors with integrated digital twin software bundling. Monitor IECEx certification timeline compression at notified bodies as inflection indicator for supply-constrained premium tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | Broad ATEX/IECEx coverage captures Rotterdam and Antwerp refinery procurement mandates. |
| Embedded AI Diagnostics Development | Predictive maintenance contracts displace break-fix service models at German chemical processors. |
| Backward Integration into RF Semiconductors | In-house 80GHz design reduces South Korean and Japanese foundry concentration risk. |
| Asset Performance Contract Launch | Subscription bundling aligns with Dutch and Danish municipal utility procurement preferences. |
| Edge-to-Cloud Platform Integration | Digital twin architectures compress unplanned downtime for process manufacturers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged plant engineers at Rotterdam and Antwerp refining clusters, procurement leads at German chemical processors, municipal water utility operations managers in the Netherlands and Denmark, and aftermarket service heads at European instrumentation distributors. Secondary validation drew from IECEx certification databases, ATEX directive implementation reports, SEC filings of diversified industrial conglomerates, and customs records of radar module trade flows. Bottom-up unit demand estimates triangulated against top-down industrial automation spending benchmarks.
Historical reference periods anchored the projection horizon through verified replacement cycle data and certification deadline impacts. The analytical framework modeled demand across technology type, application environment, end-user concentration, and regional regulatory cluster. CAGRs derived from segment-level growth rate reconciliation against macro industrial automation indicators. Forecast inputs incorporated stainless steel alloy price volatility coefficients and semiconductor foundry capacity utilization trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel market disruption or IECEx testing backlog extension scenarios. Projections reflect assumptions regarding ATEX compliance deadline adherence and microwave radar migration pace. Material deviation in alloy input costs or certification body processing timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Industrial Safety Valves Market
Valves
Global Valves in Chemical Market
Valves
Manual Control Valve Market
Valves
Global Gas Pressure Regulator Market
Valves
Axial and Radial Seals Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Fluid Power Cylinder Market
Valves
Pipeline Strainers Market
Valves
Butterfly Valves Market
Valves
Flanges Market
Valves
Hydraulic Valves Market
Valves
Cryogenic Valve Market
Valves
Industrial Valves and Actuators Market
Valves
Pressure Gauge Market
Valves
North America Butterfly Valve Market
Valves
Refrigeration Valves Market