
 Self-Monitoring Blood Glucose Devices Market | 2026-2036
Self-Monitoring Blood Glucose Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Monitoring Blood Glucose Devices Market Analysis
The EU MDR is realigning the cost-of-entry calculus for glucose monitoring devices across European markets. F. Hoffmann-La Roche leverages its diagnostic heritage to sustain premium positioning in electrochemical strip systems. Abbott Laboratories anchors its competitive stance through integrated continuous monitoring platforms that reduce calibration burdens.
Self-monitoring blood glucose devices comprise portable analytical instruments that measure capillary glucose concentration via electrochemical or optical transduction, typically requiring sample volumes under one microliter and producing results within five seconds for real-time metabolic management. Continuous glucose monitors and smart meters command expanding share as patients seek reduced fingerstick frequency, while standard meters occupy the value tier where price sensitivity dominates procurement decisions. Electrochemical technology leads unit shipments, though optical methods gain traction in non-invasive research prototypes.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape device approval timelines, while ISO 15197 accuracy standards govern strip performance thresholds in competitive tenders. China's NMPA now requires in-country clinical validation for imported glucose monitors, extending registration cycles for multinational suppliers. Stakeholders must monitor reimbursement compression in public health systems against the premium commanded by smartphone-integrated monitoring ecosystems.
Market Dynamics
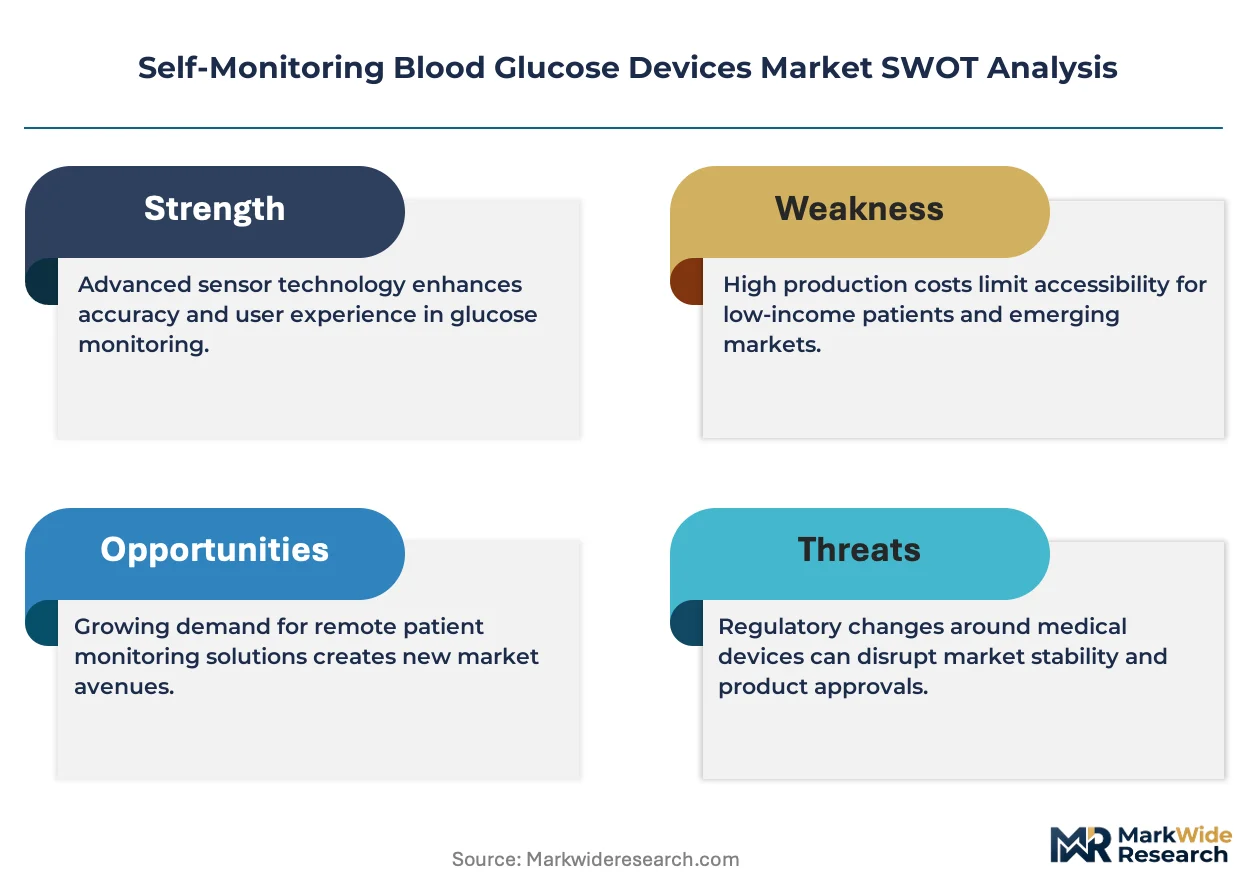
EU MDR recertification timelines and FDA 510(k) pathway modifications are compressing product launch windows while simultaneously elevating compliance expenditure for glucose monitoring manufacturers.
Growth Catalysts
- Type 2 diabetes prevalence in home care:Patients managing chronic metabolic conditions outside clinical settings require frequent glucose data, expanding addressable demand for portable monitoring systems.
- ISO 15197 accuracy standards:Stringent performance thresholds for strip electrochemical systems drive replacement cycles as older devices fail to meet updated precision requirements.
- Continuous glucose monitor miniaturization:Sensor form factor reductions enable longer wear periods and improved patient adherence, particularly among pediatric and elderly populations.
Market Restraints
- Precious metal electrode costs:Palladium and gold price volatility in electrochemical strip manufacturing compresses margins for standard meter producers.
- Supply concentration in Asian substrate production:Polymer membrane and enzyme reagent sourcing clusters create single-point vulnerability for strip manufacturers.
- Non-invasive optical prototype limitations:Spectroscopic glucose detection through skin remains clinically unreliable, blocking substitution of fingerstick methods.
Strategic Opportunities
- Smartphone-integrated monitoring ecosystems:Bluetooth-enabled meters paired with insulin dosing apps create sticky patient platforms and recurring revenue streams.
- China NMPA in-country clinical validation:Localized trial requirements, while burdensome, create moats against low-cost competitors lacking regulatory infrastructure.
- Artificial intelligence and predictive analytics convergence:Pattern recognition algorithms applied to continuous glucose data enable hypoglycemic event forecasting.
Industry Challenges
- Biocompatibility engineering talent scarcity:Specialized expertise in enzyme stabilization and interference rejection limits R&D throughput for next-generation strips.
- Cleanroom manufacturing capex intensity:ISO 13485-compliant production facilities for sterile sensor assembly demand substantial capital deployment.
- Legacy health record integration complexity:Proprietary data formats from established meter brands obstruct seamless electronic health record connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Monitoring Blood Glucose Devices Market |
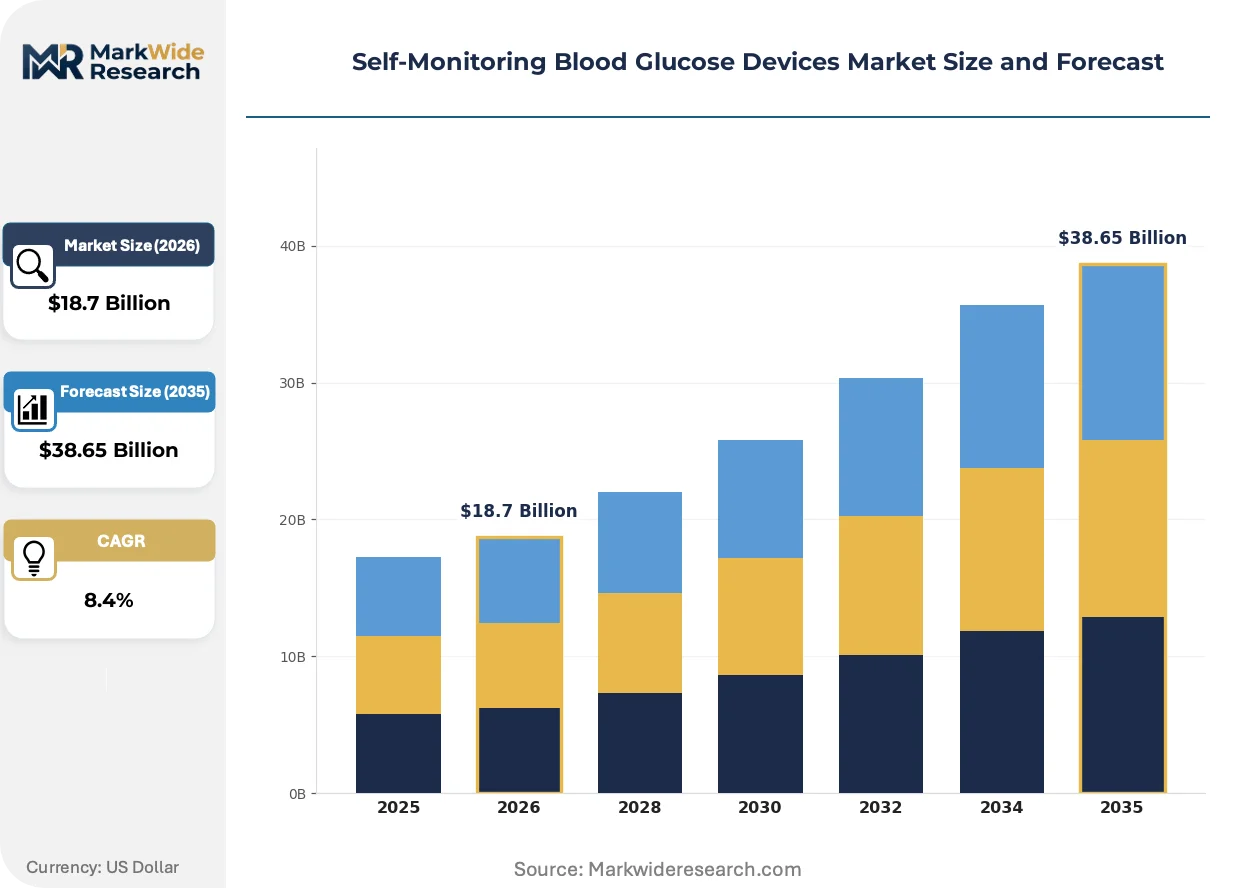
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Meters, Continuous Glucose Monitors, Smart Meters, Integrated Systems Application: Diabetes Management, Home Care, Hospital Use, Preventive Care End User: Patients, Healthcare Professionals, Clinics, Laboratories Technology: Electrochemical, Optical, Enzymatic, Non-Invasive |
| Companies Covered | F. Hoffmann-La Roche, Abbott Laboratories, Ascensia Diabetes Care Holdings, LifeScan, Sinocare, Arkray, Trividia Health, Bionime, AgaMatrix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Monitoring Blood Glucose Devices Market Emerging Trajectories
Sensor chemistry advances and algorithmic interpretation capabilities are compressing the functional gap between intermittent fingerstick monitors and continuous glucose systems.
Factory-calibrated continuous glucose monitors eliminate patient-driven calibration routines through stabilized sensor chemistry and embedded reference algorithms. Type 1 diabetes patients and intensive insulin users adopt these systems fastest, reducing daily intervention burdens. This convergence is electrifying competitive pressure on traditional meter-strip economics as reimbursement pools shift toward seamless data capture.
EU MDR technical documentation requirements now mandate clinical performance studies for all glucose monitoring device renewals, extending approval timelines substantially. Manufacturers face expanded notified body scrutiny of biocompatibility and software validation files. Small and mid-sized suppliers in Germany and France are consolidating or exiting as compliance costs outstrip revenue from legacy product lines.
Direct-to-consumer subscription models for continuous glucose sensors bypass traditional pharmacy and durable medical equipment distribution channels. Tech-savvy patients in urban United States markets purchase hardware outright while paying recurring fees for sensor replenishment. This channel disintermediation forces established manufacturers to rebuild commercial infrastructure around patient relationship management rather than wholesale account servicing.
Self-Monitoring Blood Glucose Devices Market Segmentation
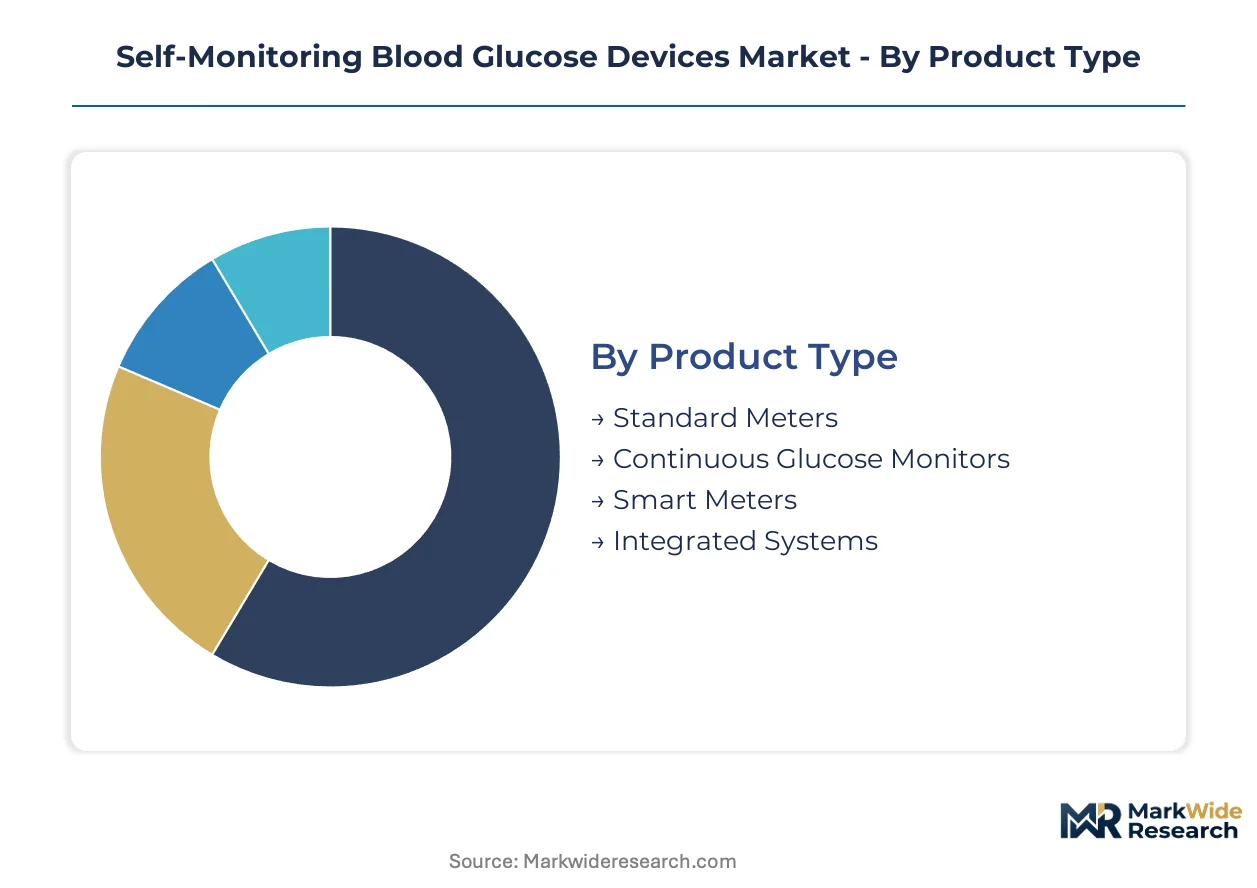
Product architecture in glucose monitoring determines reimbursement eligibility, regulatory pathway complexity, and manufacturing capital requirements. Segment boundaries blur as electrochemical strip systems integrate Bluetooth connectivity and continuous monitors adopt factory-calibrated sensors.
Product Type:
Capital intensity varies sharply across this category, with cleanroom sensor fabrication demanding substantially higher upfront investment than electrochemical strip assembly.
- Continuous Glucose Monitors:Factory-calibrated sensors with embedded algorithms eliminate patient calibration routines. Demand concentrates among Type 1 diabetes patients in Germany and the United States as reimbursement frameworks expand coverage for real-time data systems.
- Smart Meters:Bluetooth-enabled handheld devices pair with smartphone applications for pattern recognition and insulin dosing recommendations. Home care settings in China drive volume as NMPA registration pathways mature for connected devices.
- Standard Meters:Electrochemical strip-based systems with minimal connectivity features serve price-sensitive procurement channels.
- Integrated Systems:Combined pump-monitor platforms with automated insulin delivery capabilities target intensive insulin users.
Continuous glucose monitors absorb the bulk of installed capacity; smart meters are expanding most quickly.
Application:
Reimbursement tiering separates institutional procurement from patient out-of-pocket expenditure, with hospital tenders favoring accuracy-certified systems and home care emphasizing convenience features.
- Home Care:Patients managing chronic conditions outside clinical settings require frequent glucose data with minimal intervention burden. United States Medicare and German statutory health insurance reimbursement decisions shape device selection criteria.
- Diabetes Management:Intensive insulin therapy protocols demand precise, time-stamped glucose readings for dosing calculations.
- Hospital Use:Point-of-care testing in acute settings prioritizes rapid turnaround and electronic health record integration.
- Preventive Care:Prediabetes screening and lifestyle intervention programs employ lower-cost monitoring for metabolic risk assessment.
Home care captures the dominant share of unit volume; preventive care applications are climbing the fastest.
End User:
Procurement authority fragmentation creates parallel sales channels, with patients selecting retail devices while healthcare institutions negotiate volume contracts for clinical-grade systems.
- Patients:Direct consumers prioritize ease of use, data visualization, and insurance coverage compatibility. Urban United States markets show strongest adoption of subscription-based sensor replenishment models.
- Healthcare Professionals:Physicians and diabetes educators influence device selection through prescribing patterns and formulary recommendations.
- Clinics:Outpatient facilities balance accuracy requirements against operational throughput for high-volume glucose screening.
- Laboratories:Centralized testing operations utilize automated analyzers with traceable calibration chains for diagnostic confirmation.
Patients account for the majority of procurement decisions; clinics are gaining share fastest.
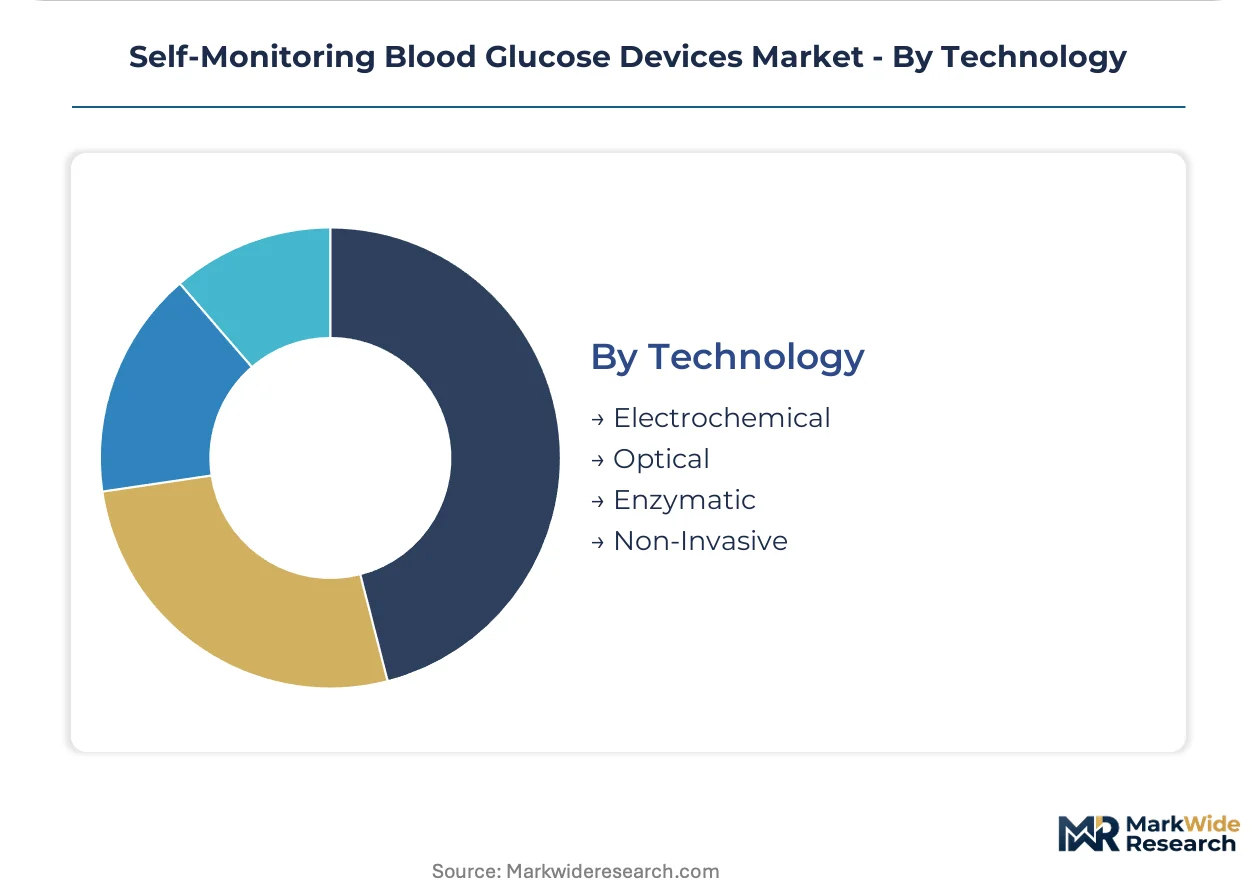
Technology:
Intellectual property concentration in enzyme stabilization and interference rejection chemistry shapes competitive moats, with electrochemical methods dominating commercial shipments while optical approaches remain research-stage.
- Electrochemical:Glucose oxidase or dehydrogenase reactions on palladium or gold electrodes generate current proportional to analyte concentration. ISO 15197 accuracy standards govern strip performance in competitive tenders across European and North American markets.
- Enzymatic:Modified enzyme formulations reduce oxygen dependence and hematocrit interference for improved precision.
- Optical:Spectroscopic detection methods through interstitial fluid or dermal layers remain clinically unreliable for regulatory approval.
- Non-Invasive:Raman spectroscopy and near-infrared approaches continue prototype development without commercial validation.
Electrochemical technology holds the dominant installed base; enzymatic advances are gaining traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Shanghai concentrate glucose monitor manufacturing capacity for Asia-Pacific distribution. These special economic zones offer tariff exemptions on imported sensor substrates and streamlined NMPA registration pathways.
United States
Medicare reimbursement expansion for continuous glucose monitors drives patient adoption in home care settings. FDA 510(k) clearance timelines average 90-120 days for predicate device pathways. Minneapolis and San Diego host dense clusters of diabetes technology R&D operations.
Germany
Statutory health insurance covers factory-calibrated sensors for Type 1 diabetes patients, accelerating continuous monitor penetration. EU MDR notified body scrutiny extends recertification cycles for legacy strip-based systems. Mannheim and Hamburg anchor electrochemical strip manufacturing corridors.
China
NMPA in-country clinical validation requirements filter low-cost competitors lacking trial infrastructure. Provincial procurement tenders in Jiangsu and Zhejiang prioritize connected devices with data export capabilities. Hangzhou and Shenzhen dominate smart meter assembly and Bluetooth module integration.
Japan
PMDA approval standards emphasize interference rejection chemistry for aging populations with polypharmacy profiles. METI subsidies support non-invasive glucose detection research consortia. Osaka and Tokyo metropolitan areas concentrate precision sensor fabrication operations.
India
CDSCO medical device rules now classify glucose monitors as Class C devices, requiring quality management system audits. Price-controlled tendering in Tamil Nadu and Karnataka favors standard meters over premium continuous systems. Hyderabad and Ahmedabad emerge as contract manufacturing hubs for strip enzyme reagent production.
Self-Monitoring Blood Glucose Devices Market Vendor Landscape
Swiss and German producers anchor the premium diagnostic tier; Chinese specialists hold dominant positions in high-volume strip manufacturing. The vendor base organizes around three strategic archetypes: integrated healthcare conglomerates with diagnostic heritage, pure-play diabetes technology firms, and contract manufacturers serving private-label brands. Competitive moves concentrate on M&A for sensor chemistry IP and strategic partnerships with insulin pump manufacturers for closed-loop integration.
Among Swiss healthcare conglomerates, F. Hoffmann-La Roche exemplifies the premium electrochemical tier through its diagnostic equipment lineage. Abbott Laboratories and Ascensia Diabetes Care Holdings occupy positions within the integrated monitoring ecosystem segment, representing divergent approaches to patient data platform architecture. These three entities anchor competitive positioning across reimbursement-tiered markets.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Abbott Laboratories |
| Ascensia Diabetes Care Holdings |
| LifeScan |
| Sinocare |
| Arkray |
| Trividia Health |
| Bionime |
| AgaMatrix |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up diagnostic specialists have consolidated electrochemical strip manufacturing in Germany and China, tightening supply discipline and preserving premium pricing tiers for ISO 15197-certified systems while compressing margins for uncertified competitors.
Pricing Analysis
Short lead-time premiums of 15-20% apply to factory-calibrated continuous glucose sensors for Type 1 diabetes patients in German statutory health insurance channels, while spot inventory of standard meters trades at discounts in Indian price-controlled tenders. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-integrated smart meters from basic electrochemical systems and uncertified private-label strips. Pricing pressure stems from palladium electrode cost volatility and reimbursement compression in United States Medicare channels. Home care patients in China exhibit highest price sensitivity; intensive insulin users in Germany show lowest sensitivity due to comprehensive coverage.
Supply Chain Analysis
Freight cost differentials of 8-12% separate Asian substrate shipments from European final assembly, concentrating margin pressure on manufacturers lacking regional production footprints. Supply concentrates in China for polymer membrane and enzyme reagent production, Germany for precision electrode fabrication, and the United States for algorithm development and software validation. Raw material dependencies include palladium and gold for electrochemical strips, glucose oxidase enzymes for sensor chemistry, and medical-grade polymers for sensor housings. Single-source vulnerability in Asian enzyme reagent supply creates disruption risk. Distribution runs through durable medical equipment channels for continuous monitors and retail pharmacy for standard meters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom manufacturing capacity for sterile sensor assembly operates at effective utilization above 85% across major production clusters, propping pricing discipline for factory-calibrated systems as demand outstrips qualified supply.
For Market Incumbents: Anticipate margin compression in standard meter segments from Chinese low-cost entrants by accelerating backward integration into enzyme reagent production and securing long-term palladium supply agreements. Defensive consolidation of notified body relationships under EU MDR recertification timelines preserves premium positioning. Prioritize R&D investment in biocompatibility engineering talent to maintain sensor chemistry moats against optical prototype challengers. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription models in urban United States markets, bypassing entrenched pharmacy distribution relationships that incumbent manufacturers control. Target preventive care applications for prediabetes screening as the most penetrable segment with lower regulatory barriers and price-sensitive procurement. Pursue white-label manufacturing partnerships with established Chinese assembly operations to achieve NMPA registration without captive clinical trial infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized German strip manufacturers facing EU MDR compliance cost overruns, particularly those holding ISO 15197 certification and established hospital system contracts. Long-term viability over the next decade hinges on successful pivot from transactional meter sales to recurring sensor revenue models. Watch for FDA 510(k) clearance acceleration for factory-calibrated systems as the inflection signal indicating reimbursement pool migration toward continuous monitoring platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortens approval timelines for predicate device pathways in competitive United States reimbursement channels. |
| CE Marking Pathway Investment | Navigates EU MDR technical documentation requirements for glucose monitoring device renewals. |
| Hospital System Partnership | Secures formulary placement for accuracy-certified systems in institutional procurement tenders. |
| Software Companion Development | Enables Bluetooth-enabled meter integration with insulin dosing apps for sticky patient platforms. |
| Reimbursement Strategy Execution | Expands Medicare coverage for continuous glucose monitors in United States home care settings. |
Methodological Framework
Multi-period observation of NMPA registration timelines, EU MDR recertification cycles, and Medicare reimbursement decisions anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and diabetes technology R&D directors. Secondary validation drew from FDA 510(k) filings, CMS Medicare coverage determinations, NMPA approval databases, and ISO 15197 certification records. Bottom-up shipment estimates by product tier triangulated against top-down expenditure flows from national health accounts.
Input-output matrices modeled unit demand across continuous glucose monitors, smart meters, standard meters, and integrated systems against supply capacity for cleanroom sensor fabrication and electrochemical strip assembly. Segmentation dimensions included product architecture, application setting, end-user procurement authority, and technology platform. CAGRs were derived from regression analysis of historical penetration rates against diabetes prevalence projections and reimbursement policy trajectories. Forecast inputs incorporated sensor miniaturization cost curves and biocompatibility engineering labor scarcity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of abrupt palladium price spikes or accelerated FDA breakthrough device designation for non-invasive optical prototypes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Global Insulin Infusion Pumps Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Hyperinsulinemia Hypoglycaemia Treatment Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market