
 Blockchain in BFSI Market | 2026-2036
Blockchain in BFSI Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain in BFSI Market Intelligence
Project finance for consortium blockchain infrastructure is tilting competitive advantage toward technology vendors with balance-sheet capacity to underwrite multi-year deployments. IBM Corporation leverages its hybrid cloud architecture to anchor enterprise blockchain engagements across capital markets. Microsoft Corporation sustains platform differentiation through Azure-based confidential computing integrations that appeal to regulated financial institutions. R3 competes through Corda specialization in trade finance workflows, occupying a defensible niche among correspondent banks.
Blockchain in BFSI denotes cryptographically linked distributed ledgers maintaining immutable transaction records across permissioned or permissionless node networks, typically employing consensus mechanisms such as proof-of-stake or Byzantine fault tolerance with throughput thresholds exceeding 1,000 transactions per second for enterprise deployments. The technology's primary commercial purpose centers on eliminating reconciliation latency, counterparty risk, and manual settlement friction in multi-party financial workflows. Payment processing applications now lead deployment value as real-time gross settlement systems migrate from legacy messaging protocols to programmable ledger infrastructure. Consortium blockchain deployments represent the fastest-expanding configuration, capturing margin pools from institutions requiring shared governance without full public network exposure. Identity management segments remain comparatively mature, with established vendors extracting maintenance revenues from early KYC-ledger pilots.
The US SEC mandates climate-risk and custody disclosures that shape how BFSI institutions evaluate blockchain audit trails, while the EU's MiCA framework imposes reserve-backing and operational-resilience standards on payment-token issuers. Singapore's MAS and Japan's FSA have each issued stablecoin licensing regimes that directly determine market-access eligibility for blockchain service providers. Stakeholders must monitor how fragmented supervisory approaches to smart-contract liability and node-operator accountability evolve across these jurisdictions.
Market Dynamics
Enterprise blockchain infrastructure is migrating from experimental pilots to production-grade settlement networks as real-time gross settlement requirements compress legacy messaging latency from days to seconds. This structural shift forces institutions to choose between consortium governance models and fully decentralized architectures.
Growth Catalysts
- MiCA Framework:The EU's Markets in Crypto-Assets regulation mandates auditable reserve-backing for payment tokens, compelling banks to deploy compliant ledger infrastructure.
- Tokenized Deposits:Singapore's MAS-licensed wholesale settlement networks demonstrate programmable money clearing at scale, attracting correspondent banking volume.
- Confidential Computing:Azure-based secure enclaves enable regulated institutions to process sensitive transaction data without exposing plaintext to node operators.
Market Restraints
- Interoperability Fragmentation:Absence of universal cross-chain messaging standards forces institutions to maintain redundant infrastructure across Ethereum, Hyperledger Fabric, and Corda networks.
- Specialized Talent Scarcity:Smart contract auditors and zero-knowledge proof engineers command compensation premiums that inflate deployment budgets by 40-60%.
- Energy Input Volatility:Proof-of-stake validation still requires substantial computational infrastructure, exposing operators to data center power cost fluctuations.
Strategic Opportunities
- Trade Finance Digitization:Letter-of-credit workflows on Corda reduce document processing from weeks to hours, unlocking working capital for commodity traders.
- India Stack Integration:Unified Payments Interface connectivity with blockchain rails offers real-time settlement for cross-border remittance corridors.
- AI-Contract Convergence:Machine learning oracles feeding smart contracts enable automated credit scoring and dynamic collateral management.
Industry Challenges
- Core Banking Integration:COBOL-based legacy systems require expensive middleware layers to communicate with distributed ledger nodes.
- Cross-Border Regulatory Arbitrage:Fragmented smart-contract liability frameworks across SEC, MAS, and FSA jurisdictions complicate multi-national deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain in BFSI Market |
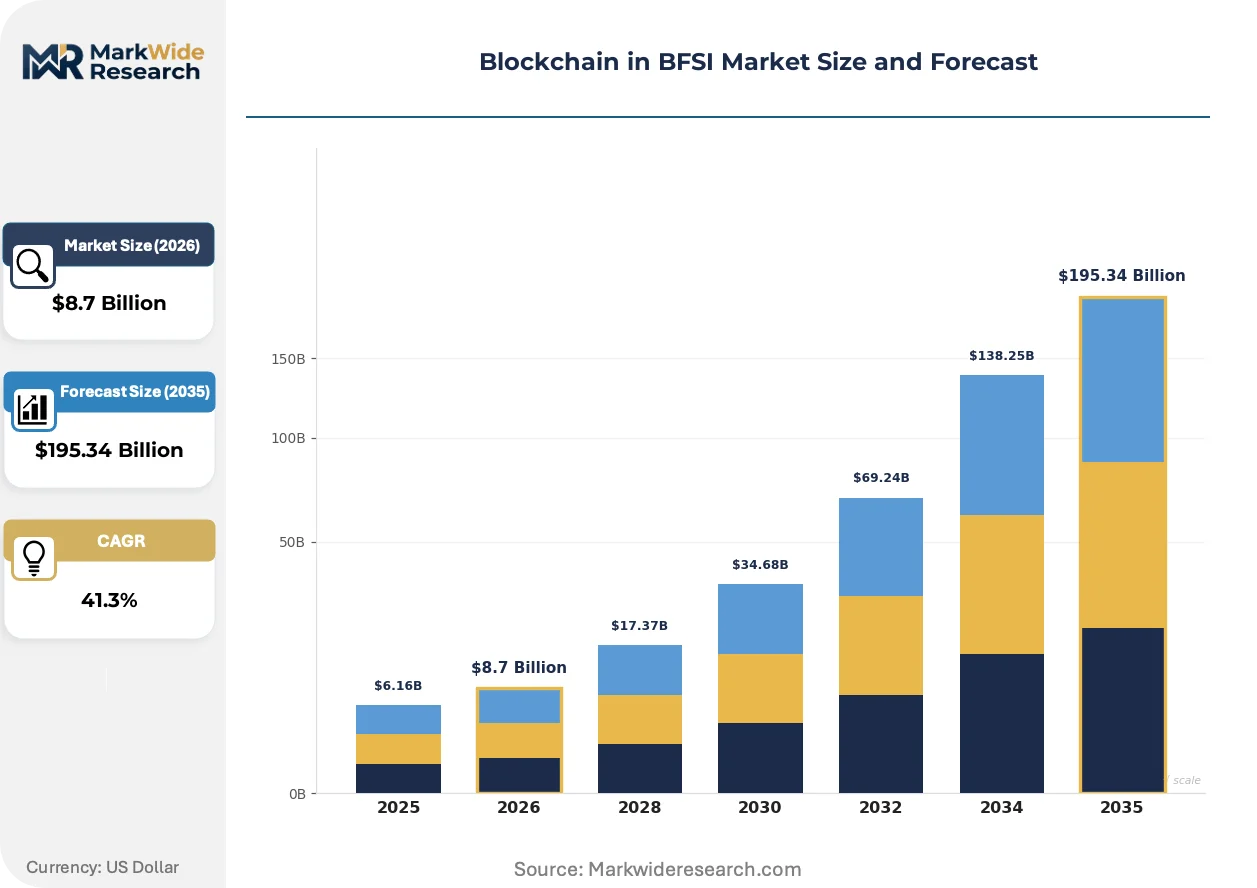
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $195.34 Billion |
| CAGR (2026 – 2036) | 41.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Payment Processing, Identity Management, Trade Finance, Compliance Management Service Type: Consulting, Implementation, Integration, Support & Maintenance, Training Deployment: Private Blockchain, Public Blockchain, Consortium Blockchain, Hybrid Blockchain Customer Type: Banks, Insurance Providers, Asset Management Firms, Payment Gateways, Microfinance Institutions |
| Companies Covered | IBM Corporation, Microsoft Corporation, Amazon Web Services, Accenture, JPMorgan Chase, R3, SAP SE, Oracle Corporation, Ripple Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain in BFSI Market Strategic Shifts & Innovations
Settlement infrastructure is undergoing fundamental architectural change as programmable ledgers absorb functions previously executed by correspondent banking networks and clearinghouses. Three concurrent developments are compressing the timeline for enterprise adoption.
Zero-knowledge proof technology is migrating from academic cryptography to production transaction privacy. JPMorgan Chase deploys zk-SNARKs to validate payment instructions without revealing counterparty balances or transaction amounts. This capability enables competitive bidding for settlement services while preserving regulatory audit trails.
Japan's FSA stablecoin licensing regime imposes 1:1 reserve requirements and third-party custody audits on yen-backed token issuers. The regulation forces domestic banks to segregate blockchain operations from traditional deposit-taking functions. Mitsubishi UFJ Financial Group responded by establishing standalone digital asset subsidiaries with independent capital structures.
Buyers now demand consumption-based pricing for blockchain infrastructure rather than perpetual software licenses. Capital markets divisions at tier-one banks negotiate transaction-fee arrangements capped at monthly minimums. This shift concentrates vendor selection power among institutions with sufficient volume to negotiate meaningful discounts.
Blockchain in BFSI Market Segmentation
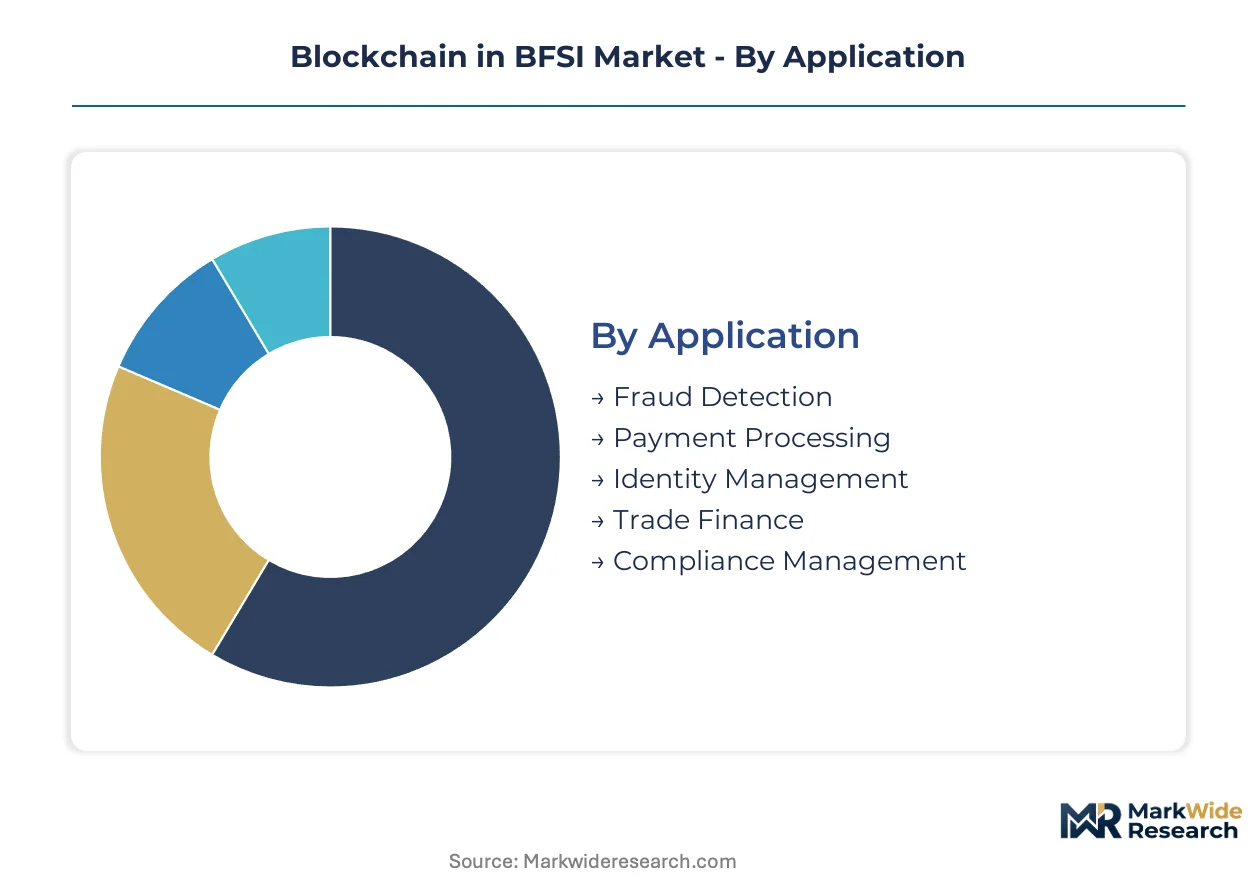
Segmentation in blockchain for BFSI reveals how value pools concentrate across distinct operational workflows and institutional buyer profiles. Understanding these divisions exposes where infrastructure spending prioritizes settlement speed versus regulatory compliance versus customer-facing digitization.
Application:
After-sales service intensity varies sharply across application segments, with live transaction monitoring and smart-contract upgrade cycles demanding continuous vendor engagement years post-deployment.
- Payment Processing:Real-time gross settlement systems replace SWIFT messaging with programmable ledger rails, compressing clearing from days to seconds. Demand concentrates at JPMorgan Chase and Singapore's MAS-licensed wholesale networks where throughput requirements exceed 1,000 transactions per second.
- Trade Finance:Letter-of-credit digitization on distributed ledgers reduces document processing from weeks to hours, unlocking working capital for commodity traders in correspondent banking corridors. R3's Corda specialization anchors this segment among European and Asian trade banks.
- Fraud Detection:Immutable audit trails enable pattern recognition across transaction histories without exposing plaintext data.
- Identity Management:KYC-ledger pilots from early implementations now generate maintenance revenues for established vendors.
- Compliance Management:MiCA-mandated reserve-backing disclosures require auditable infrastructure for payment token issuers.
By volume, Payment Processing leads. By growth pace, Trade Finance is ahead.
Service Type:
Cost tier differentiation separates advisory engagements from multi-year managed service contracts with SLA-backed uptime guarantees.
- Implementation:Enterprise deployments demand 18-36 month timelines with dedicated project teams configuring consensus mechanisms and node architecture. IBM and Microsoft compete through balance-sheet capacity to underwrite these capital-intensive engagements.
- Support & Maintenance:Production-grade networks require 24/7 monitoring, smart-contract patching, and validator node management. Singapore's digital asset hub concentrates demand where MAS licensing mandates operational resilience standards.
- Consulting:Regulatory navigation across SEC, MiCA, and FSA frameworks drives advisory demand.
- Integration:COBOL legacy systems require expensive middleware layers to communicate with distributed ledger nodes.
- Training:Smart contract auditors and zero-knowledge proof engineers command compensation premiums.
By revenue concentration, Implementation dominates. By margin expansion, Support & Maintenance is climbing fastest.
Deployment:
Customer type determines architecture selection, with correspondent banks favoring shared governance while retail-facing institutions isolate infrastructure.
- Consortium Blockchain:Shared governance models capture margin pools from institutions requiring multi-party coordination without full public network exposure. This configuration absorbs the fastest-expanding deployment value as trade finance and cross-border payment networks mature.
- Private Blockchain:Single-entity control suits custody operations and internal reconciliation where counterparty risk is minimal. Japan's FSA stablecoin licensing forced Mitsubishi UFJ Financial Group to establish standalone digital asset subsidiaries with independent capital structures.
- Public Blockchain:Permissionless networks attract decentralized finance integrations and retail token issuance.
- Hybrid Blockchain:Selective disclosure combines private transaction processing with public settlement anchoring.
By installed base, Private Blockchain leads. By new project initiations, Consortium Blockchain shows the steepest expansion trajectory.
Customer Type:
Geography shapes procurement patterns, with Singapore's hub status concentrating wholesale banking demand while India's UPI integration drives retail corridor innovation.
- Banks:Tier-one institutions negotiate consumption-based pricing capped at monthly minimums, concentrating vendor selection power among high-volume settlement operators. Cross-border payment corridors at JPMorgan Chase absorb enterprise-grade distributed ledger infrastructure.
- Payment Gateways:Real-time retail clearing demands programmable money rails with sub-second finality. India's Unified Payments Interface connectivity with blockchain settlement offers remittance corridor advantages.
- Insurance Providers:Parametric smart contracts automate claims processing for catastrophe bonds.
- Asset Management Firms:Tokenized fund administration requires custody-grade infrastructure with third-party audit integration.
- Microfinance Institutions:Cost constraints favor SaaS-delivered blockchain identity verification over proprietary deployments.
By current spending, Banks dominate. By growth momentum, Payment Gateways are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory clarity is concentrating blockchain infrastructure investment in jurisdictions with explicit licensing frameworks. Singapore's MAS wholesale settlement regime, the EU's MiCA disclosure mandates, and Japan's FSA stablecoin rules each create distinct compliance obligations that shape vendor selection and deployment timelines.
United States
JPMorgan Chase anchors enterprise-grade distributed ledger deployment for cross-border payment corridors. The SEC mandates climate-risk and custody disclosures that shape how institutions evaluate blockchain audit trails. New York's financial district concentrates demand where tier-one banks negotiate consumption-based pricing for settlement infrastructure.
Singapore
The Monetary Authority of Singapore licenses wholesale settlement networks that demonstrate programmable money clearing at scale. MAS operational-resilience standards directly determine market-access eligibility for blockchain service providers. The city-state's digital asset hub attracts correspondent banking volume seeking real-time gross settlement alternatives to legacy messaging protocols.
Japan
Mitsubishi UFJ Financial Group established standalone digital asset subsidiaries with independent capital structures to comply with FSA stablecoin licensing. The regulator imposes 1:1 reserve requirements and third-party custody audits on yen-backed token issuers. Tokyo's financial institutions segregate blockchain operations from traditional deposit-taking functions.
Germany
German banks absorb consortium blockchain configurations for trade finance digitization requiring multi-party coordination without full public network exposure. The EU's MiCA framework mandates auditable reserve-backing for payment tokens, compelling institutions to deploy compliant ledger infrastructure. Frankfurt's capital markets divisions negotiate transaction-fee arrangements capped at monthly minimums.
India
Unified Payments Interface connectivity with blockchain rails offers real-time settlement for cross-border remittance corridors. The central bank's digital currency pilots shape how payment gateways integrate programmable ledger infrastructure. Mumbai's financial technology clusters concentrate demand for sub-second finality in retail clearing applications.
Blockchain in BFSI Market Key Industry Players
Channel-controlling players compete with product-specialist players across implementation, platform, and advisory segments. The vendor base organizes around three archetypes: cloud hyperscalers with confidential computing integrations, enterprise software vendors with hybrid cloud architectures, and distributed ledger specialists with workflow-specific protocols. Consolidation pressure intensifies as multi-year deployment contracts favor balance-sheet capacity. Strategic partnerships between technology vendors and regulated institutions outpace pure M&A activity in this capital-intensive segment.
Within the cloud-platform tier, IBM Corporation and Microsoft Corporation exemplify archetypes leveraging existing enterprise relationships to anchor blockchain engagements. R3 occupies a specialist position through protocol-level trade finance optimization. These three entities represent distinct competitive vectors: hybrid cloud infrastructure, confidential computing integration, and industry-specific ledger configuration.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Amazon Web Services |
| Accenture |
| JPMorgan Chase |
| R3 |
| SAP SE |
| Oracle Corporation |
| Ripple Labs |
| Others |
Cost & Logistics Intelligence
Specialized zero-knowledge proof engineering talent concentrates in Singapore and Switzerland, anchoring margin pools in high-complexity implementation contracts where smart contract auditors command compensation premiums that inflate deployment budgets substantially. This upstream scarcity feeds downstream pricing power to vendors with captive access to cryptographic expertise.
Pricing Analysis
Certification level under MAS operational-resilience standards creates the primary spread between premium implementation tiers and standard service bundles. Consumption-based transaction-fee arrangements capped at monthly minimums dominate enterprise procurement, with tier-one banks negotiating volume discounts that compress margins for mid-tier service providers. Pricing pressure stems from hyperscaler cloud platforms bundling confidential computing infrastructure at scale. Payment gateways exhibit highest price sensitivity due to thin retail clearing margins, while custody-grade infrastructure buyers absorb premium pricing for third-party audit integration.
Supply Chain Analysis
Contract manufacturing of enterprise-grade validator hardware concentrates with Foxconn and Quanta Computer facilities in Taiwan and Vietnam. Specialized semiconductor components for secure enclave processing draw from TSMC foundries and Samsung memory fabs. Single-source vulnerability in custom ASIC supply for zero-knowledge proof acceleration creates chokepoint exposure. Distribution runs through direct enterprise sales teams and systems integrator partnerships, bypassing traditional channel intermediaries for production-grade deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one banks with sufficient transaction volume to negotiate consumption-based pricing, fragmenting vendor selection criteria between hyperscaler platforms and specialized protocol providers.
For Market Incumbents: Insulate core enterprise relationships by embedding confidential computing infrastructure into multi-year managed service contracts with SLA-backed uptime guarantees. Defend against emerging cloud-native challengers through vertical integration into zero-knowledge proof acceleration hardware. Prioritize certification investment under Singapore MAS and EU MiCA frameworks to maintain compliance moats. For New Entrants and Emerging Players: Establish a beachhead in trade finance digitization workflows where R3's Corda specialization leaves whitespace for alternative protocol providers. Target India's UPI-blockchain integration corridor as the most penetrable geography for retail settlement innovation. Pursue partnership-first go-to-market angles with regional banks lacking in-house distributed ledger expertise. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed enterprise software vendors holding legacy mainframe integration capabilities that blockchain middleware demands. Long-term viability hinges on 5-10 year contract backlogs with tier-one financial institutions. Monitor stablecoin licensing application volumes at Japan's FSA and Singapore's MAS as inflection indicators for wholesale settlement infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Integration | Azure secure enclaves enable JPMorgan Chase to process sensitive transaction data without plaintext exposure. |
| MAS Licensing Compliance | Operational-resilience certification unlocks Singapore wholesale settlement network market access eligibility. |
| Trade Finance Protocol Specialization | Corda optimization for letter-of-credit workflows captures correspondent banking margin pools at European trade banks. |
| Zero-Knowledge Proof Deployment | zk-SNARK validation preserves regulatory audit trails while shielding counterparty balances from node operators. |
| Consumption-Based Pricing Transition | Transaction-fee arrangements with monthly minimums align vendor incentives with institutional settlement volume growth. |
Research Approach
Cross-validation between primary interviews with distributed ledger architects and secondary analysis of SEC disclosure filings anchors the qualitative findings. Chief technology officers at tier-one banks, smart contract auditors, MAS licensing officers, and enterprise procurement leads provided operational perspectives. Regulatory databases, hyperscaler capex disclosures, and consortium blockchain governance documents supplied external validation. Bottom-up deployment tracking and top-down infrastructure spending estimates were reconciled across the analysis window.
Calibration against historical adoption curves in enterprise software and payment infrastructure shaped the projection framework. Segmentation dimensions modeled include application type, deployment architecture, customer tier, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and average contract value trajectories. Consensus mechanism throughput benchmarks and validator node deployment counts served as industry-specific forecast inputs throughout the modeling period.
Sensitivities concentrate around MiCA implementation timelines, stablecoin reserve-backing enforcement intensity, and zero-knowledge proof hardware commoditization curves. Forecasts reflect assumptions regarding regulatory harmonization progress and legacy system replacement cycles. Quarterly review of licensing application volumes at Singapore's MAS and Japan's FSA is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
US Luxury Travel Market
Others
Industrial Computers Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Short Video Applications Market
Others
Tanned Fish Skin Leather Market
Others
Document Camera Market
Others
Global on-Demand Laundry Service Market
Others
Global Enterprise Mobility in Healthcare Market
Others
5G Smartphone Market
Others
Smart Home Water Softener Market
Others
South Asia Geosynthetics Market
Others
Global Mobile Gambling Market
Others
Global Hardware As a Service (Haas) Market
Others
Global Application Testing Services Market
Others
Fabric Based Computing Market
Others
UK Cat Food Market