
 Industrial Direct Radiography Market | 2026-2036
Industrial Direct Radiography Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Direct Radiography Market Foresight
Software-defined image processing and cloud-connected analytics is broadening what suppliers monetize beyond hardware sales. Fujifilm Holdings Corporation leverages its medical imaging heritage to anchor digital workflow platforms in industrial settings. Comet Holding AG sustains technology leadership through specialized X-ray tube architectures that serve high-resolution inspection requirements. Shimadzu Corporation competes by integrating real-time defect recognition algorithms directly into detector firmware.
Industrial direct radiography employs solid-state digital detectors—typically amorphous silicon or selenium thin-film transistor arrays coupled with cesium iodide scintillators—to capture penetrating radiation and convert it instantaneously into high-resolution digital images for nondestructive testing. Flat panel detectors dominate installed value due to their superior spatial resolution and elimination of chemical processing, while real-time systems capture the fastest expansion as inline process control replaces batch inspection in manufacturing. Quality control applications concentrate margin pools where automated pass-fail algorithms reduce labor dependency and accelerate throughput.
The FAA and EASA shape product standards by mandating digital radiography protocols for turbine blade and airframe weld certification, while ISO 17636-2 defines compliance benchmarks for weld inspection across industrial sectors. ASTM E2737 governs long-term stability testing of digital detector arrays, creating a barrier to market entry for uncertified equipment. Stakeholders must monitor how evolving AI-assisted defect classification standards from ASTM and ISO reshape software validation requirements and service contract structures.
Market Dynamics
Digital detector arrays are displacing film-based radiography in nondestructive testing workflows, compressing inspection timelines from hours to minutes while eliminating chemical processing infrastructure. This hardware transition is reshaping supplier economics toward software and service revenue streams.
Growth Catalysts
- FAA and EASA airworthiness mandates:Turbine blade and airframe weld certification protocols now explicitly recognize digital radiography standards, forcing aerospace manufacturers to upgrade inspection infrastructure.
- Inline process control adoption:Automotive and electronics manufacturers deploy real-time direct radiography systems to replace batch inspection, capturing defect data during production rather than post-manufacturing.
- German industrial cluster replacement cycles:Munich and Hamburg manufacturing hubs drive equipment refresh demand as aging NDT systems reach end-of-life and face stricter ISO 17636-2 compliance requirements.
Market Restraints
- Cesium iodide scintillator supply concentration:Japanese and Chinese suppliers control critical raw material inputs for flat panel detector manufacturing, creating vulnerability to export restrictions or price volatility.
- ASTM E2737 certification barriers:Long-term stability testing requirements for digital detector arrays extend product validation timelines and exclude uncertified equipment from regulated industries.
- Computed tomography substitution threat:Industrial CT systems offer three-dimensional defect visualization that direct radiography cannot match, pressuring two-dimensional inspection in high-value applications.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for domestic production create openings for localized NDT equipment deployment as quality standards tighten under BIS oversight.
- AI-assisted defect classification convergence:Machine vision algorithms integrated with detector firmware enable automated pass-fail decisions, reducing labor dependency in high-throughput environments.
- Cloud-connected analytics platforms:Remote image storage and collaborative review tools open recurring revenue models beyond one-time hardware sales, particularly for distributed inspection networks.
Industry Challenges
- Radiographer certification gaps:Qualified technicians capable of interpreting digital radiographs against evolving ASTM and ISO defect classification standards remain scarce relative to deployment growth.
- Legacy film archive integration:Manufacturers with decades of film-based inspection records face complex migration requirements to maintain traceability under regulatory audit protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Direct Radiography Market |
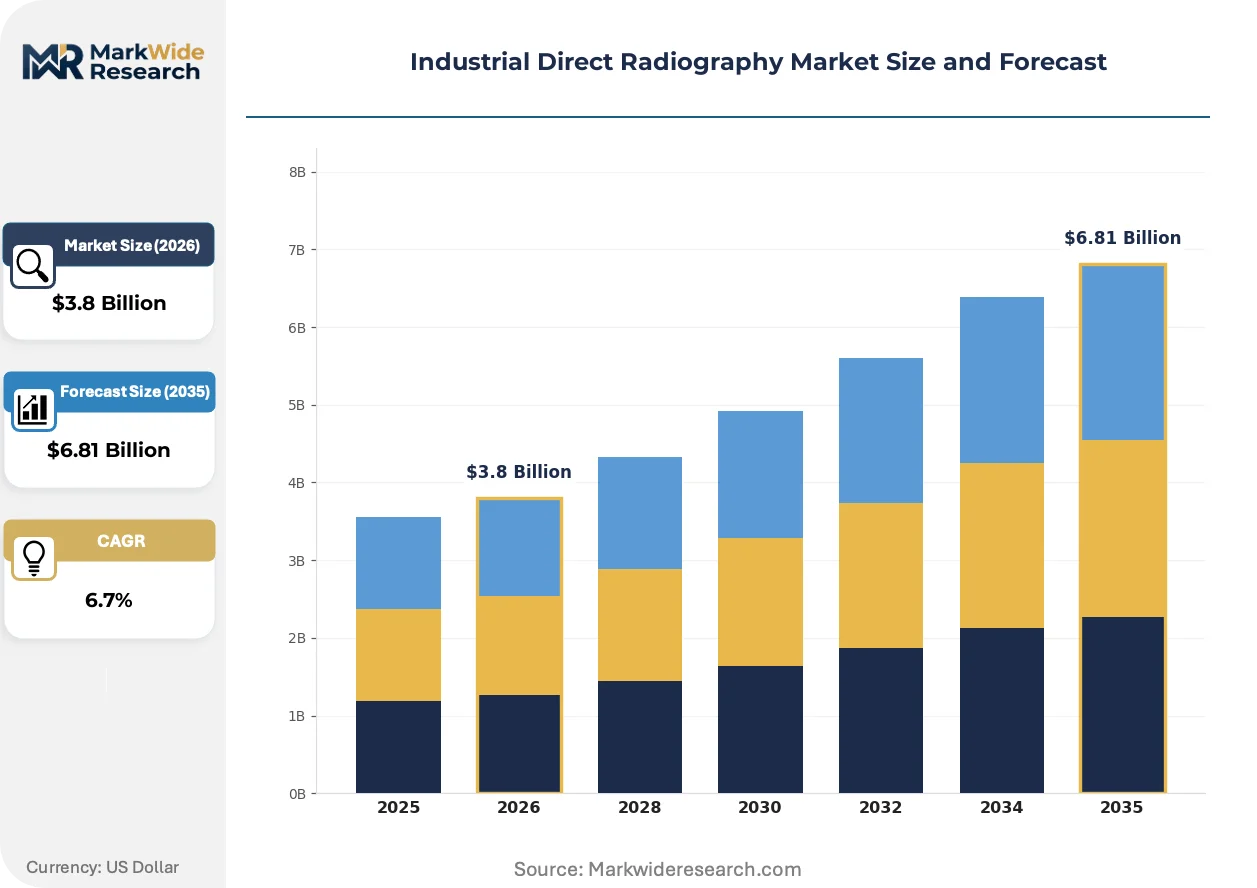
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panel Detectors, Image Plates, Scanners, Real-Time Systems End User: Manufacturing, Aerospace, Energy, Construction Technology: X-Ray, Gamma Ray, Computed Tomography, Digital Imaging Application: Quality Control, Material Inspection, Asset Management, Preventive Maintenance |
| Companies Covered | Durr NDT GmbH & Co. KG, Intertek Group Plc, Mistras Group, Inc., TWI Global, OR Technology, Comet Holding AG, Fujifilm Holdings Corporation, Shimadzu Corporation, 3DX-Ray Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Direct Radiography Market Shifts & Advancements
Direct radiography is evolving from standalone hardware toward integrated digital workflow platforms. Software-defined image processing, real-time analytics, and predictive maintenance capabilities are becoming primary differentiation vectors rather than detector specifications alone.
Amorphous selenium direct conversion detectors are consolidating market preference over indirect scintillator-based architectures for high-resolution applications. Aerospace precision component manufacturers in Germany and France adopt selenium arrays for sub-50-micron feature detection in turbine blade inspection. This technology compression is eliminating the performance gap that previously justified premium pricing for specialized film systems.
EU AI Act classification requirements are reshaping software validation protocols for automated defect recognition systems. Industrial radiography equipment with embedded machine learning now faces conformity assessment procedures previously reserved for medical devices. German notified bodies and French ANSM are developing sector-specific guidance for AI-assisted NDT, creating compliance complexity for suppliers without established quality management systems.
Buyer consolidation among tier-one aerospace and automotive OEMs is compressing vendor qualification cycles and centralizing procurement decisions. Tier-one manufacturers in the US and Germany now mandate cloud-connected inspection data for supplier audit trails, displacing standalone detector sales with platform subscriptions. This behavioral shift concentrates purchasing power and favors suppliers with established enterprise software integration capabilities.
Industrial Direct Radiography Market Segmentation
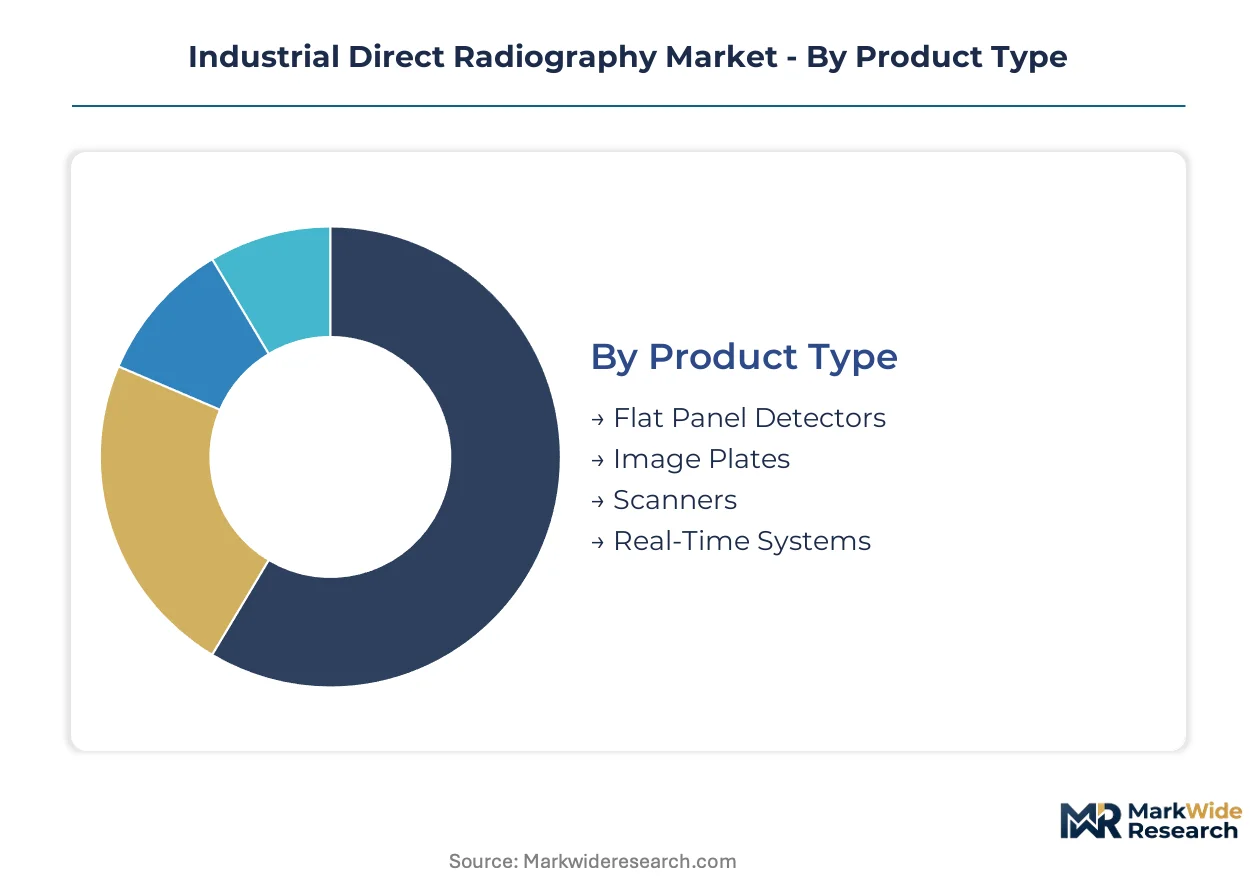
Industrial direct radiography segments reflect divergent technology maturities and regulatory exposure levels. Supplier economics vary sharply between hardware-centric detector sales and recurring software revenue from integrated workflow platforms.
Product Type:
Supply concentration for scintillator materials and TFT array manufacturing shapes competitive dynamics across detector architectures.
- Flat Panel Detectors:Amorphous silicon or selenium thin-film transistor arrays coupled with cesium iodide scintillators deliver sub-50-micron spatial resolution without chemical processing. Aerospace manufacturers in Germany and France anchor demand for turbine blade inspection where FAA and EASA airworthiness mandates require digital certification protocols.
- Real-Time Systems:Inline direct radiography captures penetrating radiation continuously during production cycles rather than post-manufacturing batch inspection. Automotive OEMs in Stuttgart and Wolfsburg deploy these for weld verification on battery enclosure assemblies, compressing defect detection timelines from hours to seconds.
- Image Plates:Photostimulable phosphor plates serve as intermediate digital capture media for facilities transitioning from film workflows.
- Scanners:Dedicated readout devices convert exposed image plates into digital radiographs for facilities with legacy plate inventories.
Flat panel detectors absorb the bulk of installed capacity; real-time systems are expanding most quickly.
End User:
Regulatory stringency and asset criticality create tiered demand patterns across industrial sectors.
- Aerospace:Turbine blade and airframe weld certification under FAA and EASA protocols mandates digital radiography infrastructure with ASTM E2737 stability validation. Boeing and Airbus supplier networks in Washington state and Toulouse drive replacement cycles for aging film-based inspection systems.
- Energy:Pipeline weld integrity and pressure vessel inspection for oil and gas operators require portable direct radiography for field deployment. North Sea operators and Gulf Coast refineries prioritize equipment with ISO 17636-2 compliance for offshore asset certification.
- Manufacturing:General industrial quality control spans automotive, electronics, and metal fabrication with varying resolution requirements.
- Construction:Structural weld verification and concrete inspection utilize lower-specification portable systems for civil infrastructure projects.
Aerospace commands premium pricing through certification complexity; manufacturing delivers volume scale across diversified applications.
Technology:
Radiation source selection determines penetration depth, safety protocols, and regulatory classification for deployment environments.
- X-Ray:Sealed tube and linear accelerator sources generate controlled bremsstrahlung radiation for thin-to-medium section inspection. Electronics manufacturers in Shenzhen and semiconductor fabs in Hsinchu anchor demand for sub-10-micron feature detection on printed circuit assemblies.
- Gamma Ray:Iridium-192 and cobalt-60 isotope sources penetrate thick-section castings and pipeline welds where X-ray tube voltage limits apply. Pipeline operators in Alberta and Kazakhstan deploy gamma radiography for in-service inspection of corrosion under insulation.
- Computed Tomography:Rotational scanning reconstructs three-dimensional defect volumes that direct radiography cannot resolve.
- Digital Imaging:Software-defined acquisition and processing workflows unify detector hardware with cloud-connected analytics platforms.
X-ray systems dominate installed base through versatility; gamma ray applications persist in thick-section energy infrastructure.
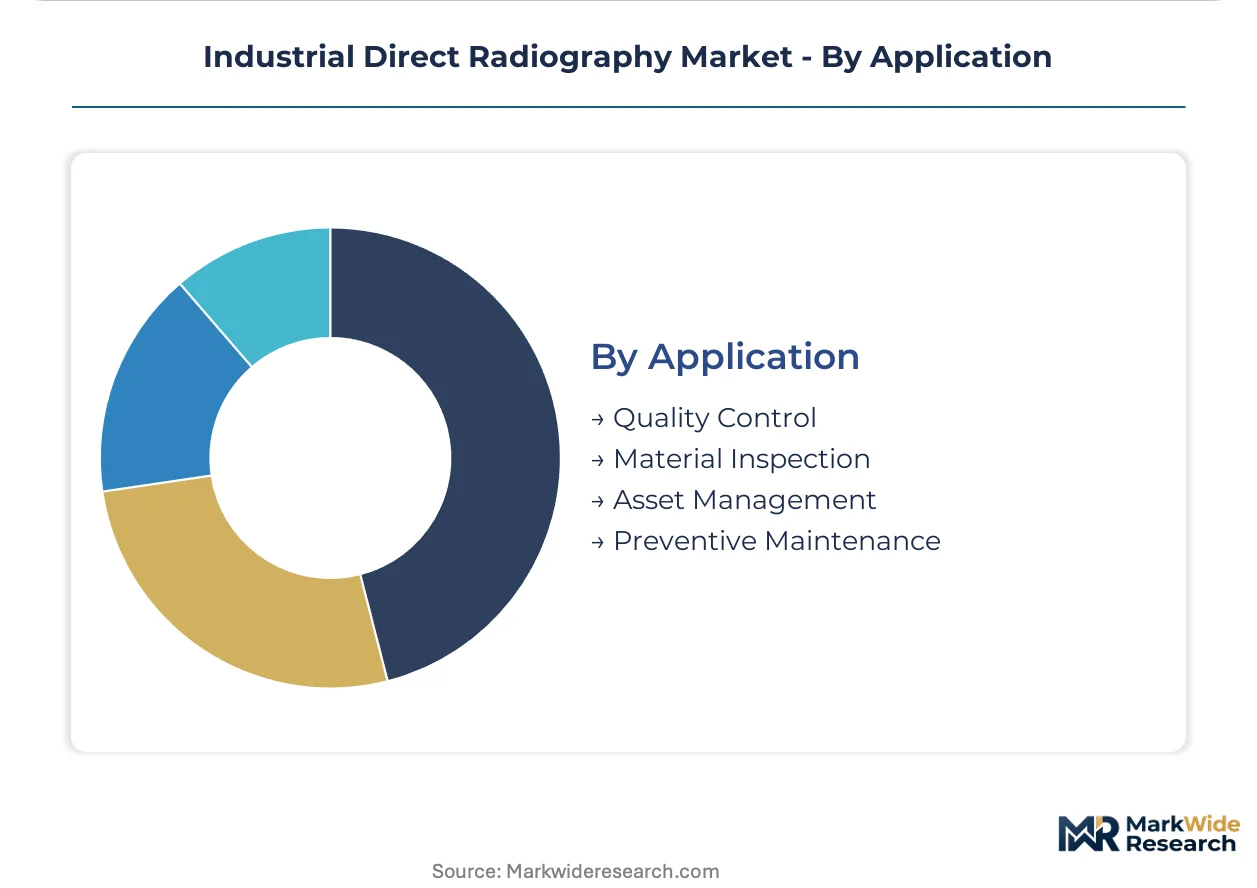
Application:
Automation intensity and labor substitution potential segment value capture across inspection workflows.
- Quality Control:Automated pass-fail algorithms integrated with detector firmware eliminate radiographer interpretation for high-throughput manufacturing. Automotive stamping plants in Detroit and Munich deploy inline systems where ISO 17636-2 compliance gates supplier qualification.
- Preventive Maintenance:Scheduled inspection of rotating machinery and pressure equipment extends asset life through early defect detection. Petrochemical complexes in Rotterdam and Houston integrate direct radiography into reliability-centered maintenance programs.
- Material Inspection:Incoming raw material verification and in-process weld monitoring support traceability requirements.
- Asset Management:Digital radiograph archives enable comparative degradation analysis across inspection intervals for critical infrastructure.
Quality control concentrates software and service revenue; preventive maintenance is climbing the fastest as predictive analytics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the majority of high-resolution flat panel detector arrays, while the United States and China absorb the largest shares of installed inspection capacity. Japan controls critical cesium iodide scintillator supply chains. Aerospace certification requirements in France and regulatory tightening in India are redistributing demand patterns.
United States
Boeing supplier networks in Washington state and Alabama anchor replacement demand for aging film-based NDT infrastructure. The FAA mandates digital radiography protocols for turbine blade and airframe weld certification, forcing upgrade cycles across aerospace manufacturing clusters. Detroit automotive stamping plants deploy inline real-time systems for battery enclosure weld verification under ISO 17636-2 compliance gates.
Germany
Industrial clusters around Munich and Hamburg drive equipment refresh cycles as aging NDT systems face stricter ISO 17636-2 weld inspection requirements. The KBA enforces vehicle component traceability standards that accelerate digital workflow adoption. Stuttgart automotive OEMs deploy real-time direct radiography for inline process control on electric vehicle battery assemblies.
China
Electronics manufacturers in Shenzhen and semiconductor fabs in Hsinchu anchor demand for sub-10-micron feature detection on printed circuit assemblies. MIIT standards for industrial equipment digitization create procurement pressure for domestic NDT infrastructure. Yangtze River Delta manufacturing hubs integrate cloud-connected inspection platforms for supplier audit trail centralization.
France
Airbus supplier networks in Toulouse drive premium detector demand for turbine blade inspection under EASA airworthiness mandates. The ANSM develops sector-specific guidance for AI-assisted NDT systems under EU AI Act classification requirements. Auvergne-Rhône-Alpes precision component manufacturers adopt amorphous selenium arrays for sub-50-micron defect detection.
India
PLI scheme incentives for domestic manufacturing create openings for localized NDT equipment deployment as BIS oversight tightens quality standards. Maharashtra and Gujarat industrial corridors drive demand for portable direct radiography in pipeline weld integrity applications. Chennai automotive suppliers face accelerating customer mandates for digital inspection data in supplier qualification processes.
Industrial Direct Radiography Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the detector value chain. The market structure concentrates around three tiers: integrated imaging conglomerates with medical-industrial crossover capabilities, specialized X-ray component manufacturers with captive tube architectures, and inspection service providers bundling equipment with analytical expertise. Strategic moves center on software platform integration and detector firmware algorithm development.
Within the integrated imaging tier, Fujifilm Holdings Corporation and Shimadzu Corporation exemplify medical-to-industrial technology transfer strategies. Comet Holding AG occupies a specialized position among Swiss-based component architects focused on high-resolution source technologies. Durr NDT GmbH & Co. KG represents the German engineering-centric archetype linking equipment manufacturing with automated inspection system integration.
| Leading Market Players |
|---|
| Durr NDT GmbH & Co. KG |
| Intertek Group Plc |
| Mistras Group, Inc. |
| TWI Global |
| OR Technology |
| Comet Holding AG |
| Fujifilm Holdings Corporation |
| Shimadzu Corporation |
| 3DX-Ray Ltd. |
| Others |
Supply & Pricing Matrix
ASTM E2737 certification tiers create a sharp bifurcation between validated digital detector arrays and uncertified equipment, concentrating pricing power with suppliers who have cleared long-term stability testing while relegating commodity alternatives to price-sensitive construction and general manufacturing applications. This tier divergence manifests in supply chain configurations where certified amorphous selenium arrays flow through aerospace-qualified channels in Germany and France, while indirect scintillator-based detectors source through volume distributors serving automotive and electronics manufacturers.
Pricing Analysis
Cost-down pressure on flat panel detectors accelerates as automotive OEMs in Stuttgart and Wolfsburg mandate ISO 17636-2 compliant inline systems for battery enclosure inspection. Three-tier pricing structure across premium, standard, and economy levels separates FAA-validated aerospace arrays from industrial quality-control units and portable construction-grade equipment. Buyers in manufacturing segments exhibit highest price sensitivity, while energy sector procurement for offshore pipeline inspection prioritizes reliability over unit cost.
Supply Chain Analysis
Refurbishment flows for end-of-life TFT arrays create secondary supply channels serving cost-constrained facilities transitioning from film workflows. Manufacturing concentrates in Japan for cesium iodide scintillators, Germany for amorphous silicon detector backplanes, and China for electronics assembly integration. Single-source vulnerability in scintillator raw materials exposes flat panel production to export restriction risk. Distribution runs through specialized NDT equipment distributors with certified service capabilities rather than general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial direct radiography sits in a technology-transition phase where solid-state digital detectors displace film-based radiography across regulated inspection workflows. This displacement compresses hardware margins while expanding software and service revenue pools.
For Market Incumbents: Anchor platform subscription models by integrating cloud-connected analytics with detector firmware, defending against computed tomography substitution in high-value aerospace applications. Deepen backward integration into X-ray tube architectures to control critical component supply. Prioritize AI-assisted defect classification R&D ahead of EU AI Act conformity assessment requirements. For New Entrants and Emerging Players: Capture white-space in India's PLI scheme manufacturing corridors where BIS oversight is tightening quality standards without established incumbent relationships. Target portable direct radiography for pipeline weld integrity in Maharashtra and Gujarat industrial corridors. Pursue inspection-service bundling rather than equipment-only sales to bypass ASTM E2737 certification barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated imaging conglomerates seeking medical-to-industrial technology transfer capabilities. Long-term viability favors suppliers with embedded software platforms over hardware-only detector manufacturers. Monitor FAA and EASA mandate expansion timelines as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Defect Classification Development | EU AI Act conformity requirements from French ANSM reshape software validation protocols for automated NDT systems. |
| Cloud-Connected Analytics Platform Launch | Boeing and Airbus supplier networks in Washington and Toulouse now mandate remote inspection data for audit trails. |
| Backward Integration into X-Ray Tube Manufacturing | Comet Holding AG's captive source architectures demonstrate margin protection against component supply volatility. |
| Certification Investment for ASTM E2737 Compliance | Stability validation creates barrier to regulated aerospace and energy sector procurement for uncertified equipment. |
| Geographic Expansion into Indian Manufacturing Corridors | PLI scheme incentives in Maharashtra and Gujarat create localized deployment openings as BIS standards tighten. |
Research Methodology
Independent corroboration across primary interviews with NDT equipment procurement managers, aerospace quality directors, and industrial radiography service technicians, combined with secondary validation from FAA airworthiness directives, EASA certification protocols, and ISO 17636-2 compliance documentation, underwrites the qualitative findings. Bottom-up triangulation against customs data for scintillator material trade flows and top-down reconciliation with industrial automation capex disclosures anchor market sizing.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by detector architecture, end-use regulatory exposure, and technology maturity. The modeling framework incorporates flat panel detector replacement cycles, real-time system adoption in automotive inline inspection, and gamma ray penetration requirements for energy infrastructure. CAGRs derive from equipment shipment patterns correlated with aerospace manufacturing output and weld inspection regulatory mandate expansion.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cesium iodide export restrictions, AI Act classification enforcement timing, and computed tomography cost-down trajectories. Forecasts reflect documented assumptions regarding regulatory mandate adoption rates and equipment replacement cycle timing. Practitioners should monitor FAA digital protocol expansion, EASA airworthiness bulletin updates, and EU AI Act notified body guidance publication for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Tube Tester Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
Pump Testers Market
Test and Measurement
Leak Testing Market
Test and Measurement
Permeation Testing Machines Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market
Test and Measurement
Printed Circuit Board Inspection Equipment Market
Test and Measurement
MEMS and Sensor Performance and Reliability Test Equipment Market
Test and Measurement
Structure Tester Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
Gloss Meters Market
Test and Measurement
Rohs Tester Market
Test and Measurement
Automated Optical Inspection Market