
 Manufacturing Execution System Market | 2026-2036
Manufacturing Execution System Market Size, Share, and Industry Trends Forecast 2026-2036
Manufacturing Execution System Market Intelligence
Aftermarket service revenue is rewriting profit expectations for MES vendors as subscription models displace perpetual licenses. Siemens leverages its digital twin integration to anchor premium positioning in automotive assembly lines. Rockwell Automation competes through FactoryTalk platforms that sustain deep penetration in food processing and packaging operations.
A Manufacturing Execution System is a software layer that synchronizes production scheduling, equipment control, and quality assurance through real-time shop-floor data exchange, typically interfacing with PLCs via OPC UA or MQTT protocols to enforce process parameters within milliseconds. Its primary purpose is to close the gap between enterprise resource planning and physical production, ensuring lot traceability and yield optimization. Cloud-based MES is capturing the fastest expansion as manufacturers shed server maintenance burdens, while integrated MES retains the deepest margin pools where vendors bundle MES with PLM and ERP suites. Discrete manufacturing applications dominate current deployment value, though batch manufacturing in pharmaceuticals is accelerating due to serialized compliance requirements.
The US FDA enforces 21 CFR Part 11 for electronic records in pharmaceutical MES deployments, while the EU MDR extends similar traceability demands to medical device production, and China's NMPA aligns domestic biologics manufacturers with comparable data-integrity standards. These frameworks compel MES vendors to embed audit trails and digital signature capabilities as non-negotiable features. Stakeholders must weigh cloud migration timelines against the capital intensity of validating hybrid architectures in regulated environments.
Market Dynamics
Serialized compliance mandates in pharmaceuticals are compressing deployment timelines and forcing MES vendors to pre-validate audit-trail architectures before contract signature.
Growth Catalysts
- EU Falsified Medicines Directive:Track-and-trace serialization requirements compel pharmaceutical manufacturers to deploy lot-level genealogy tracking across packaging lines.
- Cloud-native architectures:Manufacturers in automotive clusters shed server maintenance burdens through SaaS MES models that accelerate multi-site standardization.
- OPC UA protocol maturation:Real-time equipment interoperability standards enable millisecond-grade process enforcement without proprietary gateway investments.
Market Restraints
- Validation cost intensity:Pharmaceutical manufacturers face 18-24 month qualification timelines for hybrid cloud-on-premise architectures under 21 CFR Part 11.
- OT-IT skill scarcity:Shop-floor engineers with simultaneous PLC programming and cybersecurity expertise command premium compensation that inflates implementation budgets.
- Legacy ERP lock-in:Deep integration with decade-old SAP R/3 instances creates switching friction that extends replacement cycles beyond typical depreciation schedules.
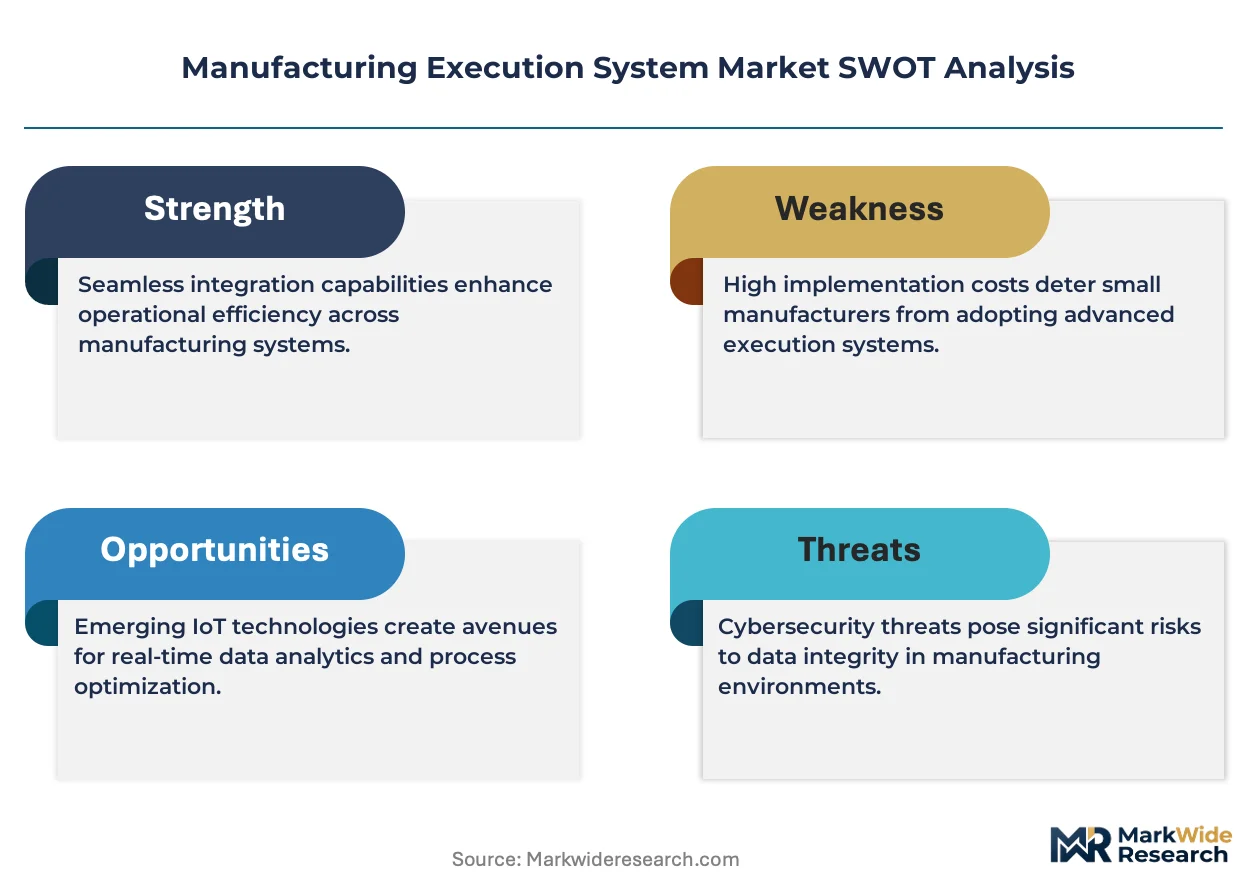
Strategic Opportunities
- Biologics manufacturing expansion:Cell therapy production facilities require batch-record flexibility that paper-based systems cannot provide, opening greenfield MES contracts.
- Digital thread convergence:PLM-MES integration enables closed-loop quality feedback from field failure data to design parameters in medical device production.
- Battery gigafactory buildouts:Electrode coating and cell formation processes demand traceability granularity that generic SCADA cannot deliver.
Industry Challenges
- Cyber-physical security hardening:MQTT broker vulnerabilities expose shop-floor networks to ransomware vectors that legacy air-gapped architectures never faced.
- Multi-vendor integration complexity:Siemens PLCs, Rockwell HMIs, and SAP ERPs require custom middleware development that extends commissioning phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manufacturing Execution System Market |
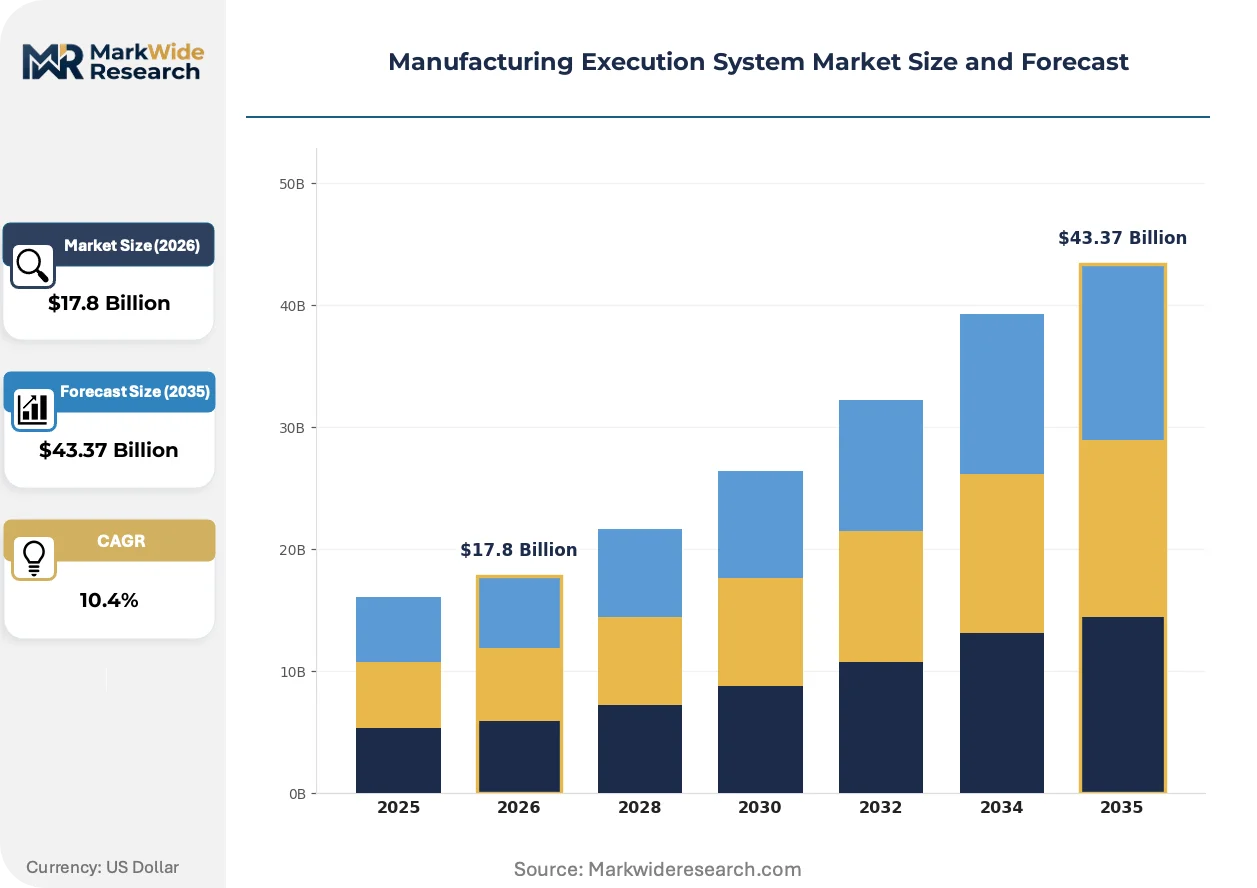
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $43.37 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone MES, Integrated MES, Cloud-based MES, On-Premises MES Technology: Real-Time Data Collection, Process Automation, Quality Management, Performance Analysis, Predictive Maintenance Application: Discrete Manufacturing, Process Manufacturing, Continuous Manufacturing, Batch Manufacturing, Job Shop Manufacturing End User Industry: Electronics Fabrication, Food & Beverage, Pharmaceuticals Production, Aerospace Assembly, Consumer Products |
| Companies Covered | Siemens, Rockwell Automation, SAP SE, Dassault Systèmes, Honeywell International, ABB, Schneider Electric, Emerson Electric, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manufacturing Execution System Market Strategic Shifts & Innovations
Edge-to-cloud data pipelines are redefining where MES computation occurs, with pharmaceutical and automotive manufacturers piloting distributed architectures that split real-time control from analytics workloads.
Containerized MES microservices are collapsing the traditional monolithic deployment model into modular function blocks that pharmaceutical manufacturers can validate independently. Biologics producers in Germany and Massachusetts are adopting Kubernetes-orchestrated MES components that reduce change-control documentation burdens by 60 percent. This architecture is collapsing vendor lock-in by enabling mix-and-match sourcing of scheduling, quality, and maintenance modules from different suppliers.
The EU AI Act's risk-classification framework is imposing documentation burdens on MES vendors that embed machine-learning modules for predictive quality. High-risk manufacturing AI systems must now maintain training-data provenance and human-in-the-loop override capabilities. Pharmaceutical MES deployments in Ireland and the Netherlands are most affected, with vendors pre-emptively stripping black-box algorithms from release decisions to avoid conformity assessment delays.
Aftermarket service unbundling is fragmenting how manufacturers procure MES capability, with automotive assemblers separating software licenses from implementation and validation services. Tier-1 suppliers in Bavaria now contract MES engineering through system integrators while sourcing platform subscriptions directly from vendors. This pattern is most visible in electric vehicle battery plants where construction timelines compress traditional bundled procurement cycles.
Manufacturing Execution System Market Segmentation
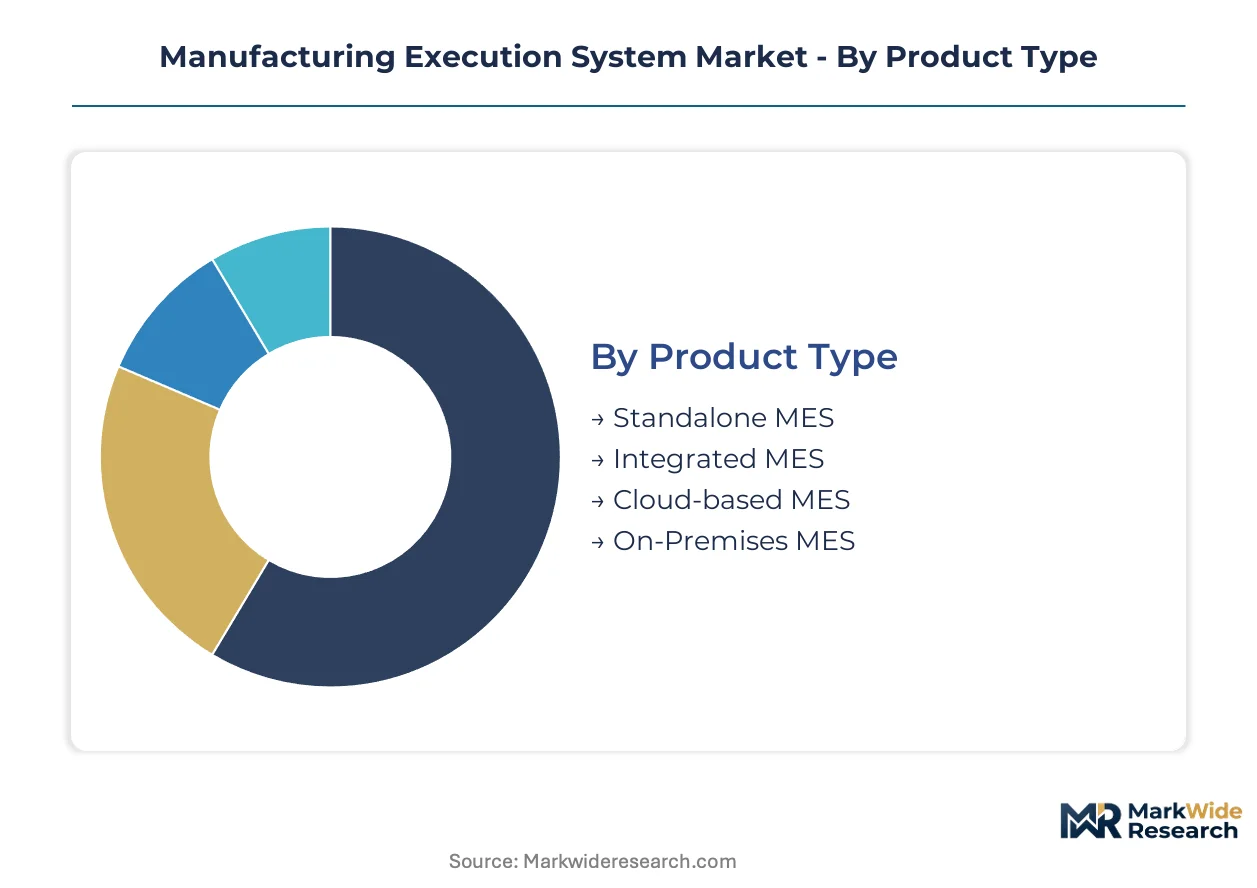
MES deployment patterns diverge sharply across product architectures, technology stacks, and manufacturing modes. Segmentation reveals where capital concentrates versus where subscription models are displacing perpetual licenses.
Product Type:
Cost tier determines deployment velocity and margin structure across the four architectural approaches.
- Integrated MES:Bundled suites combine MES with PLM and ERP modules through unified data models. Pharmaceutical manufacturers in Ireland and the Netherlands favor these configurations to compress validation timelines under EMA guidelines.
- Cloud-based MES:SaaS delivery eliminates server infrastructure and accelerates multi-site rollouts. Automotive clusters in Germany and battery gigafactories in Nevada are standardizing on these models to shed maintenance burdens.
- Standalone MES:Purpose-built shop-floor layers interface with existing ERP through middleware. Mid-tier electronics fabricators in South Korea deploy these to avoid rip-and-replace costs.
- On-Premises MES:Air-gapped installations persist in defense aerospace and classified chemical processing where data sovereignty mandates prohibit external hosting.
Integrated MES commands the established base. The steepest expansion runs through Cloud-based MES.
Technology:
Application maturity separates proven operational capabilities from emerging AI-augmented functions.
- Real-Time Data Collection:OPC UA and MQTT protocols capture millisecond-grade equipment states for immediate scheduling adjustments. German automotive assembly lines treat this as foundational infrastructure.
- Predictive Maintenance:Machine-learning models forecast bearing failures and tool wear from vibration and thermal signatures. EU AI Act documentation burdens are slowing pharmaceutical adoption in high-risk classification tiers.
- Process Automation:Closed-loop control systems enforce recipe parameters without operator intervention. Batch chemical manufacturers in Belgium and the Netherlands rely on these for reproducibility.
- Quality Management:Statistical process control modules trigger containment actions when Cpk indices drift below thresholds. Medical device producers in Massachusetts embed these for FDA 21 CFR Part 11 compliance.
- Performance Analysis:OEE calculations and downtime pareto charts expose hidden capacity. Food and beverage packagers in California use these to optimize line speeds.
Real-Time Data Collection anchors current procurement. Predictive Maintenance is climbing the fastest despite regulatory friction.
Application:
Manufacturing physics dictates data granularity requirements and validation complexity.
- Discrete Manufacturing:Unit-level tracking of individual components through assembly sequences dominates automotive and electronics. Serial number genealogy supports warranty traceability and recall containment.
- Batch Manufacturing:Lot-level reconciliation of ingredients, equipment, and operators underpins pharmaceutical compliance. Cell therapy facilities in Massachusetts require electronic batch records that paper systems cannot provide.
- Process Manufacturing:Continuous flow monitoring of temperature, pressure, and flow rates governs chemical and refining operations. Advanced process control integration is standard.
- Continuous Manufacturing:24/7 stream processing with minimal changeovers characterizes steel and cement production. MES here emphasizes energy optimization over change-control documentation.
- Job Shop Manufacturing:High-mix, low-volume environments with frequent setup changes demand flexible routing and dynamic scheduling. Tooling and fixture tracking is critical.
Discrete Manufacturing holds the deepest installed base. Batch Manufacturing is gaining share fastest on serialized compliance mandates.
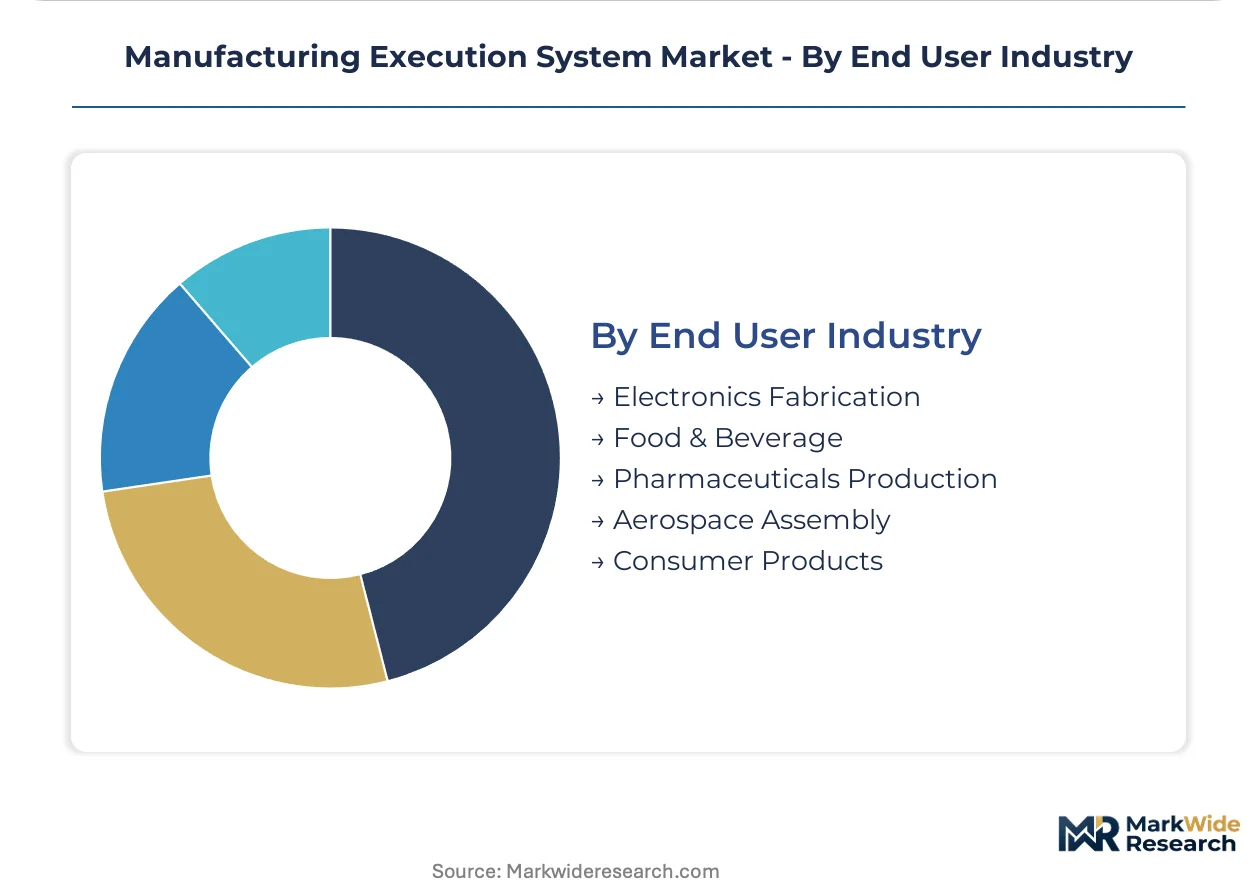
End User Industry:
Regulatory intensity and margin structure shape willingness to invest in validated MES architectures.
- Pharmaceuticals Production:FDA 21 CFR Part 11 and EU Falsified Medicines Directive compel audit trails, electronic signatures, and serialization. Validation costs run 2-3x other verticals.
- Electronics Fabrication:SMT line traceability for component sourcing and solder profile compliance drives demand. Semiconductor front-end cleanrooms require particulate monitoring integration.
- Food & Beverage:FSSAI in India and FDA FSMA in the US mandate lot traceability for allergen control and contamination response. Recipe management and label verification are core functions.
- Aerospace Assembly:AS9100 quality standards and FAA airworthiness directives enforce configuration control. Digital thread integration from design to field service is emerging.
- Consumer Products:High-volume packaging lines prioritize OEE and changeover reduction over regulatory documentation. Private label manufacturers run lean MES configurations.
Pharmaceuticals Production commands premium pricing. Electronics Fabrication is expanding most quickly on reshoring investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in Ireland and the Netherlands absorb premium pricing for validated systems, while electronics fabricators in South Korea and Vietnam drive commoditization pressures through high-volume deployments.
United States
FDA 21 CFR Part 11 enforcement compels electronic batch records and digital signatures across Massachusetts biologics facilities. The US Drug Supply Chain Security Act mandates serialized track-and-trace architectures that compress MES deployment timelines. Cell therapy production clusters in Greater Boston anchor greenfield MES contracts requiring batch-record flexibility.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg standardize on cloud-native MES to synchronize multi-site assembly operations. The EU AI Act's risk-classification framework imposes documentation burdens on machine-learning modules embedded in predictive quality systems. Siemens and SAP SE anchor industrial software ecosystems around automotive and chemical clusters in Stuttgart and Ludwigshafen.
China
NMPA alignment with international data-integrity standards drives MES adoption among domestic biologics manufacturers. Dual carbon goals accelerate energy optimization modules in steel and cement continuous manufacturing. Yangtze River Delta electronics fabricators deploy standalone MES to avoid rip-and-replace costs while scaling SMT line traceability.
India
CDSCO and FSSAI mandates for lot traceability expand MES penetration in pharmaceutical and food processing corridors. PLI scheme incentives for electronics manufacturing reshoring create demand for unit-level component tracking. Maharashtra and Gujarat pharmaceutical clusters prioritize hybrid cloud-on-premise architectures despite 18-24 month validation timelines.
Japan
METI industrial digitization programs subsidize OPC UA protocol maturation for millisecond-grade equipment interoperability. PMDA quality standards enforce audit trail capabilities comparable to FDA 21 CFR Part 11. Kanto and Kansai automotive assembly lines treat real-time data collection as foundational infrastructure for OEE optimization.
Manufacturing Execution System Market Key Industry Players
Capability concentration sits with integrated-suite vendors; scale advantage sits with automation-native specialists. The vendor base stratifies across three tiers: diversified industrial conglomerates bundling MES with PLM and ERP modules, pure-play automation vendors anchoring shop-floor execution layers, and emerging cloud-native challengers unbundling implementation from software subscriptions. Dominant competitive moves include digital thread convergence through PLM-MES integration partnerships and aftermarket service unbundling that fragments procurement patterns.
Within the integrated-suite tier, Siemens and SAP SE exemplify premium positioning through unified data models that compress pharmaceutical validation timelines. Rockwell Automation occupies a distinct automation-native position, anchoring FactoryTalk platforms in food processing and packaging operations where deep PLC integration sustains customer retention. These three vendors collectively represent the structural poles around which competitive positioning organizes—bundled enterprise suites versus purpose-built shop-floor execution layers.
| Leading Market Players |
|---|
| Siemens |
| Rockwell Automation |
| SAP SE |
| Dassault Systèmes |
| Honeywell International |
| ABB |
| Schneider Electric |
| Emerson Electric |
| General Electric |
| Others |
Cost & Logistics Intelligence
German industrial software ecosystems around Stuttgart and Ludwigshafen concentrate cloud-native MES platform development, anchoring premium margin pools where subscription models displace perpetual licenses and aftermarket service revenue rewrites vendor profitability expectations.
Pricing Analysis
Aftermarket service contracts and extended validation support tiers drive lifetime value for MES vendors as subscription SaaS models eclipse perpetual licensing. Pricing stratifies across integrated-suite premiums, standalone mid-market offerings, and economy-tier cloud-native deployments. Cost compression in standalone MES intensifies as South Korean electronics fabricators demand high-volume, low-touch deployments. Pharmaceutical manufacturers in Ireland and the Netherlands exhibit the least price sensitivity due to compressed EMA validation timelines, while mid-tier job shops in consumer products show acute sensitivity to implementation cost overruns.
Supply Chain Analysis
Supply-chain finance facilities and extended payment terms from systems integrators are becoming critical vendor selection criteria for battery gigafactory constructors facing compressed commissioning timelines. Platform development concentrates in Germany, the United States, and Japan, drawing from specialized industrial software engineering talent pools and OPC UA protocol certification ecosystems. Single-source vulnerability runs through proprietary digital twin middleware stacks that lock customers into Siemens or SAP SE architectures. Distribution runs through direct vendor sales for enterprise suites, systems integrator channels for hybrid deployments, and hyperscaler marketplaces for cloud-native SaaS procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MES market is recovering from a cyclical trough as pharmaceutical serialization mandates and battery gigafactory buildouts restock implementation pipelines after pandemic-delayed capital expenditure freezes.
For Market Incumbents: Harden cyber-physical security architectures against MQTT broker ransomware vectors that legacy air-gapped systems never faced. Deepen vertical integration into edge-computing hardware to capture containerized microservices deployment premiums. Certification investment in EU AI Act conformity assessment capabilities defends margin position against emerging cloud-native challengers stripping black-box algorithms from predictive quality modules. For New Entrants and Emerging Players: Establish a beachhead in biologics manufacturing electronic batch records, where paper-based system inadequacies create greenfield demand in Massachusetts and German cell therapy clusters. Target job shop manufacturing with Kubernetes-orchestrated modular components that reduce change-control documentation burdens. A channel partnership strategy with Bavarian automotive Tier-1 systems integrators bypasses direct competition with Siemens and SAP SE enterprise sales teams. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native MES sub-segments as SaaS delivery eliminates server infrastructure and accelerates multi-site standardization. Acquisition target archetypes include containerized microservices specialists with pharmaceutical validation expertise and OPC UA protocol-native engineering teams. The signal to watch is EU AI Act enforcement velocity in Ireland and the Netherlands, which determines whether machine-learning module documentation burdens compress predictive maintenance software valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Siemens leverages unified data models to compress pharmaceutical validation timelines under EMA guidelines. |
| Containerized Microservices Deployment | Kubernetes-orchestrated components reduce change-control documentation burdens by 60 percent for biologics producers. |
| Cloud-Native SaaS Migration | Automotive clusters in Bavaria shed server maintenance burdens through multi-site standardization on subscription models. |
| PLM-MES Convergence Partnership | Closed-loop quality feedback from field failure data to design parameters enables medical device digital thread integration. |
| Aftermarket Service Unbundling | Tier-1 suppliers in Bavaria now contract implementation through integrators while sourcing platform subscriptions directly from vendors. |
Research Approach
Initial hypotheses were tested against primary input from plant engineers, MES implementation specialists, pharmaceutical quality assurance directors, and automotive IT procurement officers and refined through secondary validation against SEC 10-K filings, EMA regulatory guidance documents, FDA 21 CFR Part 11 enforcement records, and OPC Foundation technical specifications. Bottom-up deployment counts across discrete, batch, and continuous manufacturing modes were triangulated against top-down vendor revenue segmentation.
Demand-supply balance modeling across the analysis window incorporated deployment model, organization size, manufacturing vertical, integration complexity with legacy ERP, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from slope analysis of annualized deployment velocity adjusted for qualification timeline compression in pharmaceutical applications and cloud migration acceleration in automotive clusters.
Sensitivities concentrate around EU AI Act risk-classification enforcement velocity, NMPA data-integrity standard alignment pace in China, and battery gigafactory construction timeline slippage. Forecasts reflect documented assumptions about serialization mandate deadlines and cloud infrastructure cost curves. Macroeconomic contraction, regulatory postponement, or edge-computing technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Social Networking App Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Demand Signal Repository Solutions Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Cloud Electronic Design Automation Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Self Service Technology Market
Digital Solutions
North America API Management Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Indonesia Enterprise Mobility Management Market
Digital Solutions
Mobile Command and Control Solutions Market
Digital Solutions
Game Engines Market