
 Global Connected Workplace Market | 2026-2036
Global Connected Workplace Market Size, Share, and Industry Trends Forecast 2026-2036
Global Connected Workplace Market Foresight
The EU AI Act is rebalancing the cost-of-entry calculus for vendors deploying algorithmic workforce management tools across European enterprises. Microsoft leverages its cloud infrastructure to anchor unified communications deployments in regulated industries. Siemens dominates industrial IoT integration for facility management, while Schneider Electric specializes in edge computing architectures that sustain energy-efficient connected workplace operations.
A connected workplace denotes an integrated digital ecosystem where unified communications, IoT sensors, edge computing nodes, and AI-driven analytics platforms interoperate to coordinate physical and remote work environments through real-time data exchange and automated workflow orchestration. Cloud computing solutions currently lead solution-type revenue pools, though edge computing deployments are capturing the fastest expansion as latency-sensitive applications such as augmented reality remote assistance and predictive facility maintenance proliferate. Artificial intelligence segments command premium margins in performance tracking and compliance monitoring applications, while workflow automation remains a mature category with consolidated vendor participation.
The EU AI Act, GDPR, and ISO 27001 collectively shape product standards for AI-enabled employee monitoring and cross-border data residency in connected workplace deployments. The US FDA and OSHA frameworks influence health and safety compliance for wearable-enabled workforce tracking in manufacturing environments. Stakeholders must monitor how divergent AI governance regimes across the European Union, United States, and China fragment platform certification requirements and redirect R&D investment toward modular compliance architectures.
Market Dynamics
The convergence of edge computing architectures with AI-enabled workforce analytics is compressing deployment timelines for facility-wide digitalization, forcing vendors to reconfigure service delivery models around real-time inference rather than cloud-dependent batch processing.
Growth Catalysts
- EU AI Act compliance mandates:Risk-based classification of algorithmic management tools is accelerating procurement of auditable workforce analytics platforms among German and French industrial conglomerates seeking regulatory pre-certification.
- Industrial IoT retrofit cycles:Manufacturing facilities in the United States are replacing siloed building management systems with unified sensor networks to satisfy OSHA tracking requirements for wearable-enabled safety monitoring.
- Financial services consolidation:Distributed banking operations are unifying communications and physical security infrastructure under single-vendor contracts to reduce operational fragmentation across branch networks.
Market Restraints
- Semiconductor supply concentration:Edge computing node production depends on concentrated advanced chip fabrication in Taiwan, exposing deployment schedules to geopolitical supply disruptions.
- GDPR data residency friction:Cross-border workforce analytics deployments face structural barriers from divergent member-state interpretations of lawful processing grounds for employee monitoring data.
- Legacy system entrenchment:Facility management software from the 2010s lacks API interoperability, forcing expensive middleware development for brownfield integration.
Strategic Opportunities
- India manufacturing corridor expansion:PLI scheme incentives for electronics and automotive production are creating first-mover advantage for vendors offering integrated IoT and workforce safety platforms.
- Augmented reality maintenance convergence:Real-time video annotation combined with predictive equipment diagnostics opens new service revenue streams in energy and chemical processing facilities.
- CSRD sustainability reporting:Mandatory disclosure of building energy intensity is driving demand for Schneider Electric-style edge architectures that capture granular consumption data for audit trails.
Industry Challenges
- Edge AI engineering scarcity:Deployment of on-device inference engines requires specialized firmware and embedded systems expertise that outpaces current vocational training pipelines.
- Multi-framework certification timelines:Simultaneous ISO 27001, SOC 2, and sector-specific audits for financial services clients extend sales cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Connected Workplace Market |
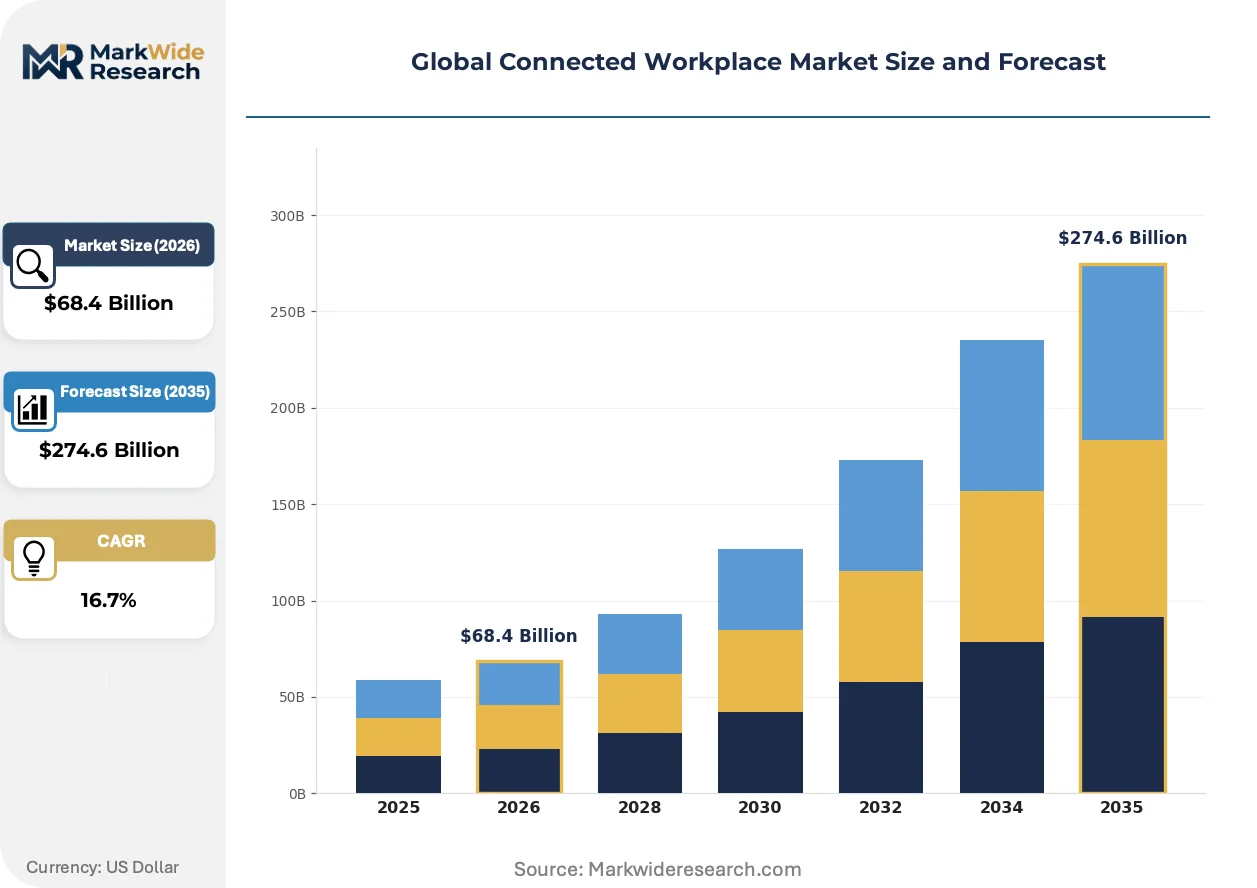
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $274.6 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Unified Communications, Collaboration Tools, IoT Integration, Workflow Automation, Analytics Platforms, Security Solutions Technology: Cloud Computing, Edge Computing, Artificial Intelligence, Augmented Reality, Virtual Reality, Blockchain Application: Remote Workforce Management, Employee Engagement, Facility Management, Resource Scheduling, Compliance Monitoring, Performance Tracking End User: Information Technology, Financial Services, Education Institutions, Government Agencies, Real Estate, Telecommunications |
| Companies Covered | Honeywell International Inc., Microsoft, Siemens, Schneider Electric, Accenture, Zebra Technologies, Oracle, Fujitsu, Tata Consultancy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Connected Workplace Market Shifts & Advancements
Workplace technology procurement is pivoting from point solutions toward unified platforms that collapse communications, security, and facilities management into single vendor relationships, compressing supplier diversity by design.
On-premise edge inference clusters are overtaking cloud-dependent analytics for latency-sensitive applications such as real-time occupancy optimization and predictive equipment failure detection. Automotive and semiconductor fabrication facilities in Japan and Germany are deploying these architectures to sub-10 millisecond response requirements. The shift is overtaking traditional SaaS pricing models and forcing vendors toward hardware-plus-software bundled contracts with multi-year service commitments.
The EU AI Act's risk classification framework for biometric and emotion recognition systems is redrawing product roadmaps for workforce monitoring vendors. High-risk system designations trigger mandatory conformity assessments and human oversight requirements that add eighteen to twenty-four months to product launch timelines. Financial services and logistics operators in France and the Netherlands are prioritizing vendors with existing EU-notified body certifications to preempt procurement delays.
Building operators are consolidating vendor relationships around integrated platform providers capable of spanning access control, energy management, and space utilization analytics through single-pane dashboards. This concentration is displacing the previous multi-point solution procurement pattern where facilities managers maintained separate contracts for security, HVAC, and IT infrastructure. The pattern is most visible in London and Singapore commercial real estate markets where landlord competition for credit-rated tenants drives amenity standardization.
Global Connected Workplace Market Segmentation
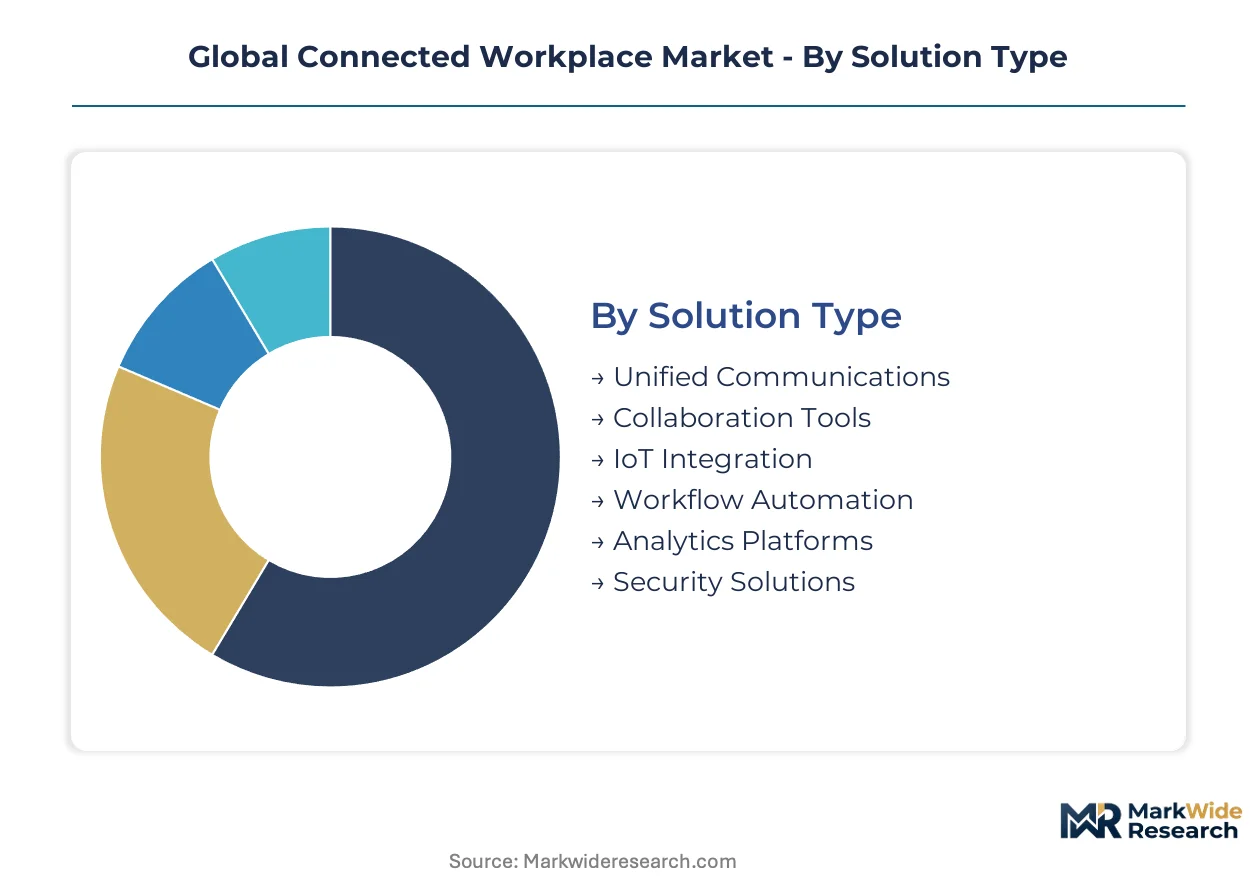
Connected workplace procurement follows distinct technology adoption curves across solution types, deployment architectures, and industry verticals. Segmentation reveals where capital expenditure concentrates and which integration patterns compress implementation timelines.
Solution Type:
Enterprise upgrade cycles favor platforms that collapse multiple operational functions into unified contracts, reducing vendor management overhead.
- Unified Communications:Voice, video, and messaging infrastructure converges under single-vendor deployments. Financial services firms in Germany and the United States prioritize these platforms to synchronize distributed trading floors and compliance recording requirements.
- IoT Integration:Sensor networks for occupancy, environmental monitoring, and equipment telemetry demand edge-native architectures. Industrial conglomerates retrofitting facilities in Japan and Germany drive demand for interoperable device management layers that bypass legacy building automation silos.
- Collaboration Tools:Document co-creation and asynchronous project management suites.
- Workflow Automation:Rules-based task orchestration and robotic process automation connectors.
- Analytics Platforms:Workforce productivity measurement and predictive operational intelligence.
- Security Solutions:Zero-trust access control and biometric identity verification systems.
Volume placements concentrate in Unified Communications; the faster expansion belongs to IoT Integration.
Technology:
Cost tier differentiation separates hyperscale cloud deployments from capital-intensive edge infrastructure requiring localized hardware investment.
- Cloud Computing:Centralized SaaS delivery models dominate initial digital workplace rollouts. Mid-market enterprises in France and Singapore default to cloud-native architectures to avoid data center capital expenditure and accelerate procurement cycles.
- Edge Computing:Sub-50 millisecond latency requirements for augmented reality assistance and predictive maintenance push compute closer to facilities. Automotive fabrication plants in Germany and semiconductor cleanrooms in Japan deploy on-premise inference clusters to satisfy real-time safety monitoring mandates.
- Artificial Intelligence:Algorithmic workforce scheduling and sentiment analysis engines.
- Augmented Reality:Remote expert guidance and spatial training overlays for field technicians.
- Virtual Reality:Immersive onboarding and hazardous environment simulation modules.
- Blockchain:Credential verification and audit trail immutability for compliance documentation.
Cloud Computing captures the largest installed base; Edge Computing is climbing the fastest as latency-sensitive manufacturing applications proliferate.
Application:
Customer type stratification separates regulated industries with mandatory audit trails from commercial sectors prioritizing employee experience metrics.
- Facility Management:Integrated HVAC, lighting, and access control through unified building operating systems. Commercial real estate operators in London and Singapore consolidate these functions to attract credit-rated tenants demanding sustainability certification and flexible space utilization.
- Compliance Monitoring:Automated capture of workforce safety data and regulatory reporting workflows. OSHA-tracked manufacturing environments in the United States and EU AI Act-governed employee monitoring in France drive procurement of auditable analytics platforms with human oversight architectures.
- Remote Workforce Management:Distributed team coordination and productivity visibility tools.
- Employee Engagement:Pulse surveys and recognition platforms for retention analytics.
- Resource Scheduling:Dynamic desk and meeting space allocation systems.
- Performance Tracking:Individual and team output measurement with benchmarking dashboards.
Facility Management holds the deepest current penetration; Compliance Monitoring is gaining share fastest as regulatory enforcement tightens across the European Union and United States.
End User:
Margin structures vary sharply between price-sensitive education procurement and premium-priced financial services contracts with dedicated compliance modules.
- Financial Services:Unified trading floor communications, surveillance recording, and physical security integration. Banks in Germany and the United States consolidate these capabilities under single-vendor relationships to reduce operational fragmentation across branch networks and satisfy SEC and BaFin retention requirements.
- Information Technology:Internal technology workforce enablement and developer collaboration infrastructure.
- Education Institutions:Hybrid learning platforms and campus safety systems with constrained capital budgets.
- Government Agencies:Classified and unclassified network separation with FedRAMP or equivalent certification.
- Real Estate:Landlord-facing building automation and tenant experience platforms.
- Telecommunications:Field technician dispatch and network operations center coordination tools.
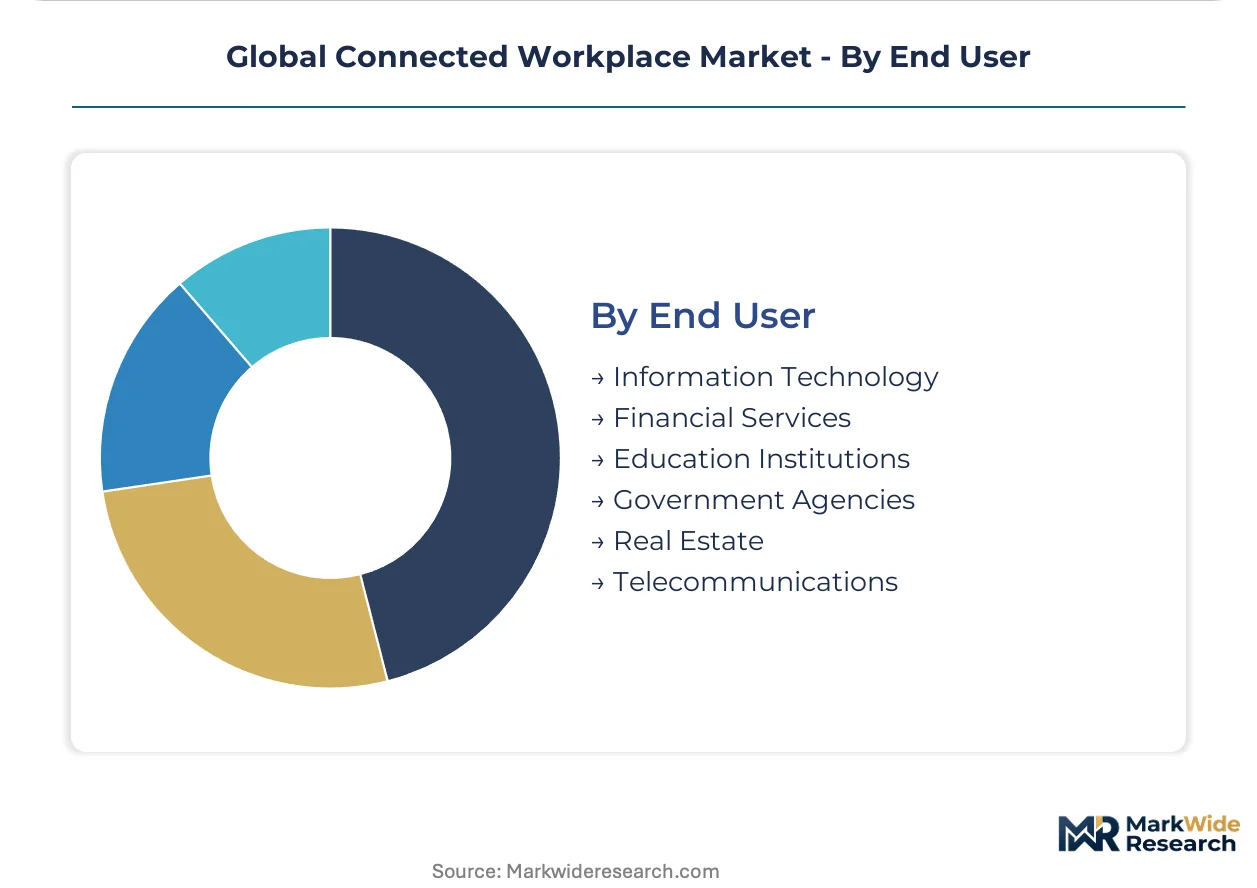
Contract value concentrates in Financial Services; the steepest expansion trajectory belongs to Real Estate as commercial landlords compete on amenity standardization in London, Singapore, and New York.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial conglomerates currently concentrate procurement of integrated IoT and edge computing infrastructure, while financial services firms in the United States and United Kingdom accelerate unified communications deployments to synchronize distributed operations.
United States
OSHA-tracked manufacturing environments drive wearable-enabled safety monitoring procurement, while SEC retention requirements push financial services toward unified surveillance recording platforms. The FDA and OSHA frameworks jointly influence health and safety compliance standards for workforce tracking systems. Automotive fabrication plants in Michigan and semiconductor cleanrooms in Arizona deploy on-premise edge inference clusters to satisfy sub-10 millisecond response requirements for predictive maintenance.
Germany
Industrial IoT retrofit cycles dominate capital allocation as conglomerates replace siloed building management systems with unified sensor networks. The EU AI Act's risk-based classification framework triggers mandatory conformity assessments for algorithmic workforce management tools. Manufacturing clusters in Bavaria and Baden-Württemberg anchor demand for Schneider Electric-style edge architectures that capture granular energy consumption data for CSRD audit trails.
United Kingdom
Commercial real estate operators in London consolidate vendor relationships around integrated platform providers spanning access control, energy management, and space utilization analytics. GDPR data residency requirements create structural barriers for cross-border workforce analytics deployments. The Southeast and Midlands regions concentrate landlord competition for credit-rated tenants demanding sustainability certification and flexible space utilization through single-pane dashboards.
Japan
Automotive and semiconductor fabrication facilities deploy on-premise edge inference clusters to satisfy real-time safety monitoring mandates with sub-50 millisecond latency requirements. METI standards shape building energy intensity disclosure frameworks that drive demand for granular consumption data capture. The Kanto region around Tokyo and the Chubu region around Nagoya anchor deployment of augmented reality remote assistance systems for field technician guidance.
India
PLI scheme incentives for electronics and automotive production create first-mover advantage for vendors offering integrated IoT and workforce safety platforms. BIS certification requirements shape product standards for sensor networks and edge computing nodes entering government and enterprise procurement. Manufacturing corridors in Maharashtra and Gujarat concentrate new facility construction with native connected workplace architectures rather than brownfield retrofit cycles.
Global Connected Workplace Market Competitive Landscape
United States-based hyperscale cloud providers anchor one tier; European industrial technology specialists hold differentiated positions in facility management and energy-efficient edge architectures. The vendor base organizes around three strategic archetypes: cloud-native unified communications platforms, industrial IoT integration specialists, and edge computing infrastructure providers. Competitive dynamics center on M&A activity to collapse communications, security, and facilities management capabilities, alongside strategic partnerships to satisfy multi-framework certification requirements.
Within the cloud-native tier, Microsoft exemplifies the unified communications archetype through infrastructure deployments in regulated industries. Siemens and Schneider Electric occupy complementary positions in industrial IoT integration and edge computing architectures respectively, representing the European industrial technology specialist cluster. These three anchors illustrate how procurement is pivoting from point solutions toward unified platforms that compress supplier diversity by design.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Microsoft |
| Siemens |
| Schneider Electric |
| Accenture |
| Zebra Technologies |
| Oracle |
| Fujitsu |
| Tata Consultancy Services |
| Others |
Supply & Pricing Matrix
Semiconductor wafer pricing indices cascade through connected workplace hardware tiers, compressing margins on edge computing nodes while amplifying premium capture for AI-enabled analytics platforms with firmware-level optimization.
Pricing Analysis
Volume placements concentrate in standardized cloud SaaS tiers with thin margins, while edge-native deployments with sub-10 millisecond latency guarantees command substantial premiums. Pricing stratifies across certified compliance tiers, with EU AI Act pre-certified platforms capturing margin premiums against uncertified alternatives. Cost compression in mid-market unified communications stems from hyperscaler bundling strategies. Education institutions exhibit acute price sensitivity, whereas financial services firms prioritize audit-grade certification over unit cost.
Supply Chain Analysis
Specialized edge AI engineering talent shortages in Taiwan, Germany, and Japan constrain firmware development velocity for on-premise inference clusters. Advanced node fabrication draws from concentrated Taiwanese foundry capacity, while sensor component sourcing rests on South Korean and Chinese manufacturing bases. Single-source vulnerability in 7nm and below chip supply exposes deployment timelines to geopolitical disruption. Distribution runs through systems integrators with multi-framework certification capabilities, particularly for financial services and government verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The connected workplace market is becoming a vertical-integration race, with control over edge computing hardware and AI inference firmware emerging as the decisive margin lever.
For Market Incumbents: Anchor market position through captive edge hardware production and exclusive workforce analytics algorithm development. Microsoft exemplifies cloud-to-edge integration leverage, while Siemens and Schneider Electric demonstrate industrial IoT control advantages. Defensive consolidation around multi-framework certification capabilities—ISO 27001, SOC 2, EU AI Act conformity—creates procurement friction against unqualified entrants. Threat substitution from hyperscaler bundling demands proprietary firmware differentiation to escape commodity SaaS pricing. For New Entrants and Emerging Players: Systems integrators with existing industrial relationships represent the most accessible channel leverage point for platform penetration. White-space concentration appears in India's PLI-funded manufacturing corridors, where greenfield facility construction bypasses legacy system entrenchment. Mid-market commercial real estate in Southeast Asian gateway cities offers lower competitive density than saturated London and Singapore markets. A compliance-first go-to-market targeting EU AI Act pre-certification requirements accelerates procurement access in France and Germany. For Investors and Strategic Acquirers: Distressed-cycle entries favor edge computing hardware specialists with established automotive or semiconductor fabrication customer relationships in Germany and Japan. Long-term viability over the next decade hinges on modular compliance architectures that adapt to divergent AI governance regimes across the European Union, United States, and China. Acquisition target archetypes include workforce analytics vendors with existing EU-notified body certifications and edge firmware engineering teams with automotive safety-critical systems experience. Watch for CSRD enforcement tightening as the signal triggering accelerated building energy intensity platform procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Hardware Vertical Integration | Captive production of inference nodes secures margin control against foundry pricing volatility. |
| EU AI Act Pre-Certification | Existing conformity assessments compress sales cycles by eighteen to twenty-four months in regulated European procurement. |
| Systems Integrator Partnership | Channel relationships with multi-framework certified integrators unlock financial services and government vertical access. |
| AR Maintenance Convergence | Real-time video annotation combined with predictive diagnostics opens service revenue in energy and chemical processing. |
| CSRD Compliance Module Development | Granular building energy capture capabilities satisfy mandatory sustainability disclosure requirements in European commercial real estate. |
Research Methodology
SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory notification databases formed the secondary backbone for vendor revenue and deployment scale estimation. Primary interviews with facility management directors, IT procurement officers, edge computing platform engineers, and systems integration specialists validated technology adoption timelines and procurement decision criteria. Bottom-up triangulation across named vendor contract values and top-down cross-checks against vertical expenditure patterns ensured segmentation integrity.
Historical trendline analysis of cloud and edge infrastructure deployment velocities established baseline growth parameters across the projection horizon. Segmentation modeling incorporated solution type, deployment architecture, industry vertical, and regional regulatory cluster dimensions. CAGRs derived from curve-fitting across technology adoption S-cycles, with specific adjustment for EU AI Act implementation friction and semiconductor supply concentration effects.
Several conditions sit outside the modeled scope, including extreme geopolitical supply disruptions, abrupt regulatory framework reversals, and breakthrough quantum computing displacement of classical edge inference. Forecasts reflect documented assumptions regarding compliance timeline adherence and foundry capacity expansion trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Echo Reduction Software Market
Digital Solutions
India PLM Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Bangladesh ICT Market
Digital Solutions
Labor Management System in Retail Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Business As a Service Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
Electronic Document Management System (EDMS) Market
Digital Solutions
Digital Pen Market
Digital Solutions
Global Sharing Economy Market
Digital Solutions
Canada Digital Twin Market
Digital Solutions
Global Commerce Cloud Solution Market
Digital Solutions
Poland ICT Market
Digital Solutions
Business Document Work Process Management Market
Digital Solutions
Data Converter Market