

Chitosan Films Market Size, Share, and Industry Trends Forecast 2026-2036
Chitosan Films Market Insights
Market Context
Asian crustacean-processing hubs is decoupling from traditional gelatin supply chains as chitosan extraction scales. Primex leverages its Nordic marine-resource network to secure consistent raw material flows. KitoZyme sustains fermentation-based production in Belgium, reducing seasonal dependency on shell waste. Heppe Medical Chitosan specializes in pharmaceutical-grade purification, occupying a narrow but high-margin segment.
Technical and Segment Structure
Chitosan films comprise deacetylated chitin matrices, typically exhibiting 70-95% deacetylation, formed through solvent-casting or electrospinning into barrier layers with oxygen permeability below 10 cc/m²/day. Composite films and functionalized variants command structural attention due to their integration of antimicrobial agents and active packaging functionality, where margin pools concentrate among pharmaceutical and food-grade certifications. Dry film formulations dominate current output, though gel films are gaining traction in wound-care applications where moisture retention parameters determine clinical acceptance.
Regulatory Environment and Outlook
EMA pharmaceutical-grade standards, EU Green Deal biodegradability mandates, and FDA food-contact notifications collectively shape product specifications and market access pathways for chitosan film producers. REACH compliance for residual protein content and EFSA novel food assessments add layers of analytical burden that favor laboratories with established regulatory dossiers. Stakeholders must monitor evolving compostability certification requirements across multiple jurisdictions to anticipate qualification timelines.
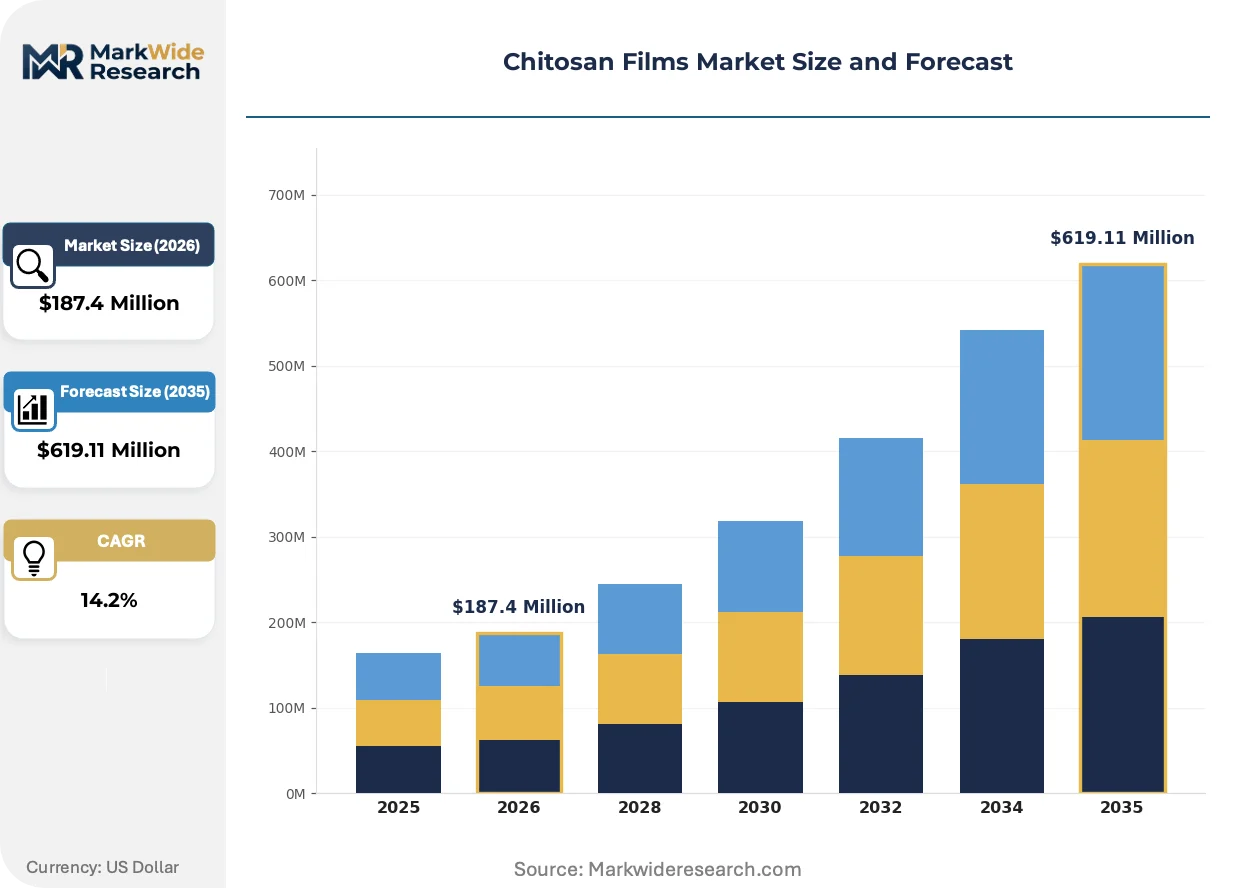
Market Dynamics
EU Green Deal biodegradability mandates are compressing gelatin and synthetic polymer film margins while concentrating chitosan supply contracts among certified European processors. This regulatory pressure is restructuring raw material procurement and end-use qualification timelines simultaneously.
Growth Catalysts
- EU Green Deal packaging mandates:The framework's 2030 reduction targets for single-use plastics are redirecting food-contact film procurement toward chitosan alternatives in Germany, France, and the Netherlands.
- Antimicrobial functionalization:Integration of nisin and ε-polylysamine into chitosan matrices is opening active packaging applications for fresh protein and dairy segments.
- Wound care moisture retention:Gel film formulations with controlled hydration profiles are displacing hydrocolloid dressings in hospital procurement across Japan and South Korea.
Market Restraints
- Crustacean shell supply seasonality:Asian shrimp and crab processing cycles create raw material availability gaps that fermentation-based alternatives have not fully closed.
- Pharmaceutical-grade purification costs:EMA residual protein limits below 0.2% require multi-stage ultrafiltration that doubles unit production costs against food-grade equivalents.
- Cellulose nanocrystal substitution:Wood-derived barrier films with comparable oxygen permeability are capturing price-sensitive packaging segments in Nordic markets.
Strategic Opportunities
- Brazilian aquaculture waste valorization:Shrimp farming expansion in Ceará and Rio Grande do Norte is generating untapped chitin feedstock for regional film production.
- Electrospun nanofiber membranes:Convergence of electrospinning with 3D bioprinting scaffolds is creating tissue engineering applications beyond traditional film formats.
- Compostability certification harmonization:Pending ISO 17088 alignment across EU member states will streamline multi-jurisdiction product qualification for exporters.
Industry Challenges
- Deacetylation control expertise:Narrow 70-95% specification windows require process engineers with rare cross-training in polymer chemistry and marine biochemistry.
- REACH dossier compilation timelines:ECHA substance registration for novel chitosan derivatives extends market entry by 18-24 months for mid-scale producers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chitosan Films Market Trends and Innovations
Active packaging functionality is migrating from premium pharmaceutical films toward mid-tier food applications as antimicrobial integration costs decline. This shift is compressing traditional passive barrier film margins while opening new formulation service revenue streams.
Layer-by-layer assembly of chitosan with alginate or pectin polyelectrolytes is electrifying multilayer barrier design for oxygen-sensitive pharmaceuticals. Contract manufacturers in Switzerland and Germany are adopting these deposition systems to serve specialty drug packaging contracts. The technology is compressing conventional co-extrusion equipment utilization rates among legacy film producers.
REACH Annex XVII amendments on microplastic labeling are forcing explicit biodegradability claims verification for film products entering EU distribution. Laboratory accreditation requirements for OECD 301B testing are consolidating analytical service contracts among three specialized European providers. Pharmaceutical-grade film exporters are responding by pre-certifying compostability through TÜV Austria and DIN CERTCO before commercial launch.
Buyer consolidation among European supermarket private-label programs is shifting procurement toward direct manufacturer relationships and away from regional distributors. Lidl and Aldi Süd are negotiating multi-year chitosan film supply agreements with specified volume tiers and quality audits. This channel compression is most visible in Germany, where centralized buying desks now control 60% of biodegradable produce bag specifications.
Chitosan Films Market Segmentation
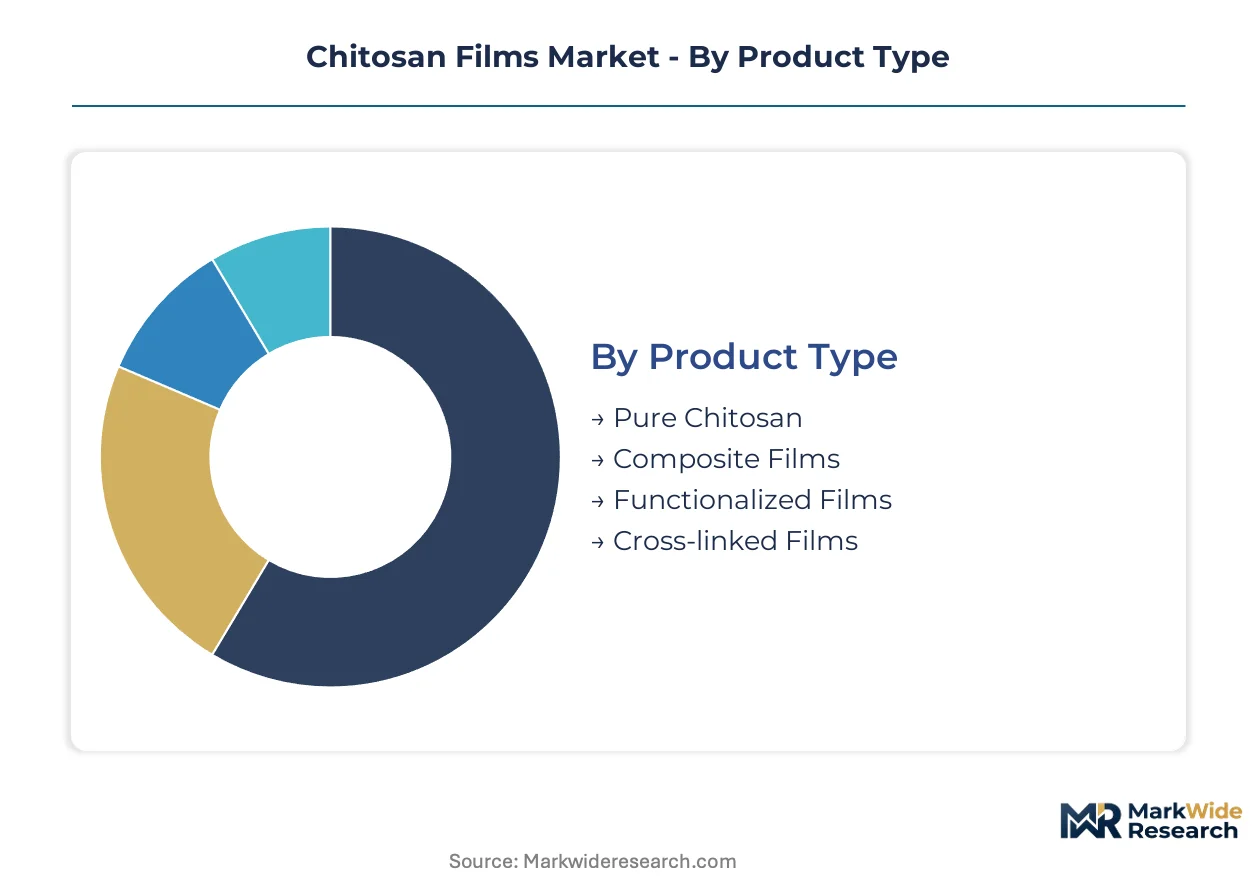
Chitosan film producers face divergent margin profiles across product architectures and end-use certifications. Segmentation reveals where pharmaceutical-grade purification commands premium pricing versus food-contact volume plays.
Product Type:
Purchasing specifications split between commodity-grade films and functionalized variants requiring active ingredient integration.
- Composite Films:Blend chitosan with cellulose, alginate, or pectin matrices to tune mechanical strength and barrier properties. German pharmaceutical packaging contracts and Japanese wound-care procurement drive specification intensity here, with EMA residual protein limits determining supplier qualification.
- Functionalized Films:Incorporate antimicrobial agents such as nisin or ε-polylysamine for active packaging functionality. Fresh protein retail programs in France and the Netherlands specify these for extended shelf-life claims under EU Green Deal biodegradability mandates.
- Pure Chitosan:Single-polymer matrices with 70-95% deacetylation, serving cost-sensitive barrier applications where oxygen permeability below 10 cc/m²/day suffices.
- Cross-linked Films:Chemical or enzymatic cross-linking enhances moisture resistance for agricultural coating applications against rainfall exposure.
Composite films lead volumes today; functionalized variants are gaining share fastest.
Application:
End-use requirements range from passive oxygen barriers to moisture-retentive therapeutic interfaces.
- Food Packaging:Biodegradable produce bags and protein trays dominate procurement volumes. Lidl and Aldi Süd centralized buying desks in Germany now specify chitosan alternatives for 60% of private-label biodegradable packaging, compressing regional distributor margins.
- Wound Dressings:Gel film formulations with controlled hydration profiles displace hydrocolloid dressings in hospital procurement across Japan and South Korea, where moisture retention parameters determine clinical acceptance.
- Agricultural Coatings:Seed treatment and controlled-release fertilizer applications leverage chitosan's natural antimicrobial properties against soil-borne pathogens.
- Water Treatment:Heavy metal chelation and flocculation applications use lower-grade chitosan films where pharmaceutical purity is unnecessary.
Food packaging commands the largest revenue pool; wound dressings exhibit the steepest expansion trajectory.
End User:
Certification burdens separate pharmaceutical-grade buyers from commodity procurement.
- Pharmaceutical Manufacturers:Require EMA pharmaceutical-grade standards with residual protein below 0.2%, doubling unit production costs through multi-stage ultrafiltration. Heppe Medical Chitosan and Swiss contract manufacturers specialize here.
- Food Processors:Demand FDA food-contact notifications and EFSA novel food assessments, with REACH compliance for residual protein content adding analytical burden.
- Agricultural Producers:Price-sensitive buyers accepting broader specification windows for seed coating and crop protection films.
- Water Purification Firms:Industrial-scale procurement prioritizing throughput over film uniformity, sourcing from Asian crustacean-processing hubs.
Pharmaceutical manufacturers pay the highest unit prices; food processors generate the greatest aggregate demand.
Form:
Physical state determines manufacturing method and end-use handling requirements.
- Dry Film:Solvent-cast or electrospun matrices dominate current output, formed through evaporation of acetic acid or formic acid solutions. Standard format for food packaging and passive barrier applications.
- Gel Film:Hydrated formulations with controlled moisture retention for wound-care applications. Layer-by-layer assembly with alginate polyelectrolytes enables multilayer barrier design for oxygen-sensitive pharmaceuticals in Swiss and German contract manufacturing.
- Coated Film:Surface-modified substrates where chitosan functions as an active top layer on conventional polymer films during transition periods.
- Laminated Film:Multi-layer constructions combining chitosan with synthetic or natural polymers for enhanced mechanical performance.
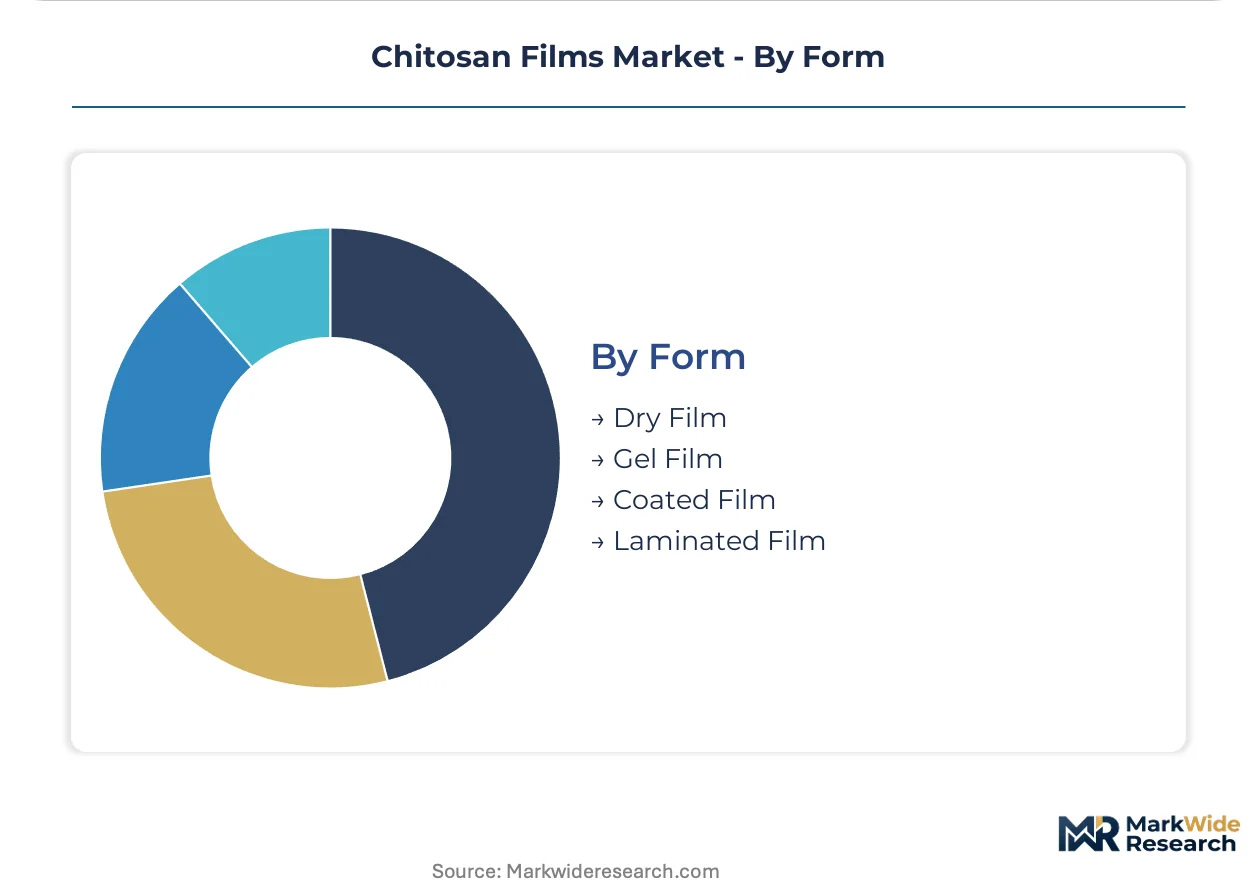
Dry films anchor production volumes today; gel films are climbing the fastest as wound-care adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Producers are arbitraging compliance costs by migrating pharmaceutical-grade purification to jurisdictions with established EMA dossier pathways, while food-grade manufacturing concentrates near Asian crustacean processing clusters to capture raw material proximity advantages.
Germany
EMA pharmaceutical-grade certification requirements concentrate high-margin production around Hamburg and Berlin, where multi-stage ultrafiltration capabilities serve specialty drug packaging contracts. The EU Green Deal's 2030 single-use plastic reduction targets redirect Lidl and Aldi Süd procurement toward biodegradable alternatives. Pharmaceutical and food-grade film producers cluster in these metropolitan regions to access centralized buying desks controlling 60% of private-label specifications.
Belgium
Fermentation-based chitosan production reduces seasonal dependency on shell waste, sustaining year-round output for wound-care gel film formulations. EFSA novel food assessments and REACH compliance requirements favor established laboratories with regulatory dossiers. KitoZyme's operations exemplify how biotechnology hubs around Brussels-Leuven anchor alternative supply chains independent of Asian crustacean cycles.
Japan
Gel film formulations with controlled hydration profiles displace hydrocolloid dressings in hospital procurement across Tokyo-Osaka corridors, where moisture retention parameters determine clinical acceptance. METI standards for medical device materials shape product qualification timelines. Electrospun nanofiber membrane development converges with 3D bioprinting scaffold applications in Kansai region research institutes.
South Korea
MFDS pharmaceutical-grade specifications drive wound-care film adoption in Seoul metropolitan hospital networks, where gel film moisture retention benchmarks exceed conventional dressing performance. Active packaging antimicrobial integration serves fresh protein retail programs with extended shelf-life claims. Domestic producers leverage proximity to Japanese technical standards while competing on cost structures.
Brazil
Shrimp farming expansion in Ceará and Rio Grande do Norte generates untapped chitin feedstock for regional film production, though ANVISA pharmaceutical-grade pathways remain underdeveloped compared to European benchmarks. Aquaculture waste valorization opportunities attract investment toward food-grade packaging applications. Raw material availability advantages position northeastern states for export-oriented manufacturing if certification harmonization advances.
Chitosan Films Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fermentation-based and electrospun nanofiber specializations to bypass crustacean supply seasonality. Market structure reflects a bifurcation between pharmaceutical-grade purifiers with EMA-compliant dossiers and food-grade volume producers competing on raw material proximity. Three archetypes dominate: crustacean-extraction specialists with Asian supply networks, fermentation-based biotechnology platforms, and pharmaceutical-grade contract manufacturers with ultrafiltration capabilities. Capacity expansion and strategic partnerships constitute the primary competitive moves, with layer-by-layer assembly technology licensing gaining traction among Swiss and German contract manufacturers.
Within the pharmaceutical-grade tier, Heppe Medical Chitosan occupies a position exemplifying EMA residual protein limit compliance below 0.2%. Primex represents Nordic marine-resource network leverage for consistent raw material flows. KitoZyme anchors fermentation-based production archetypes that reduce seasonal dependency. These three entities collectively illustrate how certification intensity and supply chain architecture determine competitive positioning across divergent margin pools.
| Leading Market Players |
|---|
| Primex |
| KitoZyme |
| Heppe Medical Chitosan |
| Golden-Shell Pharmaceutical |
| Qingdao Yunzhou Biochemistry |
| Panvo Organics |
| G.T.C. Bio Corporation |
| Advanced Biopolymers |
| Agratech International |
| Others |
Pricing and Supply Chain Analysis
Centralized buying desks at Lidl and Aldi Süd now control sixty percent of biodegradable produce bag specifications in Germany, forcing supply chain reconfiguration toward direct manufacturer relationships and compressing distributor margins across food-grade film tiers.
Pricing Analysis
Distributor margin compression dominates the channel economics as retailer direct procurement eliminates intermediaries. Three-tier pricing structure across pharmaceutical, food-grade, and industrial certifications separates EMA-compliant ultrafiltration products from commodity barrier films. Pricing pressure stems from cellulose nanocrystal substitution in Nordic packaging segments. Agricultural producers exhibit highest price sensitivity; pharmaceutical manufacturers accept premium positioning for residual protein compliance below 0.2%.
Supply Chain Analysis
Freight cost differentials between Asian crustacean hubs and European fermentation facilities are narrowing as biotechnology platforms scale. Raw material procurement draws from Vietnamese shrimp processing cycles, Chinese crab waste streams, and Brazilian aquaculture expansion in Ceará. Single-source vulnerability persists in pharmaceutical-grade ultrafiltration equipment. Distribution runs through specialized chemical distributors for food-grade volumes and direct contracts for pharmaceutical certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade purification and active packaging functionalization as antimicrobial integration costs decline and EMA certification scarcity persists.
For Market Incumbents: Hedge against cellulose nanocrystal substitution by deepening backward integration into Nordic marine-resource networks and securing multi-year supply agreements with centralized retail procurement desks. Invest in layer-by-layer assembly licensing to defend positioning in oxygen-sensitive pharmaceutical packaging against conventional co-extrusion competitors. For New Entrants and Emerging Players: Enter via Brazilian aquaculture waste valorization in Rio Grande do Norte, where ANVISA pathway underdevelopment creates temporary regulatory arbitrage for food-grade export manufacturing. Target wound-care gel film formulations in Japanese hospital procurement, where moisture retention specifications exceed hydrocolloid dressing performance and create specification-driven entry points. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation-based biotechnology platforms that eliminate crustacean supply seasonality while maintaining EFSA novel food dossier capabilities. Long-term viability favors producers with dual pharmaceutical and food-grade certification infrastructure. Watch electrospun nanofiber membrane adoption in tissue engineering as inflection signal beyond traditional film formats.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Marine Feedstock | Primex-style Nordic resource networks secure consistent raw material flows against Asian seasonality. |
| Layer-by-Layer Assembly Licensing | Swiss and German contract manufacturers adopt polyelectrolyte deposition for oxygen-sensitive drug packaging. |
| Active Packaging Functionalization | Nisin and ε-polylysamine integration opens fresh protein retail programs under EU Green Deal mandates. |
| Fermentation Platform Scale-Up | KitoZyme-model biotechnology reduces dependency on shrimp and crab processing cycles. |
| Compostability Pre-Certification | TÜV Austria and DIN CERTCO qualification streamlines multi-jurisdiction EU market entry timelines. |
Research Methodology
Direct dialogue with pharmaceutical packaging procurement managers, food-grade film plant engineers, regulatory affairs specialists at EMA-notified bodies, and crustacean processing facility operators grounded qualitative findings. Secondary validation drew from EMA pharmaceutical-grade standards documentation, EFSA novel food assessment registers, REACH Annex XVII amendment filings, and EU Green Deal implementation progress reports. Bottom-up volume estimates from grade-specific production capacities triangulated against top-down market sizing from end-use demand aggregation.
Segmented outputs across pharmaceutical, food packaging, wound care, and agricultural coating applications combined with form-based splits between dry, gel, coated, and laminated film architectures. Deacetylation specification bands, residual protein compliance tiers, and oxygen permeability thresholds informed unit economics modeling. CAGRs derived from regression analysis against EU single-use plastic reduction targets and antimicrobial integration cost curves.
Inputs from EMA certification databases and Brazilian aquaculture production statistics were available through the study window; gaps in ANVISA pharmaceutical-grade pathway documentation introduce uncertainty bands for South American market sizing. Forecasts reflect assumptions about regulatory harmonization timelines and substitution elasticity from cellulose-derived barrier films. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.