
 Global Clinical Trial Consumables Market | 2026-2036
Global Clinical Trial Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Trial Consumables Market Foresight
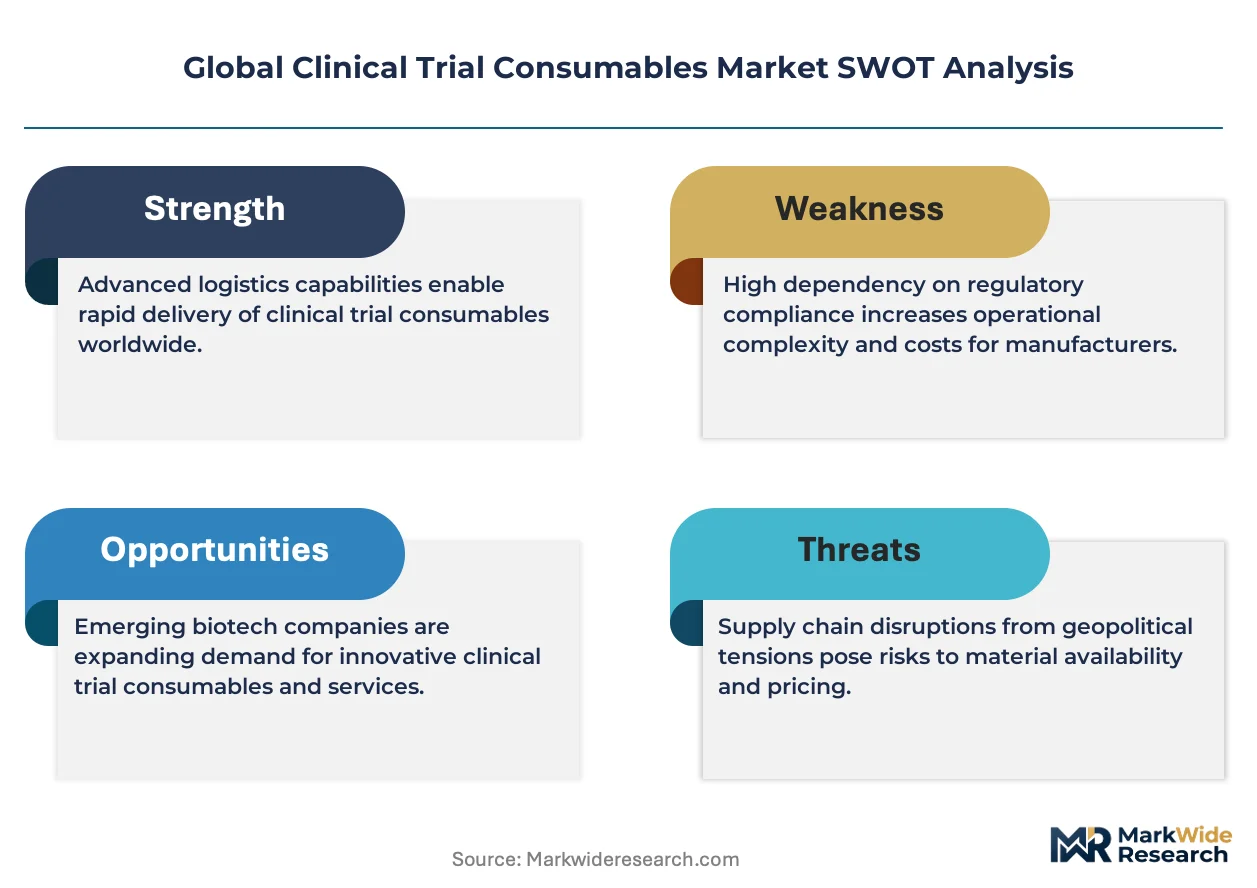
The EU Medical Device Regulation is expanding compliance burdens for single-use clinical supplies across European trial networks. Thermo Fisher Scientific Inc. leverages its integrated supply chain to pre-validate consumable kits for multinational protocols. Catalent Inc. anchors its competitive position through specialized cold-chain packaging for cell therapy trials. Agilent Technologies differentiates via analytical-grade consumables that meet stringent chromatography validation requirements.
Clinical trial consumables encompass sterile and non-sterile single-use items—polypropylene sampling tubes, borosilicate glass vials, latex and nitrile examination gloves, and intravenous administration sets—manufactured under ISO 13485 quality systems and gamma-sterilized to SAL 10^-6 for parenteral applications. These products enable patient safety, sample integrity, and protocol standardization across investigative sites. Syringes and sampling tubes command the largest volume share due to universal protocol requirements, while sterile packaging carries the steepest margin premium as sponsors prioritize tamper-evident integrity for temperature-sensitive biologics. Phase III trials drive the highest absolute consumable throughput because of their multi-thousand patient enrollment scales and extended duration.
The FDA enforces Current Good Manufacturing Practice for finished pharmaceuticals, directly governing consumable sterility assurance and supplier qualification. The EMA's Clinical Trials Regulation harmonizes investigational medicinal product labeling and accountability, reshaping kit assembly and distribution workflows across EU member states. China's NMPA accelerates local manufacturing audits for imported consumables used in multinational trials. Stakeholders must monitor divergent sterilization validation requirements between FDA 510(k) and EU MDR pathways when selecting dual-market suppliers.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing supplier qualification timelines while biopharmaceutical sponsors simultaneously expand decentralized trial footprints, creating a structural tension between compliance burden and operational flexibility.
Growth Catalysts
- Regulatory Harmonization:The EMA's Clinical Trials Regulation streamlines investigational medicinal product labeling across EU member states, reducing kit assembly complexity for sponsors running multinational protocols.
- Cell Therapy Expansion:Autologous and allogeneic cell therapies require specialized single-use consumables with validated cold-chain integrity, pulling demand for gamma-sterilized packaging and temperature-monitoring devices.
- China NMPA Acceleration:Local manufacturing audits for imported consumables used in multinational trials are expediting market entry timelines for Western suppliers establishing domestic production.
Market Restraints
- Polypropylene Feedstock Volatility:Resin price fluctuations directly compress margins on high-volume consumables like sampling tubes and syringes where contract pricing locks are prevalent.
- Gamma Sterilization Bottleneck:Cobalt-60 supply concentration and irradiation facility capacity constraints in North America and Western Europe create scheduling risks for SAL 10^-6 validation.
- EU MDR Technical Documentation:The expanded clinical evidence requirements for Class I reusable surgical instruments are spilling into consumable supplier qualification protocols, extending onboarding cycles.
Strategic Opportunities
- Decentralized Trial Infrastructure:Direct-to-patient shipping models create white space for pre-validated, patient-centric consumable kits with embedded temperature loggers and simplified disposal protocols.
- India CDSCO Manufacturing Incentives:The Production Linked Incentive scheme for pharmaceuticals is attracting consumable suppliers to establish ISO 13485-certified facilities serving Asia-Pacific trial networks.
- Real-Time Release Testing:Rapid microbiological methods and automated visual inspection are converging to enable parametric release, compressing inventory holding periods for sterile consumables.
Industry Challenges
- ISO 13485 Auditor Scarcity:Qualified third-party auditors for medical device quality management systems are concentrated in Germany and the United States, creating certification backlogs for emerging market suppliers.
- Legacy ERP Integration:Sponsor demand for serialized traceability data requires consumable suppliers to retrofit manufacturing execution systems with unit-level aggregation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Trial Consumables Market |
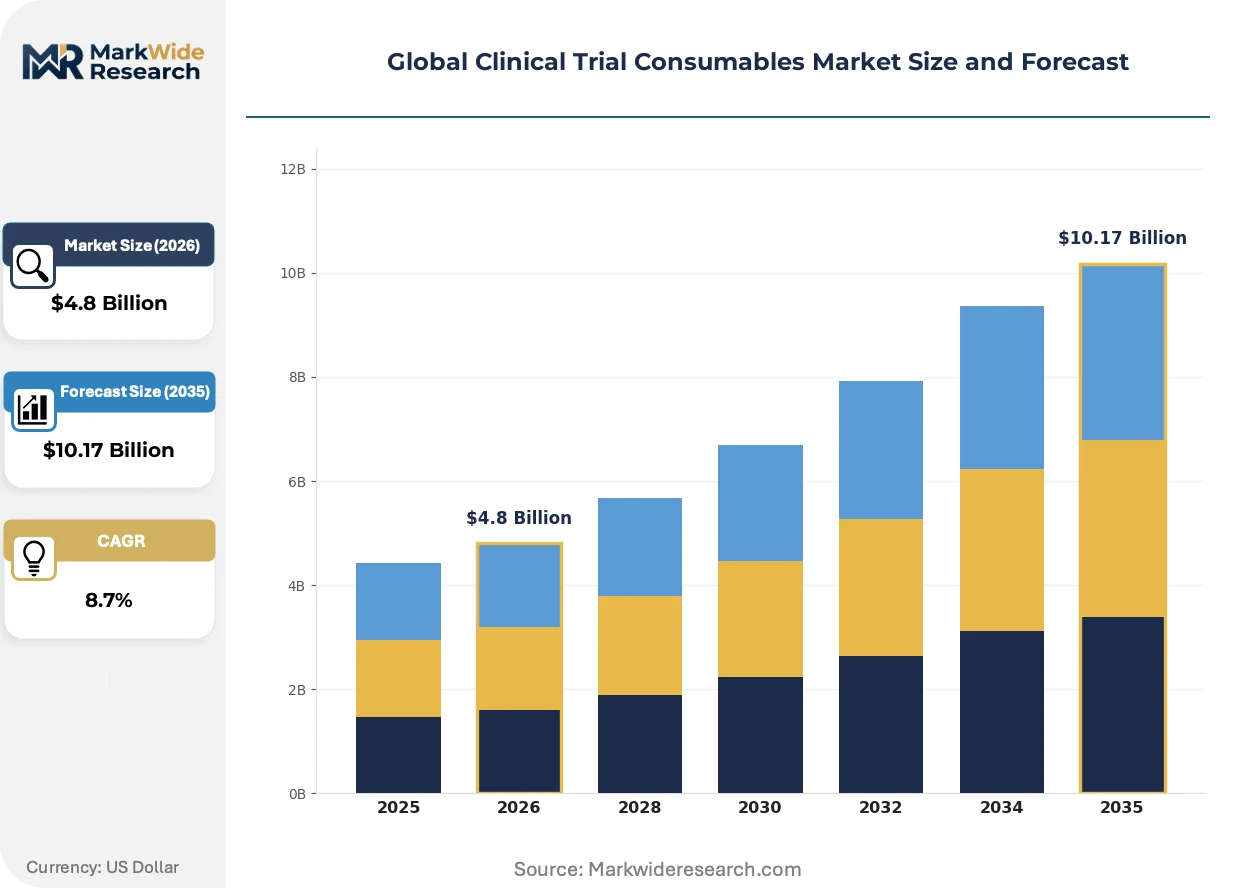
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Vials, Sampling Tubes, IV Sets, Gloves, Blood Bags Application: Phase I Trials, Phase II Trials, Phase III Trials, Bioequivalence Studies, Safety Studies End User: Clinical Research Organizations, Contract Manufacturing Organizations, Pharmaceutical Companies, Biotech Firms, Diagnostic Laboratories Packaging Type: Primary Packaging, Secondary Packaging, Sterile Packaging, Tamper-Evident Packaging, Bulk Packaging |
| Companies Covered | Thermo Fisher Scientific Inc., Almac Group, Catalent Inc., Parexel International Corporation, Agilent Technologies, Biocair, United Parcel Service of America, Inc., Sharp Services, KLIFO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Trial Consumables Market Shifts & Advancements
Digital serialization and sustainable material transitions are actively reshaping competitive positioning in clinical trial consumables, compressing traditional procurement cycles while elevating technical qualification thresholds.
Pre-sterilized, ready-to-use (RTU) vials and closure systems are consolidating vendor relationships in parenteral drug trials. Biopharmaceutical sponsors are adopting RTU formats to eliminate in-house washing and depyrogenation steps. This consolidation is compressing the addressable market for standalone glass vial manufacturers while elevating barrier-to-entry for integrated closure-vial-syringe system suppliers.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing reformulation of fluoropolymer-coated stoppers and lubricated syringe components used in biologic drug-device combinations. The ECHA's 2023 PFAS restriction proposal is accelerating supplier migration to silicone oil alternatives and thermoplastic elastomer formulations. Chromatography vial manufacturers serving analytical method validation are most affected, with Agilent Technologies and Thermo Fisher Scientific advancing borosilicate glass surface treatments as PFAS-free alternatives.
Site-level inventory optimization is compressing traditional distributor intermediation in consumable procurement. Large academic medical centers and contract research organizations are consolidating purchasing through group purchasing organizations with direct manufacturer contracts, displacing regional medical supply distributors. This disintermediation is most visible in the United States, where Vizient and Premier contract portfolios now cover 60 percent of Phase III investigative sites.
Global Clinical Trial Consumables Market Segmentation
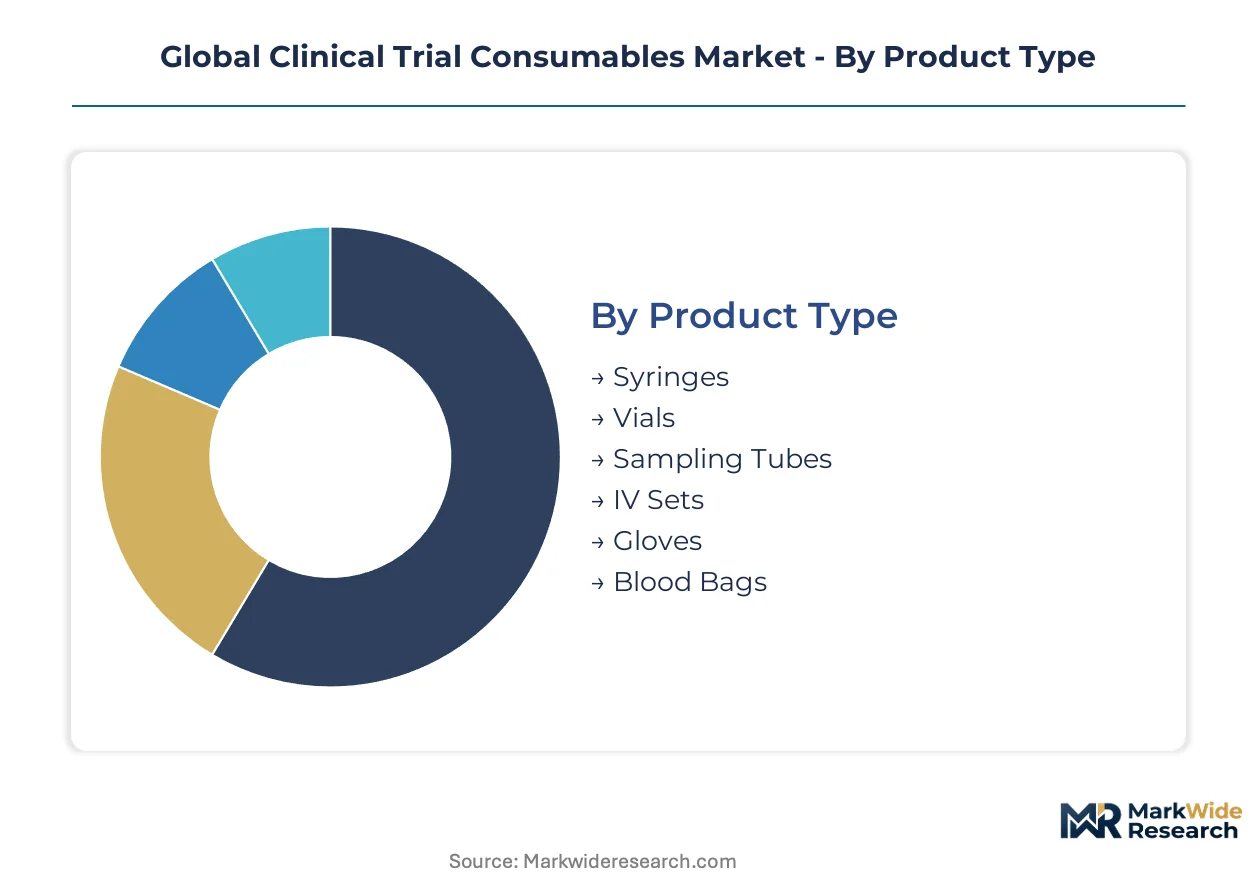
Segmentation in clinical trial consumables reveals how product specifications, trial phases, and end-user procurement power reshape supplier margins. Each category exposes distinct commercial pressures—from ISO 13485 certification thresholds to cold-chain validation requirements—that determine competitive positioning.
Product Type:
Standardization dominates high-volume polypropylene items while customization concentrates in glass and barrier-coated formats.
- Syringes:Gamma-sterilized disposable syringes with silicone oil lubrication serve universal protocol requirements across parenteral drug delivery. Demand clusters in Phase III oncology trials in the United States and Germany, where multi-thousand patient enrollment drives absolute throughput.
- Vials:Borosilicate glass and cyclic olefin polymer vials with validated closure integrity support biologic stability for cell therapy applications. Sponsors in Switzerland and Japan prioritize RTU formats to eliminate in-house depyrogenation, compressing lead times for autologous trials.
- Sampling Tubes:EDTA and serum separator tubes manufactured under ISO 13485 enable standardized specimen collection across decentralized networks.
- IV Sets:Sterile intravenous administration sets with needle-free connectors reduce catheter-related bloodstream infection risks in inpatient trial settings.
- Gloves:Nitrile and latex examination gloves meet OSHA bloodborne pathogen compliance for investigative site personnel.
- Blood Bags:PVC and polyolefin blood collection systems with anticoagulant coatings support transfusion medicine and hematology trials.
Leading the category by volume: Syringes. Expanding most quickly: Vials.
Application:
Cost tier stratification separates high-complexity cell therapy protocols from commodity bioequivalence studies.
- Phase III Trials:Multi-year, multi-site protocols with thousands of patients drive absolute consumable throughput and demand serialized traceability for regulatory audit trails. Sponsors in China and the United States absorb premium pricing for pre-validated kit configurations.
- Phase I Trials:First-in-human studies with intensive pharmacokinetic sampling require specialized analytical-grade consumables for chromatography method validation. Sites in Germany and the United Kingdom prioritize Agilent-grade vials for bioanalytical labs.
- Phase II Trials:Dose-ranging studies with moderate patient cohorts balance standardization against protocol-specific customization.
- Bioequivalence Studies:Generic drug trials with compressed timelines favor high-volume, contract-priced consumables from approved vendor lists.
- Safety Studies:Toxicology and pharmacovigilance protocols require specialized specimen handling for long-term storage.
Phase III Trials anchor absolute revenue. Phase I Trials command the steepest per-patient premium.
End User:
Procurement authority concentrates with organizations running multinational protocol portfolios.
- Clinical Research Organizations:IQVIA, Parexel, and PRA Health Sciences leverage centralized purchasing to negotiate direct manufacturer contracts, displacing regional distributors. CROs in India and the United States consolidate 60 percent of Phase III site procurement through group purchasing organizations.
- Pharmaceutical Companies:Large biopharma sponsors including Roche, Novartis, and Pfizer demand embedded temperature loggers and serialized unit-level aggregation for cold-chain biologics.
- Contract Manufacturing Organizations:Catalent and Thermo Fisher Scientific integrate consumable supply with kit assembly services, capturing margin through vertical control.
- Biotech Firms:Cell therapy developers prioritize specialized sterile packaging with validated SAL 10^-6 assurance.
- Diagnostic Laboratories:Central labs processing trial samples require high-throughput compatible consumables for automated analytical platforms.
Clinical Research Organizations dominate procurement volume. Biotech Firms drive fastest adoption of specialized cold-chain formats.
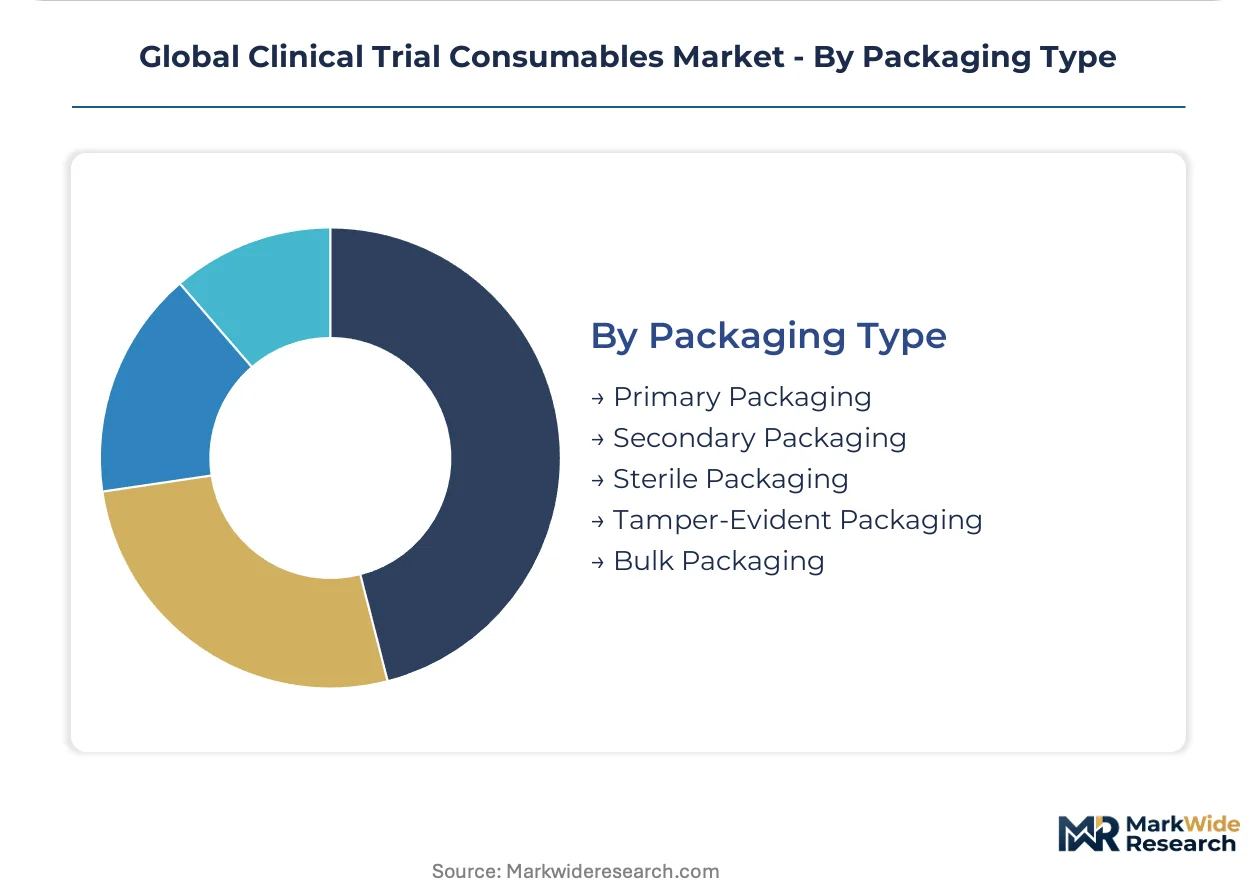
Packaging Type:
Margin tiering separates commodity bulk formats from validated sterile barrier systems.
- Sterile Packaging:Tyvek and medical-grade paper laminates with gamma-irradiation validation carry the steepest margin premium as sponsors prioritize tamper-evident integrity for temperature-sensitive biologics. EU MDR technical documentation requirements extend supplier onboarding cycles for European trials.
- Tamper-Evident Packaging:Breakage indicators and holographic seals satisfy FDA and EMA investigational medicinal product accountability requirements.
- Primary Packaging:Direct product-contact materials including glass vials and polymer tubes face REACH and PFAS restriction pressures.
- Secondary Packaging:Cartons and labels supporting kit assembly workflows streamline multinational distribution.
- Bulk Packaging:Unsterilized intermediate containers optimize logistics for high-volume, low-margin consumables.
Sterile Packaging commands peak margin. Tamper-Evident Packaging gains share fastest under tightening EMA accountability rules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in India, China, and Singapore concentrate clinical trial consumable production capacity alongside FDA and EMA-aligned regulatory infrastructure. These zones attract Western suppliers seeking cost-advantaged bases with export certification compatibility. Trial site density and sponsor headquarters location then determine regional demand patterns.
United States
Phase III oncology trials at academic medical centers in Boston, Houston, and San Diego drive absolute consumable throughput. The FDA enforces Current Good Manufacturing Practice for finished pharmaceuticals, directly governing sterility assurance and supplier qualification protocols. The Research Triangle Park cluster in North Carolina hosts centralized kit assembly operations for multinational protocols.
Germany
First-in-human studies at sites in Munich and Heidelberg require analytical-grade chromatography consumables for bioanalytical method validation. The EU Medical Device Regulation tightens technical documentation requirements for Class I consumables, extending supplier onboarding cycles. The Rhine-Main biotech corridor concentrates cell therapy sponsors demanding gamma-sterilized cold-chain packaging.
China
Multinational trial expansion by domestic biopharma sponsors in Shanghai and Suzhou accelerates local manufacturing audits for imported consumables. The NMPA expedites certification timelines for Western suppliers establishing ISO 13485-certified domestic production. The Zhangjiang Hi-Tech Park anchors foreign-invested consumable fabrication serving Asia-Pacific trial networks.
Switzerland
Autologous cell therapy developers in Basel and Geneva prioritize ready-to-use vial formats to eliminate in-house depyrogenation steps. Swissmedic alignment with EMA Clinical Trials Regulation harmonizes investigational medicinal product labeling requirements. The Greater Zurich Area concentrates specialized sterile packaging suppliers with validated SAL 10^-6 assurance.
India
Contract research organizations in Hyderabad and Bengaluru consolidate procurement through group purchasing organizations, displacing regional distributors. The CDSCO Production Linked Incentive scheme for pharmaceuticals attracts consumable suppliers to establish ISO 13485-certified facilities. The Genome Valley biotech cluster serves as a kit assembly hub for decentralized trial shipments across South Asia.
Global Clinical Trial Consumables Market Competitive Landscape
United States producers anchor the integrated supply chain tier; European specialists hold the analytical-grade consumable segment. The market structures around three tiers: multinational conglomerates with end-to-end kit assembly capabilities, mid-scale regional fabricators serving single geography trial networks, and niche cold-chain logistics providers. Strategic moves concentrate on backward integration into gamma sterilization capacity and upstream control over polymer resin supply.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Catalent Inc. exemplify archetypes combining consumable supply with kit assembly services. Agilent Technologies occupies a position representing analytical-grade specialization for chromatography validation requirements. These three entities anchor competitive dynamics: Thermo Fisher leverages pre-validated kit configurations for multinational protocols, Catalent captures margin through vertical control of cold-chain packaging for cell therapy trials, and Agilent differentiates via borosilicate glass surface treatments as PFAS-free alternatives.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Almac Group |
| Catalent Inc. |
| Parexel International Corporation |
| Agilent Technologies |
| Biocair |
| United Parcel Service of America, Inc. |
| Sharp Services |
| KLIFO |
| Others |
Supply & Pricing Matrix
Polypropylene resin feedstock cascades from Gulf Coast petrochemical complexes through contract-locked pricing tiers to high-volume consumable manufacturers, compressing margins on sampling tubes and syringes while elevating premium capture for gamma-sterilized barrier packaging serving cell therapy cold chains.
Pricing Analysis
Lead-time premiums stratify consumable procurement, with sponsors absorbing surcharges for validated kit configurations delivering inside four-week windows versus standard twelve-week contract cycles. Three-tier pricing structure across premium, standard, and economy levels separates gamma-sterilized SAL 10^-6 barrier systems from ISO 13485-certified bulk formats from unvalidated spot inventory. Cost compression in standard polypropylene items is intensifying because resin price volatility transfers downstream under annual contract locks. Bioequivalence study sponsors exhibit highest price sensitivity, while cell therapy developers absorb steepest premiums for tamper-evident cold-chain integrity.
Supply Chain Analysis
Gamma sterilization capacity rests on Cobalt-60 irradiation facilities concentrated in the United States, Germany, and Belgium, creating single-source vulnerability for SAL 10^-6 validation required across parenteral applications. Borosilicate glass vials, fluoropolymer-coated stoppers, and medical-grade paper laminates constitute critical input dependencies tethered to specialty chemical producers. Tariff exposure runs through EU MDR technical documentation requirements extending supplier onboarding cycles. Distribution runs through centralized kit assembly operations in Research Triangle Park and the Greater Zurich Area, displacing regional medical supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cobalt-60 irradiation facility scarcity props pricing power for validated sterile packaging, constraining throughput expansion for cell therapy sponsors and compressing qualification timelines for multinational protocols.
For Market Incumbents: Anchor competitive position through backward integration into captive gamma sterilization capacity in Germany and the United States, eliminating scheduling risks from third-party irradiation bottlenecks. Defend margin structure by embedding serialized traceability data and temperature-logging capabilities into pre-validated kit configurations, raising technical qualification thresholds that emerging regional fabricators cannot match against EU MDR documentation requirements. For New Entrants and Emerging Players: Direct-to-patient shipping platforms offer the most penetrable white space, with decentralized trial models in India and the United States demanding simplified disposal protocols and patient-centric kit formats that incumbent distributors have not configured. Target CDSCO Production Linked Incentive manufacturing incentives in Hyderabad and Bengaluru to establish ISO 13485-certified production serving Asia-Pacific trial networks at cost-advantaged positions. For Investors and Strategic Acquirers: NMPA acceleration of local manufacturing audits for Western suppliers establishing domestic Chinese production is the leading indicator that Asia-Pacific supply chain repositioning will consolidate around foreign-invested facilities in Zhangjiang Hi-Tech Park. Long-term viability favors acquisition targets combining gamma-sterilized packaging validation with cold-chain logistics integration, with inflection signaled by REACH PFAS restriction enforcement accelerating silicone oil alternative adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gamma Sterilization | Catalent and Thermo Fisher Scientific eliminate Cobalt-60 capacity bottlenecks through captive irradiation facilities in North America and Western Europe. |
| CDSCO Manufacturing Incentive Utilization | Western suppliers establishing ISO 13485-certified facilities in Genome Valley capture cost advantages serving decentralized trial networks across South Asia. |
| Real-Time Release Testing Adoption | Rapid microbiological methods compress inventory holding periods for sterile consumables, accelerating cash conversion cycles for high-volume manufacturers. |
| PFAS-Free Formulation Migration | Agilent Technologies and Thermo Fisher Scientific advance borosilicate glass surface treatments replacing fluoropolymer-coated stoppers under ECHA restrictions. |
| Serialized Traceability Infrastructure | Unit-level aggregation capabilities in manufacturing execution systems satisfy sponsor audit trail requirements for Phase III multinational protocols. |
Research Methodology
FDA 510(k) filings, EMA Clinical Trials Regulation guidance documents, and ClinicalTrials.gov protocol registries formed the secondary backbone, cross-referenced against customs trade data and ISO 13485 certification databases. Primary interviews with clinical supply chain directors, regulatory affairs leads at biopharma sponsors, GPO contracts managers at Vizient and Premier, and gamma sterilization facility operators combined with secondary validation through bottom-up and top-down triangulation. Stakeholder perspectives spanned consumable manufacturers, CRO procurement heads, and hospital purchasing committees at academic medical centers in Boston, Houston, and San Diego.
Bottom-up modeling anchored volume projections in protocol-level consumable throughput assumptions, while top-down verification checked aggregate spend patterns against sponsor R&D disclosures. Segmentation dimensions spanned product type sterility grade, trial phase complexity tier, end-user procurement authority, and regional regulatory cluster alignment. CAGRs derived from slope-intercept fitting across the projection horizon, with sensitivity bands testing resin price volatility scenarios and EU MDR documentation timeline extensions. Industry-specific inputs incorporated gamma sterilization facility capacity utilization rates and CDSCO audit acceleration timelines for Western suppliers.
Inputs from NMPA certification databases and CDSCO PLI scheme disclosures were available through the study window; gaps in real-time Cobalt-60 facility capacity utilization introduce uncertainty bands around sterilization scheduling risk assumptions. Forecasts reflect documented assumptions regarding regulatory harmonization progress and polymer feedstock price stabilization. REACH PFAS restriction enforcement velocity, NMPA local manufacturing audit acceleration, and gamma irradiation facility expansion announcements constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Global Life Science Products Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Organ Care Products Market
Healthcare Products
Incontinence Products Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
Birth Tissue Products Market
Healthcare Products
Nursing Products Market