
 Europe Hand Sanitizer Market | 2026-2036
Europe Hand Sanitizer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hand Sanitizer Market Analysis
Ethanol is restructuring cost structures across European hand sanitizer manufacturing as producers shift from isopropyl alcohol to grain-derived feedstocks amid energy-price volatility. Reckitt Benckiser Group PLC leverages its pharmaceutical-grade supply chain to dominate hospital procurement channels. Henkel AG & Company KGaA anchors the institutional segment with concentrated bulk-dispenser systems. Unilever PLC competes through private-label partnerships with major retail pharmacy chains.
Hand sanitizer denotes a topical antiseptic preparation containing alcohol concentrations between 60% and 95% by volume, formulated with humectants, emollients, and gelling agents to reduce microbial load on intact skin without water rinsing. Gel formulations occupy the largest volume share due to viscosity control and dispenser compatibility across healthcare settings. Spray formats represent the fastest-growing product type as hospitality operators prioritize rapid-drying, metered-dose application protocols. Alcohol-based formulations command premium positioning against non-alcohol alternatives in clinical environments where pathogen-kill efficacy determines procurement standards.
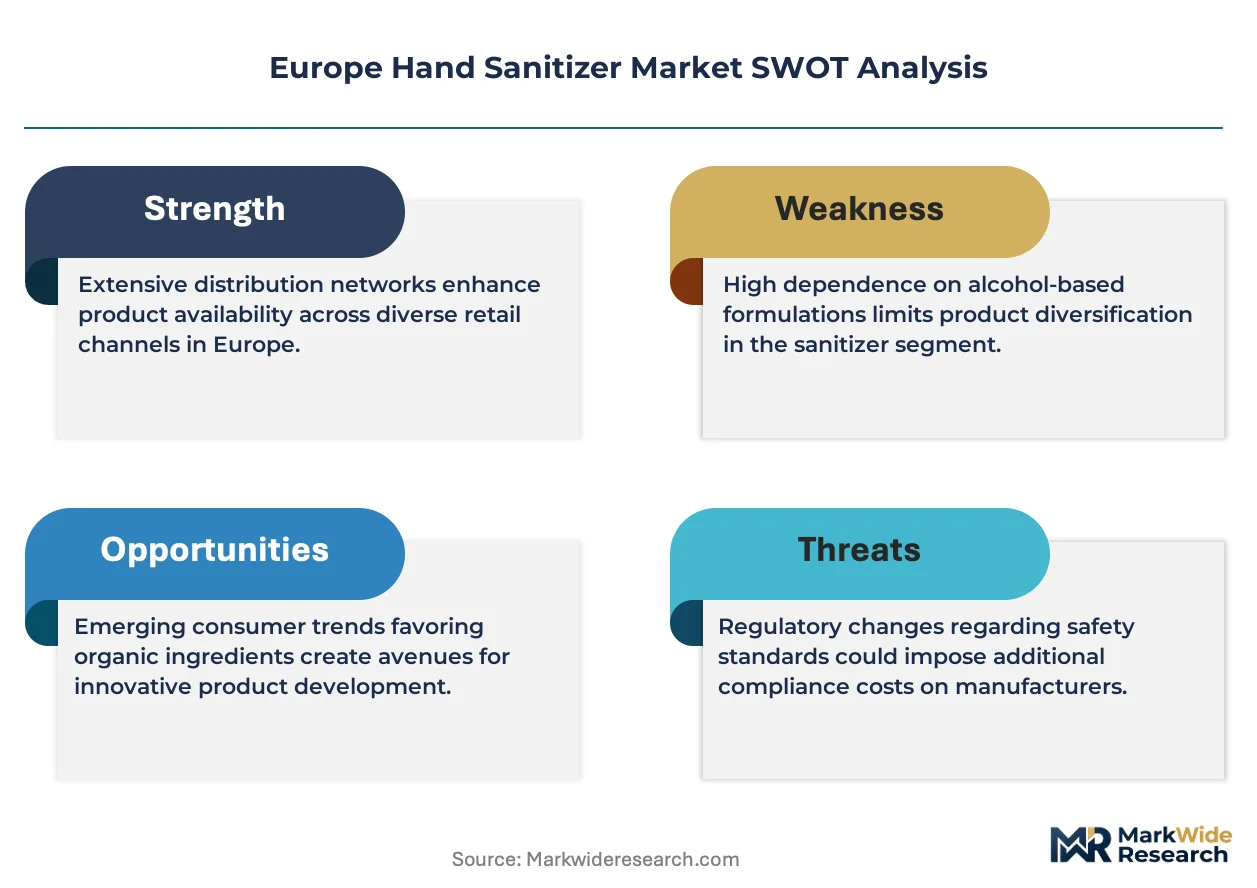
The European Chemicals Agency (ECHA) administers biocidal active-substance approvals under BPR Article 95, while national competent authorities enforce product-type-specific efficacy claims. REACH compliance obligations restrict certain synthetic additives, redirecting R&D investment toward plant-derived emollient systems. Stakeholders must monitor the EU Green Deal's emerging criteria for sustainable chemical manufacturing as these frameworks will determine which formulation platforms retain market access.
Market Dynamics
The EU Biocidal Products Regulation is restructuring authorization pathways for ethanol and isopropyl alcohol, forcing manufacturers to consolidate active-substance dossiers and redirect R&D budgets toward plant-derived emollient systems that satisfy REACH compliance obligations.
Growth Catalysts
- Post-pandemic protocol permanence:German hospital systems have institutionalized alcohol-based hand hygiene as mandatory pre-procedure standards, creating recurring procurement contracts for institutional-grade gel formulations.
- REACH-compliant emollient innovation:Formulators are substituting synthetic additives with glycerin and aloe vera derivatives to meet restricted substance lists, opening premium positioning for natural-derived product lines.
- Educational institution mandates:French and British primary schools now require dispenser-compatible sanitizer stations at entry points, expanding volume demand beyond healthcare into facility management channels.
Market Restraints
- Grain-derived ethanol cost volatility:Energy-price fluctuations across the European Union are compressing margins for producers dependent on agricultural feedstocks rather than petrochemical isopropyl alcohol.
- Active-substance authorization concentration:ECHA's Article 95 compliance requirements have consolidated approved supplier lists to a handful of dossier holders, creating single-source vulnerability for small and mid-size manufacturers.
- Non-alcohol substitute efficacy claims:Benzalkonium chloride formulations are gaining traction in retail channels where consumers perceive skin gentleness advantages, threatening alcohol-based volume in non-clinical settings.
Strategic Opportunities
- Eastern European hospital modernization:Polish and Romanian healthcare infrastructure upgrades are creating first-mover advantages for suppliers establishing institutional-grade distribution networks ahead of EU Cohesion Fund deployment.
- Spray format hospitality adoption:Rapid-drying metered-dose systems are displacing gel dispensers in hotel and restaurant chains seeking operational efficiency through reduced contact time protocols.
- EU Green Deal manufacturing incentives:Emerging criteria for sustainable chemical production are channeling capital toward bio-based carbon feedstocks and closed-loop water systems in sanitizer production facilities.
Industry Challenges
- Biocidal efficacy certification timelines:ECHA's product-type 1 authorization process requires 18-24 month evaluation periods, delaying market entry for reformulated products and freezing innovation pipelines.
- Supply chain reconfiguration friction:Manufacturers shifting from Asian-sourced isopropyl alcohol to European grain ethanol face equipment retrofit costs and formulation stability testing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hand Sanitizer Market |
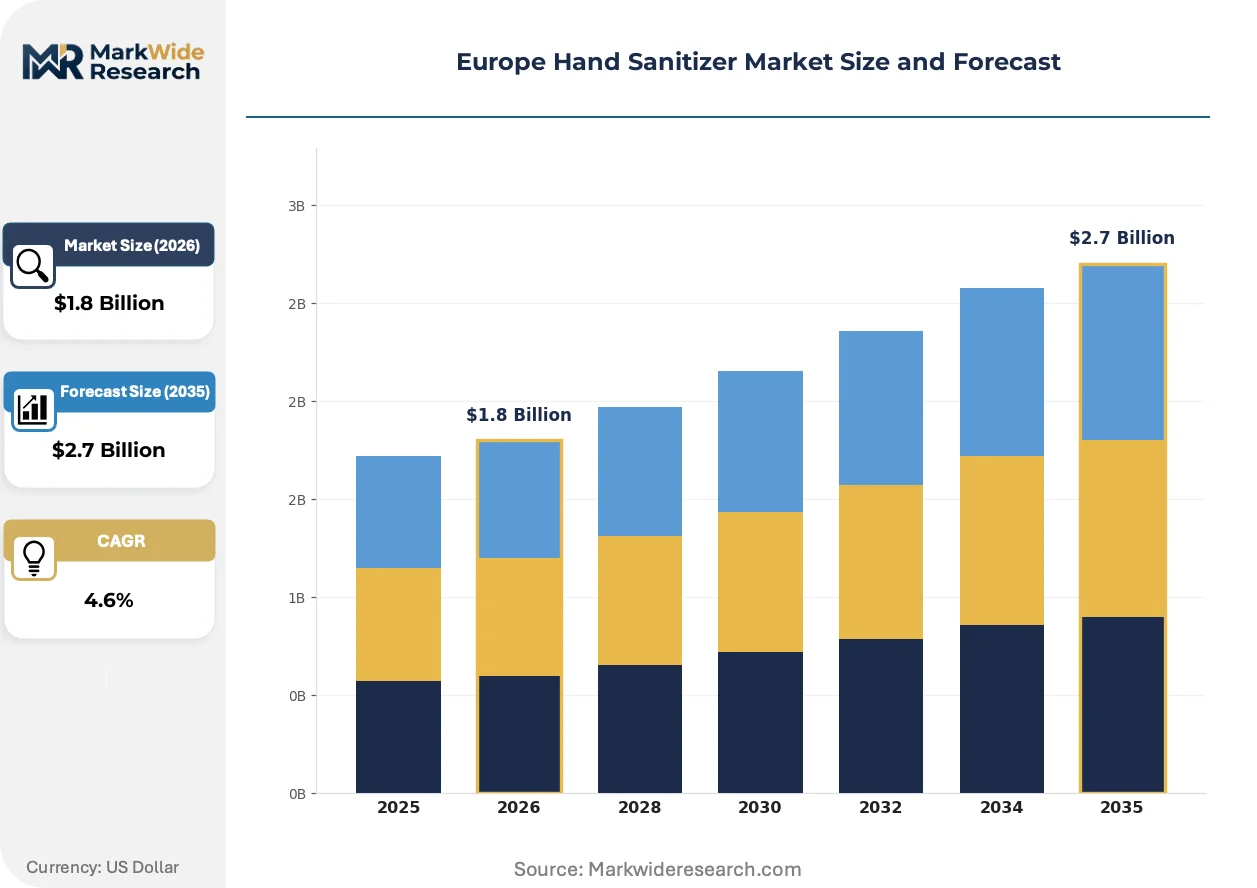
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Foam, Spray, Wipe Distribution Channel: Online Retail, Drugstores, Supermarkets, Convenience Stores End User: Healthcare, Education, Hospitality, Household Formulation Type: Alcohol-Based, Non-Alcohol-Based, Essential Oil Infused, Antibacterial |
| Companies Covered | Reckitt Benckiser Group PLC, 3M Company, GOJO Industries Inc., Unilever PLC, Ecolab Inc., Henkel AG & Company KGaA, Procter & Gamble Company, Sanofi S.A., Kimberly-Clark Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hand Sanitizer Market Emerging Trajectories
Formulation chemistry and dispensing technology are converging to reshape product architecture, with sustainability mandates and operational efficiency driving parallel innovation tracks across manufacturing and end-use deployment.
Plant-derived humectant systems are absorbing market share from petroleum-based alternatives as glycerin from European rapeseed and sunflower processing gains cost parity. German pharmaceutical contract manufacturers are adopting these feedstocks at scale to preempt REACH additive restrictions. This absorption is compressing synthetic emollient supplier margins while elevating bio-based certification as a procurement filter in hospital tenders.
REACH restrictions on synthetic additives are redirecting R&D investment toward compliant formulation platforms before 2027 enforcement deadlines. National competent authorities in France and Germany are intensifying efficacy claim verification, forcing label revisions and clinical testing expenditure. Hospital procurement departments are responding by requiring pre-submitted biocidal product-type documentation from all bidders, raising competitive barriers for non-compliant suppliers.
Buying committees in British National Health Service trusts are consolidating supplier relationships from multi-vendor arrangements to single-source framework agreements with annual volume commitments. This compression is displacing spot-market purchases and fragmenting smaller manufacturers who lack balance-sheet capacity for extended payment terms. The shift is most visible in England's acute care networks, where procurement centralization has reduced active vendor pools by half since 2023.
Europe Hand Sanitizer Market Segmentation
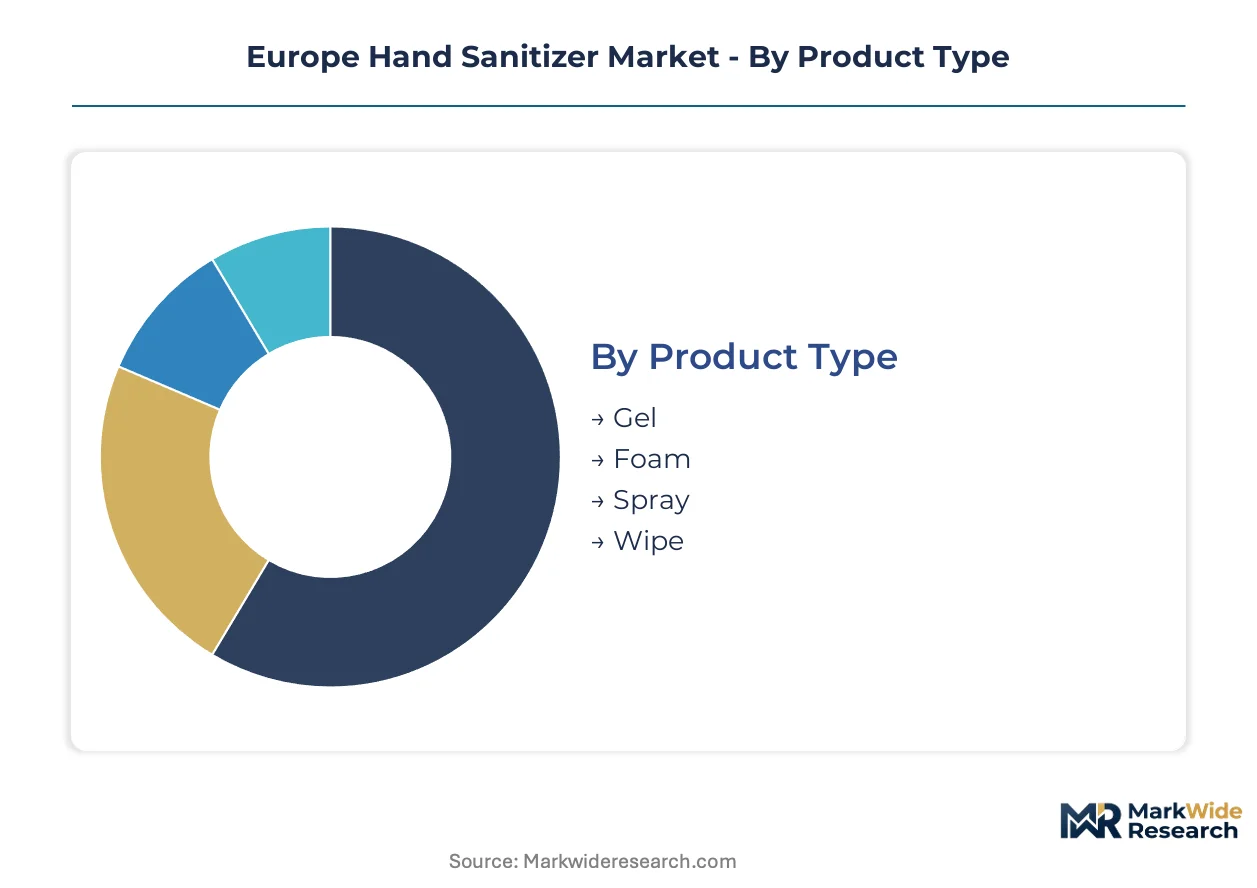
Segmentation in the European hand sanitizer market reveals how procurement specifications diverge across clinical, institutional, and consumer channels. Each dimension—product format, route to market, end-use environment, and active chemistry—creates distinct compliance burdens and margin profiles for manufacturers.
Product Type:
Hospital procurement teams prioritize dispenser compatibility and dwell-time control when selecting formats.
- Gel:Viscous formulations containing 60-95% ethanol or isopropyl alcohol with hydroxypropyl methylcellulose thickeners enable precise dosing through wall-mounted dispensers. German hospital systems specify gel viscosity ranges of 1000-4000 cP to prevent drip contamination in surgical corridors.
- Spray:Metered-dose aerosol and pump systems deliver rapid-drying thin-film coverage. French hospitality chains favor spray formats for lobby and dining-area deployment where reduced contact time accelerates staff workflows.
- Foam:Air-entrained formulations expand upon dispensing to increase perceived volume coverage. British educational institutions specify foam for primary school installations where visual residue confirmation improves compliance monitoring among young users.
- Wipe:Impregnated nonwoven substrates packaged in flow-wrap or canister formats serve mobile healthcare workers and foodservice operators requiring surface-skin dual utility.
Volume sits with gel; growth tilts toward spray.
Distribution Channel:
Channel selection determines margin retention and brand control for formulation suppliers.
- Drugstores:Pharmacy chains across France, Germany, and Italy enforce biocidal product-type documentation requirements that filter out non-compliant suppliers. Boots and dm-drogerie markt dominate shelf placement decisions for alcohol-based formulations.
- Supermarkets:Carrefour, Tesco, and REWE Group leverage private-label procurement to capture value-conscious household demand. Own-brand sanitizer lines now command significant shelf space in personal care aisles.
- Online Retail:Amazon.de and Zalando Beauty enable direct-to-consumer subscription models for premium natural-derived formulations. Digital channels bypass wholesale markups but expose brands to price transparency pressures.
- Convenience Stores:Petrol station networks and urban kiosk operators stock impulse-purchase formats in travel-sized packaging. Limited shelf space favors established brands with distributor relationships.
Drugstores concentrate institutional-grade volume; online channels expand most quickly for premium positioning.
End User:
End-use environments dictate efficacy certification requirements and procurement contract structures.
- Healthcare:Acute care hospitals, outpatient clinics, and long-term care facilities mandate EN 1500 and EN 12791 bactericidal efficacy validation. NHS England procurement frameworks require annual volume commitments with 90-day payment terms.
- Education:Primary and secondary schools across France and Britain deploy entry-point dispenser stations as mandatory hygiene infrastructure. Facility management contracts bundle sanitizer supply with maintenance services.
- Hospitality:Hotel chains and restaurant groups prioritize rapid-drying formulations to minimize guest inconvenience. Accor and Marriott International specify spray formats for housekeeping carts and front-of-house placement.
- Household:Individual consumers select formats based on skin sensitivity claims and fragrance profiles. Retail price sensitivity drives private-label substitution in mass-market channels.
Healthcare anchors contract value; education extends volume through facility mandates.
Formulation Type:
Active chemistry determines regulatory pathway and clinical positioning for European market access.
- Alcohol-Based:Ethanol and isopropyl alcohol formulations at 60-95% concentration deliver rapid bactericidal and virucidal action. ECHA Article 95 compliance requirements restrict active-substance sourcing to approved dossier holders.
- Non-Alcohol-Based:Benzalkonium chloride and polyhexamethylene biguanide alternatives target consumers with dermatological sensitivity concerns. Efficacy claims require separate biocidal authorization under product-type 1.
- Essential Oil Infused:Tea tree, eucalyptus, and lavender derivatives position in natural-product retail channels. REACH restrictions on allergenic fragrance components limit formulation flexibility.
- Antibacterial:Triclosan-free alternatives with chloroxylenol or hydrogen peroxide address specific pathogen-targeting claims. Veterinary and agricultural applications drive niche demand outside human healthcare.
Alcohol-based formulations dominate clinical procurement; non-alcohol alternatives gain share in retail skin-care positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement contracts concentrate demand in Germany, France, and the United Kingdom, while Eastern European healthcare modernization and Nordic sustainability mandates create divergent growth trajectories across the region.
Germany
Bavarian pharmaceutical contract manufacturers supply gel formulations to university hospital networks enforcing EN 1500 compliance. The Federal Institute for Drugs and Medical Devices (BfArM) coordinates with ECHA on biocidal product-type authorizations. North Rhine-Westphalia's chemical corridor hosts ethanol distillation capacity serving sanitizer producers shifting from isopropyl alcohol feedstocks.
France
Accor and Marriott International properties in Paris and Lyon specify spray formats for housekeeping protocols requiring rapid-drying coverage. ANSM intensifies efficacy claim verification for natural-derived product lines ahead of 2027 REACH enforcement. The Auvergne-Rhône-Alpes cluster concentrates essential oil extraction facilities supplying plant-based humectant systems.
United Kingdom
NHS England procurement frameworks consolidate supplier relationships into single-source agreements with 90-day payment terms. The Medicines and Healthcare products Regulatory Agency (MHRA) enforces post-Brexit biocidal registration requirements diverging from EU BPR timelines. London-based facility management contractors bundle dispenser maintenance with sanitizer supply for educational institution mandates.
Poland
EU Cohesion Fund deployment accelerates hospital infrastructure upgrades in Warsaw and Kraków, creating procurement opportunities for institutional-grade distributors. The national Office for Registration of Medicinal Products coordinates biocidal authorization with ECHA Article 95 compliance. Silesian manufacturing zones attract contract packaging investments from Western European brands seeking cost-competitive production.
Netherlands
Randstad region hospitality operators adopt metered-dose spray systems for operational efficiency in high-traffic venues. The Dutch Health and Youth Care Inspectorate (IGJ) enforces product-type 1 documentation requirements for hospital tenders. Rotterdam's bio-based chemical cluster supplies rapeseed-derived glycerin for REACH-compliant emollient formulations.
Europe Hand Sanitizer Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade suppliers dominating hospital procurement while private-label fabricators capture retail volume. The vendor base concentrates around three strategic archetypes: diversified consumer health conglomerates with pharmaceutical supply chains, institutional hygiene specialists with dispenser ecosystem control, and regional contract manufacturers serving cost-optimized retail channels. Competitive moves center on biocidal dossier consolidation for ECHA compliance and backward integration into ethanol feedstock sourcing.
Among diversified consumer health conglomerates, Reckitt Benckiser Group PLC and Unilever PLC occupy positions anchored by pharmaceutical-grade distribution networks and retail pharmacy relationships respectively. Henkel AG & Company KGaA exemplifies the institutional hygiene specialist archetype through concentrated bulk-dispenser system deployment. These three entities represent distinct competitive vectors: pharmaceutical supply chain leverage, private-label partnership scale, and facility management channel control.
| Leading Market Players |
|---|
| Reckitt Benckiser Group PLC |
| 3M Company |
| GOJO Industries Inc. |
| Unilever PLC |
| Ecolab Inc. |
| Henkel AG & Company KGaA |
| Procter & Gamble Company |
| Sanofi S.A. |
| Kimberly-Clark Corporation |
| Others |
Supply Flow & Price Mechanics
Grain-derived ethanol feedstock costs cascade through three pricing tiers as Bavarian distillers supply North Rhine-Westphalia formulation plants serving German hospital procurement frameworks. Energy-price volatility across the European Union compresses margins for agricultural-dependent producers while petrochemical isopropyl alcohol alternatives retain cost stability in spot-market transactions.
Pricing Analysis
Volume concentrates in economy-tier institutional contracts while margin accretion sits with premium pharmaceutical-grade certifications. Three-tier pricing structure across premium, standard, and economy levels separates EN 1500-validated hospital formulations from private-label retail SKUs and bulk educational dispensers. Cost compression in standard-tier gel formulations is intensifying because French and British school district procurement centralization demands extended payment terms. Retail pharmacy chains exhibit highest price sensitivity; NHS England single-source framework agreements show lowest elasticity due to regulatory compliance requirements.
Supply Chain Analysis
Specialized chemical workforce availability constrains capacity expansion in Germany's North Rhine-Westphalia corridor and Poland's Silesian manufacturing zones. Supply concentrates in Germany, Poland, and the Netherlands as contract packaging investments shift eastward from Western European cost bases. Raw material dependencies center on rapeseed-derived glycerin from Rotterdam bio-based clusters, grain ethanol from Bavarian agricultural processors, and hydroxypropyl methylcellulose thickeners from pharmaceutical chemical suppliers. Single-source vulnerability runs through ECHA Article 95 approved dossier holders for active substance authorization. Distribution runs through pharmaceutical-grade wholesalers for hospital channels and retail pharmacy chains for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where ECHA biocidal authorization timelines and REACH compliance investments force sub-scale manufacturers toward exit or acquisition. Regulatory burden concentration rewards balance-sheet capacity for extended certification processes.
For Market Incumbents: To counter single-source active-substance vulnerability, Reckitt Benckiser Group PLC and Henkel AG should pursue backward integration into Bavarian ethanol distillation capacity or captive supply agreements with Article 95 dossier holders. Channel control through dispenser ecosystem lock-in raises switching costs for NHS England procurement frameworks.
For New Entrants and Emerging Players: Rapid-drying spray formulation technology offers first-mover positioning in French hospitality chains and Polish hospital modernization programs ahead of EU Cohesion Fund deployment. White-space targets include metered-dose system manufacturing for Accor housekeeping protocols and REACH-compliant natural-derived emollient lines for German pharmacy premium shelves. Direct-to-institutional sales bypassing wholesale markups provides viable go-to-market angle for specialized contract manufacturers.
For Investors and Strategic Acquirers: ECHA product-type 1 authorization approval for reformulated plant-derived platforms is the leading indicator that natural-derived positioning will capture sustainable margin expansion. Five-to-ten year viability favors mid-cap specialists with captive ethanol sourcing and established hospital procurement relationships over pure-brand consumer plays. Watch for Polish and Romanian distributor acquisitions by Western European incumbents as signal of Eastern European infrastructure upgrade timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Feedstock | Bavarian distillation capacity secures supply cost stability against energy-price volatility in agricultural markets. |
| REACH-Compliant Emollient R&D Investment | Plant-derived glycerin systems from Rotterdam bio-clusters preempt 2027 enforcement deadline displacement risk. |
| Spray Format Manufacturing Scale-Up | Metered-dose production lines capture Accor and Marriott International hospitality chain specification shifts. |
| Eastern European Distribution Network Buildout | Polish and Romanian hospital infrastructure upgrades create first-mover advantage ahead of EU funding deployment. |
| Single-Source Framework Agreement Conversion | NHS England procurement consolidation rewards suppliers with balance-sheet capacity for extended payment terms. |
Methodological Framework
Multi-period observation of ECHA Article 95 authorization timelines, REACH restriction enforcement patterns, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with formulation chemists at German pharmaceutical contract manufacturers, procurement managers within NHS England acute care networks, regulatory affairs specialists navigating BPR compliance, and facility management contractors serving French educational institutions. Secondary validation drew from ECHA biocidal product-type registration databases, EU customs trade statistics for ethanol and isopropyl alcohol flows, BfArM medical device market surveillance reports, and hospital procurement framework disclosure documents. Bottom-up volume modeling across product format and end-use segments triangulated against top-down market sizing from chemical industry association datasets.
Segment-weighting approaches distributed value estimates across gel, spray, foam, and wipe formats proportionally to German hospital dispenser compatibility specifications and French hospitality rapid-drying requirements. End-use segmentation incorporated healthcare, education, hospitality, and household channels with distinct procurement contract structures and efficacy certification burdens. CAGRs were derived from trend extrapolation of institutional procurement normalization patterns and REACH compliance investment cycles. Industry-specific forecast inputs included EU Green Deal sustainable manufacturing incentive trajectories and Eastern European healthcare infrastructure investment pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA authorization timeline delays or grain ethanol cost spikes beyond energy-price volatility norms. Forecasts reflect assumptions regarding post-pandemic hygiene protocol permanence and regulatory enforcement intensity without guaranteed outcome. Material deviation in biocidal product-type approval rates or EU Cohesion Fund deployment timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Birth Tissue Products Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
Elderly Walker Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Medical Products Market
Healthcare Products
Nursing Products Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
Menstrual Sponge Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Global Consumer Healthcare Products Market