
 Cooling Mattress Market | 2026-2036
Cooling Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Cooling Mattress Market Insights
Market Context
Phase change material (PCM) microencapsulation is restructuring cost structures across premium cooling mattress tiers, replacing legacy gel-infusion as the dominant thermal-management approach. Tempur-Pedic leverages its proprietary foam chemistry to sustain premium positioning in the PCM segment. Brooklyn Bedding anchors its competitive stance through vertically controlled manufacturing in Arizona, compressing lead times for direct-to-consumer fulfillment. Eight Sleep differentiates via active-cooling hardware integration, occupying the smart-sleep niche with app-connected temperature control.
Technical Definition and Segment Structure
A cooling mattress is a sleep surface engineered with thermally conductive or heat-dissipating materials—typically open-cell viscoelastic foam, gel-infused polyurethane, or natural latex with perforated ventilation channels—designed to maintain a microclimate between 60°F and 67°F for optimal sleep physiology. Gel-infused products currently lead unit volume, though hybrid constructions combining memory foam with innerspring ventilation represent the fastest-expanding margin pool as consumers trade up from basic foam. Phase change material technology commands the highest price tier but remains supply-constrained by specialized chemical sourcing, while natural ventilation approaches using bamboo and Tencel face raw material availability pressures that limit scale.
Regulatory Environment and Outlook
The U.S. Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1633, while California's Bureau of Household Goods and Services administers additional chemical disclosure requirements through SB 1019, compelling manufacturers to reformulate flame retardants and document foam composition. The EPA's formaldehyde emission limits for composite wood products, extended through TSCA Title VI, indirectly shape adhesive and substrate choices in hybrid mattress assembly. Stakeholders must monitor evolving state-level extended producer responsibility legislation, as mattress recycling mandates in California, Connecticut, and Rhode Island are expanding to cover cooling component recovery and refrigerant handling in active-cooling units.
Market Dynamics
PCM microencapsulation chemistry is consolidating thermal-management tiers across cooling mattress manufacturing, compressing gel-infusion margins while elevating specialized foam compounders to bottleneck status in premium supply chains.
Growth Catalysts
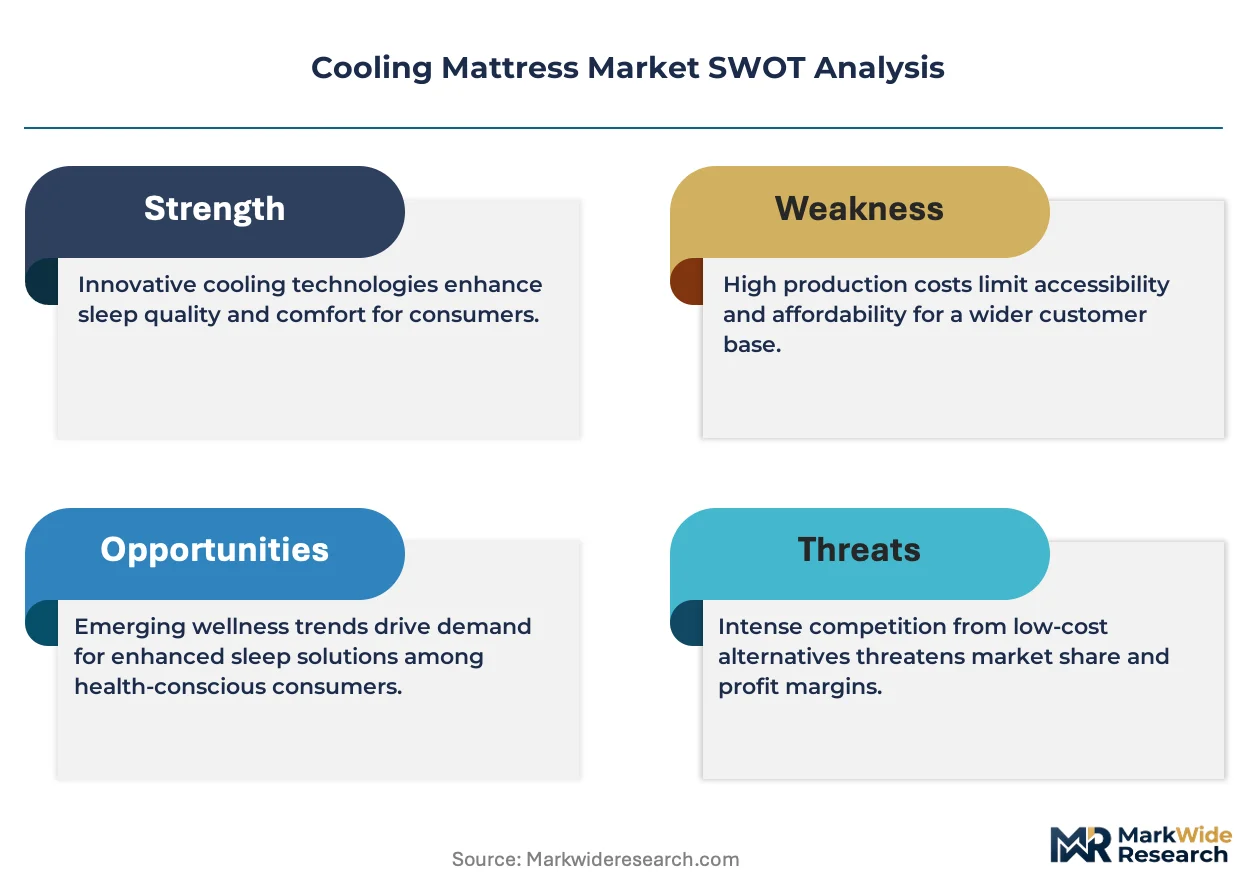
- Sun Belt Urbanization:Metropolitan expansion across Phoenix, Houston, and Miami is concentrating household formation in high-heat zones where cooling features command sustained premium positioning.
- SB 1019 Compliance:California's chemical disclosure mandate is accelerating foam reformulation investments, pushing manufacturers toward certified low-emission chemistries that differentiate at retail.
- Hospitality Procurement:Hotel and resort operators are standardizing temperature-regulating sleep surfaces across property renovation cycles, creating recurring B2B volume anchors.
Market Restraints
- Specialized PCM Sourcing:Encapsulated paraffin and salt hydrate supply concentrates among German and Japanese chemical specialists, exposing assemblers to allocation risk during polymer feedstock disruptions.
- Refrigerant Handling Costs:Active-cooling units containing compressed refrigerants trigger hazardous waste protocols under California's extended producer responsibility framework, elevating end-of-life logistics costs.
- Natural Latex Substitution:Perforated Dunlop latex from Southeast Asian plantations offers comparable breathability at lower unit cost, capping pricing power for synthetic foam tiers.
Strategic Opportunities
- Smart-Sleep Convergence:Integration of biometric monitoring hardware with thermoelectric cooling modules is opening subscription revenue streams beyond one-time mattress sales.
- Direct-to-Consumer Compression:Roll-pack logistics innovations are enabling bypass of traditional furniture retail, capturing margin otherwise allocated to showroom networks.
- EU F-Gas Regulation:Restrictions on hydrofluorocarbon refrigerants are creating first-mover advantage for solid-state thermoelectric alternatives in European export markets.
Industry Challenges
- Polymer Chemist Scarcity:Formulation expertise for viscoelastic-PCM hybrids concentrates among aging technical workforces in Ohio and North Carolina manufacturing corridors.
- 16 CFR Part 1633 Certification Timelines:Flammability testing protocols for novel foam compositions extend product development cycles by 8-14 months, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooling Mattress Market |
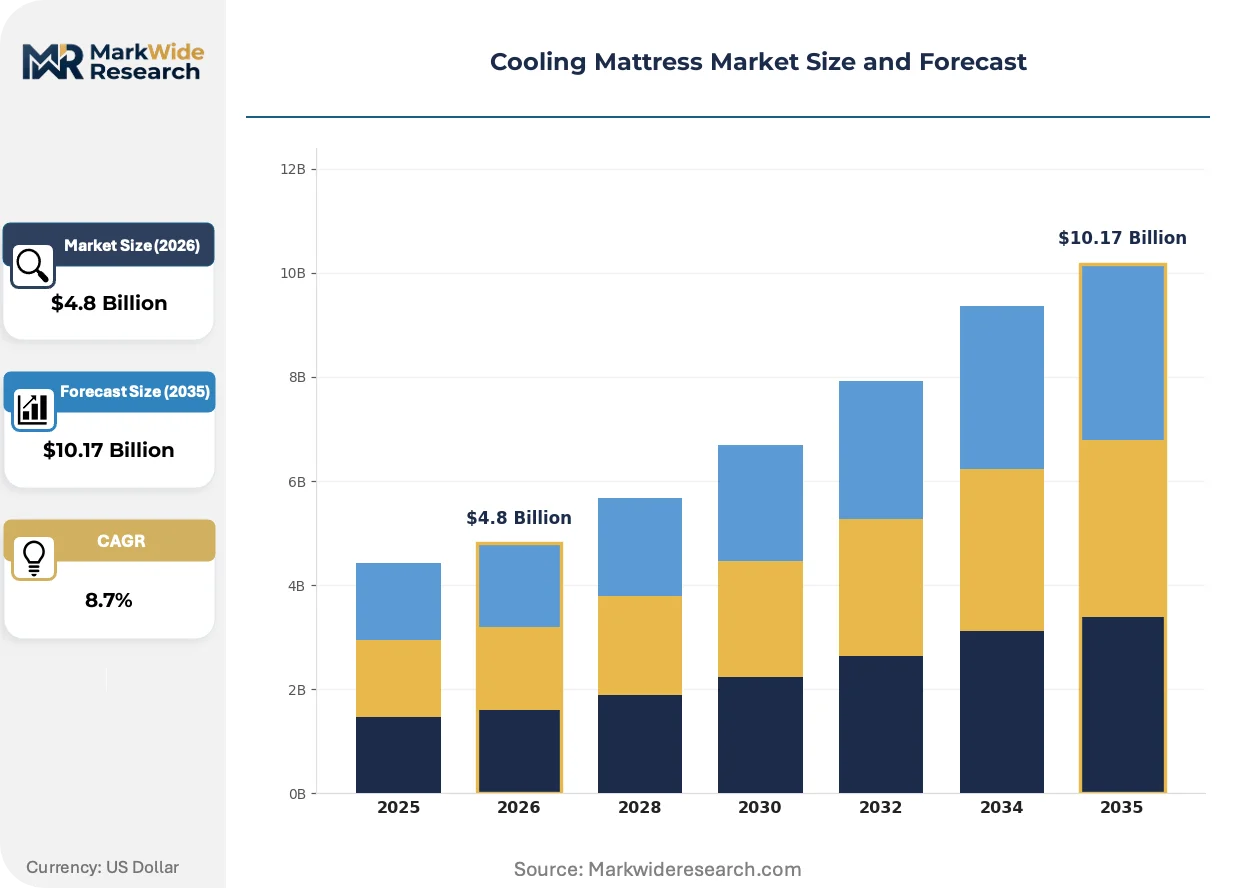
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Gel-Infused, Latex, Hybrid Material: Polyester, Cotton, Bamboo, Tencel Cooling Technology: Phase Change Material, Active Cooling, Natural Ventilation, Gel Layers End User: Residential, Hospitality, Healthcare, Institutional |
| Companies Covered | Helix Sleep, Leesa, Nectar, DreamCloud, Saatva, WinkBed, Brooklyn Bedding, Tempur-Pedic, Eight Sleep, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooling Mattress Market Trends and Innovations
Active-cooling hardware integration is bifurcating the competitive landscape between passive material science and powered thermal systems, with software-enabled sleep optimization emerging as the decisive differentiation vector.
Thermoelectric cooling modules embedded beneath foam comfort layers is electrifying the high-end segment. Luxury hotel operators and tech-forward consumers are adopting these systems at accelerating rates. This technology is compressing traditional premium foam margins while elevating electrical engineering capabilities to core competency status among mattress assemblers.
The EPA's Safer Choice program criteria for low-emission foam are tightening material qualification standards. Manufacturers must now document supply chain chemistry through third-party certification to maintain retail placement. Small and mid-tier foam producers lacking analytical testing infrastructure face exclusion from national retail distribution.
Subscription-based mattress refresh programs are displacing traditional replacement cycles among urban millennials. Direct-to-consumer brands are bundling cooling surface upgrades with sleep coaching services. This pattern concentrates in coastal metropolitan markets where housing turnover and lifestyle mobility remain elevated.
Cooling Mattress Market Segmentation
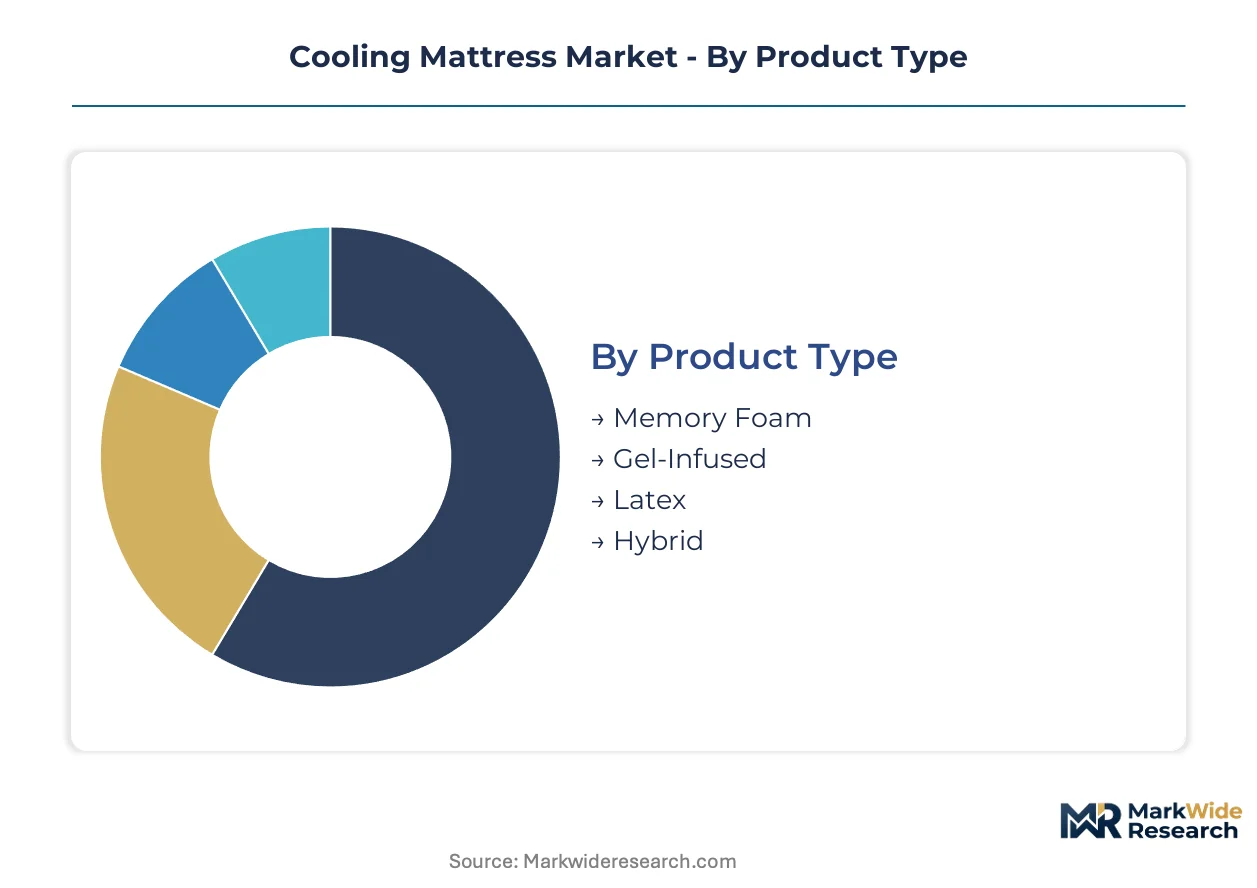
Cooling mattress segmentation reveals how thermal-management technologies concentrate manufacturing capability and procurement budgets across distinct performance tiers. Material sourcing constraints and end-use specifications fragment supply chains, creating specialized production clusters that resist commoditization.
Product Type:
Supply-side capability clusters around foam chemistry expertise and coil integration infrastructure, with distinct manufacturing footprints for each construction approach.
- Memory Foam:Open-cell viscoelastic formulations with thermally conductive additives dominate mass-market production. Sun Belt metropolitan areas absorb the bulk of residential demand, where heat retention concerns drive replacement cycles. Manufacturing concentrates in North Carolina and Ohio corridor facilities with legacy polyurethane expertise.
- Gel-Infused:Bead-integrated polyurethane layers offer intermediate cooling at accessible price points. Hospitality procurement channels standardize this construction across property renovation cycles, creating volume anchors that sustain dedicated production lines.
- Latex:Perforated Dunlop and Talalay constructions from Southeast Asian rubber plantations supply breathable alternatives. Raw material availability pressures limit scale expansion despite comparable thermal performance.
- Hybrid:Coil-spring foundations with foam comfort layers represent the fastest-expanding margin pool as consumers trade up from basic all-foam constructions.
Memory Foam absorbs the bulk of installed capacity; Hybrid is expanding most quickly.
Material:
Cost tier stratification separates commodity synthetics from certified natural fibers, with sustainability premiums widening price spreads at retail.
- Polyester:Petroleum-derived synthetic fibers provide moisture-wicking at lowest unit cost. Mass-market direct-to-consumer brands anchor positioning here, compressing margins through volume scale.
- Cotton:Conventional and organic grades occupy mid-tier positioning. California SB 1019 disclosure requirements favor certified low-emission cotton sourcing, differentiating compliant products at specialty retail.
- Bamboo:Cellulose-based rayon from bamboo pulp offers breathability with sustainability signaling. Supply constraints from Chinese processing facilities limit consistent availability.
- Tencel:Lyocell fiber from Austrian Lenzing AG commands premium positioning through closed-loop production certification. European hospitality procurement favors this material for ESG alignment.
Polyester captures the greatest production volume; Tencel climbs the fastest on sustainability premiums.
Cooling Technology:
Technology maturity curves separate passive material approaches from powered systems, with electrical engineering capabilities becoming decisive for competitive positioning.
- Phase Change Material:Microencapsulated paraffin and salt hydrate chemistry from German and Japanese specialists enables precise temperature regulation. Supply concentrates among limited chemical compounders, exposing assemblers to allocation risk during polymer feedstock disruptions.
- Active Cooling:Thermoelectric modules and refrigerant-based systems electrify the high-end segment. Eight Sleep and similar entrants capture subscription revenue through app-connected temperature control, though California extended producer responsibility frameworks elevate end-of-life logistics costs.
- Natural Ventilation:Perforated foam structures and breathable fiber matrices avoid powered components. This approach faces substitution pressure from lower-cost latex alternatives with comparable airflow characteristics.
- Gel Layers:Conductive gel-infused comfort zones represent legacy thermal management, with margins compressing as PCM technology scales.
Gel Layers retain the largest installed base; Active Cooling gains share fastest on smart-sleep convergence.
End User:
Application-specific requirements fragment demand across warranty terms, fire certification standards, and replacement cycle predictability.
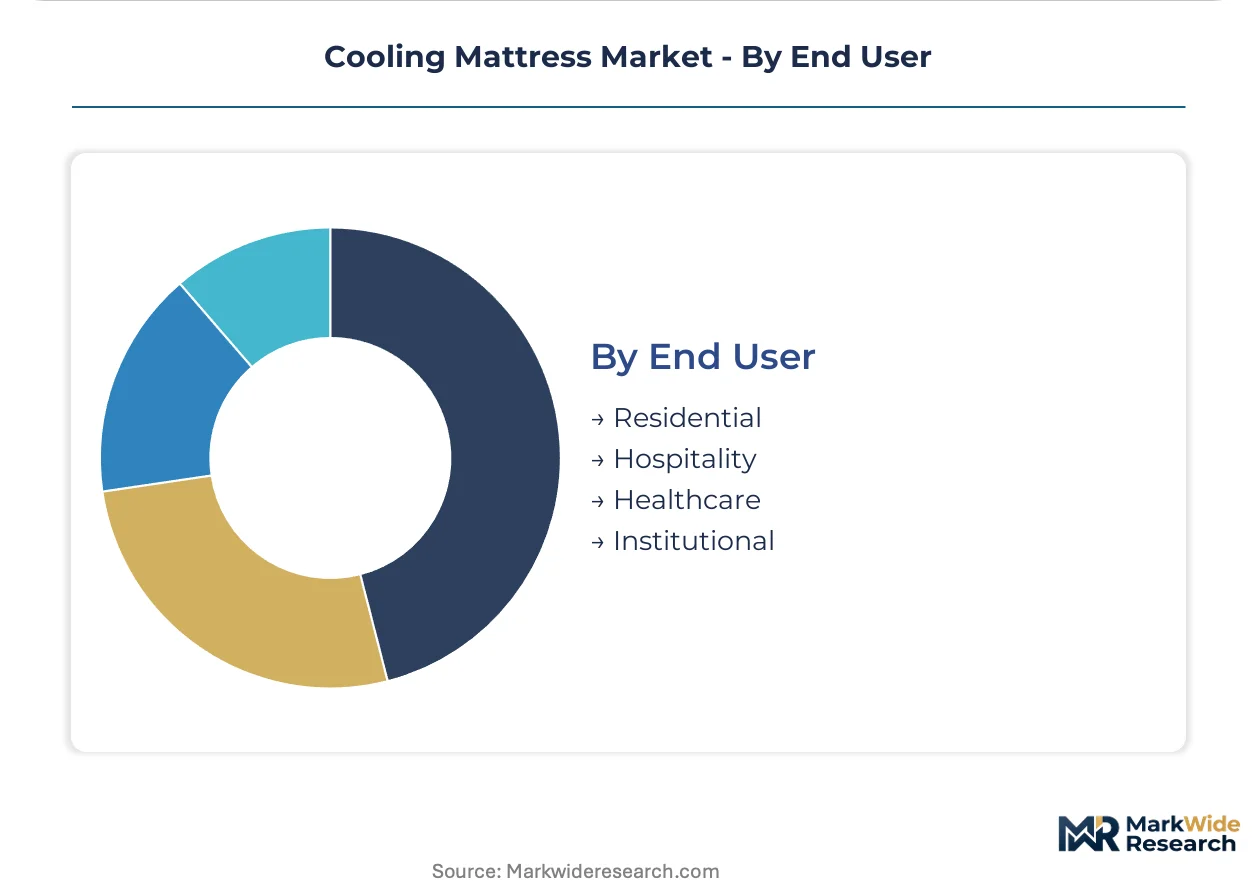
- Residential:Individual consumers purchasing through retail or direct-to-consumer channels drive unit volume. Sun Belt household formation concentrates demand for premium cooling features.
- Hospitality:Hotel and resort operators standardize temperature-regulating surfaces across renovation cycles. Procurement specifications emphasize durability certifications and bulk replacement logistics.
- Healthcare:Medical facilities require pressure-relief and thermal regulation for patient populations. 16 CFR Part 1633 flammability compliance and infection-control protocols shape product selection.
- Institutional:University dormitories, military housing, and correctional facilities prioritize cost durability over feature sophistication. Extended replacement cycles and centralized procurement limit margin capture.
Residential absorbs the bulk of revenue; Hospitality is expanding most quickly on property renovation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household formation in high-temperature metropolitan zones concentrates cooling mattress demand in specific national markets, with regulatory frameworks and hospitality investment patterns diverging sharply across developed economies.
United States
Sun Belt urbanization across Phoenix, Houston, and Miami drives premium positioning for temperature-regulating sleep surfaces. The EPA Safer Choice program and California SB 1019 chemical disclosure rules compel foam reformulation investments. North Carolina and Ohio manufacturing corridors host legacy polyurethane expertise that supplies domestic assembly networks.
Germany
Specialized chemical compounders in the Rhine-Ruhr industrial zone supply microencapsulated phase change materials to premium mattress assemblers. The EU F-Gas Regulation restricts hydrofluorocarbon refrigerants, accelerating solid-state thermoelectric alternatives for export markets. Bavarian hospitality operators standardize certified low-emission sleep surfaces across property renovation cycles.
Japan
Japanese chemical specialists concentrate supply of encapsulated paraffin and salt hydrate chemistry for precision temperature regulation. METI energy efficiency standards shape thermal management system specifications for residential applications. Osaka-based manufacturing clusters integrate advanced foam chemistry with precision electronics assembly.
China
Domestic mattress consumption expands in Yangtze River Delta and Pearl River Delta metropolitan zones where summer heat stress elevates cooling feature prioritization. The National Medical Products Administration oversees flammability certification for hospitality procurement channels. Zhejiang and Jiangsu provinces host vertically integrated foam production and coil spring fabrication facilities.
United Kingdom
London and Southeast England concentrate direct-to-consumer brand headquarters leveraging roll-pack logistics for European market access. The UK Furniture and Furnishings (Fire) (Safety) Regulations 1988 impose flammability standards that shape foam composition choices. Midlands manufacturing bases supply hybrid coil-and-foam constructions to hospitality renovation programs.
Cooling Mattress Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium tiers consolidating around proprietary foam chemistry while mass-market production fragments among regional assemblers. Three strategic archetypes dominate: vertically integrated foam compounders controlling raw material access, direct-to-consumer brands compressing retail margins through roll-pack fulfillment, and hospitality-focused OEMs securing multi-year property renovation contracts. Capacity expansion and technology licensing represent the dominant competitive moves, with players securing exclusive PCM microencapsulation supply agreements or acquiring regional foam fabrication assets.
Among US-based branded specialists, Tempur-Pedic anchors premium positioning through proprietary viscoelastic formulations, while Brooklyn Bedding exemplifies vertically controlled manufacturing with Arizona-based production compressing lead times for direct fulfillment. Eight Sleep occupies the smart-sleep niche, representing the active-cooling hardware integration archetype that captures recurring subscription revenue beyond one-time mattress sales.
| Leading Market Players |
|---|
| Helix Sleep |
| Leesa |
| Nectar |
| DreamCloud |
| Saatva |
| WinkBed |
| Brooklyn Bedding |
| Tempur-Pedic |
| Eight Sleep |
| Others |
Pricing and Supply Chain Analysis
California SB 1019 chemical disclosure mandates are forcing foam reformulation investments that compress margins for non-compliant assemblers while rewarding certified low-emission producers with retail placement premiums. Hospitality procurement consolidation across Sun Belt property renovations concentrates volume leverage, squeezing per-unit pricing power for undifferentiated gel-infusion suppliers.
Pricing Analysis
Volume concentrates in gel-infused polyurethane tiers where mass-market direct-to-consumer brands compress margins through scale, while premium-mid-economy pricing differentiation separates phase change material constructions at the top. Price differentiation hinges on EPA Safer Choice certification status and hospitality durability warranties. Cost compression in gel tiers is intensifying because PCM microencapsulation scales at lower incremental cost. Institutional buyers in university and military housing exhibit highest price sensitivity; luxury hotel operators show lowest sensitivity due to ESG alignment requirements.
Supply Chain Analysis
Hospitality procurement teams now mandate dual-sourcing qualification for microencapsulated paraffin and salt hydrate chemistry, forcing assemblers to qualify both German and Japanese compounders simultaneously. Raw material dependencies center on Southeast Asian latex plantations, Chinese bamboo pulp processing facilities, and Austrian Lenzing AG lyocell fiber. Single-source vulnerability concentrates in Japanese salt hydrate chemistry specialists. Distribution runs through direct-to-consumer roll-pack fulfillment and hospitality OEM multi-year renovation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically controlled manufacturing and certified low-emission chemistry as EPA and California regulations force smaller foam producers out of national retail distribution.
For Market Incumbents: Deepen backward integration into Arizona and North Carolina foam compounding corridors to secure captive supply of viscoelastic-PCM hybrids. Lock exclusive multi-year supply agreements with German and Japanese microencapsulation specialists before allocation risk materializes. Invest in 16 CFR Part 1633 testing infrastructure to compress certification timelines against emerging active-cooling entrants. For New Entrants and Emerging Players: Direct-to-consumer channel partners in London and Southeast England offer lowest barrier to European market entry through roll-pack logistics integration. White-space targets include solid-state thermoelectric modules for EU F-Gas compliance and subscription-based mattress refresh programs for coastal millennial cohorts. Pursue hospitality OEM partnerships rather than retail slotting fee competition. For Investors and Strategic Acquirers: The window for entry favors vertically controlled foam compounders with existing EPA Safer Choice certification and Sun Belt manufacturing footprint. Long-term viability hinges on electrical engineering capabilities for smart-sleep convergence. Watch California extended producer responsibility enforcement intensity as the inflection signal for active-cooling unit logistics cost structure viability.| Strategic Initiative | Industry Significance |
|---|---|
| PCM Microencapsulation Supply Agreement | Secures allocation priority from German and Japanese chemical specialists during polymer feedstock disruptions. |
| Direct-to-Consumer Roll-Pack Launch | Bypasses furniture retail showroom networks to capture margin otherwise allocated to brick-and-mortar distribution. |
| EPA Safer Choice Certification Investment | Maintains national retail placement as low-emission foam standards tighten under federal procurement criteria. |
| Smart-Sleep Platform Integration | Captures recurring subscription revenue through app-connected thermoelectric temperature control modules. |
| Hospitality OEM Multi-Year Contract | Creates volume anchors across property renovation cycles in Phoenix, Houston, and Miami metropolitan zones. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cooling mattress market assessment. Primary interviews with foam compounding plant managers, hospitality procurement directors, California Bureau of Household Goods and Services compliance officers, and direct-to-consumer brand supply chain heads combined with bottom-up and top-down triangulation. Secondary validation drew from EPA Safer Choice certified product listings, California SB 1019 disclosure databases, and North Carolina and Ohio manufacturing corridor employment records.
Segment-level granularity modeled cooling technology tiers, material certification grades, and end-use application specifications across the projection horizon. CAGRs derived from installed capacity expansion rates in polyurethane foam corridors and hospitality renovation cycle frequency. Forecast inputs incorporated Sun Belt household formation velocity and EU F-Gas Regulation compliance cost trajectories for refrigerant-based active-cooling units.
Caveats apply where California extended producer responsibility enforcement intensity or Japanese salt hydrate chemistry allocation disruptions could materially shift the outlook. Deviation in PCM microencapsulation scaling economics would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Global Life Science Products Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Global Consumer Healthcare Products Market
Healthcare Products
Toothbrush Sanitizer Market
Healthcare Products
Birth Tissue Products Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Global Healthcare Distribution Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Elderly Walker Market
Healthcare Products
Incontinence Products Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Blood and Organ Bank Market