
 Incontinence Products Market | 2026-2036
Incontinence Products Market Size, Share, and Industry Trends Forecast 2026-2036
Incontinence Products Market Intelligence
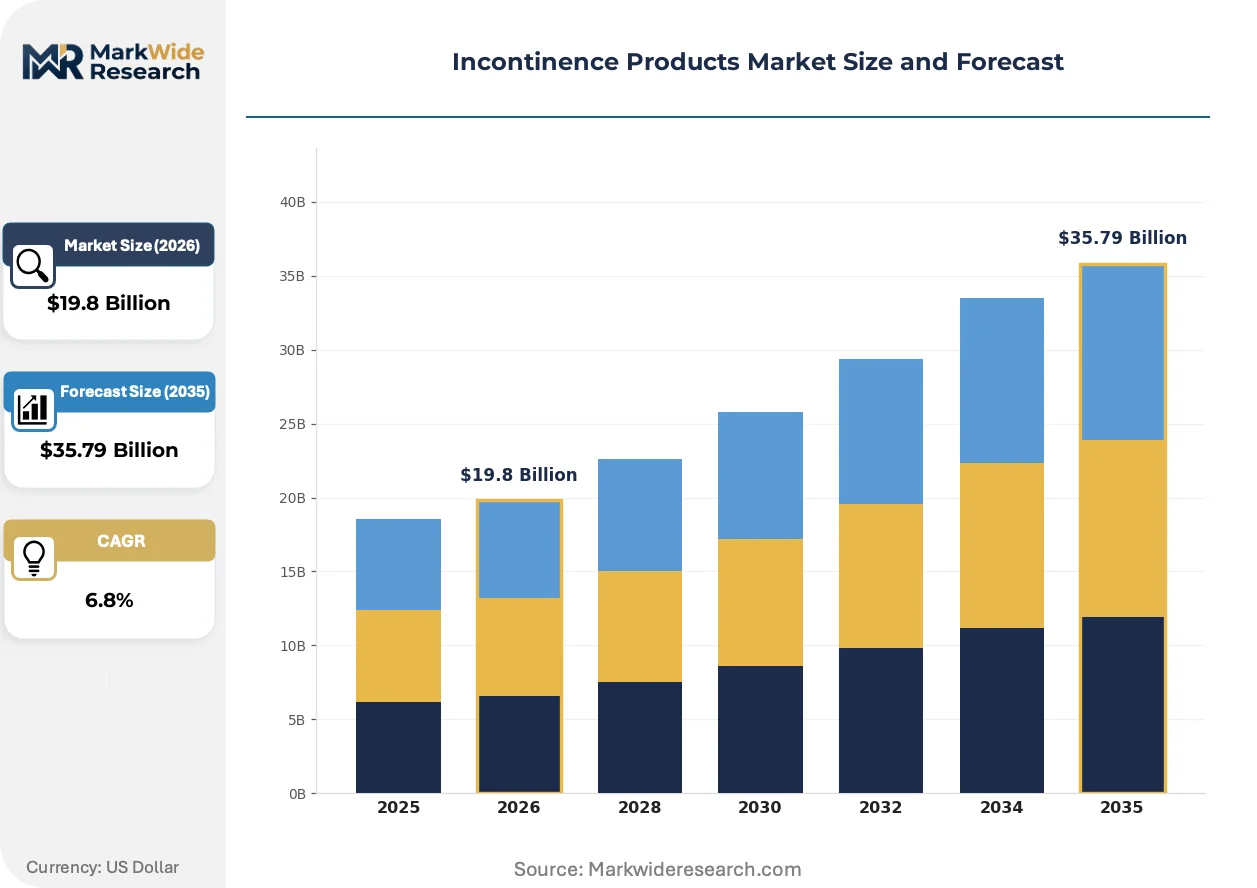
Subscription-based leasing and asset-light procurement models for institutional buyers is reshaping competitive dynamics in incontinence care. Kimberly-Clark Corporation leverages its North American manufacturing scale to anchor hospital supply contracts. Essity AB differentiates through R&D intensity in sustainable absorbent materials. Ontex specializes in private-label production for European pharmacy chains.
Incontinence products are absorbent hygiene articles engineered with superabsorbent polymers, acquisition layers, and breathable backsheet films designed to capture and isolate bodily fluids while maintaining skin integrity. These products serve therapeutic and dignity-preserving functions across acute care, long-term care, and independent living settings. Adult diapers command the largest revenue pool due to institutional volume commitments, while protective underwear captures faster growth as ambulatory users seek discretion. Home care patients represent the most rapidly expanding end-user category, though hospitals still dominate absolute volume through centralized purchasing.
The EU Medical Device Regulation (MDR) and FDA 510(k) pathways govern product registration, absorbency claims, and clinical performance documentation across their respective jurisdictions. REACH compliance in Europe and state-level Medicaid reimbursement schedules in the US directly influence material choices and market access economics. Stakeholders must monitor evolving extended producer responsibility frameworks for single-use hygiene products, as these will reshape cost structures and competitive positioning in major markets.
Market Dynamics
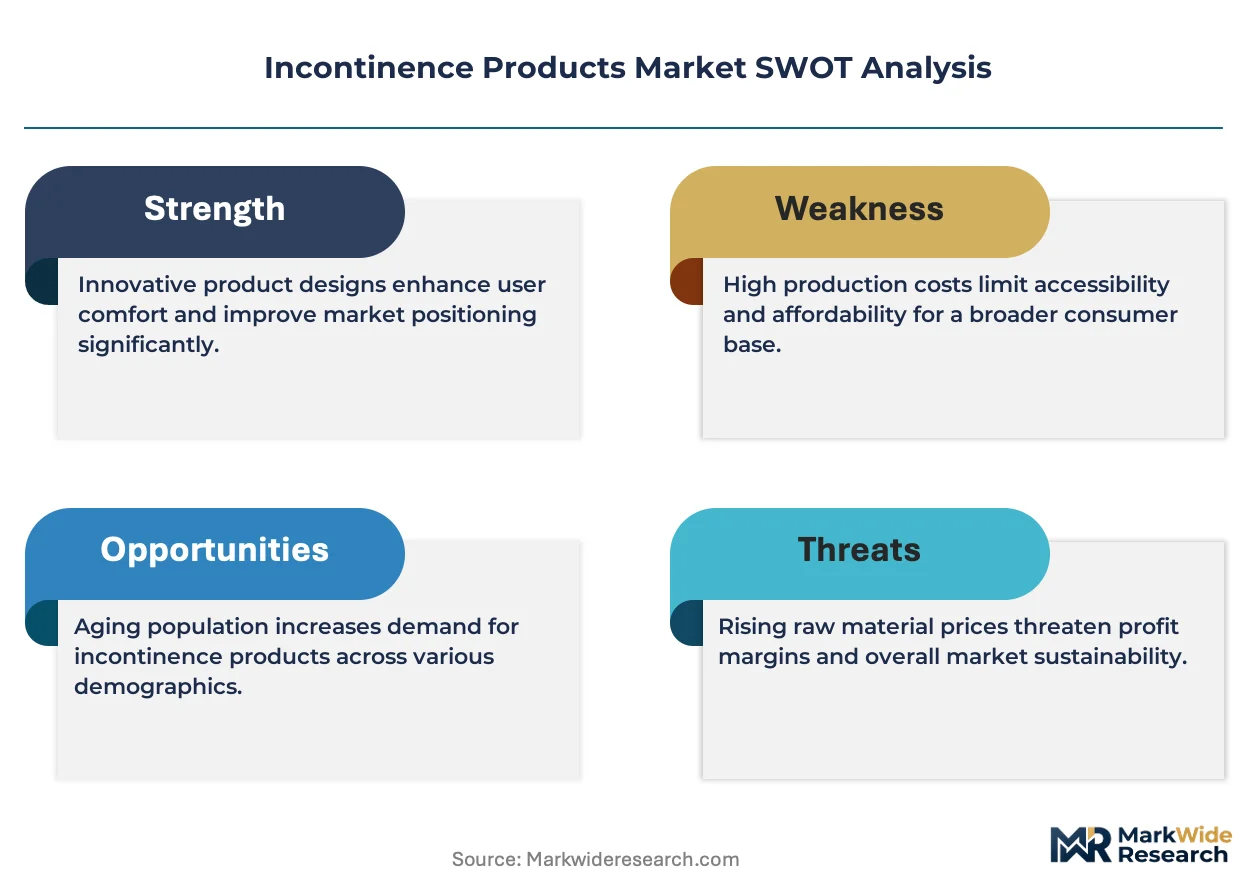
Home care preference among aging populations is compressing institutional procurement volumes while forcing manufacturers to rebalance distribution toward direct-to-consumer channels and pharmacy retail networks.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter absorbency and biocompatibility standards in Europe are accelerating product premiumization and clinical-grade certification across the supply base.
- Superabsorbent polymer innovation:Advanced SAP formulations with enhanced fluid retention and odor control are expanding addressable demand among ambulatory adults seeking discreet protection.
- Germany's reimbursement infrastructure:Comprehensive long-term care insurance coverage for incontinence supplies sustains higher per-capita utilization rates than neighboring European markets.
Market Restraints
- Petrochemical input volatility:Fluctuating polypropylene and polyethylene prices squeeze margins for breathable backsheet film production.
- Supply concentration in Southeast Asian nonwoven manufacturing:Dependence on concentrated spunbond and meltblown capacity creates vulnerability to regional logistics disruptions.
- Reusable garment substitution:Washable absorbent underwear for light-to-moderate incontinence limits addressable market for single-use products among environmentally conscious consumers.
Strategic Opportunities
- Subscription direct-to-home models:Automated replenishment services bypass pharmacy intermediaries and capture recurring revenue from home care patients.
- Extended producer responsibility frameworks:EU-wide mandates for single-use hygiene product recycling create first-mover advantage for circular material innovators.
- Smart wearable integration:Sensor-enabled garments that alert caregivers to moisture events open premium positioning in institutional and home care dementia segments.
Industry Challenges
- Clinical validation timelines:EU MDR and FDA 510(k) pathways demand extensive absorbency performance documentation, extending product launch cycles.
- Legacy distributor integration:Hospital supply chain incumbents resist disintermediation by direct-to-consumer platforms, creating channel conflict for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incontinence Products Market |
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $35.79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Diapers, Protective Underwear, Pads & Liners, Catheters, Bed Pads Application: Urinary Incontinence, Fecal Incontinence, Mixed Incontinence, Post-surgical Use End User: Hospitals, Assisted Living Facilities, Home Care Patients, Rehabilitation Centers Distribution Channel: Pharmacies, Online Retailers, Medical Supply Stores, Supermarkets |
| Companies Covered | Ontex, Medline Industries Inc., Kimberly-Clark Corporation, Paul Hartmann AG, First Quality Enterprises Inc., Essity AB, Coloplast A/S, Kao Corporation, Unicharm Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incontinence Products Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory pressure on single-use plastics are forcing simultaneous innovation in absorbent core architecture and end-of-life product design across the value chain.
Plant-based superabsorbent polymers derived from cellulose and agricultural waste streams are collapsing the historical performance gap between petroleum-derived and bio-based absorbent materials. Home care patients and sustainability-focused pharmacy chains in Northern Europe are piloting these formulations at scale. The technology is collapsing premium pricing power for conventional SAP suppliers as bio-based alternatives achieve parity on fluid retention metrics.
REACH compliance requirements for chemical safety and biodegradability are compelling reformulation of acquisition layers and adhesives across European manufacturing footprints. Industrial consequence includes accelerated R&D spend on bio-based hot-melt adhesives and plant-derived topsheet materials. Adult diaper and protective underwear categories face the steepest compliance cost increases, with German and French manufacturers leading material substitution programs.
Hospital purchasing consortiums are consolidating vendor panels and demanding outcome-based metrics linking product performance to skin integrity outcomes and nursing labor efficiency. Traditional fee-for-product supply contracts are yielding to performance-guaranteed agreements with penalty clauses for leakage-related adverse events. This behavioral shift is most pronounced in US integrated delivery networks and Dutch hospital procurement cooperatives.
Incontinence Products Market Segmentation
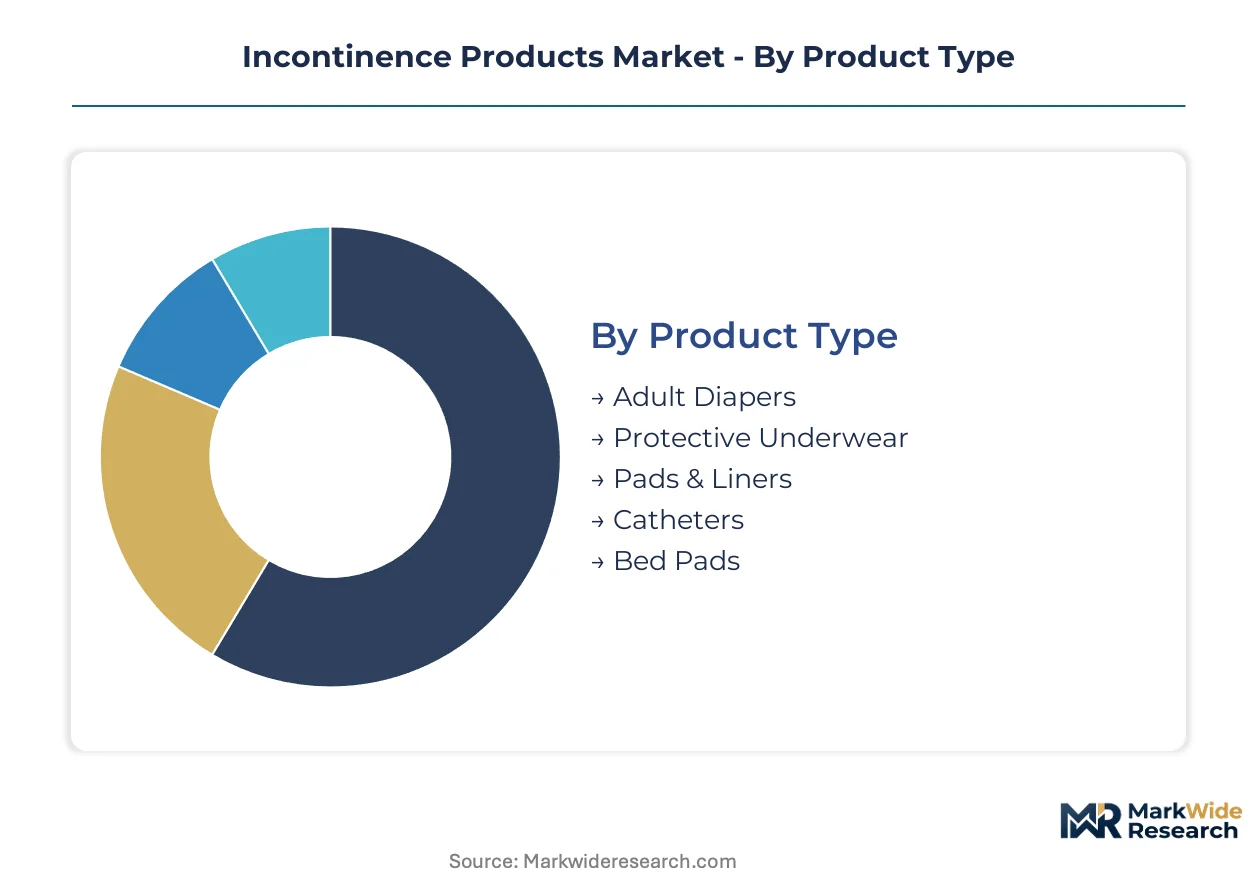
Segmentation in incontinence products determines service intensity, reimbursement pathways, and supply chain configuration. Product type dictates manufacturing complexity and clinical validation requirements. End-user channels demand divergent logistics models and customer support architectures.
Product Type:
After-sales service intensity varies sharply across product categories, with institutional volume contracts requiring field nursing support and home-use items demanding remote troubleshooting infrastructure.
- Adult Diapers:Multi-layer absorbent cores with superabsorbent polymers and breathable backsheet films engineered for extended wear. Hospital procurement consortiums in Germany and the Netherlands anchor institutional demand through centralized purchasing agreements with performance guarantees.
- Protective Underwear:Elasticized waistbands and discreet profiles mimic conventional undergarments for ambulatory users. Home care patients in Northern Europe drive expansion through pharmacy retail and subscription direct-to-home channels seeking dignity-preserving alternatives.
- Pads & Liners:Thin-profile absorbent inserts for light-to-moderate leakage management. Retail pharmacy chains stock extensive SKU ranges for self-directed consumer selection.
- Catheters:Sterile drainage devices requiring clinical insertion training and infection protocol compliance. Urology clinics and rehabilitation centers maintain specialized supply relationships.
- Bed Pads:Waterproof underlays protecting mattress surfaces from nocturnal leakage. Long-term care facilities standardize on disposable formats for hygiene protocol adherence.
Adult diapers hold the largest share; momentum sits with protective underwear.
Application:
Application segmentation tracks reimbursement coding complexity and clinical outcome documentation requirements across acute and chronic care settings.
- Urinary Incontinence:Stress, urge, and overflow variants drive the majority of product utilization. German long-term care insurance provides comprehensive coverage, sustaining higher per-capita consumption than neighboring markets.
- Fecal Incontinence:Higher-acuity condition requiring specialized odor-control formulations and skin barrier protection. Post-acute rehabilitation centers in France and Belgium generate concentrated demand for premium-tier products.
- Mixed Incontinence:Co-occurring urinary and fecal symptoms complicate product selection and sizing. Urology and gastroenterology specialists coordinate procurement decisions for complex cases.
- Post-surgical Use:Temporary protection following prostatectomy, hysterectomy, or pelvic floor procedures. Hospital discharge planning protocols increasingly prescribe take-home supplies to prevent readmission.
Urinary incontinence dominates volume; fecal incontinence commands the steepest premium pricing.
End User:
End-user concentration shapes channel strategy, with institutional buyers demanding contract pricing and home care patients requiring consumer-grade branding and discretion.
- Hospitals:Centralized materials management and infection control committees govern product selection. Dutch hospital procurement cooperatives pioneer outcome-based contracts linking leakage events to supplier penalties.
- Assisted Living Facilities:Balanced workforce of licensed nurses and certified nursing assistants influences product training requirements. Regulatory surveys in Germany and Austria mandate documented skin integrity protocols.
- Home Care Patients:Aging-in-place preferences compress institutional volumes while expanding direct-to-consumer and pharmacy retail penetration. REACH-compliant bio-based materials attract sustainability-conscious segments in Scandinavia.
- Rehabilitation Centers:Transitional care settings with intensive therapy schedules and mobility-focused recovery goals. Staff-to-patient ratios determine change-frequency requirements and product absorbency specifications.
Hospitals retain the largest absolute volume; home care patients are expanding most quickly.
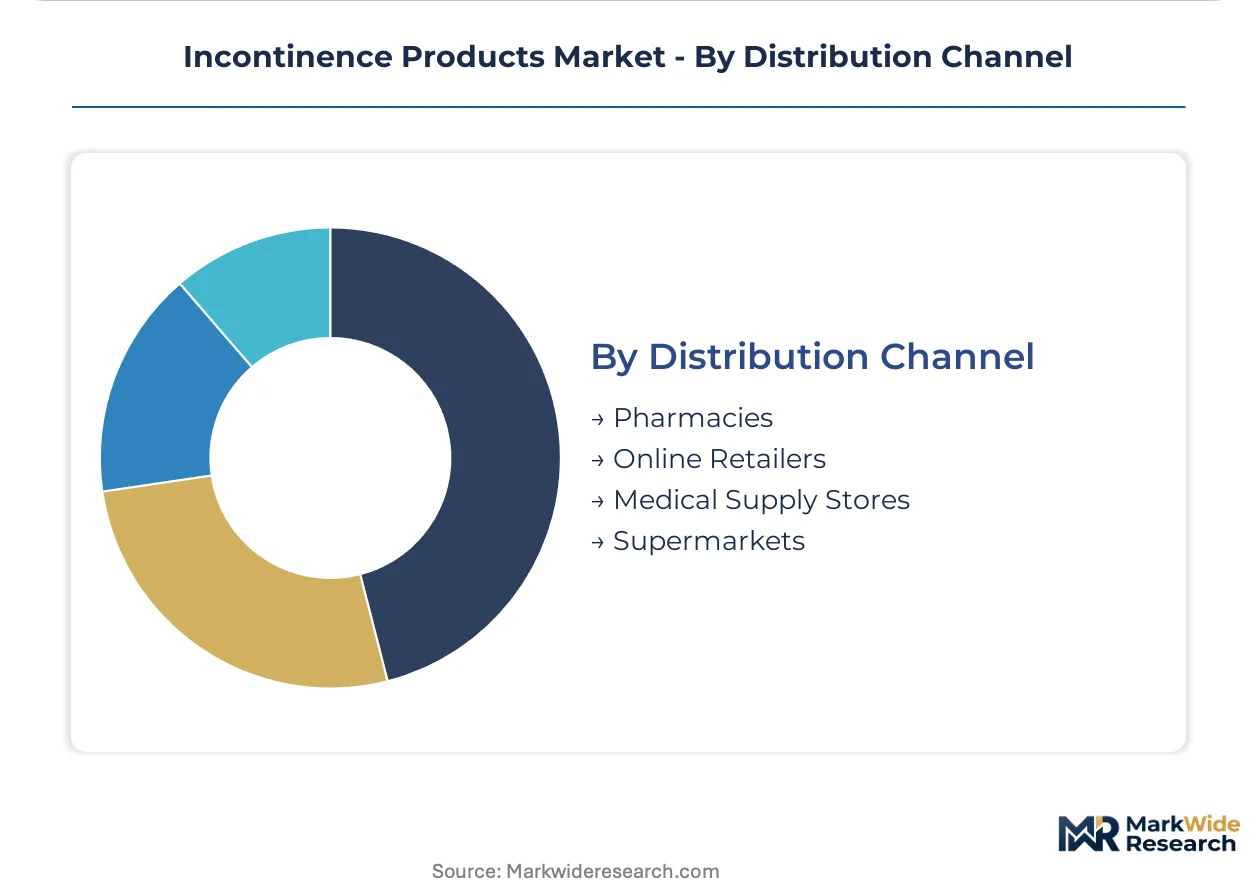
Distribution Channel:
Channel fragmentation reflects divergent customer journeys, with institutional procurement favoring contracted distributors and consumer segments migrating toward digital convenience.
- Pharmacies:Pharmacist consultation services support product selection for first-time users. German pharmacy chains maintain extensive incontinence sections with private-label and branded alternatives.
- Online Retailers:Subscription algorithms and discreet packaging address home care patient preferences for privacy and automated replenishment. EU extended producer responsibility mandates reshape logistics cost structures for cross-border e-commerce.
- Medical Supply Stores:Durable medical equipment dealers serve Medicare and Medicaid beneficiaries with insurance documentation support. State-level reimbursement schedules in the US create geographic variation in channel viability.
- Supermarkets:Mass-market retail placements normalize incontinence purchasing and reduce stigma. Limited shelf space favors high-velocity SKUs over specialized clinical grades.
Pharmacies command the largest share; online retailers gain share fastest through subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in absorbent hygiene articles tilt toward net-import dependence in Western Europe and North America, while Southeast Asian manufacturing clusters supply converted finished goods across Pacific Rim markets. Currency-adjusted procurement costs and extended producer responsibility levies are reshaping regional sourcing strategies.
Germany
Long-term care insurance coverage sustains per-capita utilization rates above European averages, with pharmacy chains and institutional procurement cooperatives anchoring distribution. The EU MDR absorbency certification requirements have compressed product launch timelines for domestic manufacturers. The Rhine-Ruhr industrial corridor hosts specialized nonwoven conversion facilities serving Central European hospital networks.
United States
State-level Medicaid reimbursement schedules create geographic variation in home care patient access, with Medicare Advantage plans increasingly covering subscription-based delivery. FDA 510(k) pathways govern clinical absorbency claims and skin integrity documentation. The Midwest manufacturing belt retains spunbond and meltblown capacity for breathable backsheet film production.
Japan
Aging demographics and single-person household growth expand ambulatory user demand for discreet protective underwear formats. METI guidelines on single-use plastics accelerate bio-based material substitution programs. The Kanto region around Tokyo concentrates R&D activity for sensor-enabled smart garments targeting dementia care segments.
France
Post-acute rehabilitation centers generate concentrated demand for premium-tier fecal incontinence products with odor-control formulations. ANSM oversight of medical device biocompatibility aligns with broader ECHA REACH compliance frameworks. The Auvergne-Rhône-Alpes cluster houses specialized adhesive and topsheet material suppliers reformulating for biodegradability mandates.
China
Rapid urbanization and expanding private long-term care infrastructure are creating institutional procurement volume growth. NMPA medical device registration requirements for absorbent hygiene products are converging toward international standards. The Yangtze River Delta manufacturing zone supplies superabsorbent polymer feedstock to regional converters serving domestic and export markets.
Incontinence Products Market Key Industry Players
On the supply side, the industry is consolidating around three structural tiers: multinational hygiene conglomerates with captive polymer supply, specialized medical device manufacturers with clinical validation expertise, and private-label converters serving pharmacy and retail channels. Strategic archetypes include scale-driven absorptive core innovators, sustainability-focused bio-material specialists, and asset-light subscription platform operators. Dominant competitive moves encompass backward integration into superabsorbent polymer production and geographic expansion through regional distributor acquisitions.
Among North American hygiene conglomerates, Kimberly-Clark Corporation occupies a position exemplifying scale-driven institutional contracting. European specialists in clinical-grade medical devices include Coloplast A/S and Paul Hartmann AG, representing the regulatory-intensive premium tier. Ontex sits within the private-label conversion archetype, anchoring supply relationships with European pharmacy retail networks.
| Leading Market Players |
|---|
| Ontex |
| Medline Industries Inc. |
| Kimberly-Clark Corporation |
| Paul Hartmann AG |
| First Quality Enterprises Inc. |
| Essity AB |
| Coloplast A/S |
| Kao Corporation |
| Unicharm Corporation |
| Others |
Cost & Logistics Intelligence
Petrochemical input volatility in polypropylene and polyethylene feedstocks compresses margin structures across breathable backsheet film production while simultaneously forcing tiered pricing spreads between clinical-grade and economy absorbent products. This cost pressure radiates through contract negotiations with hospital procurement consortiums and subscription-based direct-to-consumer channels alike.
Pricing Analysis
Hospital procurement consortiums anchor a contract-based pricing structure with volume-scaled discounts and performance-guaranteed penalty clauses for leakage-related adverse events. Price differentiation hinges on EU MDR certification tier and absorbency validation documentation, with clinical-grade products commanding substantial premiums over pharmacy retail economy lines. Pricing pressure intensifies from bio-based superabsorbent polymer substitution collapsing historical petroleum-derived SAP premiums. Home care patients demonstrate highest price sensitivity through subscription algorithm comparison shopping, while integrated delivery networks maintain lowest sensitivity due to outcome-based contracting insulation.
Supply Chain Analysis
Extended payment terms from German and Dutch hospital procurement cooperatives strain working capital for nonwoven converters while supply-chain finance facilities concentrate liquidity access among multinational hygiene conglomerates. Manufacturing gravity centers on Southeast Asian spunbond and meltblown capacity in Thailand and Indonesia, with the Rhine-Ruhr corridor retaining specialized conversion for European clinical-grade production. Raw material dependencies span superabsorbent polymer feedstock from the Yangtze River Delta, breathable film resins from Saudi petrochemical complexes, and bio-based cellulose derivatives from Nordic pulp processors. Single-source vulnerability in Southeast Asian nonwoven capacity creates exposure to regional logistics disruptions. Distribution runs through pharmacy retail networks for home care patients and contracted medical supply distributors for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in home care patient segments as aging-in-place preferences disintermediate traditional institutional procurement channels and create niche openings for specialized subscription operators.
For Market Incumbents: Harden supply chain resilience through backward integration into superabsorbent polymer production or captive nonwoven manufacturing in the US Midwest industrial belt. Lock in exclusive performance-guaranteed contracts with Dutch hospital procurement cooperatives before outcome-based metrics become universal. Defend against bio-based material substitution by accelerating R&D spend on plant-derived acquisition layers that preempt REACH compliance cost advantages for emerging competitors. For New Entrants and Emerging Players: Pursue white-space opportunity in sensor-enabled smart garments for dementia care segments, where institutional pilot programs in Japanese Kanto-region facilities validate premium positioning. Target Scandinavian home care patients through subscription direct-to-home models emphasizing REACH-compliant bio-based materials and discreet packaging. Anchor initial market entry through pharmacy private-label partnerships with Northern European retail chains seeking sustainable product differentiation. For Investors and Strategic Acquirers: The market sits at a premiumization phase that favors clinical-grade medical device manufacturers with EU MDR certification infrastructure and established urology clinic relationships. Long-term viability over the next decade hinges on regulatory compliance capabilities rather than commodity scale. Acquisition targets should demonstrate validated absorbency performance documentation and existing hospital system partnerships. Monitor EU extended producer responsibility framework implementation timelines as the critical inflection signal for circular material economics reshaping competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Clinical-grade absorbency validation opens institutional procurement contracts with German hospital networks. |
| Bio-based Material Transition | Plant-derived superabsorbent polymers preempt REACH compliance penalties and attract Scandinavian pharmacy chains. |
| Subscription Platform Development | Automated replenishment algorithms capture recurring revenue from aging-in-place home care patients. |
| Smart Wearable Integration | Sensor-enabled moisture alerts command premium pricing in Japanese dementia care institutional segments. |
| Extended Producer Responsibility Compliance | EU-wide recycling mandates create first-mover advantage for circular material innovators in absorbent hygiene. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with supply chain directors at hospital procurement consortiums, category managers at European pharmacy retail networks, and R&D leads at absorbent material suppliers; and secondary validation through EU MDR certification databases, FDA 510(k) filings, REACH compliance registries, and customs trade data on superabsorbent polymer feedstock flows. Bottom-up triangulation across product type segmentation and top-down reconciliation against national long-term care insurance expenditure data anchored volume and value estimates.
Forecast inputs incorporated product type segmentation across adult diapers, protective underwear, and pads; end-user channel dynamics spanning hospitals, assisted living facilities, and home care patients; and application severity tiers from light urinary to fecal incontinence with odor-control requirements. CAGRs were derived from regression analysis against aging demographic projections and reimbursement policy trajectories, with cross-validation against historical utilization elasticities in German and Japanese markets. Bio-based material substitution curves and EU extended producer responsibility implementation timelines served as scenario-weighting variables.
Sensitivities concentrate around petrochemical price volatility, REACH biodegradability mandate acceleration, and Medicaid reimbursement schedule fragmentation across US states. Forecasts reflect documented assumptions on home care patient preference shifts and institutional procurement consolidation trajectories. Macroeconomic contraction affecting long-term care insurance solvency, regulatory deviation in MDR absorbency certification timelines, or breakthrough reusable garment technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Ejiao Health Products Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Global Consumer Healthcare Products Market
Healthcare Products
Nursing Products Market
Healthcare Products
Global Life Science Products Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Medical Products Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Toothbrush Sanitizer Market
Healthcare Products
Consumer Healthcare Market