
 Global Life Science Products Market | 2026-2036
Global Life Science Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Life Science Products Market Foresight
ISO 13485 certification is unwinding the competitive landscape for analytical systems suppliers. Thermo Fisher Scientific leverages its vertical integration across reagents and instruments to sustain pricing power in bioprocessing workflows. Danaher Corporation anchors its position through stringent quality management systems that dominate clinical diagnostics channels. Merck KGaA competes by extending its biosafety testing portfolio to capture downstream validation demand from gene therapy manufacturers.
Life science products encompass instruments, reagents, consumables, and analytical systems engineered to precise optical, thermal, and fluidic tolerances for biological sample manipulation, measurement, and manufacturing scale-up. These products enable reproducible data generation, process validation, and regulatory-compliant production across pharmaceutical, agricultural, and environmental applications. Chromatography systems command the largest installed base among technology segments, though microfluidics represents the fastest-expanding margin pool as miniaturization reduces reagent volumes and assay turnaround times. Diagnostics reagents generate recurring revenue streams that outperform capital-intensive laboratory instruments in profitability stability, while genomics products attract premium pricing from CRISPR-guided cell therapy developers requiring certified nucleic acid inputs.
FDA enforces Current Good Manufacturing Practice standards that dictate equipment qualification protocols and batch record integrity for pharmaceutical manufacturers seeking market authorization. EMA's Medical Device Regulation and REACH chemical restrictions compound compliance burdens for suppliers distributing across European Union member states. China's NMPA accelerates localized type testing requirements that reshape import substitution strategies for foreign instrument vendors. Stakeholders must monitor how divergent qualification timelines between FDA 510(k) pathways and EMA notified body reviews redistribute commercial launch sequencing and regional revenue recognition.
Market Dynamics
Single-use bioprocessing systems are compressing equipment qualification timelines while fragmenting supplier relationships across pharmaceutical manufacturing networks. This shift from stainless-steel infrastructure is redistributing capital deployment patterns and reconfiguring validation protocols for multi-product facilities.
Growth Catalysts
- ATMP Guidelines Expansion:EMA's evolving advanced therapy medicinal products framework is accelerating qualification demand for gene therapy manufacturers seeking centralized marketing authorization across EU member states.
- Microfluidics Integration:Miniaturized fluidic architectures are displacing conventional chromatography workflows in cell therapy process development, reducing reagent volumes by orders of magnitude.
- China NMPA Localization:Accelerated type testing mandates for imported analytical instruments are forcing foreign vendors to establish domestic manufacturing footprints or forfeit market access.
Market Restraints
- Resin Supply Concentration:Chromatography media production concentrates among three specialized chemical suppliers, creating input vulnerability for downstream purification system manufacturers.
- REACH Chemical Restrictions:ECHA's evolving substance authorization requirements are extending compliance timelines for reagent formulations containing candidate-listed compounds.
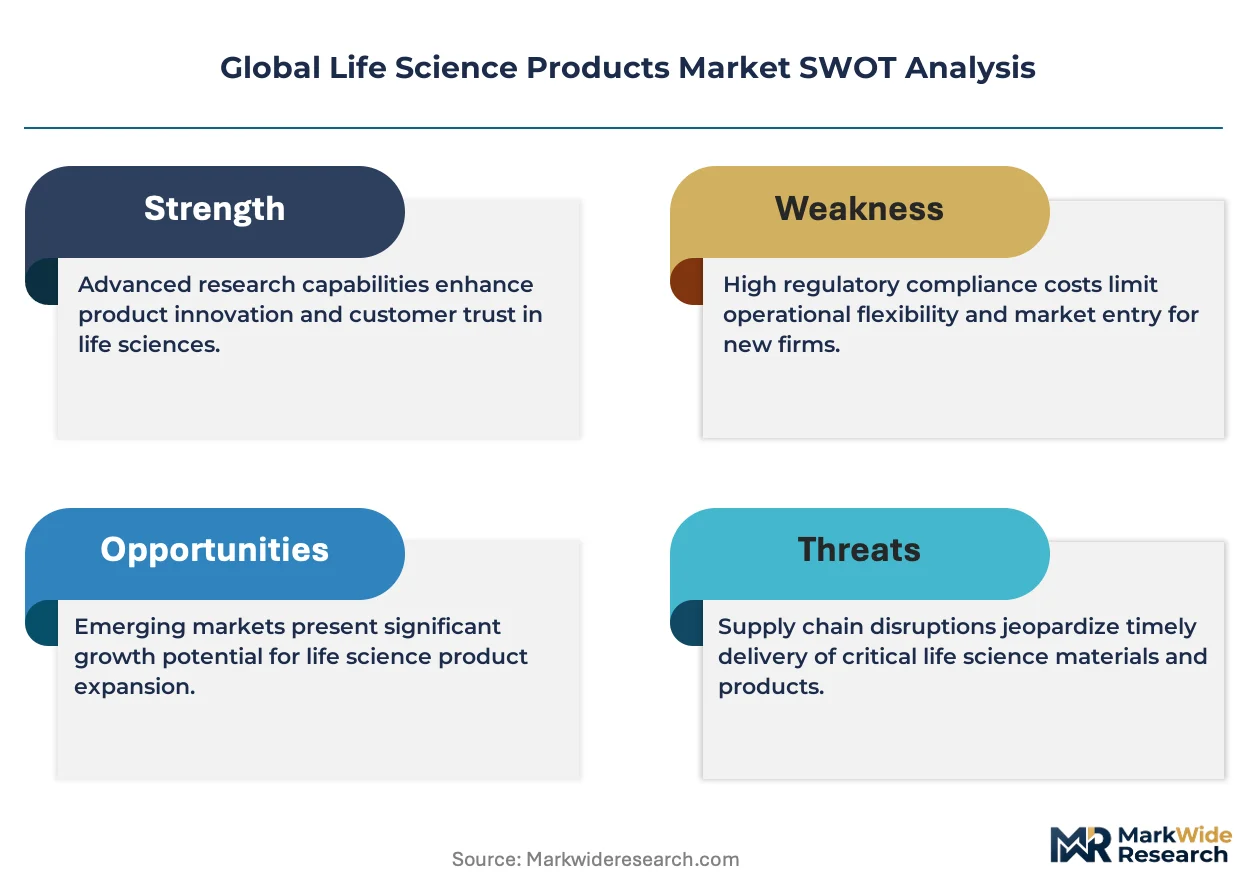
- Qualification Cost Escalation:FDA's enhanced equipment validation documentation under Quality by Design is inflating pre-commercialization expenditure for multi-modal analytical platforms.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Maharashtra and Telangana are underpenetrated for biosafety testing services, creating white space for validation portfolio extensions.
- CRISPR Input Certification:Premium-grade nucleic acid reagents for cell therapy developers command pricing power where ISO 13485-certified supply chains remain scarce.
- Service Unbundling:After-sales support contracts are separating from capital equipment sales, enabling recurring revenue capture independent of instrument replacement cycles.
Industry Challenges
- Metrology Skill Scarcity:Optical system calibration expertise for fluorescence-activated cell sorting platforms is concentrated among aging specialist workforces in Massachusetts and Baden-Württemberg.
- Legacy Integration Friction:Digital batch record systems encounter interoperability failures when interfacing with decades-old distributed control architectures in established biologics facilities.
- Notified Body Bottlenecks:EMA's Medical Device Regulation implementation has compressed review capacity, extending CE marking timelines for in-vitro diagnostic instrument launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Life Science Products Market |
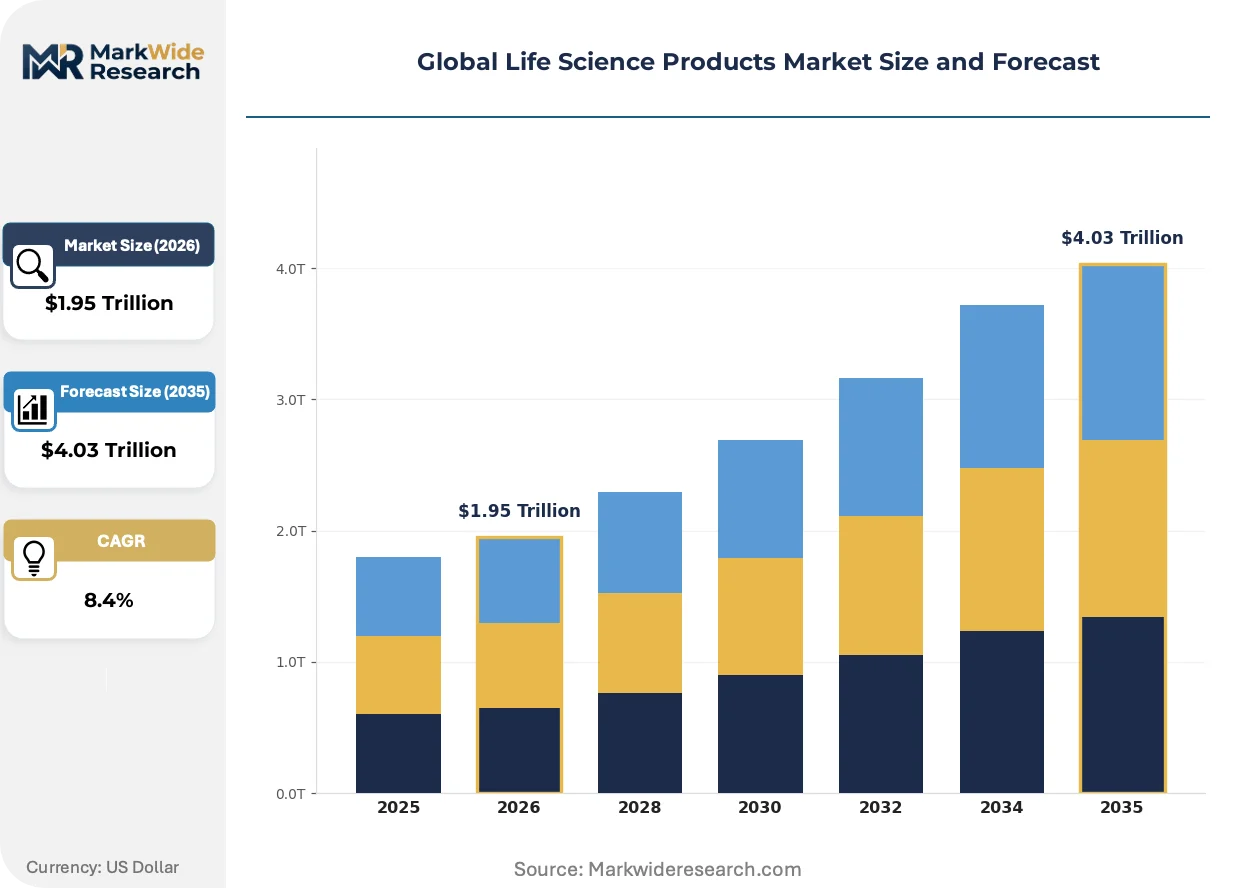
| Market Size in 2026 | $1.95 Trillion |
| Market Size in 2035 | $4.03 Trillion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioprocessing Equipment, Laboratory Instruments, Diagnostics Reagents, Genomics Products, Analytical Systems Technology: Chromatography, Spectrometry, Electrophoresis, PCR Technology, Microfluidics Application: Drug Discovery, Clinical Research, Agricultural Biotechnology, Environmental Testing, Food Safety Analysis End User: Pharmaceutical Manufacturers, Research Institutions, Biotechnology Firms, Diagnostic Laboratories, Academic Centers |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Danaher Corporation, Bio-Rad Laboratories, Agilent Technologies, Becton Dickinson and Company, F. Hoffmann-La Roche, Illumina, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Life Science Products Market Shifts & Advancements
Fluidic architectures and data infrastructure are converging to compress assay turnaround times while fragmenting traditional equipment procurement patterns. These shifts are redistributing value capture from capital hardware toward consumable and service revenue streams.
Microfluidic cartridge systems are miniaturizing sample preparation workflows for next-generation sequencing pipelines. Cell therapy developers in Boston and San Diego are adopting these platforms at accelerating pace to reduce nucleic acid input requirements. The technology is miniaturizing reagent consumption and enabling point-of-care analytical deployment that bypasses centralized laboratory infrastructure.
REACH chemical authorization timelines are extending compliance burdens for reagent suppliers distributing across European Union member states. ECHA's evolving candidate list is forcing formulation redesigns for histology stains and cell culture media additives. In-vitro diagnostic manufacturers with integrated chemical synthesis capabilities are internalizing substitution R&D to preserve market access.
Consolidated procurement consortia among top-ten pharmaceutical manufacturers are compressing vendor negotiation cycles and unbundling service contracts from capital purchases. Thermo Fisher Scientific and Danaher Corporation are encountering purchasing departments that benchmark total cost of ownership across multi-year horizons. Germany's largest CDMO networks are pioneering this model, pressuring mid-tier analytical suppliers to adopt subscription-based pricing or exit preferred vendor lists.
Global Life Science Products Market Segmentation
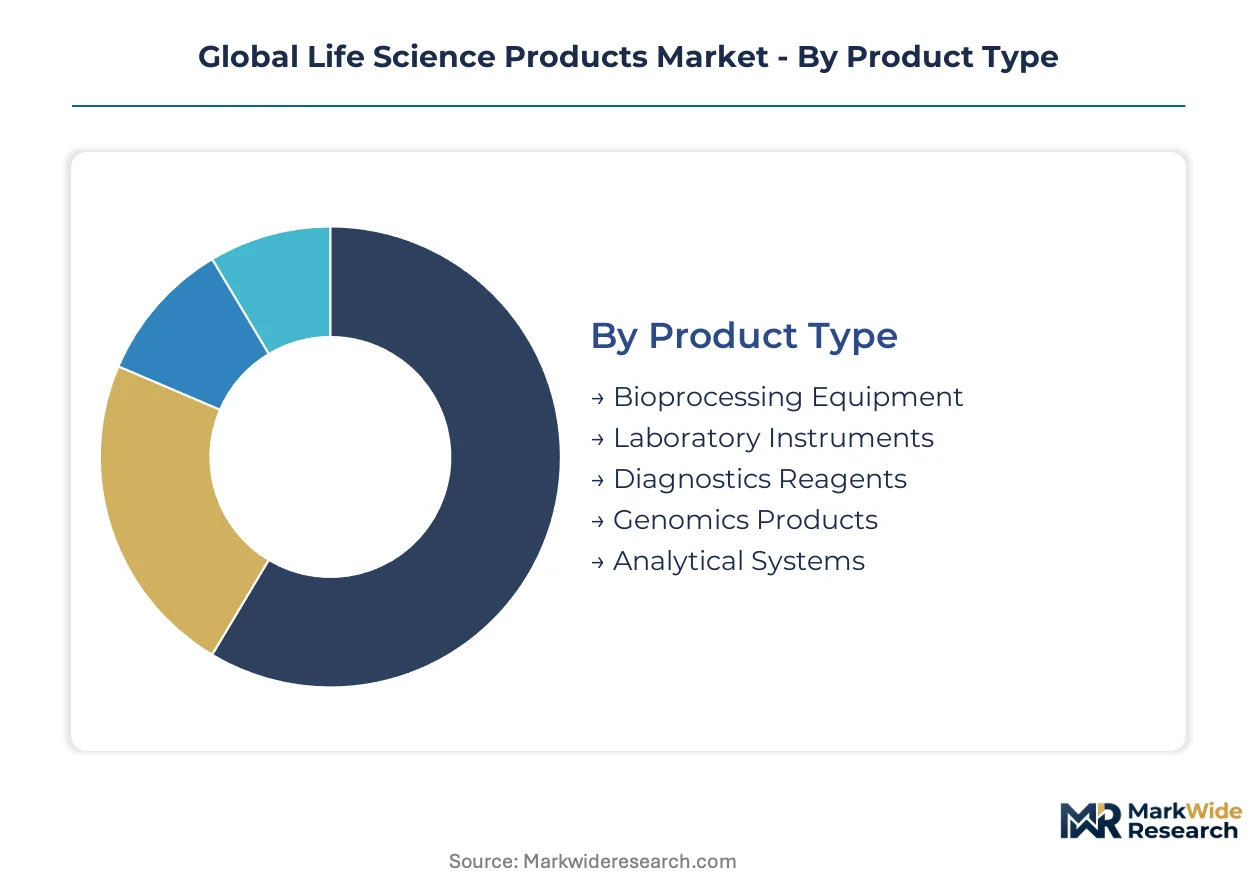
Segmentation in life science products reveals distinct procurement patterns across regulated industries. Pharmaceutical manufacturers prioritize qualification documentation while research institutions optimize for experimental flexibility. Understanding these divergent purchasing logics enables targeted portfolio positioning.
Product Type:
Domestic production dominates bioprocessing equipment and diagnostics reagents, while genomics products and analytical systems flow through concentrated export channels from Massachusetts and Baden-Württemberg.
- Bioprocessing Equipment:Stainless-steel and single-use systems engineered for sterile fluid handling and cell culture propagation. Demand concentrates among GMP-certified facilities in the United States and Germany as ATMP manufacturing scales.
- Laboratory Instruments:Automated liquid handlers, centrifuges, and incubators with precision thermal and optical controls. Research institutions in Boston and Basel drive replacement cycles as NIH and Horizon Europe funding expands.
- Diagnostics Reagents:Immunoassay and molecular detection consumables with batch-certified stability profiles.
- Genomics Products:Certified nucleic acid extraction kits and CRISPR guide RNA synthesis services.
- Analytical Systems:Integrated chromatography and mass spectrometry platforms requiring IQ/OQ/PQ validation protocols.
Diagnostics reagents command the established base. The steepest expansion runs through genomics products.
Technology:
Cost tiering separates capital-intensive platforms from consumable-driven workflows, with microfluidics occupying a mid-tier position that fragments traditional procurement bundles.
- Chromatography:Purification systems leveraging resin-based separation media for biomolecule fractionation. Pharmaceutical manufacturers in Germany and Switzerland anchor installed base maintenance while China NMPA localization pressures import substitution.
- Spectrometry:Mass and optical detection systems quantifying molecular composition through ionization and light dispersion. Proteomics facilities in Cambridge and San Diego drive high-resolution platform upgrades as multi-omics integration accelerates.
- Electrophoresis:Gel and capillary systems separating charged biomolecules by size and charge.
- PCR Technology:Thermal cycling instruments amplifying nucleic acid sequences for diagnostic and research applications.
- Microfluidics:Miniaturized fluidic architectures integrating sample preparation and detection on chip-scale devices.
Chromatography systems retain the deepest installed base. Microfluidics platforms are climbing the fastest as cell therapy process development miniaturizes.
Application:
Volume concentration in drug discovery and clinical research absorbs the majority of high-value analytical instrument shipments, while agricultural and environmental applications sustain mid-tier reagent consumption.
- Drug Discovery:Target identification and lead optimization workflows requiring high-throughput screening and structural biology capabilities. Biotechnology firms in South San Francisco and Cambridge, Massachusetts, compress assay timelines through integrated automation.
- Clinical Research:Patient sample analysis and biomarker validation supporting trial endpoints. Contract research organizations in India and Eastern Europe expand bioanalytical capacity as sponsor geographic diversification accelerates.
- Agricultural Biotechnology:Crop trait development and seed quality testing for yield optimization.
- Environmental Testing:Water and soil contaminant monitoring using portable and laboratory-based detection systems.
- Food Safety Analysis:Pathogen detection and allergen quantification for regulatory compliance across supply chains.
Drug discovery absorbs the premium instrument volume. Clinical research applications are gaining share fastest as decentralized trial models proliferate.
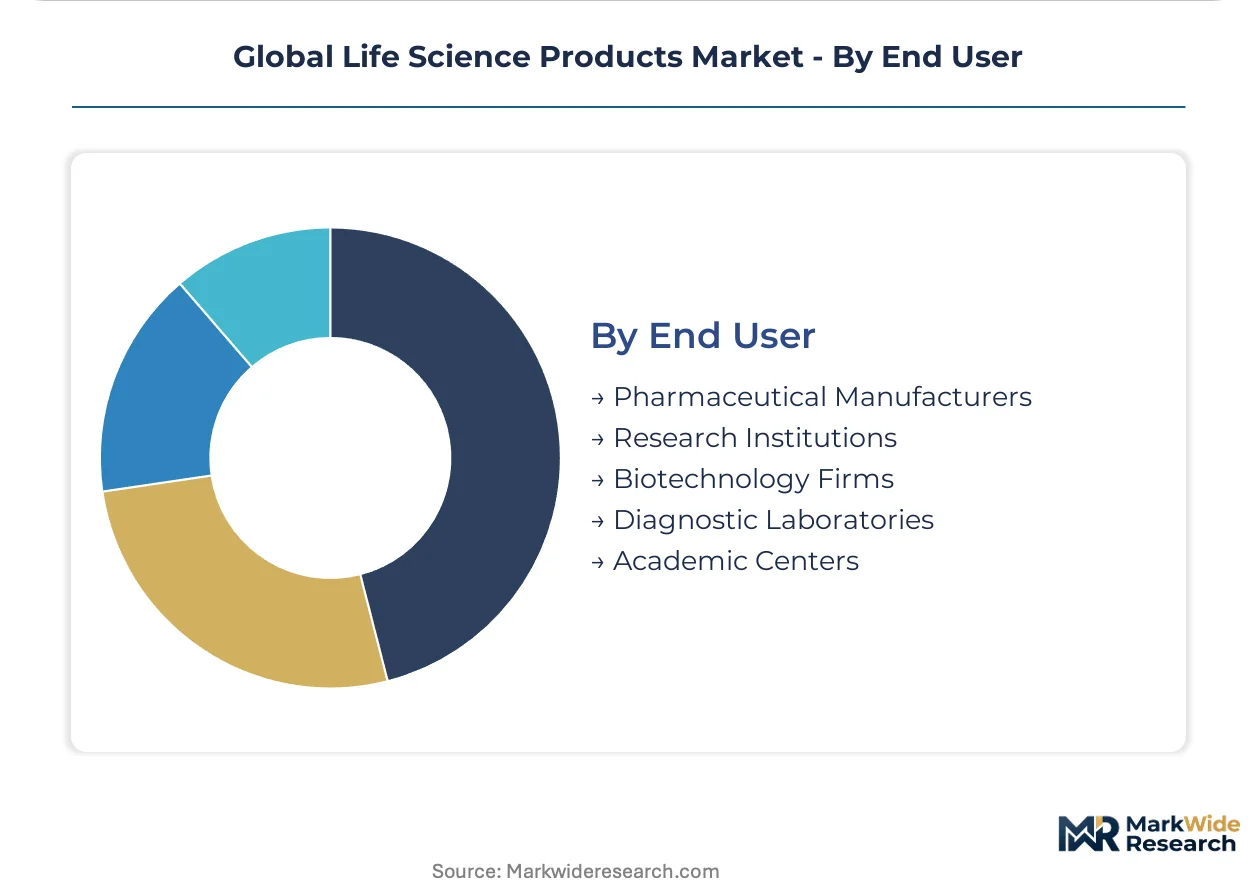
End User:
Customer type stratification separates capital-intensive pharmaceutical procurement from the fragmented purchasing patterns of academic centers, with diagnostic laboratories occupying a hybrid position that unbundles service contracts.
- Pharmaceutical Manufacturers:GMP-compliant production facilities requiring validated equipment and documented supply chains. FDA Quality by Design and EMA ATMP guidelines tighten qualification requirements for multi-product biologics plants in the United States and European Union.
- Research Institutions:Government and private laboratories prioritizing experimental flexibility over regulatory documentation. NIH-funded centers in Bethesda and Wellcome Trust facilities in London drive open-architecture instrument preferences.
- Biotechnology Firms:Venture-backed developers of cell and gene therapies with concentrated nucleic acid reagent demand.
- Diagnostic Laboratories:Clinical reference labs and hospital-based testing facilities with high-throughput automation requirements.
- Academic Centers:University research departments with constrained capital budgets and diversified experimental programs.
Pharmaceutical manufacturers anchor the premium segment. Biotechnology firms are expanding most quickly as gene therapy pipelines mature toward commercial manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Quality by Design initiative and EMA's evolving ATMP guidelines are redistributing manufacturing investment toward jurisdictions with streamlined qualification pathways. NMPA localization mandates in China and CDSCO's accelerated approval frameworks in India are reshaping vendor market entry sequencing.
United States
Boston and San Diego biotechnology clusters drive concentrated demand for CRISPR-certified nucleic acid inputs. FDA's enhanced equipment validation documentation under Quality by Design inflates pre-commercialization expenditure for multi-modal analytical platforms. Massachusetts anchors fluorescence-activated cell sorting platform deployment as cell therapy pipelines mature toward commercial manufacturing.
Germany
Baden-Württemberg and North Rhine-Westphalia host the densest concentration of GMP-certified biologics manufacturing facilities in Europe. EMA's Medical Device Regulation and REACH chemical restrictions compound compliance burdens for suppliers distributing across EU member states. Heidelberg and Munich research institutions compress assay timelines through integrated automation as Horizon Europe funding expands.
China
Yangtze River Delta and Pearl River Delta biopharmaceutical parks are scaling procurement of single-use bioprocessing systems. NMPA accelerates localized type testing requirements that reshape import substitution strategies for foreign instrument vendors. Shanghai and Suzhou manufacturing bases internalize chromatography media production to reduce resin supply concentration vulnerability.
India
Maharashtra and Telangana contract development and manufacturing organizations expand bioanalytical capacity as sponsor geographic diversification accelerates. CDSCO's evolving biosafety testing frameworks create white space for validation portfolio extensions. Hyderabad and Mumbai clusters undercut Western cost structures for clinical research sample analysis and biomarker validation.
Switzerland
Basel and Zurich anchor high-value analytical instrument shipments for proteomics and structural biology applications. Swissmedic maintains alignment with EMA centralized marketing authorization while preserving faster qualification timelines for ATMP manufacturers. Roche and Novartis procurement consortia benchmark total cost of ownership across multi-year horizons, pressuring mid-tier suppliers toward subscription pricing.
Global Life Science Products Market Competitive Landscape
Player mix skews toward diversified conglomerates with captive reagent supply chains and specialized diagnostics pure-plays. The vendor base separates into three tiers: integrated life science conglomerates commanding full workflow portfolios, precision instrument specialists with embedded service revenue, and regional consumables fabricators competing on batch certification speed. Consolidation pressure intensifies as procurement consortia unbundle service contracts from capital purchases and benchmark total cost of ownership across multi-year horizons.
Among integrated conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify archetypes that leverage backward integration across reagents and instruments to sustain pricing power in bioprocessing workflows. Merck KGaA occupies a position within the validation-centric tier, extending biosafety testing portfolios to capture downstream demand from gene therapy manufacturers. These three anchors demonstrate how quality management system certification and vertical control over consumable inputs determine competitive position as regulatory qualification requirements tighten across FDA, EMA, and NMPA jurisdictions.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Danaher Corporation |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Becton Dickinson and Company |
| F. Hoffmann-La Roche |
| Illumina |
| PerkinElmer |
| Others |
Supply & Pricing Matrix
FDA Quality by Design protocols and EMA ATMP qualification requirements simultaneously gate supply eligibility and stratify price tiers across bioprocessing equipment and analytical systems. Certification-grade differentiation separates ISO 13485-validated suppliers from commodity reagent vendors, compressing margins in the latter while sustaining premium capture among qualified incumbents serving GMP-certified pharmaceutical manufacturers.
Pricing Analysis
Certification level (ISO 13485/FDA-grade/CE-marked) creates the primary spread between premium and standard tiers across chromatography systems and diagnostics reagents. Three-tier pricing structure across premium, standard, and economy levels dominates, with quality-grade validation and after-sales service bundling as secondary differentiators. Cost compression in standard-grade consumables is intensifying because consolidated procurement consortia benchmark total cost of ownership across multi-year horizons. Academic centers and small biotechnology firms exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize qualification documentation over unit economics.
Supply Chain Analysis
Germany and the United States anchor precision optical component fabrication and chromatography resin formulation for analytical systems. China and India supply nucleic acid extraction kits and biosafety testing consumables, with the former internalizing chromatography media production to reduce import dependency. Single-source vulnerability concentrates in specialized resin suppliers for downstream purification systems. Distribution runs through GMP-certified manufacturing facilities in Massachusetts, Baden-Württemberg, and Shanghai biopharmaceutical parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized metrology expertise for fluorescence-activated cell sorting calibration and optical system qualification represents the critical capability gap constraining expansion in cell therapy manufacturing workflows. This scarcity redistributes competitive advantage toward incumbents with captive specialist workforces.
For Market Incumbents: Compound defensive positioning through backward integration into chromatography resin production and accelerated ISO 13485 certification investment for gene therapy input portfolios. Threat substitution from microfluidics platforms displacing conventional chromatography workflows demands pre-emptive cartridge technology acquisition or partnership. Channel control through unbundled service contracts independent of instrument replacement cycles remains the priority lever for recurring revenue capture. For New Entrants and Emerging Players: CDSCO fast-track biosafety testing frameworks in Maharashtra and Telangana create entry pathways for validation portfolio extensions targeting underpenetrated Indian CDMO networks. White space concentrates in CRISPR-certified nucleic acid reagents where ISO 13485 supply chains remain scarce. Go-to-market positioning through subscription-based pricing models aligns with consolidated procurement consortia benchmarking total cost of ownership. For Investors and Strategic Acquirers: EMA Medical Device Regulation implementation reshapes the acquisition landscape by extending CE marking timelines and compressing notified body capacity. Long-term viability favors vertically integrated platforms with captive reagent supply chains and embedded service revenue. Target acquisition archetype: precision instrument specialists with aging specialist workforces in Massachusetts or Baden-Württemberg. Signal to monitor: NMPA localization mandate acceleration forcing domestic manufacturing footprint establishment.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management system validation gates supply eligibility for FDA-regulated pharmaceutical manufacturers. |
| Microfluidics Platform Integration | Miniaturized fluidic architectures displace conventional chromatography in Boston and San Diego cell therapy pipelines. |
| India CDMO Partnership | Maharashtra and Telangana bioanalytical capacity expansion captures sponsor geographic diversification demand. |
| Service Contract Unbundling | After-sales support separation from capital sales enables recurring revenue independent of instrument cycles. |
| Chromatography Resin Internalization | Captive supply of purification media reduces vulnerability to three-supplier concentration risk. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bioprocessing equipment procurement managers, regulatory affairs leads at gene therapy developers, GMP facility qualification specialists, and chromatography resin supply planners. Secondary validation drew from FDA 510(k) filings, EMA centralized marketing authorization submissions, NMPA type testing registries, and REACH candidate list updates. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Across the analysis window, volume and value outputs reflect integrated modeling across product type, technology platform, application workflow, and end-user procurement archetype. CAGRs derive from regression analysis against biopharmaceutical capital expenditure patterns and NIH/Horizon Europe funding disbursements. Industry-specific inputs include single-use bioprocessing adoption rates and ATMP manufacturing facility commissioning timelines.
The analysis sits within stated boundaries; outcomes outside sustained regulatory alignment between FDA, EMA, and NMPA jurisdictions would require recalibration. Forecasts reflect documented assumptions regarding qualification timeline convergence and resin supply concentration stability. Recalibration cycles align with material shifts in ATMP guideline implementation and notified body capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Isolation Gowns Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Medical Products Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Nursing Products Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
Global Healthcare Distribution Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Ejiao Health Products Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Organ Care Products Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
United States Infrared Sauna Market