
 Anti-Inflammatory Cytokines Market | 2026-2036
Anti-Inflammatory Cytokines Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Inflammatory Cytokines Market Analytics
Specialty pharmacy distribution networks is reshaping how anti-inflammatory cytokine therapies reach hospital and outpatient settings. AbbVie leverages its immunology franchise infrastructure to sustain refrigerated logistics across North American infusion centers. Pfizer anchors global manufacturing scale through multi-site biologics production, while Amgen differentiates via recombinant protein engineering leadership in interleukin-modulating candidates.
Anti-inflammatory cytokines comprise signaling proteins—predominantly interleukins, tumor necrosis factors, and transforming growth factors—that suppress pro-inflammatory immune responses through receptor-mediated pathways, typically manufactured via mammalian cell culture or microbial fermentation systems for therapeutic modulation of autoimmune pathology. Injectable delivery mode dominates value capture due to bioavailability requirements and cold-chain premium pricing, whereas oral formulations represent an emerging margin pool with formulation innovation. Interleukins lead product type segmentation given established clinical utility in rheumatoid arthritis and inflammatory bowel disease, while cancer therapy applications show fastest trajectory expansion through checkpoint combination protocols.
FDA biologics license application pathways and EMA centralized marketing authorization procedures govern approval standards, with both agencies intensifying post-market pharmacovigilance for cytokine-related immunogenicity signals. ISO 13485 quality management frameworks and current good manufacturing practice standards enforce batch consistency across contract development and manufacturing organizations. Stakeholders must monitor evolving biosimilar interchangeability designations and real-world evidence requirements that will determine competitive positioning for next-generation cytokine modulators.
Market Dynamics
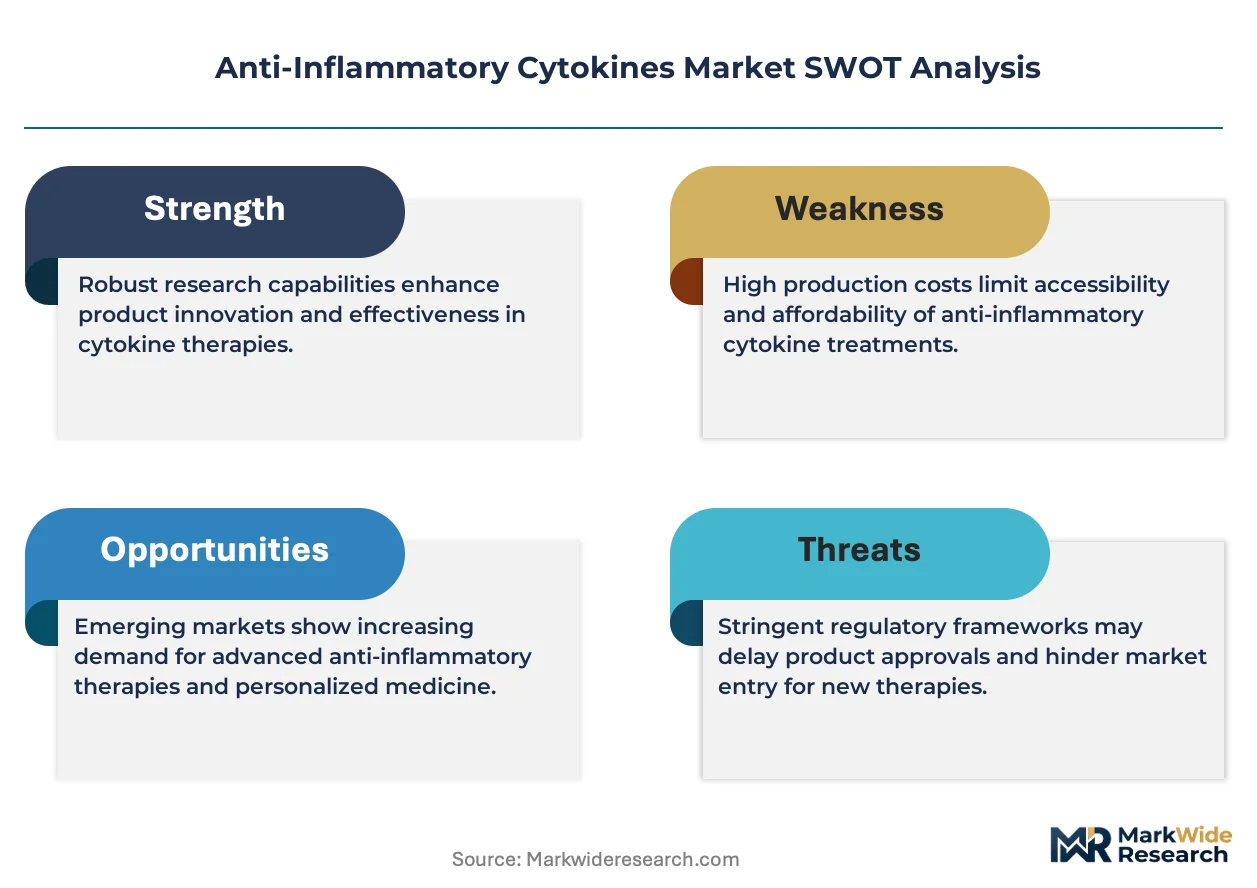
Biopharmaceutical contract manufacturing organizations are consolidating production assets around mammalian cell culture capacity, creating supply-side bottlenecks that favor sponsors with locked-in manufacturing slots over emerging developers seeking entry.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase III timelines for biologics addressing unmet autoimmune needs, enabling faster commercialization of interleukin-modulating candidates.
- Rheumatology infusion center expansion:Hospital outpatient departments in the United States are adding dedicated biologic administration suites, expanding addressable patient populations for injectable cytokine therapies.
- Single-use bioreactor adoption:Stainless steel replacement with disposable systems is cutting changeover time between recombinant protein campaigns, raising effective manufacturing throughput.
Market Restraints
- Chinese hamster ovary cell supply concentration:Master cell bank repositories concentrate in three contract development and manufacturing organizations, creating single-source vulnerability for mammalian-derived cytokine production.
- Cold-chain cost escalation:Refrigerated logistics for 2-8°C injectable biologics absorbs 12-18% of product revenue, compressing margins for high-volume indications.
- Biosimilar substitution pressure:EMA interchangeability guidelines and US state-level substitution laws are eroding originator pricing power ahead of patent cliffs for established interleukin inhibitors.
Strategic Opportunities
- Japan's aging autoimmune patient pool:PMDA's Sakigake designation offers priority review for cytokine therapies targeting rheumatoid arthritis in a market with 65-plus demographic expansion.
- Oral formulation white space:Encapsulation technologies for peptide delivery are opening margin pools beyond injectable dominance, with gastrointestinal-targeted indications showing particular promise.
- EMA centralized pediatric investigation plans:The mandate creates regulatory tailwind for sponsors developing juvenile idiopathic arthritis indications, a historically underserved segment.
Industry Challenges
- Cell line development talent scarcity:Experienced molecular biologists capable of optimizing glycosylation profiles for reduced immunogenicity command premium compensation, constraining R&D expansion.
- Multi-product facility validation complexity:Current good manufacturing practice requirements for campaign segregation between cytotoxic and anti-inflammatory biologics are extending facility qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Inflammatory Cytokines Market |
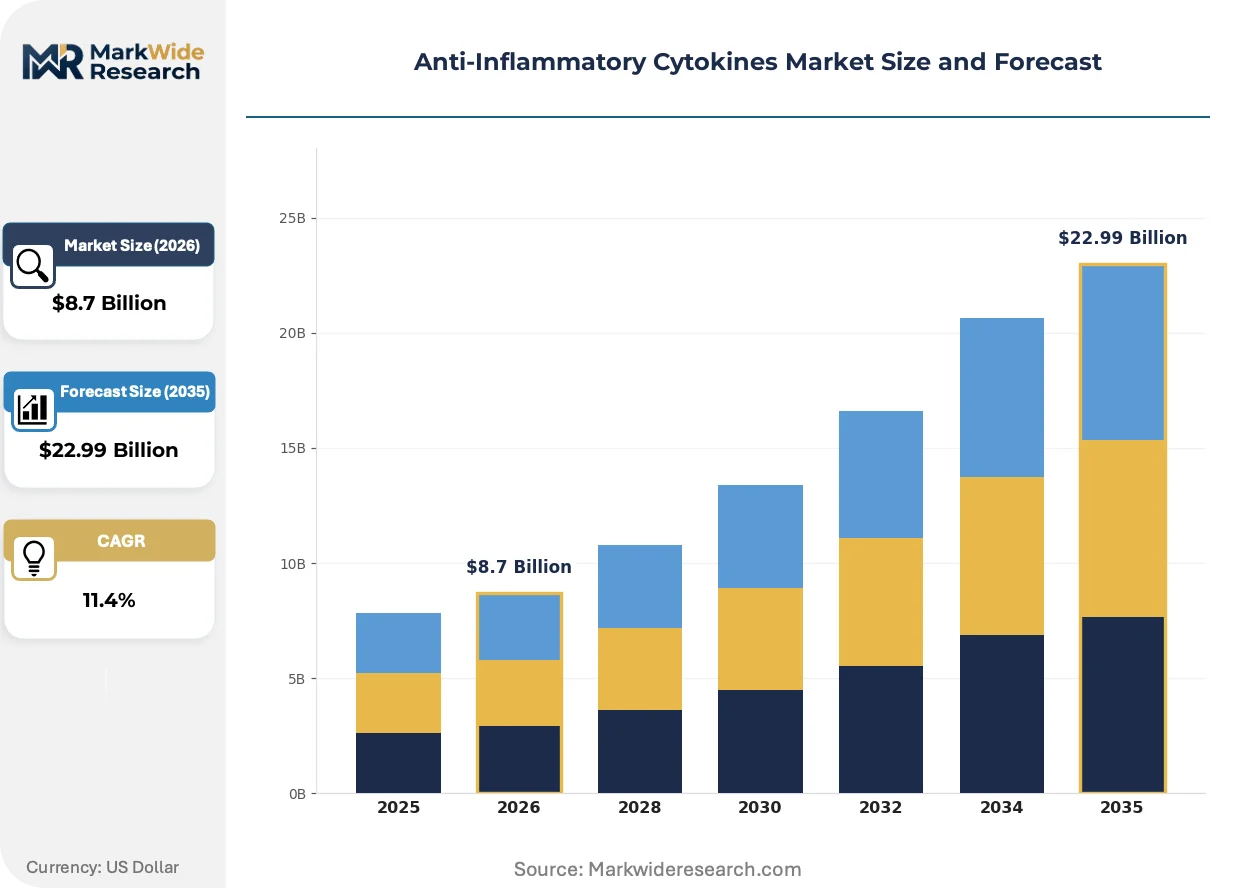
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interleukins, Tumor Necrosis Factors, Transforming Growth Factors, Chemokines Delivery Mode: Injectable, Oral, Intranasal, Topical End User: Pharmaceutical Companies, Biotech Firms, Clinical Labs, Research Institutions Application: Autoimmune Disorders, Inflammatory Diseases, Cancer Therapy, Pain Management |
| Companies Covered | AbbVie, Pfizer, Johnson & Johnson, F. Hoffmann-La Roche, Novartis, AstraZeneca, Merck & Co., GlaxoSmithKline, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Inflammatory Cytokines Market Evolving Landscape
Recombinant protein engineering and delivery platform innovation are compressing development cycles while regulatory agencies adapt pharmacovigilance frameworks to novel cytokine modulation mechanisms.
Microbial secretion systems for non-glycosylated cytokine variants are hybridizing with traditional mammalian platforms, enabling dual-source manufacturing strategies that reduce supply risk. Biopharmaceutical sponsors with existing mammalian infrastructure are piloting E. coli-based production for select interleukin candidates, creating internal competition between expression systems that is compressing cost-of-goods targets across portfolios.
EMA's intensified post-authorization safety studies for immunogenicity signals are reshaping clinical trial design requirements, mandating larger patient exposure databases prior to approval. Sponsors are responding by embedding real-world evidence collection infrastructure into phase IIIb extension protocols, particularly for tumor necrosis factor modulators where long-term neutralizing antibody data carries regulatory weight.
Hospital procurement coalitions are consolidating biologic purchasing decisions through centralized pharmacy and therapeutics committees, displacing individual physician prescribing autonomy. This concentration is compressing formulary access timelines for new cytokine entrants while extending contract duration for incumbent therapies, with the shift most visible in United States integrated delivery networks managing rheumatology and gastroenterology patient populations.
Anti-Inflammatory Cytokines Market Segmentation
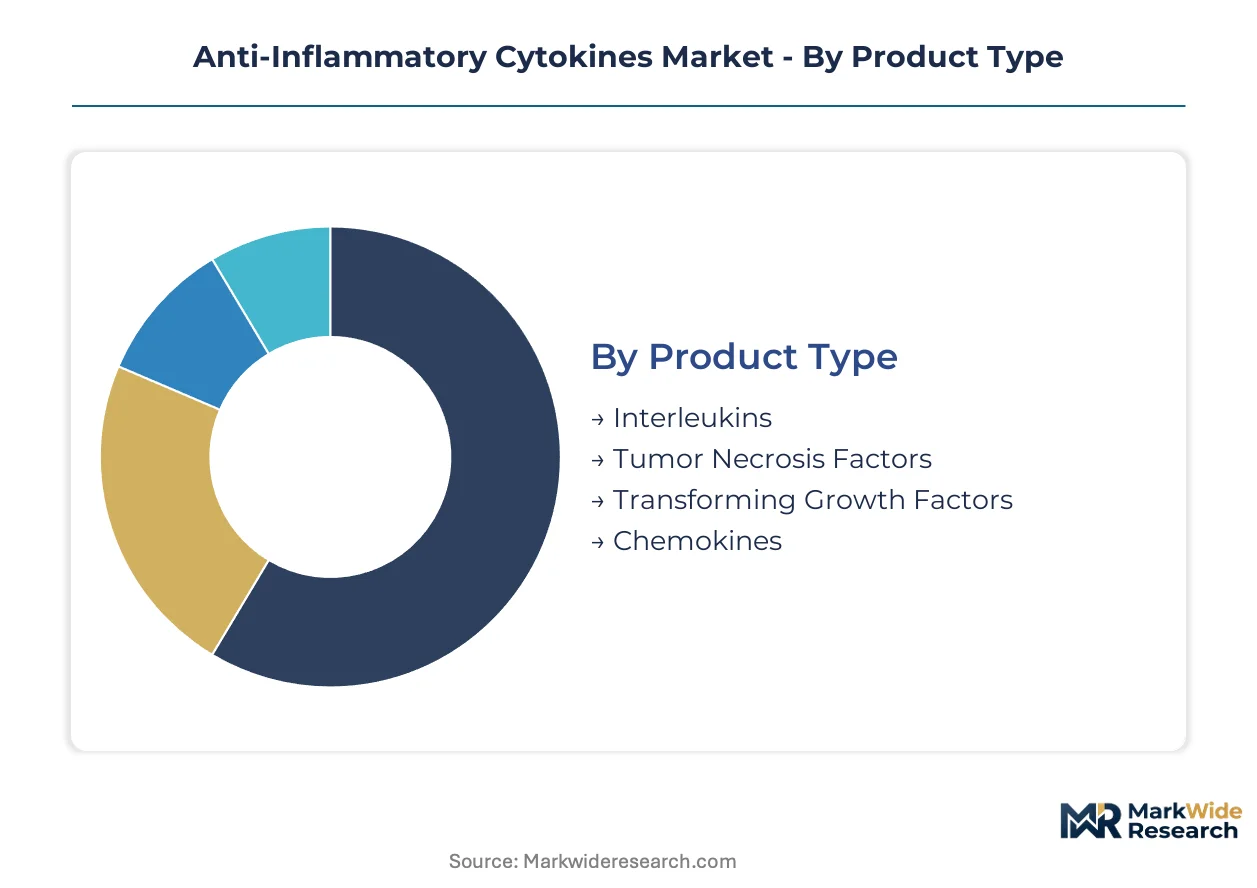
Anti-inflammatory cytokine segmentation reveals distinct value pools tied to molecular specificity, administration route, and therapeutic indication. Each dimension carries different margin profiles, regulatory pathways, and manufacturing requirements that shape competitive positioning.
Product Type:
Cost tier separation across cytokine classes reflects developmental maturity and manufacturing complexity differentials.
- Interleukins:These signaling proteins modulate immune cell differentiation and activation through receptor-mediated JAK-STAT pathways. Demand concentrates in United States rheumatology and gastroenterology practices where IL-6 and IL-17 inhibitors command premium pricing for refractory autoimmune conditions.
- Tumor Necrosis Factors:TNF-alpha suppressors were the first commercially validated cytokine class, establishing proof-of-concept for biologic autoimmune therapy. German hospital formularies and Japanese specialty clinics anchor volume given long-standing reimbursement frameworks and established infusion infrastructure.
- Transforming Growth Factors:TGF-beta modulators address fibrotic indications with distinct mechanistic profiles from interleukin pathways.
- Chemokines:This emerging class targets leukocyte migration patterns with applications in inflammatory skin and respiratory conditions.
Interleukins hold installed capacity. Chemokines are rotating up the share rankings.
Delivery Mode:
Application requirements dictate bioavailability constraints and cold-chain investment intensity across administration routes.
- Injectable:Subcutaneous and intravenous formulations dominate current revenue capture due to protein stability requirements and established reimbursement codes. United States infusion centers and German ambulatory care settings concentrate demand where prior authorization pathways favor documented bioavailability data.
- Oral:Peptide encapsulation technologies are advancing gastrointestinal stability for select cytokine variants. Early clinical programs in inflammatory bowel disease are gaining traction given patient preference for self-administration over clinic-based infusion.
- Intranasal:Mucosal delivery targets respiratory and neuroinflammatory applications with reduced systemic exposure profiles.
- Topical:Localized cytokine application serves dermatological indications with minimized immunogenicity risk.
Injectable maintains formulary dominance. Oral is climbing the fastest toward addressable patient expansion.
End User:
Customer type determines procurement scale, technical specification requirements, and relationship dynamics with manufacturing partners.
- Pharmaceutical Companies:Large sponsors drive volume through integrated development and commercialization infrastructure. Multi-site biologics manufacturing and established specialty pharmacy networks in the United States and Japan support global distribution of approved cytokine therapies.
- Biotech Firms:Emerging developers concentrate on novel interleukin targets and bispecific formats, relying on contract manufacturing organizations for mammalian cell culture capacity.
- Clinical Labs:Diagnostic and biomarker applications require reference-grade cytokine standards for assay calibration.
- Research Institutions:Academic centers supply early-stage discovery programs with exploratory cytokine variants for mechanistic studies.
Pharmaceutical companies hold installed capacity. Biotech firms are rotating up the share rankings.
Application:
Volume distribution across therapeutic areas reflects unmet need severity, competitive intensity, and reimbursement durability.
- Autoimmune Disorders:Rheumatoid arthritis, psoriasis, and inflammatory bowel disease represent the established revenue base. United States Medicare Part B and Japanese universal coverage frameworks sustain pricing for TNF and IL-17 inhibitors in these chronic conditions.
- Cancer Therapy:Checkpoint combination protocols are expanding cytokine utility beyond autoimmune origins. Oncology infusion networks in Germany and academic medical centers in the United States are piloting IL-2 variants and engineered cytokine fusion proteins.
- Inflammatory Diseases:Non-autoimmune inflammatory conditions including cardiovascular and metabolic syndromes represent emerging addressable populations.
- Pain Management:Neuropathic and inflammatory pain pathways are targets for localized cytokine modulation with reduced opioid dependency profiles.
Autoimmune disorders hold installed capacity. Cancer therapy is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cold-chain distribution networks for injectable biologics underpin commercial access across major pharmaceutical markets. These logistics assets determine which geographies sustain premium pricing for temperature-sensitive cytokine therapies.
United States
Medicare Part B reimbursement codes and commercial insurance prior authorization frameworks drive demand for TNF and IL-17 inhibitors in rheumatology practices. FDA's accelerated approval pathway compresses Phase III timelines for biologics addressing unmet autoimmune needs. The Boston-Cambridge biotech corridor anchors mammalian cell culture capacity expansion among contract development and manufacturing organizations.
Germany
Hospital outpatient departments are adding dedicated biologic administration suites, expanding addressable patient populations for injectable therapies. EMA centralized marketing authorization procedures govern approval standards, with intensified post-market pharmacovigilance for immunogenicity signals. The Rhine-Main region concentrates infusion center infrastructure serving both domestic demand and cross-border Austrian and Swiss patients.
Japan
PMDA's Sakigake designation offers priority review for cytokine therapies targeting rheumatoid arthritis in a market with 65-plus demographic expansion. Universal coverage frameworks sustain pricing for established interleukin inhibitors. The Kanto region around Tokyo hosts specialized cold-chain distribution hubs supporting biologic delivery to hospital pharmacies nationwide.
United Kingdom
NHS England's specialised commissioning frameworks determine formulary access for high-cost biologics in autoimmune indications. The Medicines and Healthcare products Regulatory Agency enforces batch consistency standards aligned with EU withdrawal agreement provisions. The Golden Triangle research cluster between London, Oxford, and Cambridge supplies early-stage discovery programs with exploratory cytokine variants.
Switzerland
Swissmedic marketing authorization procedures attract sponsors seeking concurrent EMA-aligned regulatory pathways for novel interleukin targets. Reimbursement durability under mandatory health insurance sustains premium positioning for biologic therapies. The Basel biopharmaceutical manufacturing corridor anchors multi-site production of recombinant protein therapies serving European export markets.
Anti-Inflammatory Cytokines Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in mammalian cell culture and recombinant protein engineering. The competitive structure consolidates around large sponsors with locked-in manufacturing slots, while emerging developers face supply-side bottlenecks in contract development capacity. Three archetypes dominate: integrated biopharmaceutical conglomerates with global distribution infrastructure, mid-cap specialists focused on interleukin-modulating candidates, and contract manufacturing organizations expanding single-use bioreactor adoption. Capacity expansion and strategic partnerships represent the dominant competitive moves, with sponsors securing multi-year manufacturing agreements to defend production access.
Among integrated biopharmaceutical conglomerates, AbbVie, Pfizer, and Amgen occupy positions exemplifying distinct competitive vectors. AbbVie leverages established immunology franchise infrastructure for refrigerated logistics across North American infusion centers. Pfizer anchors global manufacturing scale through multi-site biologics production networks. Amgen sits within the recombinant protein engineering leadership tier for interleukin-modulating candidates. These three entities represent how originator sponsors are responding to biosimilar substitution pressure through formulation innovation and real-world evidence generation.
| Leading Market Players |
|---|
| AbbVie |
| Pfizer |
| Johnson & Johnson |
| F. Hoffmann-La Roche |
| Novartis |
| AstraZeneca |
| Merck & Co. |
| GlaxoSmithKline |
| Amgen |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Chinese hamster ovary cell repositories determines both margin compression trajectories and cold-chain investment intensity across anti-inflammatory cytokine manufacturing tiers. Manufacturers facing biosimilar substitution pressure in established interleukin markets must absorb refrigerated logistics costs while defending premium positioning through formulation differentiation.
Pricing Analysis
Volume-discount tiering separates originator biologics from authorized biosimilars and emerging follow-on candidates. Pricing stratifies across premium, standard, and economy tiers based on glycosylation complexity and immunogenicity profile certification. Cost compression in the biosimilar tier is intensifying because EMA interchangeability guidelines and US state substitution laws accelerate physician switching. Hospital procurement coalitions exhibit highest price sensitivity, while specialty infusion centers maintain lowest sensitivity due to patient lock-in and reimbursement durability.
Supply Chain Analysis
Contract-manufacturing concentration rests with Lonza, Boehringer Ingelheim, and Samsung Biologics for mammalian cell culture capacity. Production gravity centers on Switzerland, Germany, and South Korea for multi-product biologics facilities. Raw material dependencies include cell culture media, single-use bioreactor components, and purified recombinant protein feedstocks. Single-source vulnerability in master cell bank repositories creates supply chain risk. Distribution runs through specialized cold-chain logistics providers serving hospital pharmacies and infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-inflammatory cytokines market sits at an early-cycle expansion story justified by checkpoint combination protocols in oncology that are opening novel therapeutic applications beyond autoimmune origins.
For Market Incumbents: Harden manufacturing slot control through multi-year contract manufacturing organization agreements that lock in mammalian cell culture capacity. Deepen backward integration into recombinant protein engineering capabilities to reduce cost-of-goods exposure. Defend against biosimilar substitution by embedding real-world evidence collection infrastructure into post-marketing surveillance protocols.
For New Entrants and Emerging Players: Japan's aging autoimmune patient pool offers the most penetrable geography given PMDA Sakigake designation priority review and universal coverage frameworks. Oral formulation development for inflammatory bowel disease represents the most accessible white-space segment given patient preference for self-administration. Pursue academic medical center partnerships as the primary go-to-market angle for early clinical validation.
For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors mid-cap specialists with locked-in manufacturing slots and novel interleukin targets. Long-term viability over the next decade hinges on successful navigation of biosimilar cliffs and expansion into oncology combination protocols. Watch EMA centralized pediatric investigation plan mandates as the signal indicating regulatory tailwind acceleration for juvenile idiopathic arthritis indications.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Single-use bioreactor adoption at Lonza and Samsung Biologics raises effective throughput for recombinant cytokine campaigns. |
| Regulatory Approval Pathway | FDA accelerated approval compresses Phase III timelines for interleukin-modulating candidates addressing unmet autoimmune needs. |
| Licensing Agreement | Cross-border partnerships with Japanese sponsors leverage PMDA Sakigake priority review for rheumatoid arthritis indications. |
| Pipeline Diversification | Expansion into checkpoint combination protocols for cancer therapy opens fastest-growing application segment. |
| Clinical Trial Advancement | Embedding real-world evidence collection into phase IIIb protocols satisfies EMA intensified post-authorization safety study requirements. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings for this analysis. Conversations with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers inform competitive positioning assessments. Secondary validation draws from FDA biologics license application filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov protocols, and formulary database audits. Bottom-up patient population modeling and top-down revenue triangulation across the analysis window ensure segmentation consistency.
Calibration against historical approval timelines and commercial uptake curves shapes the projection framework. The model segments by product type, delivery mode, therapeutic application, and regional regulatory cluster across the modeling period. CAGRs derive from patient population epidemiology, pricing trajectory assumptions, and manufacturing capacity expansion schedules. Forecast inputs include biosimilar substitution rates and cold-chain logistics cost escalation indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by contract manufacturing organizations to vertically integrate into sponsor roles would shift outcomes. Regulatory acceleration pathways, biosimilar interchangeability rulings, and cell line development talent scarcity represent primary revision risks. Quarterly review of FDA approval velocity, EMA safety study mandates, and manufacturing slot availability is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Chemotherapy Drugs Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
Spain Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
Global Tick-Borne Encephalitis Inactivated Vaccine Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Tamoxifen Market
Biopharmaceuticals
Iran Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Rheumatoid Arthritis Drugs Market
Biopharmaceuticals
Proteinuria Therapeutics Market