
 Materials Testing Equipment Market | 2026-2036
Materials Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Materials Testing Equipment Market Insights
Software-defined data acquisition and cloud-connected analytics is shifting how materials testing equipment creates value beyond hardware sales. Illinois Tool Works Inc. leverages its service network to embed predictive maintenance contracts across industrial accounts. ZwickRoell anchors its European position through deep calibration and certification services tied to regulatory compliance. Shimadzu Corporation extends its reach in Asia-Pacific via localized software interfaces and remote diagnostic capabilities.
Materials testing equipment comprises instruments that apply controlled mechanical, thermal, or electromagnetic forces to specimens to determine properties such as tensile strength, hardness, fatigue life, and impact resistance, typically operating across load ranges from newtons to meganewtons with displacement resolutions down to micrometers. These systems serve critical functions in quality assurance, failure analysis, and materials qualification for safety-critical components. Tensile testers and hardness testers occupy the largest installed base due to universal application across metals, polymers, and composites. Digital technology is displacing legacy mechanical and hydraulic control architectures, enabling real-time data capture and automated reporting that reduces operator variability. Ultrasonic testing segments gain traction in aerospace and electronics end-use sectors where non-destructive evaluation preserves expensive finished components.
ISO 17025 laboratory accreditation, ASTM International test methods, and FDA device validation requirements shape equipment specifications and create replacement demand as standards revise. OSHA workplace safety rules and FAA airworthiness directives in the United States, alongside CE marking and EU Machinery Directive compliance in Europe, mandate documented traceability for test results used in product certification. Stakeholders must monitor evolving harmonization between regional standards bodies and assess whether digital twin integration becomes a prerequisite for next-generation procurement specifications.
Market Dynamics
Digital twin integration is compressing equipment refresh cycles as aerospace and automotive manufacturers demand real-time simulation capabilities alongside physical testing infrastructure. This convergence of virtual and physical validation is redrawing competitive boundaries between traditional hardware suppliers and software analytics platforms.
Growth Catalysts
- ISO 17025 Laboratory Accreditation Mandates:European and North American testing facilities face mandatory equipment upgrades to maintain certification validity, driving replacement demand for automated data acquisition systems.
- Composite Material Proliferation:Wind turbine blade manufacturers and electric vehicle battery housing producers require specialized fatigue and impact testing protocols unavailable on legacy universal testing machines.
- China's Industrial Cluster Concentration:Heavy investment in domestic aerospace supply chains around Xi'an and Chengdu generates localized demand for high-capacity structural testing systems.
Market Restraints
- Sensor Supply Concentration:Precision load cell and strain gauge manufacturing concentrates in German and Japanese specialist suppliers, creating vulnerability to regional supply disruptions.
- High-Voltage Safety Compliance Costs:Electromechanical testing systems above 100kN capacity require extensive CE marking and OSHA electrical safety certification, extending sales cycles.
- Non-Destructive Testing Substitution:Industrial computed tomography and phased-array ultrasonic systems capture applications previously served by destructive mechanical testers in electronics quality assurance.
Strategic Opportunities
- India's PLI Scheme for Specialty Steel:Domestic production incentives for high-grade automotive and defense alloys create demand for metallurgical testing infrastructure in Pune and Jamshedpur industrial corridors.
- Cloud-Native Data Analytics Bundling:Equipment vendors can capture recurring revenue by embedding AI-driven failure prediction algorithms within testing software subscriptions.
- Battery Supply Chain Localization:European cell manufacturing investments under EU Green Deal funding require thermal runaway and crush testing capabilities for gigafactory qualification labs.
Industry Challenges
- Mechatronics Engineering Talent Scarcity:Integration of servo-electric actuators with real-time control systems demands hybrid mechanical-electrical-software expertise rarely available in single hires.
- Multi-Site Calibration Traceability:Corporate laboratory networks struggle to maintain consistent measurement uncertainty documentation across dispersed facilities under divergent national metrology institute standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Materials Testing Equipment Market |
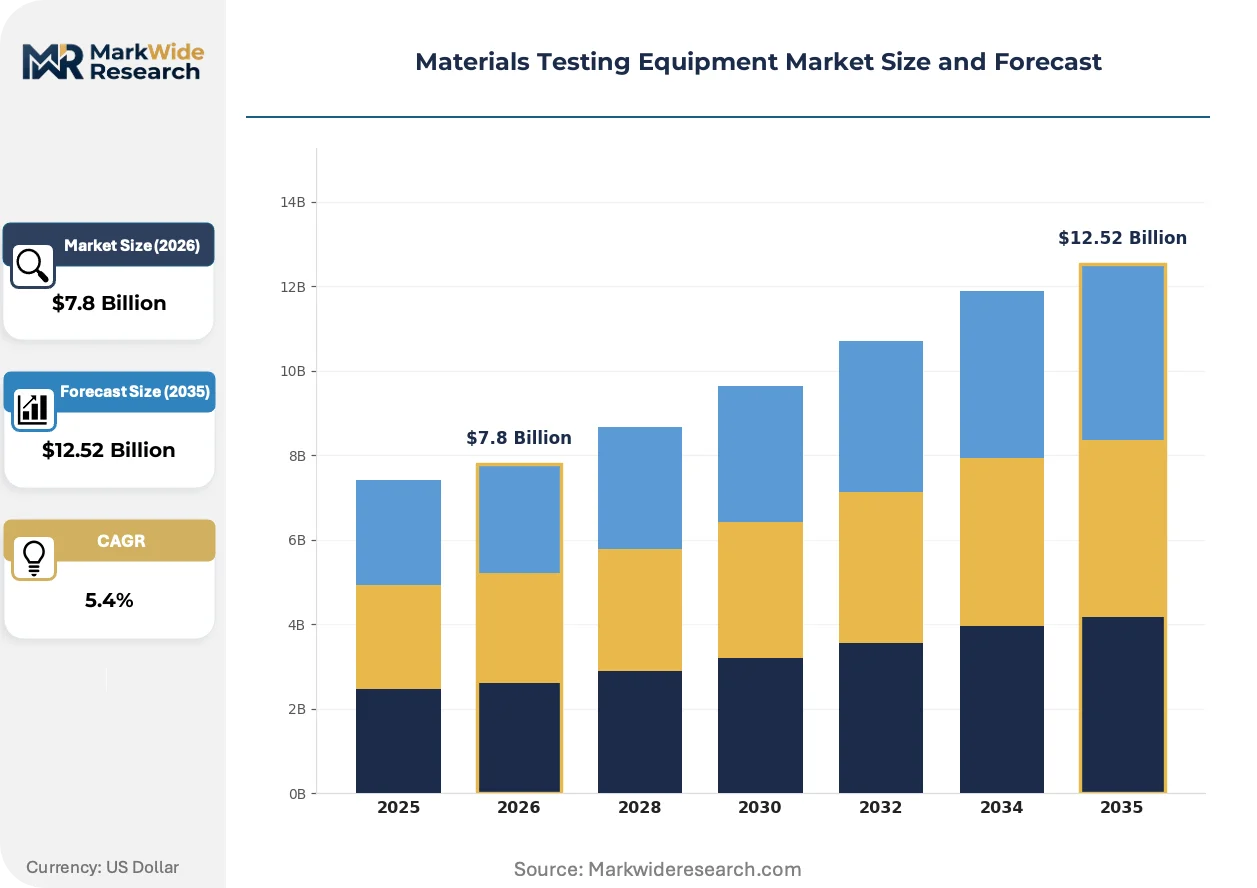
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tensile Testers, Hardness Testers, Impact Testers, Fatigue Testers Technology: Mechanical, Hydraulic, Digital, Ultrasonic End User: Aerospace, Automotive, Construction, Electronics Application: Quality Control, Research & Development, Product Testing, Compliance |
| Companies Covered | Illinois Tool Works Inc., ZwickRoell, Shimadzu Corporation, AMETEK Inc., Tinius Olsen, MTS Systems Corporation, Mitutoyo Corporation, Applied Test Systems, Bureau Veritas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Materials Testing Equipment Market Trends and Innovations
Software-defined architectures are displacing fixed-function hardware as the primary value layer in materials testing, enabling remote diagnostics and predictive maintenance that alter equipment lifecycle economics.
Electromechanical actuator technology is modularizing traditional hydraulic universal testing machine architectures. Aerospace tier-one suppliers in Germany and the United States now specify plug-and-force-channel configurations that allow rapid reconfiguration between tensile, compression, and torsion modes without hydraulic infrastructure. This architecture is modularizing capital deployment patterns, allowing manufacturers to scale capacity incrementally rather than committing to monolithic system purchases.
EU Machinery Directive 2006/42/EC amendments emphasizing functional safety for autonomous test sequences are forcing software architecture redesigns. Equipment vendors must now integrate safety-rated programmable logic controllers with deterministic real-time operating systems to achieve CE marking compliance. High-throughput automotive materials laboratories in Stuttgart and Wolfsburg face the steepest compliance timelines as they retest legacy protocols under revised risk assessment frameworks.
Buyers are unbundling hardware procurement from calibration and certification services, treating metrology support as a separately sourced subscription. Tier-two automotive suppliers in Michigan and Ontario now contract independent ISO 17025-accredited laboratories for annual verification rather than accepting OEM service agreements. This pattern is most visible in North American industrial belt regions where specialized third-party metrology providers have established dense service networks.
Materials Testing Equipment Market Segmentation
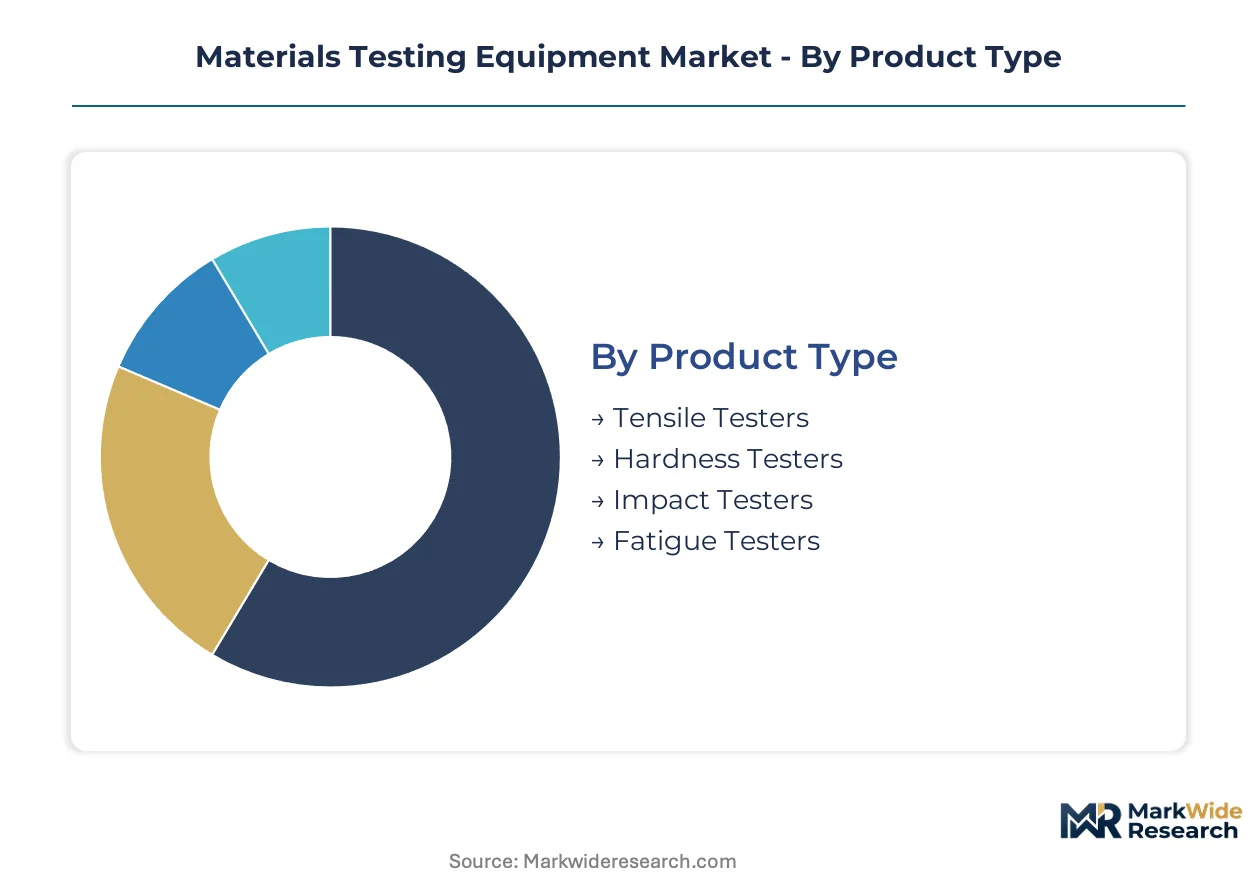
Segmentation in materials testing equipment reveals how capital deployment priorities diverge across testing modalities and compliance frameworks. Product architecture, control technology, and end-use certification requirements create distinct competitive arenas with varying margin profiles and replacement cycles.
Product Type:
Supply concentration among precision actuator manufacturers in Germany and Japan shapes equipment availability and lead times across all product categories.
- Tensile Testers:Universal electromechanical systems apply controlled axial loads from newtons to meganewtons to characterize yield strength, ultimate tensile strength, and elongation properties. Automotive stamping plants in Michigan and Bavaria drive demand for high-throughput configurations with automated specimen handling. CE marking requirements under EU Machinery Directive amendments are extending procurement timelines for European installations.
- Hardness Testers:Indentation-based systems measure resistance to localized plastic deformation through Rockwell, Brinell, Vickers, or Knoop methodologies. Heat treatment facilities in China's Shandong and Hebei provinces require portable units for on-site metallurgical verification. BIS certification mandates for domestic steel production are accelerating replacement of legacy mechanical models.
- Impact Testers:Pendulum and drop-weight systems quantify energy absorption during fracture at controlled temperatures. Wind turbine blade manufacturers specify these for composite laminate qualification.
- Fatigue Testers:Servo-hydraulic and electrodynamic systems apply cyclic loading to predict component life under repeated stress. FAA airworthiness directives for commercial aviation drive adoption of multi-axis configurations.
Tensile testers absorb the bulk of installed capacity; fatigue testers are expanding most quickly.
Technology:
Cost tier stratification separates premium digital architectures from legacy mechanical systems, with mid-market hydraulic configurations facing displacement pressure.
- Mechanical:Screw-driven and lever-based load application with analog dial indicators or basic digital displays. Small machine shops in India's Punjab and Gujarat retain these for low-volume quality checks. Capital constraints and limited technical support infrastructure sustain residual demand despite measurement uncertainty limitations.
- Hydraulic:Oil-pressure actuation delivering high-force capacity for structural and heavy-section testing. Construction materials laboratories in Brazil and Mexico maintain extensive installed bases. OSHA electrical safety certification costs for replacement systems are extending equipment lifecycles beyond optimal calibration intervals.
- Digital:Software-defined control architectures with real-time data acquisition, automated protocol execution, and cloud connectivity. Aerospace tier-one suppliers in Germany and the United States specify these for digital twin integration.
- Ultrasonic:Phased-array and time-of-flight diffraction systems for non-destructive thickness measurement and flaw detection. Electronics manufacturing in South Korea and Taiwan adopts these for wafer and substrate inspection without specimen destruction.
Hydraulic systems retain the largest installed base; digital architectures are gaining share fastest.
End User:
Application intensity varies dramatically, with safety-critical sectors demanding continuous calibration traceability while commodity producers prioritize throughput economics.
- Aerospace:Airframe and engine manufacturers require multi-axis fatigue, creep, and fracture mechanics testing under FAA and EASA oversight. Wichita and Toulouse industrial clusters specify systems with automated reporting for AS9100 compliance.
- Automotive:OEMs and tier suppliers test sheet metal, polymers, and composites for crashworthiness and durability. Stuttgart and Wolfsburg laboratories face compressed compliance timelines under revised EU Machinery Directive risk assessments.
- Construction:Cement, steel, and aggregate producers verify compressive strength and structural integrity. China's infrastructure investment around Chengdu and Xi'an generates localized demand for high-capacity compression frames.
- Electronics:Semiconductor and PCB manufacturers require micro-hardness, wire bond pull, and solder joint reliability testing. Thermal cycling and mechanical shock protocols support qualification for 5G and automotive electronics applications.
Automotive absorbs the greatest equipment volume; aerospace commands the highest specification premiums.
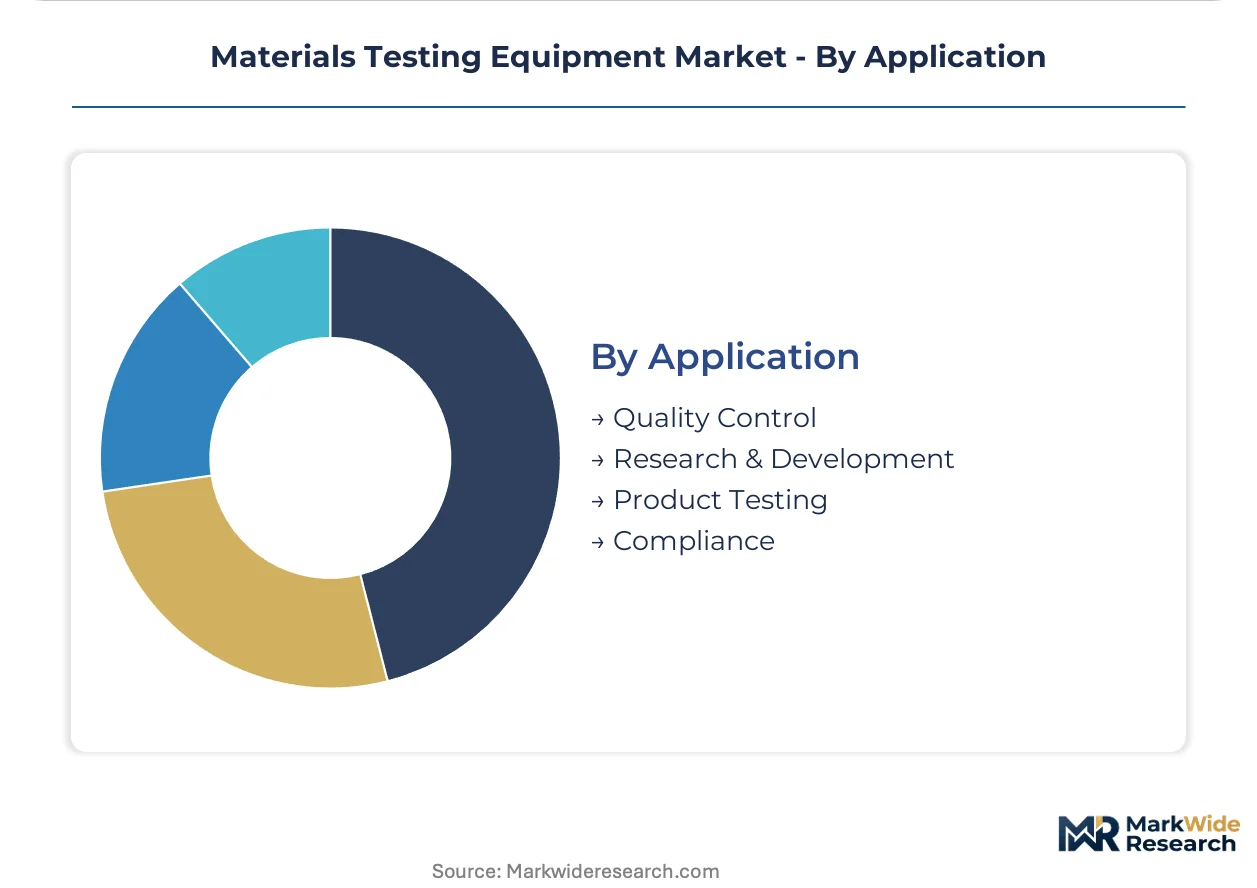
Application:
Customer type segmentation separates production-line quality control from centralized R&D facilities, with compliance testing creating distinct procurement authority structures.
- Quality Control:In-line and near-line testing integrated with manufacturing execution systems for real-time disposition decisions. High-volume automotive stamping operations in Ontario and Alabama specify automated tensile systems with sub-minute cycle times.
- Research & Development:Exploratory materials characterization supporting alloy development and process optimization. National laboratories and university centers in the United States, Germany, and Japan require configurable platforms accommodating novel specimen geometries.
- Product Testing:Validation of finished components against design specifications prior to release. Medical device manufacturers face FDA validation requirements extending equipment qualification timelines.
- Compliance:Third-party certification testing under ISO 17025 accreditation for market access documentation. Independent laboratories in the United Kingdom and Netherlands unbundle hardware procurement from calibration services, treating metrology support as separately sourced subscriptions.
Quality control represents the largest installed base; compliance applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European demand for materials testing equipment, with automotive OEMs and tier suppliers driving specifications for multi-axis fatigue and digital twin-integrated systems across safety-critical validation workflows.
United States
FAA airworthiness directives and OSHA electrical safety rules mandate documented traceability for aerospace and heavy-industry testing applications. Wichita's airframe manufacturing cluster specifies automated reporting systems for AS9100 compliance, while Michigan automotive stamping plants demand high-throughput tensile configurations with sub-minute cycle times.
Germany
EU Machinery Directive amendments emphasizing functional safety for autonomous test sequences force software architecture redesigns. Stuttgart and Wolfsburg laboratories face compressed compliance timelines under revised risk assessment frameworks, with Bavarian precision actuator manufacturers supplying servo-electric systems for modular universal testing machines.
China
BIS certification mandates for domestic steel production accelerate replacement of legacy mechanical hardness testers. Heavy investment in aerospace supply chains around Xi'an and Chengdu generates localized demand for high-capacity structural testing systems, while Shandong and Hebei heat treatment facilities require portable metallurgical verification units.
Japan
METI industrial standards and JIS certification requirements shape equipment procurement for automotive and electronics manufacturers. Nagoya-area automotive suppliers and Osaka-region semiconductor producers drive adoption of micro-hardness and wire bond pull testing systems for 5G and automotive electronics qualification protocols.
India
PLI scheme incentives for specialty steel production create demand for metallurgical testing infrastructure in Pune and Jamshedpur industrial corridors. Domestic automotive and defense alloy qualification requirements push laboratories toward automated data acquisition systems that satisfy evolving ISO 17025 accreditation standards.
Materials Testing Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across electromechanical and digital control architectures. The vendor base stratifies between integrated testing system manufacturers, precision component specialists, and software analytics platforms. Three archetypes dominate: diversified industrial conglomerates with embedded service networks, precision engineering specialists with deep calibration capabilities, and instrumentation platforms with cloud-native data architectures. Consolidation pressure intensifies as digital twin integration requirements favor vendors with simultaneous hardware and simulation software competence.
Among diversified industrial conglomerates, Illinois Tool Works Inc. and AMETEK Inc. occupy positions defined by service network density and predictive maintenance contract penetration. ZwickRoell exemplifies the precision engineering specialist archetype with European calibration and certification capabilities. Shimadzu Corporation anchors the Asia-Pacific instrumentation tier through localized software interfaces. MTS Systems Corporation and Tinius Olsen sit within the structural testing systems segment, representing scale-driven and heritage-brand positioning respectively.
| Leading Market Players |
|---|
| Illinois Tool Works Inc. |
| ZwickRoell |
| Shimadzu Corporation |
| AMETEK Inc. |
| Tinius Olsen |
| MTS Systems Corporation |
| Mitutoyo Corporation |
| Applied Test Systems |
| Bureau Veritas |
| Others |
Pricing and Supply Chain Analysis
Tier-one aerospace suppliers in Germany and the United States anchor demand for high-specification fatigue and digital twin-integrated testing systems, locking in value-based pricing tied to equipment uptime guarantees and predictive maintenance outcomes rather than capital expenditure alone.
Pricing Analysis
Outcome-based pricing tied to laboratory throughput and certification compliance anchors premium tiers across the market. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-compliant aerospace configurations from automotive quality-control workhorses and mechanical legacy units for small machine shops. Cost compression in standard-tier electromechanical systems is intensifying because Chinese actuator manufacturers are scaling servo-electric production for domestic wind turbine and battery supply chains. Small machine shops in India's Punjab and Gujarat exhibit the highest price sensitivity, while FAA-regulated aerospace laboratories in Wichita and Toulouse accept substantial premiums for documented traceability and automated reporting capabilities.
Supply Chain Analysis
Mechatronics engineering talent scarcity in Bavaria and Nagoya constrains output expansion for precision actuator and load cell manufacturers serving high-capacity structural testing applications. Component manufacturing concentrates in Germany and Japan for precision load cells and strain gauges, with servo-electric drive assemblies sourcing from China's Yangtze River Delta industrial corridor. Raw material dependencies span rare-earth magnets for electrodynamic shakers, high-grade aluminum for load frames, and specialized hydraulic fluids for legacy structural testers. Single-source vulnerability in German precision sensor suppliers exposes lead times to regional energy cost fluctuations. Distribution runs through OEM-direct sales for aerospace tier-ones, regional distributor networks for automotive stampers, and third-party metrology providers for compliance testing laboratories in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision actuator and calibration service capacity constraints in Germany and Japan prop pricing power for incumbent vendors with captive manufacturing assets, creating durable margin structures resistant to commoditization pressure from Asian electromechanical suppliers.
For Market Incumbents: Cement dominance in aerospace certification workflows by embedding predictive maintenance contracts that lock out independent metrology providers from annual verification cycles. Expand servo-electric actuator production in Bavaria to capture modular universal testing machine demand from Stuttgart and Wolfsburg automotive laboratories facing compressed EU Machinery Directive compliance timelines. Counter non-destructive testing substitution threat by integrating phased-array ultrasonic modules into software-defined control architectures. For New Entrants and Emerging Players: Begin with cloud-native data analytics bundling for mid-market automotive tier-two suppliers in Michigan and Ontario that have already unbundled hardware procurement from calibration services. Target India's PLI scheme-funded specialty steel laboratories in Pune and Jamshedpur with automated data acquisition systems priced below ISO 17025-accredited European imports. Pursue battery supply chain localization in Europe by offering thermal runaway and crush testing capabilities for gigafactory qualification labs under EU Green Deal funding. For Investors and Strategic Acquirers: The window for entry favors precision engineering specialists with deep calibration capabilities and European regulatory relationships over asset-light software platforms lacking hardware integration competence. Long-term viability rests on simultaneous competence in servo-electric actuators, deterministic real-time control systems, and simulation software for digital twin integration. Monitor harmonization progress between ISO and ASTM standards bodies as the signal indicating whether next-generation procurement specifications will mandate virtual-physical validation convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Actuator Manufacturing | Captures margin from German and Japanese load cell suppliers while securing supply continuity for high-capacity structural testers. |
| Cloud-Native Data Analytics Subscription Bundling | Transforms one-time equipment sales into recurring revenue from automotive and aerospace laboratories seeking AI-driven failure prediction. |
| CE Marking and ISO 17025 Certification Investment | Unlocks procurement eligibility for Stuttgart and Wolfsburg laboratories facing compressed compliance timelines under EU Machinery Directive amendments. |
| Joint Venture with Battery Cell Manufacturers | Secures anchor demand for thermal runaway and crush testing systems in European gigafactory qualification labs under EU Green Deal funding. |
| Geographic Expansion into India's PLI Corridors | Captures metallurgical testing infrastructure demand from specialty steel producers in Pune and Jamshedpur seeking automated data acquisition. |
Research Methodology
Independent corroboration across equipment procurement directors at aerospace tier-one suppliers, laboratory managers at ISO 17025-accredited testing facilities, and aftermarket service heads at industrial conglomerates underwrites the qualitative findings. Primary interviews with maintenance directors at automotive stamping plants, plant engineers at construction materials laboratories, and OEM procurement teams at wind turbine blade manufacturers combined with secondary validation from FAA airworthiness directives, EU Machinery Directive amendments, ASTM International test method revisions, and SEC filings from diversified industrial equipment manufacturers. Bottom-up and top-down triangulation cross-checked installed base estimates against replacement cycle assumptions.
Comparable-period anchoring to historical equipment refresh cycles under ISO 17025 and ASTM certification mandates structured the forecast window across the projection horizon. Segmentation dimensions modeled include product architecture, control technology, end-use certification requirements, and geographic regulatory enforcement intensity. CAGRs derived from weighted average of equipment replacement demand, greenfield capacity expansion, and technology upgrade cycles. Industry-specific inputs incorporated digital twin integration adoption curves, composite material proliferation rates in wind turbine and electric vehicle applications, and PLI scheme implementation timelines for specialty steel production.
Underlying measurement precision varies by segment; aerospace and automotive safety-critical applications carry tighter precision than commodity construction materials testing. Forecasts reflect assumptions regarding regulatory harmonization, supply chain continuity for precision sensors, and mechatronics engineering talent availability. Material deviation in FAA airworthiness directive timelines, EU Machinery Directive enforcement intensity, or German-Japanese actuator supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Hydrometer Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Global Lab Automation in Analytical Chemistry Market
Testing Equipment
Durometers Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Paper Tester Market
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Water Penetration Tester Market
Testing Equipment
United States Material Testing Market
Testing Equipment
Global Oxidative Stress Assay Market
Testing Equipment
Global Trace Metal Analysis Market