
 Chemical Reaction Monitoring Equipment Market | 2026-2036
Chemical Reaction Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Reaction Monitoring Equipment Market Insights
Pharmaceutical-grade resolution is collapsing the gap between at-line and laboratory reference methods. Thermo Fisher Scientific leverages its mass spectrometry portfolio to dominate bioprocess monitoring contracts with large-molecule drug manufacturers. Agilent Technologies anchors its position through deep R&D intensity in UV-Vis diode array platforms for continuous flow chemistry. Mettler-Toledo International specializes in reaction calorimetry systems that integrate directly with process control architectures.
Chemical reaction monitoring equipment encompasses analytical instrumentation designed to track reaction kinetics, intermediate formation, and endpoint determination in real time or near-real time, typically operating across temperature ranges from cryogenic conditions to 300°C and pressure environments up to 100 bar. These systems serve primarily to ensure batch consistency, prevent runaway reactions, and validate critical process parameters in regulated manufacturing environments. Spectrophotometers lead installed base value due to their versatility across organic and inorganic reaction chemistries, while mass spectrometry represents the fastest-expanding technology segment as pharmaceutical adopters seek molecular specificity for complex synthesis pathways. Research labs occupy the most price-sensitive end-user tier, whereas chemical manufacturers command the largest absolute spending pool for integrated process analytical technology suites.
FDA process analytical technology guidance and EMA good manufacturing practice annexes jointly shape equipment validation requirements and data integrity standards for vendors seeking commercial pharmaceutical contracts. REACH substance evaluation protocols in Europe and EPA toxic release inventory rules in the United States drive chemical producers toward continuous monitoring architectures that reduce sampling lag and environmental exposure risk. Stakeholders must weigh capital deployment timing against evolving pharmacopoeial acceptance criteria for spectroscopic methods as primary release tests.
Market Dynamics
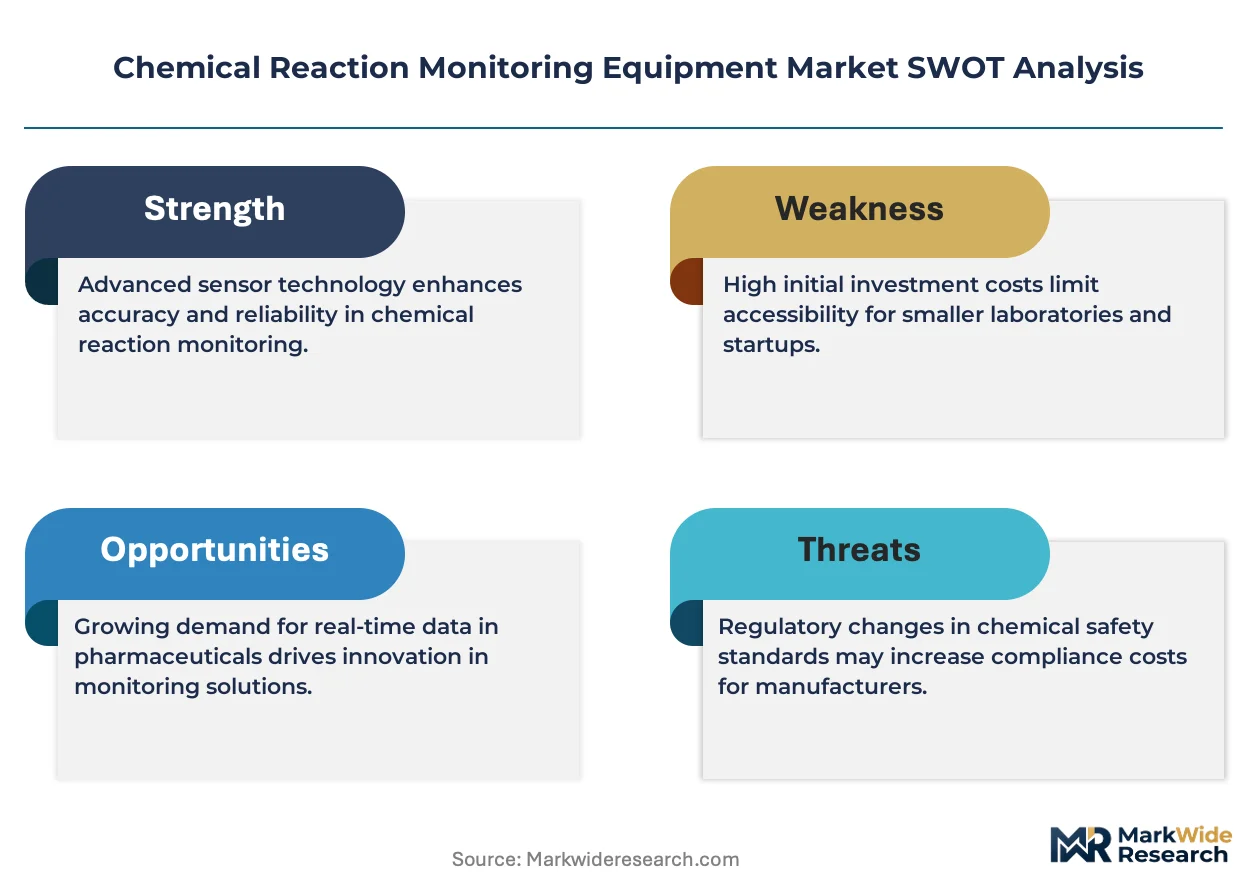
Pharmaceutical process analytical technology mandates are compressing validation timelines and forcing equipment vendors to pre-integrate data integrity architectures before deployment. This regulatory pressure is restructuring how manufacturers qualify spectroscopic methods as primary release tests.
Growth Catalysts
- EMA process analytical technology annexes:European pharmaceutical manufacturers must deploy continuous monitoring systems to satisfy good manufacturing practice requirements for real-time release testing.
- Large-molecule drug synthesis:Biologics manufacturers require mass spectrometry specificity for complex glycosylation monitoring during cell culture and purification stages.
- German chemical clusters:REACH substance evaluation protocols in the Rhine-Ruhr and Ludwigshafen regions mandate real-time impurity detection systems with sub-ppm resolution.
Market Restraints
- High-purity optical fiber costs:Spectrophotometer probe assemblies depend on specialty silica supply concentrated in Japanese and German foundries, creating input cost volatility.
- Qualified technician scarcity:NMR probe maintenance and calibration require specialized magnetic resonance physics expertise that chemical manufacturers struggle to retain.
- Legacy distributed control system incompatibility:1990s-era chemical plant automation architectures lack Ethernet-APL physical layers needed for modern spectroscopic data streaming.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO quality mandate enforcement is creating first-time demand for at-line UV-Vis systems in Ahmedabad and Hyderabad generic drug clusters.
- Raman-NIR sensor fusion:Combined vibrational spectroscopy platforms enable simultaneous polymorph identification and moisture monitoring in crystallization processes.
- Equipment-as-service contracting:Reaction calorimetry vendors are piloting outcome-based pricing tied to batch yield improvement rather than capital purchase.
Industry Challenges
- 21 CFR Part 11 software validation:Pharmaceutical equipment buyers require six-to-twelve-month qualification timelines for electronic records and signatures compliance.
- Multi-vendor data architecture integration:Chemical manufacturers struggle to normalize spectroscopic output formats across incompatible vendor platforms into unified process historians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Reaction Monitoring Equipment Market |
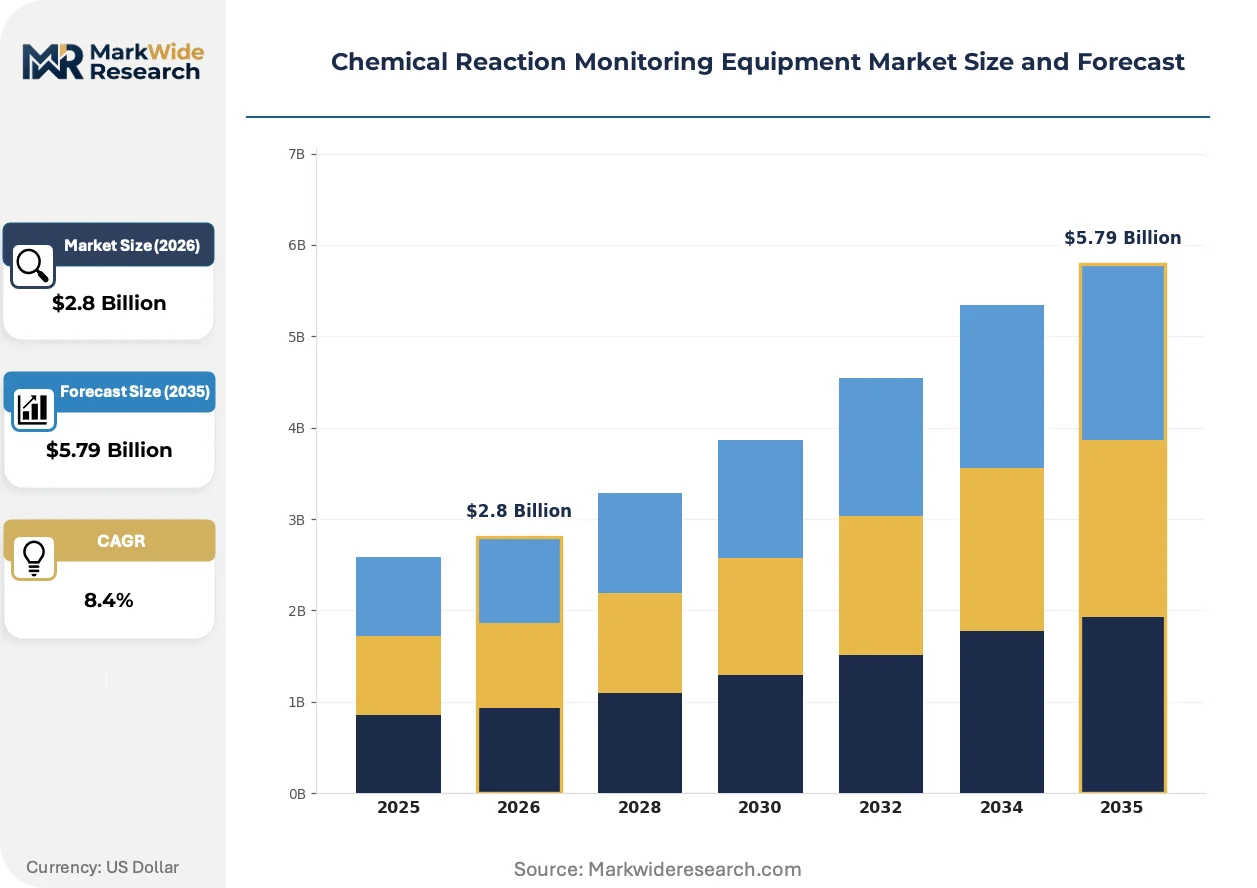
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectrophotometers, Chromatographs, Calorimeters, Sensors Technology: Infrared, UV-Vis, NMR, Mass Spectrometry End User: Chemical Manufacturers, Pharmaceuticals, Research Labs, Universities Application: Quality Control, Process Optimization, Research & Development, Compliance Testing |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Mettler-Toledo International, Waters Corporation, Shimadzu Corporation, PerkinElmer, Bruker Corporation, ABB, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Reaction Monitoring Equipment Market Trends and Innovations
Miniaturization and edge computing are redistributing analytical capability from central laboratories to production floor environments. These shifts are compressing the feedback loop between detection and process adjustment.
Benchtop NMR spectrometers with permanent magnet architectures are displacing superconducting systems for routine reaction monitoring in kilo-lab and pilot plant settings. Contract development and manufacturing organizations are adopting these systems to eliminate cryogen handling and reduce facility infrastructure requirements. The technology is displacing traditional at-line sampling and off-site laboratory analysis by enabling direct integration with automated sampling loops.
REACH authorization list expansion is compelling European chemical producers to install continuous emission monitoring interfaces on reaction vessels. ECHA substance evaluation protocols now require documented real-time detection capabilities for substances of very high concern during synthesis operations. Specialty chemical manufacturers in Belgium and the Netherlands are retrofitting existing batch reactors with Fourier-transform infrared probes to satisfy these documentation requirements.
Pharmaceutical procurement departments are consolidating spectroscopy vendor relationships to reduce qualification overhead and secure volume pricing on consumables. Large-molecule drug manufacturers are shifting from multi-vendor best-of-breed approaches to single-platform standardization for process analytical technology suites. This concentration is most pronounced among North American biotechnology firms building greenfield continuous manufacturing facilities.
Chemical Reaction Monitoring Equipment Market Segmentation
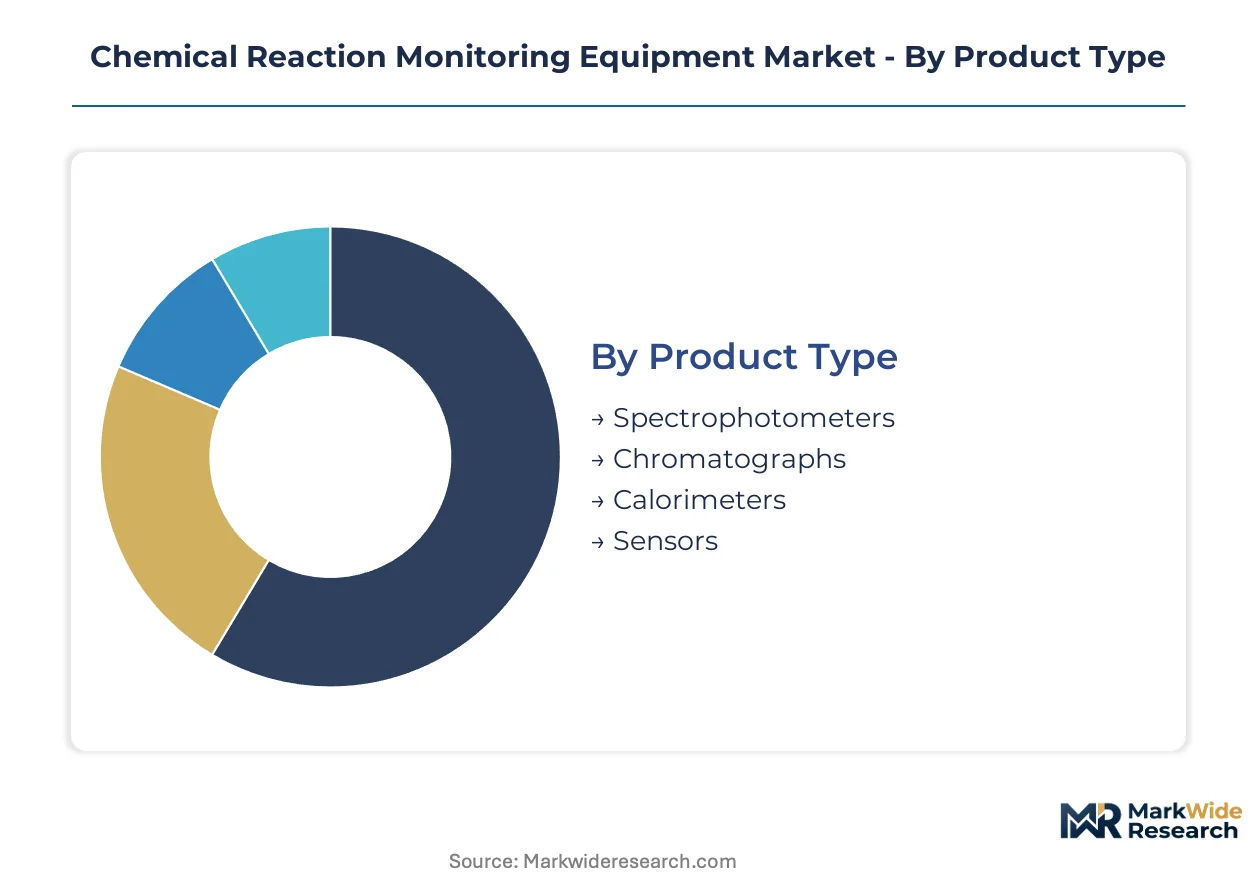
Chemical reaction monitoring equipment segments by measurement principle, deployment context, and regulatory intensity. Each dimension carries distinct margin profiles and qualification burdens that shape vendor strategy and buyer procurement cycles.
Product Type:
Domestic production dominates calorimeters and sensors for local chemical clusters, while spectrophotometers and chromatographs flow through specialized export channels serving pharmaceutical hubs.
- Spectrophotometers:These systems measure absorbance across ultraviolet, visible, and near-infrared wavelengths to track reaction kinetics in real time. Pharmaceutical manufacturers in Germany and Switzerland deploy UV-Vis diode arrays for continuous flow chemistry validation under EMA good manufacturing practice annexes.
- Chromatographs:Gas and liquid chromatography systems separate reaction mixtures for quantitative impurity profiling. Biologics producers in the United States rely on high-performance liquid chromatography for glycosylation pattern verification during cell culture monitoring.
- Calorimeters:Reaction calorimetry systems quantify heat flow to predict thermal runaway risks.
- Sensors:Inline pH, conductivity, and oxygen probes provide low-cost continuous monitoring for bulk chemical synthesis.
Spectrophotometers hold the largest share; momentum sits with calorimeters as REACH compliance timelines tighten.
Technology:
Cost tiers separate routine quality control methods from capital-intensive molecular specificity platforms, with mid-range infrared and UV-Vis systems capturing volume demand.
- Infrared:Fourier-transform infrared probes enable non-destructive functional group tracking in organic synthesis. Chemical manufacturers in Belgium retrofit batch reactors with attenuated total reflectance interfaces to satisfy ECHA substance evaluation documentation requirements.
- UV-Vis:Diode array spectrophotometers offer rapid multi-wavelength acquisition for endpoint determination. Generic drug clusters in Ahmedabad and Hyderabad deploy at-line UV-Vis systems as CDSCO quality mandate enforcement intensifies.
- NMR:Benchtop permanent magnet systems displace superconducting units for kilo-lab reaction monitoring.
- Mass Spectrometry:Molecular specificity drives adoption for complex bioprocess monitoring.
UV-Vis anchors volume deployment; mass spectrometry climbs the fastest as large-molecule drug synthesis expands.
End User:
Application maturity varies sharply—research labs pilot novel techniques while chemical manufacturers demand proven, qualified systems for production environments.
- Chemical Manufacturers:Integrated process analytical technology suites dominate capital allocation. Rhine-Ruhr and Ludwigshafen producers prioritize real-time impurity detection systems with sub-ppm resolution to meet REACH authorization timelines.
- Pharmaceuticals:Continuous manufacturing facilities require vendor consolidation to reduce qualification overhead. North American biotechnology firms standardize on single-platform spectroscopy suites for greenfield deployments.
- Research Labs:Price-sensitive adopters drive benchtop miniaturization demand.
- Universities:Educational and grant-funded research supports entry-level instrument procurement.
Chemical manufacturers command the largest spending pool; pharmaceuticals gain share fastest as continuous processing mandates spread.
Application:
Customer type stratification separates regulated pharmaceutical release testing from exploratory research functions, with compliance applications commanding premium pricing.
- Quality Control:At-line and in-line systems verify batch consistency against pharmacopoeial specifications. FDA process analytical technology guidance drives spectroscopic method qualification for real-time release testing in United States facilities.
- Process Optimization:Reaction calorimetry and inline spectroscopy identify yield-limiting parameters. Contract development organizations deploy benchtop NMR to eliminate cryogen handling while maintaining kinetic resolution.
- Research & Development:Early-phase synthesis exploration utilizes flexible, multi-technique platforms.
- Compliance Testing:Documented detection capabilities for substances of very high concern satisfy ECHA protocols.
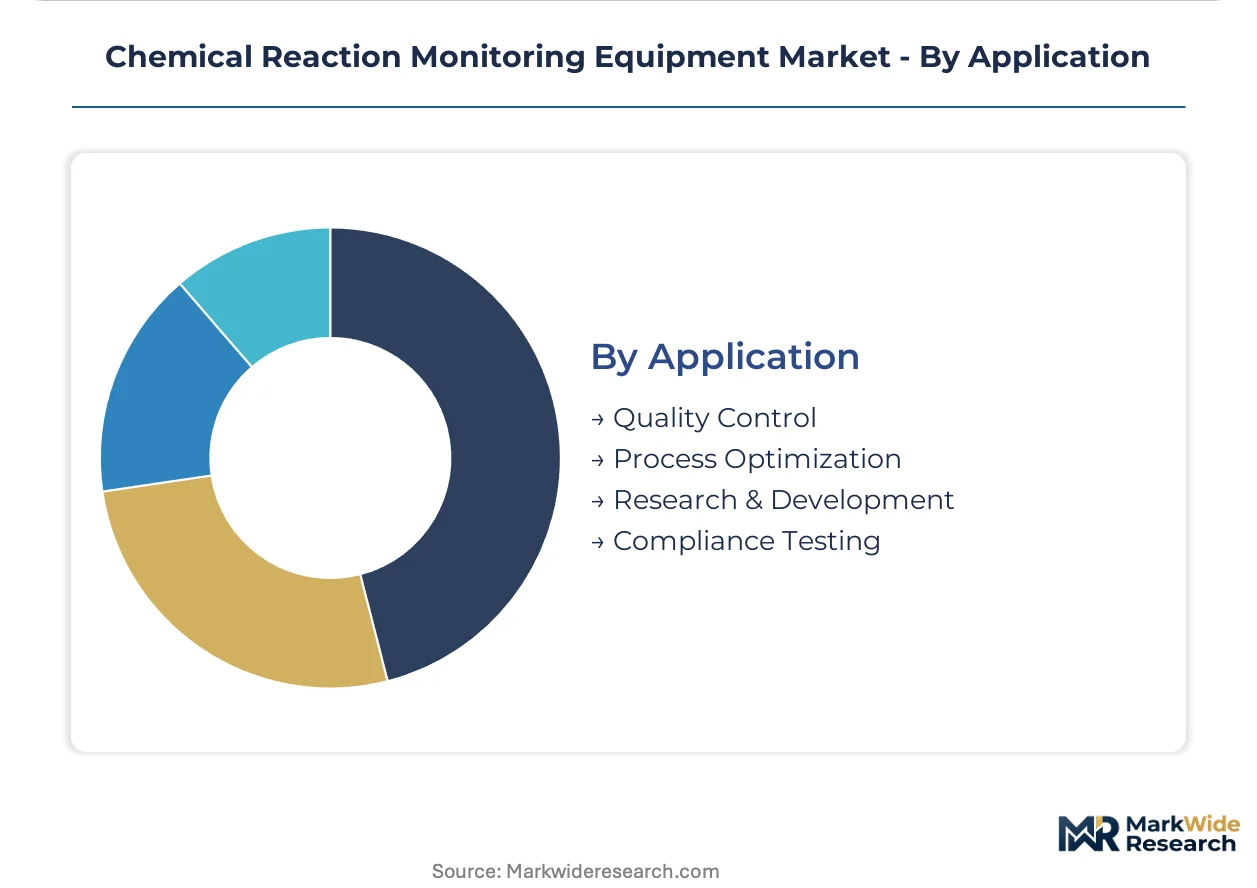
Quality control holds the largest share; process optimization expands most quickly as manufacturers pursue yield improvement contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of spectrophotometers and mass spectrometry systems concentrate from German and Japanese manufacturing hubs toward pharmaceutical clusters in the United States and India. Import dependency for high-purity optical fiber assemblies creates supply vulnerability for probe manufacturers across European chemical corridors. Regional regulatory divergence is fragmenting equipment qualification protocols and extending deployment timelines for multinational vendors.
United States
FDA process analytical technology guidance drives pharmaceutical manufacturers toward real-time release testing architectures. The agency's 21 CFR Part 11 electronic records requirements extend equipment qualification timelines to six-to-twelve months. Boston-Cambridge biotechnology clusters and New Jersey pharmaceutical corridors anchor demand for integrated spectroscopy suites in greenfield continuous manufacturing facilities.
Germany
REACH authorization list expansion compels Rhine-Ruhr and Ludwigshafen chemical producers to retrofit batch reactors with sub-ppm impurity detection systems. ECHA substance evaluation protocols mandate documented real-time monitoring for substances of very high concern during synthesis operations. Baden-Württemberg specialty chemical manufacturers are deploying Fourier-transform infrared probes to satisfy emission documentation requirements.
India
CDSCO quality mandate enforcement creates first-time demand for at-line UV-Vis systems in generic drug manufacturing. The regulator's tightened inspection protocols for active pharmaceutical ingredient facilities are accelerating spectroscopy procurement cycles. Ahmedabad and Hyderabad pharmaceutical clusters represent the fastest-expanding addressable market for benchtop reaction monitoring equipment.
China
NMPA good manufacturing practice annex revisions for biologics manufacturing are driving mass spectrometry adoption for glycosylation monitoring. The regulator's emphasis on data integrity in electronic batch records is favoring vendors with pre-validated software architectures. Yangtze River Delta contract development organizations are piloting benchtop NMR systems to eliminate cryogen handling in kilo-lab environments.
Japan
METI industrial competitiveness programs subsidize process analytical technology adoption for chemical manufacturers facing energy efficiency mandates. PMDA alignment with ICH Q13 continuous manufacturing guidelines is creating demand for vendor-consolidated spectroscopy platforms. Osaka-Kobe chemical corridors and Tokyo pharmaceutical clusters are standardizing on single-platform suites to reduce qualification overhead.
Chemical Reaction Monitoring Equipment Market Competitive Landscape
Concentration sits with diversified analytical instrumentation conglomerates that leverage cross-portfolio synergies to secure multi-year pharmaceutical contracts. The vendor base stratifies across three tiers: full-suite process analytical technology integrators, specialized spectroscopy platform developers, and regional calibration service providers. Strategic moves center on pre-integration of data integrity architectures and outcome-based contracting models tied to batch yield metrics.
Among diversified analytical instrumentation conglomerates, Thermo Fisher Scientific, Agilent Technologies, and Mettler-Toledo International occupy positions representing distinct competitive archetypes. Thermo Fisher Scientific exemplifies the mass spectrometry-dominant integrator targeting large-molecule drug manufacturers. Agilent Technologies anchors the UV-Vis diode array specialization for continuous flow chemistry applications. Mettler-Toledo International sits within the reaction calorimetry segment with direct process control integration capabilities. These three entities collectively represent the premium-tier competitive vector where vendor consolidation and qualification streamlining determine contract outcomes.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Mettler-Toledo International |
| Waters Corporation |
| Shimadzu Corporation |
| PerkinElmer |
| Bruker Corporation |
| ABB |
| Bio-Rad Laboratories |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Japanese and German optical fiber foundries shapes both supply availability and price floors for spectrophotometer probe assemblies. Pharmaceutical OEM procurement consolidation amplifies volume-discount leverage while compressing margins for mid-tier calibration service providers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA 21 CFR Part 11 pre-validation status and geographic delivery cost to regulated pharmaceutical hubs. Cost compression in the economy tier is intensifying because generic drug manufacturers in India demand stripped-down UV-Vis configurations. Research laboratories exhibit highest price sensitivity; large-molecule biologics producers show lowest sensitivity due to qualification timeline risks.
Supply Chain Analysis
Strategic stockpiling of high-purity silica preforms dominates procurement behavior among probe assembly manufacturers facing Japanese foundry allocation constraints. Supply concentrates in Japan, Germany, and the United States for specialty optical fiber; China and South Korea dominate rare-earth magnet sourcing for NMR permanent magnet architectures. Single-source vulnerability runs through cryogen-free magnet wire suppliers. Distribution runs through authorized distributor networks serving pharmaceutical validation clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of magnetic resonance physics technicians capable of NMR probe calibration creates a structural bottleneck that shapes competitive positioning and M&A targeting across vendor tiers.
For Market Incumbents: Fortify data integrity architecture pre-integration to compress six-to-twelve-month pharmaceutical qualification timelines. Pursue backward integration into high-purity optical fiber sourcing to neutralize Japanese foundry allocation volatility. Lock in multi-year consumables contracts with North American biotechnology clusters building greenfield continuous manufacturing facilities. For New Entrants and Emerging Players: CDSCO fast-track certification for at-line UV-Vis systems opens immediate penetration opportunity in Ahmedabad and Hyderabad generic drug corridors. Target price-sensitive research laboratory segments with benchtop NMR configurations eliminating cryogen handling. Lead with outcome-based pricing tied to batch yield improvement rather than capital equipment sale. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among reaction calorimetry vendors piloting equipment-as-service contracting models. Long-term viability favors acquisition targets with established EMA pre-validation dossiers and direct process control integration capabilities. Watch for inflection when REACH authorization list expansion accelerates retrofit demand in Belgian and Dutch specialty chemical corridors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Validation Investment | Compresses pharmaceutical equipment qualification timelines from twelve months toward six. |
| Backward Integration into Optical Fiber | Neutralizes supply volatility from Japanese and German specialty silica foundries. |
| Equipment-as-Service Contracting | Converts capital expenditure into recurring revenue tied to batch yield metrics. |
| Raman-NIR Sensor Fusion Development | Enables simultaneous polymorph identification and moisture monitoring for crystallization. |
| CDSCO Certification Fast-Track | Captures first-time demand in Ahmedabad and Hyderabad generic drug clusters. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with plant engineers, pharmaceutical regulatory affairs leads, OEM procurement teams, and aftermarket service heads; and secondary validation through FDA 510(k) filings, EMA qualification dossiers, customs trade records, and SEC 10-K equipment revenue disclosures. Bottom-up vendor shipment estimates triangulated against top-down pharmaceutical capital expenditure surveys.
Across the projection horizon, the analytical framework modeled technology type, deployment context, regulatory intensity tier, and end-user application maturity. CAGRs derived from segmented growth rate blending anchored in EMA and FDA mandate enforcement timelines. Industry-specific inputs included REACH authorization list expansion schedules and CDSCO inspection protocol tightening intensity.
Decision-makers should treat outputs as directional under sustained EMA process analytical technology annex enforcement; material deviation would warrant model refresh. Revision becomes warranted when legacy distributed control system retrofit penetration crosses thresholds enabling Ethernet-APL spectroscopic data streaming.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
Analytical Gel Permeation Chromatography Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Lubricant Testing Machine Market
Testing Equipment
Paper Tester Market
Testing Equipment
Cyclic Corrosion Test Chamber Market
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Hydrometer Market
Testing Equipment
Stack Emissions Real-Time Speciation and Compliance Test Systems Market
Testing Equipment
Paper Moisture Meter Market
Testing Equipment
HPLC Market
Testing Equipment
Water Test Kits Market
Testing Equipment
Material Tester Market
Testing Equipment
Hydrocarbon Tester Market