
 Liquid Chromatography Market | 2026-2036
Liquid Chromatography Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Chromatography Market Outlook
Buyer concentration is rebalancing as contract research organizations fragment procurement across specialized vendors while large pharmaceutical houses consolidate multi-year service agreements. Waters Corporation leverages its column chemistry intellectual property to sustain premium positioning in regulated pharmaceutical workflows. Agilent Technologies anchors its installed base through integrated software-hardware platforms that reduce method transfer friction between laboratories.
Liquid chromatography separates dissolved compounds by differential partitioning between a mobile liquid phase and a stationary solid phase, typically employing silica-based columns with bonded functional groups and operating pressures from 6000 psi in HPLC systems to over 15000 psi in UHPLC configurations for complex mixture resolution. Ultra-high-performance liquid chromatography systems command the fastest expansion trajectory as laboratories replace legacy HPLC infrastructure to achieve higher throughput and reduced solvent costs per sample. Pharmaceutical analysis applications concentrate the largest revenue pool given mandatory impurity profiling and bioequivalence testing requirements across branded and generic drug pipelines.
FDA enforces method validation standards under ICH Q2(R1) guidelines that directly dictate column selection and detector configuration for drug approval submissions, while EMA's MDR framework extends comparable analytical rigor to medical device leachable studies. China's NMPA accelerates local substitution policies for analytical instruments used in domestic pharmaceutical manufacturing. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP monographs to anticipate column format and detection method obsolescence risks.
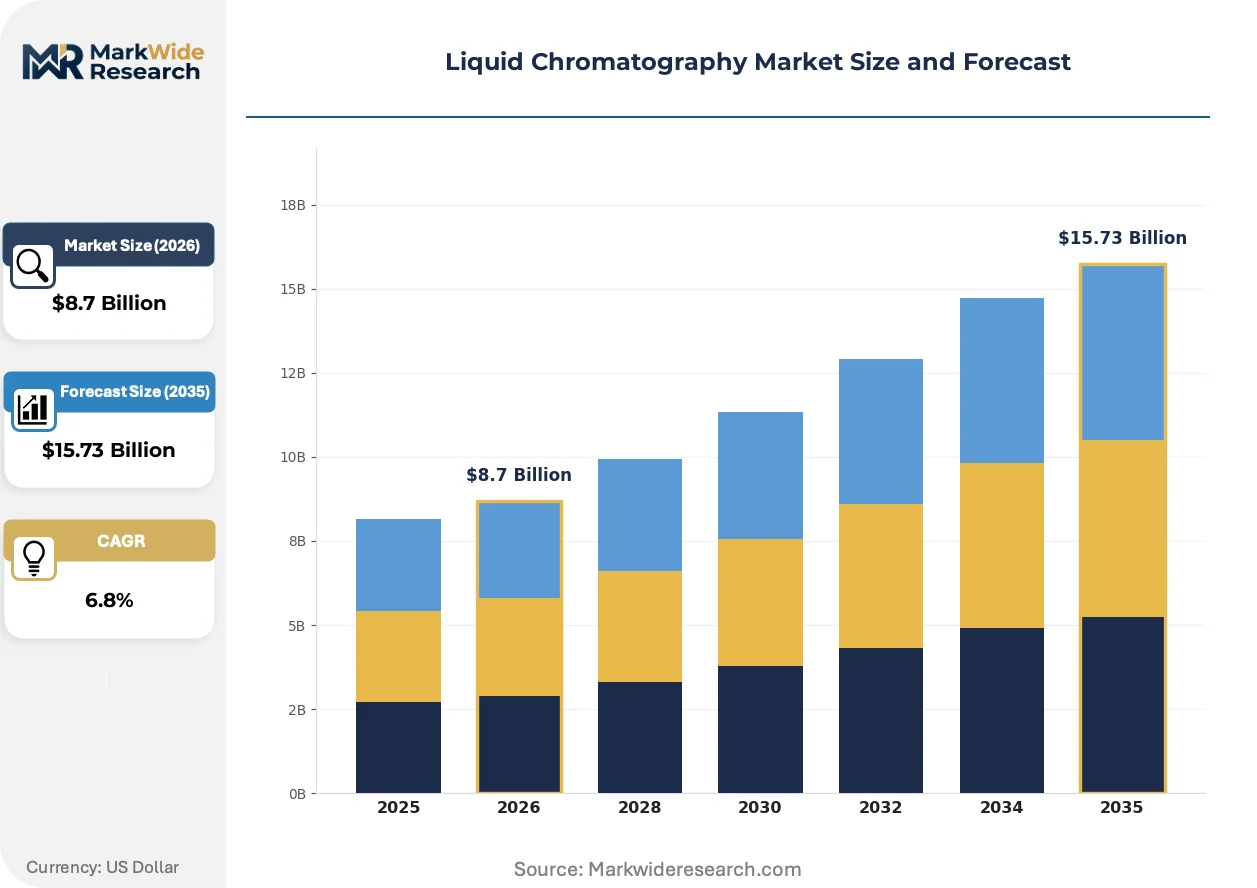
Market Dynamics
Ultra-high-performance liquid chromatography systems are compressing replacement cycles as laboratories face simultaneous pressure from FDA method validation mandates and solvent cost reduction targets. The transition from 6000 psi HPLC infrastructure to 15000 psi UHPLC platforms concentrates procurement decisions among multi-site pharmaceutical networks seeking standardized workflows.
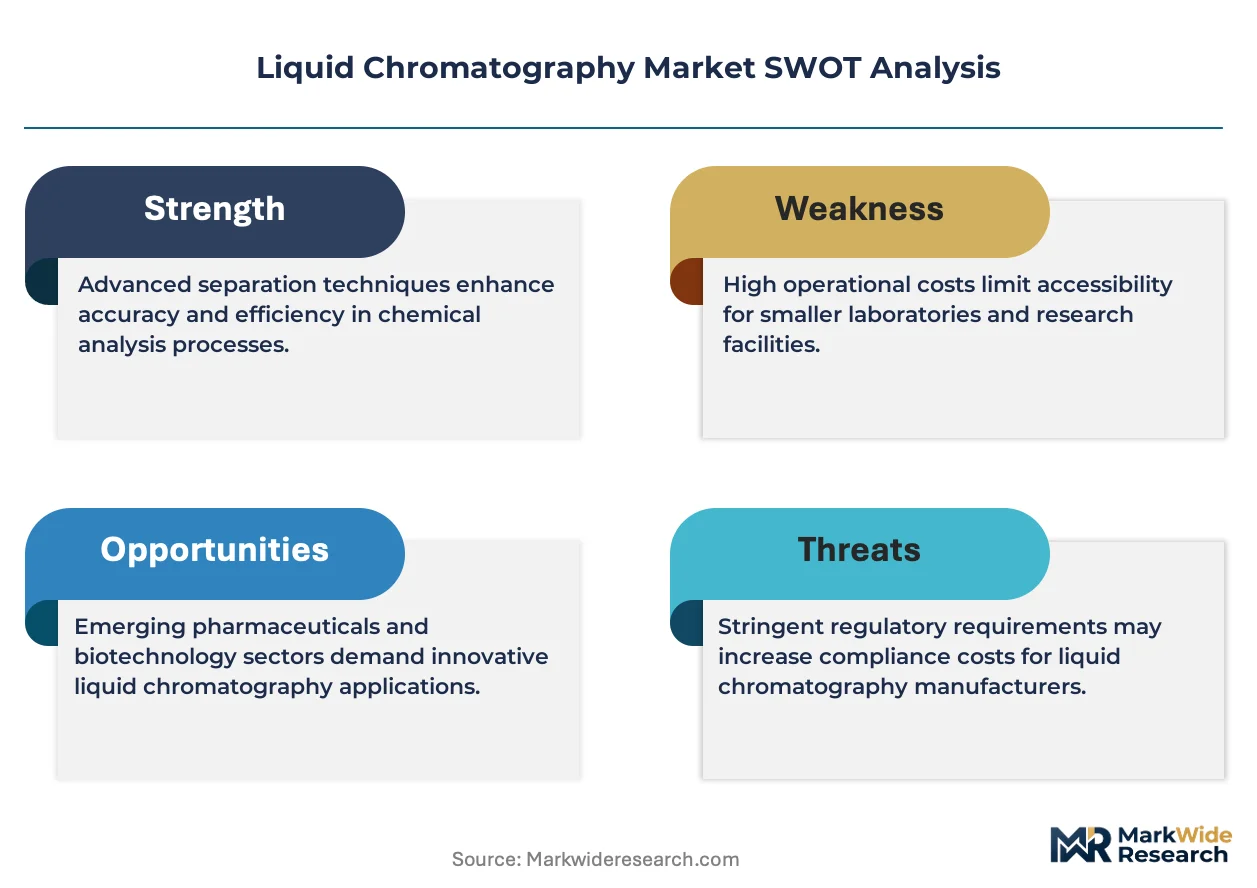
Growth Catalysts
- FDA ICH Q2(R1) Method Validation:Mandatory impurity profiling requirements for drug approval submissions force pharmaceutical manufacturers to upgrade detector configurations and column formats.
- Sub-two-micron particle columns:Advances in bonded functional group chemistry reduce run times and solvent consumption per sample, accelerating infrastructure replacement in high-throughput laboratories.
- China biologics manufacturing clusters:NMPA local substitution policies for analytical instruments used in domestic pharmaceutical production create concentrated procurement in Shanghai and Suzhou.
Market Restraints
- Helium supply volatility:Gas chromatography-mass spectrometry systems compete for constrained noble gas supplies, pressuring LC-MS detector operating costs.
- Column chemistry IP concentration:Proprietary bonded-phase patents held by incumbent suppliers limit third-party column compatibility and inflate consumables pricing.
- EMA MDR analytical rigor:Extended validation timelines for medical device leachable studies delay instrument commissioning and revenue recognition for vendors.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore require analytical capacity expansion to serve export markets.
- AI-driven method development:Machine learning algorithms for chromatographic parameter optimization converge with cloud-based data management platforms to reduce skilled analyst requirements.
- Green chemistry solvent reduction:Regulatory incentives for environmentally sustainable laboratory practices accelerate demand for low-flow UHPLC configurations.
Industry Challenges
- Cross-training analytical chemists:The shift from HPLC to UHPLC operation requires proficiency in high-pressure system maintenance and sub-two-micron column handling.
- Legacy method transfer friction:Pharmaceutical quality control laboratories face extended validation periods when migrating established compendial methods between instrument platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Chromatography Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
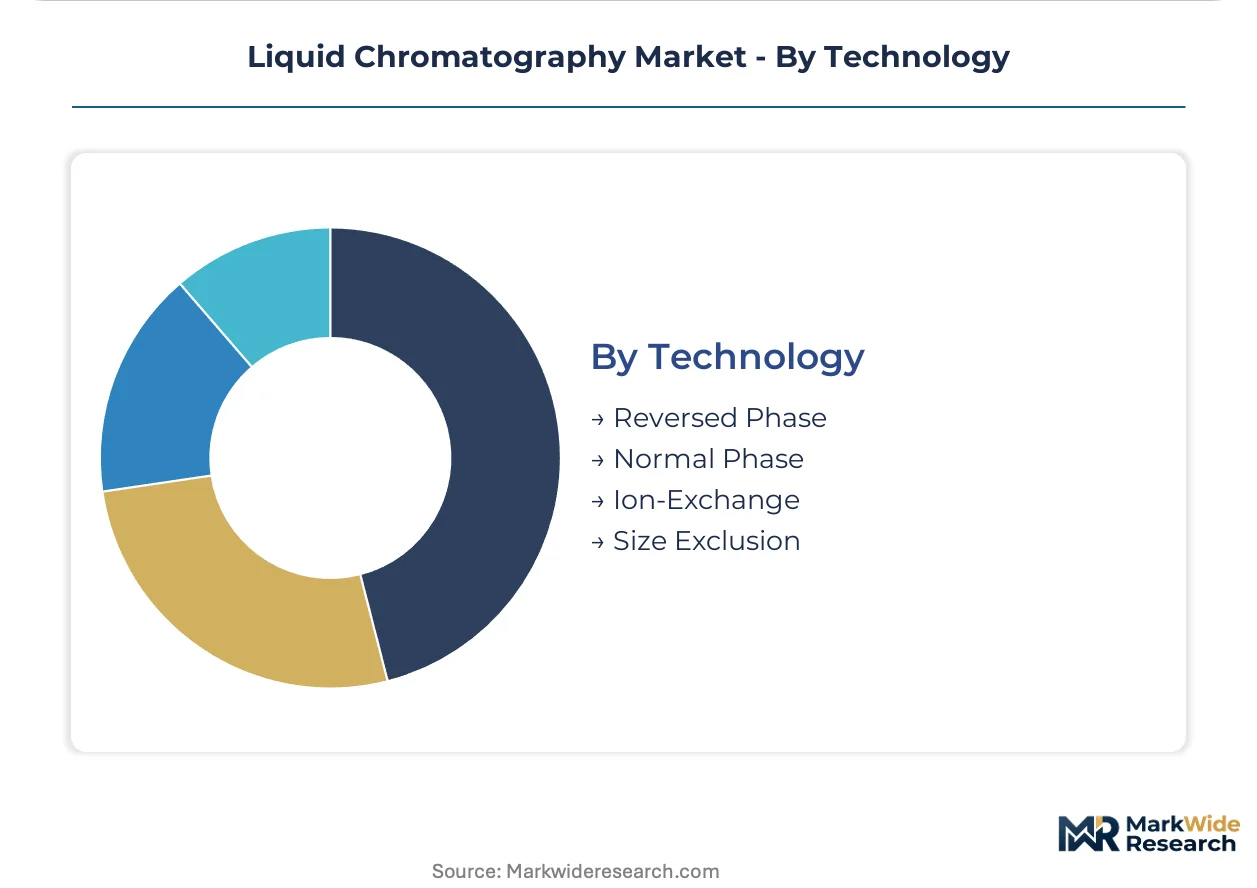
| Segmentation | Product Type: High-Performance Liquid Chromatography, Ultra-High-Performance Liquid Chromatography, Preparative Liquid Chromatography, Flash Chromatography Application: Pharmaceutical Analysis, Environmental Testing, Food Safety Testing, Clinical Diagnostics End User: Pharmaceutical Companies, Research Laboratories, Academic Institutions, Contract Research Organizations Technology: Reversed Phase, Normal Phase, Ion-Exchange, Size Exclusion |
| Companies Covered | Shimadzu Corporation, Merck KGaA, Waters Corporation, Bio-Rad Laboratories, Sartorius AG, Thermo Fisher Scientific, PerkinElmer, Tosoh Bioscience, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Chromatography Market Strategic Shifts
Chromatography vendors are embedding predictive maintenance algorithms and remote diagnostics into instrument control software, transforming capital equipment into connected analytical assets. This connectivity layer is compressing service response times and enabling usage-based consumables replenishment models.
Sub-two-micron superficially porous particle technology is expanding into peptide mapping and intact protein analysis workflows previously dominated by size-exclusion chromatography. Biologics manufacturers in Massachusetts and North Carolina are adopting these columns to reduce sample preparation steps for monoclonal antibody characterization. The technology is expanding into quality control release testing, compressing the timeline between manufacturing batch completion and regulatory documentation submission.
EMA's Medical Device Regulation extends analytical rigor to leachable and extractable studies for polymer-based delivery systems, mandating LC-MS methodology for semi-volatile organic compound identification. Medical device manufacturers in Ireland and Germany are establishing dedicated chromatography laboratories to meet notified body expectations. The regulation is forcing instrument vendors to pre-validate qualitative screening methods and standardize reporting templates for technical documentation packages.
Contract research organizations are fragmenting analytical service procurement across specialized vendors rather than consolidating with full-service providers. Large pharmaceutical houses in New Jersey and Pennsylvania now maintain approved vendor lists exceeding twenty chromatography service suppliers, each qualified for specific therapeutic area expertise. This pattern is most visible in early-phase clinical bioanalysis, where sponsor companies rotate studies among regional laboratories to mitigate single-site capacity constraints.
Liquid Chromatography Market Segmentation
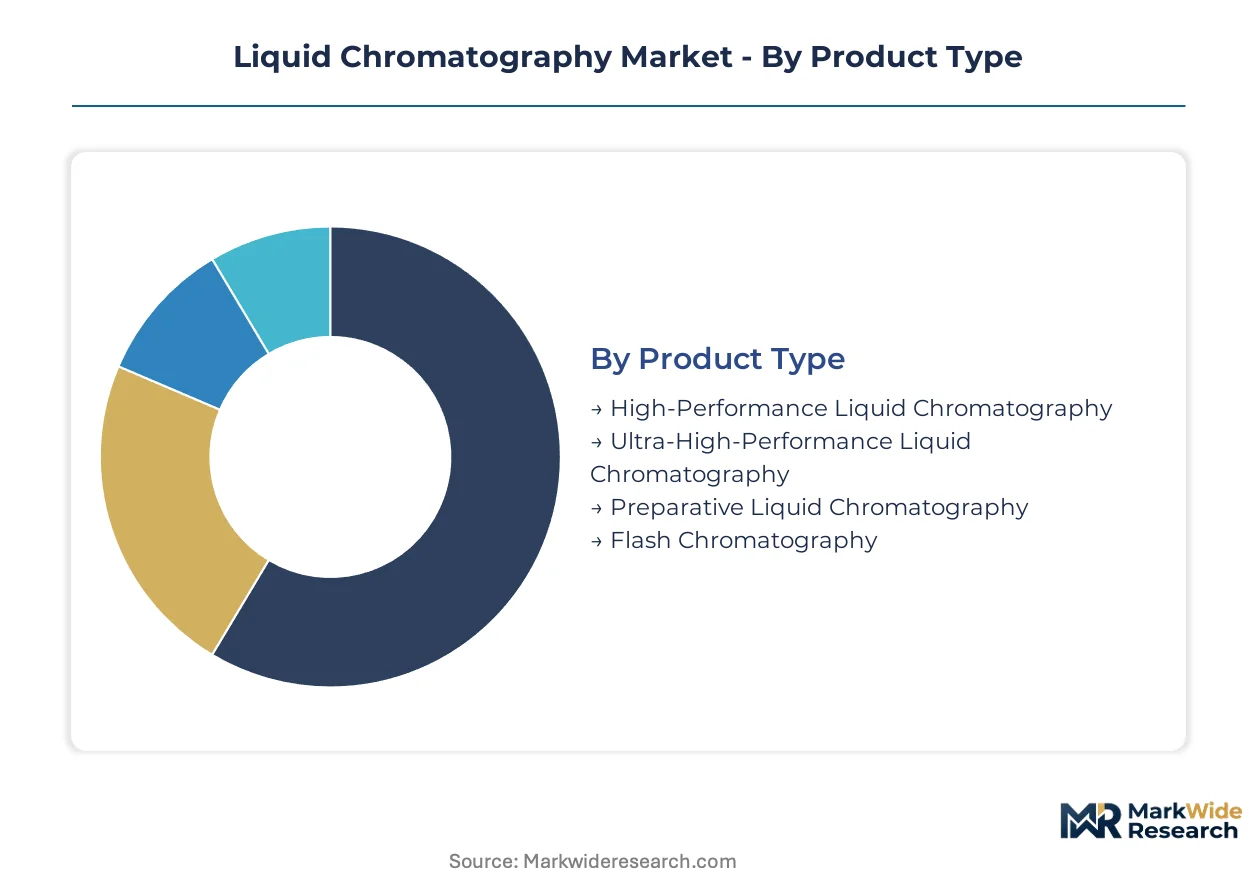
Liquid chromatography procurement patterns diverge sharply across product configurations, with pressure ratings and particle size capabilities dictating replacement cycles. Application requirements from FDA-regulated pharmaceutical workflows to environmental compliance monitoring reshape detector and column specifications within each segment.
Product Type:
Supply concentration tilts toward ultra-high-performance platforms as multi-site pharmaceutical networks standardize on 15000 psi infrastructure to reduce solvent costs per sample.
- High-Performance Liquid Chromatography:Conventional 6000 psi systems with 3-5 micron particle columns dominate legacy quality control laboratories in generic drug manufacturing facilities across India and Eastern Europe. Replacement demand concentrates where FDA method validation mandates have not yet forced infrastructure upgrades.
- Ultra-High-Performance Liquid Chromatography:Sub-two-micron particle compatibility and elevated pressure tolerance compress run times by 70% in high-throughput bioanalytical laboratories. Massachusetts and North Carolina biologics clusters drive concentrated procurement as monoclonal antibody characterization workflows migrate from size-exclusion alternatives.
- Preparative Liquid Chromatography:Scale-up purification systems serve contract manufacturing organizations in Hyderabad and Bangalore isolating active pharmaceutical ingredients for export markets.
- Flash Chromatography:Rapid purification workstations support medicinal chemistry discovery groups in academic institutions and early-phase pharmaceutical research.
Today's leader: Ultra-High-Performance Liquid Chromatography. Tomorrow's challenger: Preparative Liquid Chromatography as CDMO capacity expands.
Application:
Cost tier separation emerges between mandatory regulatory testing with validated methods and discretionary screening programs vulnerable to budget compression.
- Pharmaceutical Analysis:Impurity profiling and bioequivalence testing under ICH Q2(R1) guidelines command the largest revenue pool, with branded and generic drug pipelines requiring identical analytical rigor. United States and German facilities concentrate spending on multi-detector configurations for forced degradation studies.
- Environmental Testing:EPA Method 525.3 for semi-volatile organic compounds and emerging per- and polyfluoroalkyl substances monitoring drive LC-MS detector upgrades in commercial laboratories. Regulatory enforcement variance across states creates patchwork procurement intensity.
- Food Safety Testing:Mycotoxin and pesticide residue screening operates on slimmer margins, with third-party laboratories in China prioritizing lower-cost HPLC platforms over UHPLC migration.
- Clinical Diagnostics:Therapeutic drug monitoring and vitamin D analysis represent the fastest-climbing application as hospital laboratories consolidate chemistry and immunoassay workflows onto chromatography platforms.
Pharmaceutical Analysis captures current margin concentration. Clinical Diagnostics presents the steepest expansion trajectory as diagnostic networks automate sample preparation.
End User:
Customer type fragmentation accelerates as contract research organizations disperse procurement across specialized vendors while large pharmaceutical houses consolidate multi-year service agreements.
- Pharmaceutical Companies:Internal analytical departments in New Jersey and Pennsylvania maintain approved vendor lists exceeding twenty chromatography service suppliers, each qualified for specific therapeutic area expertise. Capital budgets prioritize UHPLC standardization across manufacturing and quality control sites.
- Research Laboratories:Government and institutional facilities face constrained equipment replacement cycles, extending HPLC platform lifespans beyond typical depreciation schedules.
- Academic Institutions:Training laboratories in Germany and Switzerland emphasize fundamental HPLC operation over UHPLC exposure, creating skills gaps for industrial placement.
- Contract Research Organizations:Early-phase clinical bioanalysis providers in Hyderabad and Bangalore rotate studies among regional laboratories to mitigate single-site capacity constraints, fragmenting instrument procurement.
Pharmaceutical Companies anchor current instrument revenue. Contract Research Organizations are gaining share fastest as sponsor companies outsource analytical capacity.
Technology:
Application maturity determines margin structure, with established bonded-phase chemistries facing pricing pressure from proprietary column patents.
- Reversed Phase:C18 and polar-embedded alkyl phases handle 80% of small-molecule pharmaceutical applications, with method transfer friction between instrument platforms extending validation timelines for quality control laboratories.
- Normal Phase:Polar stationary phases retain specialized demand for chiral separations in synthetic route development, particularly in Swiss and Irish pharmaceutical research centers.
- Ion-Exchange:Protein and peptide charge-based separation supports biologics manufacturing in Shanghai and Suzhou clusters under NMPA local substitution policies.
- Size Exclusion:Intact protein and aggregate analysis faces displacement pressure from superficially porous particle alternatives in monoclonal antibody workflows.
Reversed Phase dominates current method portfolios. Ion-Exchange is expanding most quickly as biologics manufacturing scales in China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains tighter regulatory harmonization across pharmaceutical workflows than China, where provincial manufacturing clusters operate under evolving NMPA substitution mandates that accelerate local instrument procurement.
United States
FDA ICH Q2(R1) method validation requirements drive pharmaceutical manufacturers in New Jersey and Pennsylvania to upgrade detector configurations for impurity profiling. Massachusetts biologics clusters adopt sub-two-micron particle columns to compress monoclonal antibody characterization timelines. Waters Corporation leverages column chemistry intellectual property to sustain premium positioning in regulated workflows.
Germany
EMA MDR analytical rigor extends to medical device leachable studies, mandating LC-MS methodology for polymer-based delivery systems. Medical device manufacturers in Ireland and Germany establish dedicated chromatography laboratories to meet notified body expectations. Agilent Technologies anchors its installed base through integrated software-hardware platforms that reduce method transfer friction.
China
NMPA local substitution policies for analytical instruments create concentrated procurement in Shanghai and Suzhou biologics manufacturing clusters. Contract development and manufacturing organizations in Hyderabad and Bangalore require analytical capacity expansion to serve export markets. Ion-exchange technology expands most quickly as biologics manufacturing scales under national dual carbon goals.
India
CDSCO export compliance requirements push contract research organizations in Hyderabad and Bangalore to fragment procurement across specialized vendors rather than consolidating with full-service providers. Early-phase clinical bioanalysis providers rotate studies among regional laboratories to mitigate single-site capacity constraints. Generic drug manufacturing facilities across India and Eastern Europe extend HPLC platform lifespans where FDA mandates have not yet forced infrastructure upgrades.
Japan
PMDA pharmacopeial alignment with USP and EP monographs shapes column format selection for quality control release testing. Academic training laboratories emphasize fundamental HPLC operation over UHPLC exposure, creating skills gaps for industrial placement. METI-supported research institutions face constrained equipment replacement cycles that delay platform standardization.
Liquid Chromatography Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across instrument and consumables segments, creating a tiered structure where column chemistry intellectual property concentrates margin capture. The vendor base spans analytical instrument conglomerates with broad life science portfolios, precision engineering specialists with chromatography-dedicated manufacturing, and regional suppliers serving price-sensitive emerging markets. Two dominant competitive moves define current positioning: strategic partnerships between column chemistry innovators and instrument platform vendors, and geographic expansion through localized service networks in China and India manufacturing clusters.
Among diversified analytical science conglomerates, Thermo Fisher Scientific and Agilent Technologies occupy positions as integrated platform providers spanning hardware, software, and consumables. Waters Corporation exemplifies the focused specialist archetype, leveraging proprietary bonded-phase patents to limit third-party column compatibility. Merck KGaA represents the European diversified chemical conglomerate with life science analytical divisions, while Shimadzu Corporation anchors the precision engineering tradition with chromatography-dedicated manufacturing capabilities. These four entities collectively represent the competitive spectrum from full-service integration to technology-specific depth.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Merck KGaA |
| Waters Corporation |
| Bio-Rad Laboratories |
| Sartorius AG |
| Thermo Fisher Scientific |
| PerkinElmer |
| Tosoh Bioscience |
| Agilent Technologies |
| Others |
Value Chain & Pricing Dynamics
Performance-grade bifurcation between UHPLC and legacy HPLC platforms manifests in divergent margin structures and supplier qualification requirements across pharmaceutical procurement networks. FDA-validated workflows command premium positioning through bonded-phase chemistry patents, while generic drug manufacturers in India and Eastern Europe extend depreciation cycles on conventional 6000 psi infrastructure.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for consumables and service contracts as NMPA local substitution policies accelerate domestic column manufacturing. Three-tier pricing structure across premium, standard, and economy levels separates Waters Corporation's proprietary bonded-phase offerings from Agilent's integrated platform bundles and regional third-party column suppliers. Pricing pressure stems from helium supply volatility elevating LC-MS operating costs and CRO procurement fragmentation across specialized vendors. Generic drug manufacturers exhibit highest price sensitivity, while branded pharmaceutical houses in New Jersey and Pennsylvania prioritize method validation security over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from multi-site pharmaceutical networks mandate qualified secondary suppliers for bonded-phase columns and detector modules to mitigate single-source vulnerability. Manufacturing concentration spans Germany, the United States, and China, with Shanghai and Suzhou biologics clusters driving localized instrument assembly under NMPA substitution mandates. Silica particle supply draws from specialized chemical processors in Japan and Germany, while bonded functional group chemistry rests on proprietary polymer synthesis in Massachusetts and Switzerland. Tariff exposure on precision pressure transducers and ceramic pump seals creates cost volatility for UHPLC platform assembly. Distribution runs through authorized service networks with regional depot stocking for critical consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in liquid chromatography hinges on solvent cost compression through sub-two-micron particle adoption and premium-tier consolidation around validated pharmaceutical workflows.
For Market Incumbents: Anticipate displacement pressure from superficially porous particle alternatives in monoclonal antibody characterization by deepening captive supply of bonded-phase chemistry patents. Defend installed base stickiness through integrated software-hardware platforms that extend method transfer friction penalties for competitor systems. Prioritize certification investment in EMA MDR pre-validated qualitative screening methods for medical device leachable studies. For New Entrants and Emerging Players: Direct-to-clinic service models for therapeutic drug monitoring represent the most penetrable white-space target as hospital laboratories automate sample preparation workflows. Target CDMO capacity expansion in Hyderabad and Bangalore with rental-based UHPLC configurations that reduce capital barriers for export compliance. Pursue AI-driven method development partnerships with cloud-based data management platforms to reduce skilled analyst requirements in early-phase clinical bioanalysis. For Investors and Strategic Acquirers: Consolidation pressure builds where column chemistry IP concentration limits third-party compatibility and inflates consumables pricing for generic drug manufacturers. Long-term viability favors specialists with vertical control over bonded-phase polymer synthesis rather than instrument assembly alone. Watch NMPA pharmacopeial harmonization progress with USP and EP monographs as the inflection signal for column format obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Sub-two-micron Particle Column Expansion | Reduces run times by 70% in Massachusetts biologics clusters under FDA impurity profiling mandates. |
| AI-driven Method Development Platform | Converges machine learning algorithms with cloud data management to compress skilled analyst requirements. |
| EMA MDR Pre-validated Screening Methods | Standardizes LC-MS reporting templates for polymer-based medical device leachable studies in Germany. |
| CDMO Analytical Capacity Buildout | Serves export market compliance for Hyderabad and Bangalore contract manufacturing organizations. |
| Green Chemistry Solvent Reduction Program | Accelerates low-flow UHPLC demand under regulatory incentives for sustainable laboratory practices. |
Study Parameters
Bottom-up pharmaceutical application modeling reconciled against top-down instrument shipment tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, quality control laboratory managers, and chromatography service procurement officers were validated against FDA 483 inspection observations, EMA marketing authorization databases, NMPA registration filings, and SEC 10-K instrument revenue disclosures. Secondary sources include USP-NF monograph revision notices, pharmacopeial harmonization working group minutes, and academic laboratory equipment replacement cycle surveys.
Input-output matrices connect pressure-rated platform configurations to end-use application requirements across the projection horizon. Segmentation dimensions encompass product type, application, end user, and technology, with additional modeling of regional regulatory cluster effects on procurement timing. CAGRs were derived from installed base replacement cycle analysis and solvent cost elasticity estimates. Forecast inputs include NMPA local substitution policy implementation velocity and EMA MDR notified body capacity constraints.
The model assumes a particular technology adoption path; alternative pathways for superficially porous particle displacement of size-exclusion chromatography would alter the outlook. Forecasts reflect assumptions regarding pharmacopeial harmonization progress and helium supply stabilization. Deviation in FDA method validation enforcement intensity or NMPA dual carbon goal acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
HPLC Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Paper Tester Market
Testing Equipment
Global Chromatography Instrumentation Market
Testing Equipment
Global Trace Metal Analysis Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Global Chiral Chromatography Column Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
Pellistor Bead Chemical Sensor Market
Testing Equipment
Polymer Testing Equipment Market
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
Europe Non-Destructive Testing Market