
 Pellistor Bead Chemical Sensor Market | 2026-2036
Pellistor Bead Chemical Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Pellistor Bead Chemical Sensor Market Analytics
REACH compliance is recalibrating the cost-of-entry calculus for European pellistor manufacturers, forcing reformulation of catalytic bead compositions to eliminate restricted substances. Honeywell Analytics leverages its vertically integrated sensing element production to sustain margin advantages across industrial safety contracts. MSA Safety anchors its position through deep channel control in North American oilfield services. Pepperl+Fuchs differentiates via intrinsic safety certifications that dominate hazardous area installations.
A pellistor bead chemical sensor employs a catalytically active platinum-group metal deposited on a refractory oxide bead, typically alumina, heated to 450–550°C where combustible gases oxidize and alter electrical resistance proportionally to concentration. The device serves primarily for detecting flammable gases in explosion-risk environments where real-time ppm-level sensitivity prevents catastrophic ignition events. Multi-bad configurations lead the product landscape due to redundancy requirements in offshore platforms and chemical plants, while smart bead variants incorporating temperature compensation and self-diagnostics represent the fastest-expanding margin pool. Oil and gas applications command the largest revenue share among end-use segments, though waste management installations are gaining traction from landfill methane capture regulations.
OSHA permissible exposure limits and EPA methane emissions standards in the United States shape product specifications and replacement demand cycles for installed detection networks. ECHA substance restrictions under REACH and ATEX equipment directives in Europe mandate specific material compositions and certification pathways that filter non-compliant suppliers from tender processes. Stakeholders must monitor evolving hydrogen economy safety codes, as pellistor cross-sensitivity profiles for hydrogen versus hydrocarbons will determine sensor architecture decisions in emerging energy infrastructure.
Market Dynamics
REACH substance restrictions are forcing catalytic bead reformulations across European supply chains, eliminating platinum-group metal alternatives while tightening ATEX certification pathways that filter non-compliant vendors from industrial safety tenders.
Growth Catalysts
- OSHA permissible exposure limits:US manufacturing facilities face mandatory detector replacement cycles for legacy combustible gas networks, sustaining hardware refresh demand.
- Landfill methane capture mandates:Waste management infrastructure expansion in Germany and the Netherlands drives pellistor deployment for biogas monitoring and leak detection.
- Multi-bead redundancy architectures:Offshore platform safety codes now require dual-sensor configurations, doubling unit density per installation site.
Market Restraints
- Palladium price volatility:Catalytic bead production faces input cost pressure from precious metal commodity swings, compressing margin pools for non-integrated manufacturers.
- Cross-sensitivity limitations:Hydrogen versus hydrocarbon discrimination gaps in standard pellistor designs create false-positive risks that infrared alternatives exploit.
- ATEX certification timelines:Extended approval cycles for modified bead chemistries delay product launches by 8-14 months in European markets.
Strategic Opportunities
- Hydrogen economy safety infrastructure:Emerging H2 refueling station codes in Germany and Japan create first-mover positioning for hydrogen-optimized bead formulations.
- Smart bead self-diagnostics:Temperature compensation and drift-correction algorithms enable predictive maintenance contracts that extend customer lifetime value.
- India's industrial safety modernization:Factory Act enforcement expansion and BIS standards alignment open replacement demand for unorganized sector installations.
Industry Challenges
- Specialized electrochemist recruitment:Catalytic bead R&D requires rare expertise in high-temperature heterogeneous catalysis that competes with battery and fuel cell sectors.
- Legacy 4-20mA integration:Digital smart beads face retrofit friction against existing analog control systems in mature chemical plant installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pellistor Bead Chemical Sensor Market |
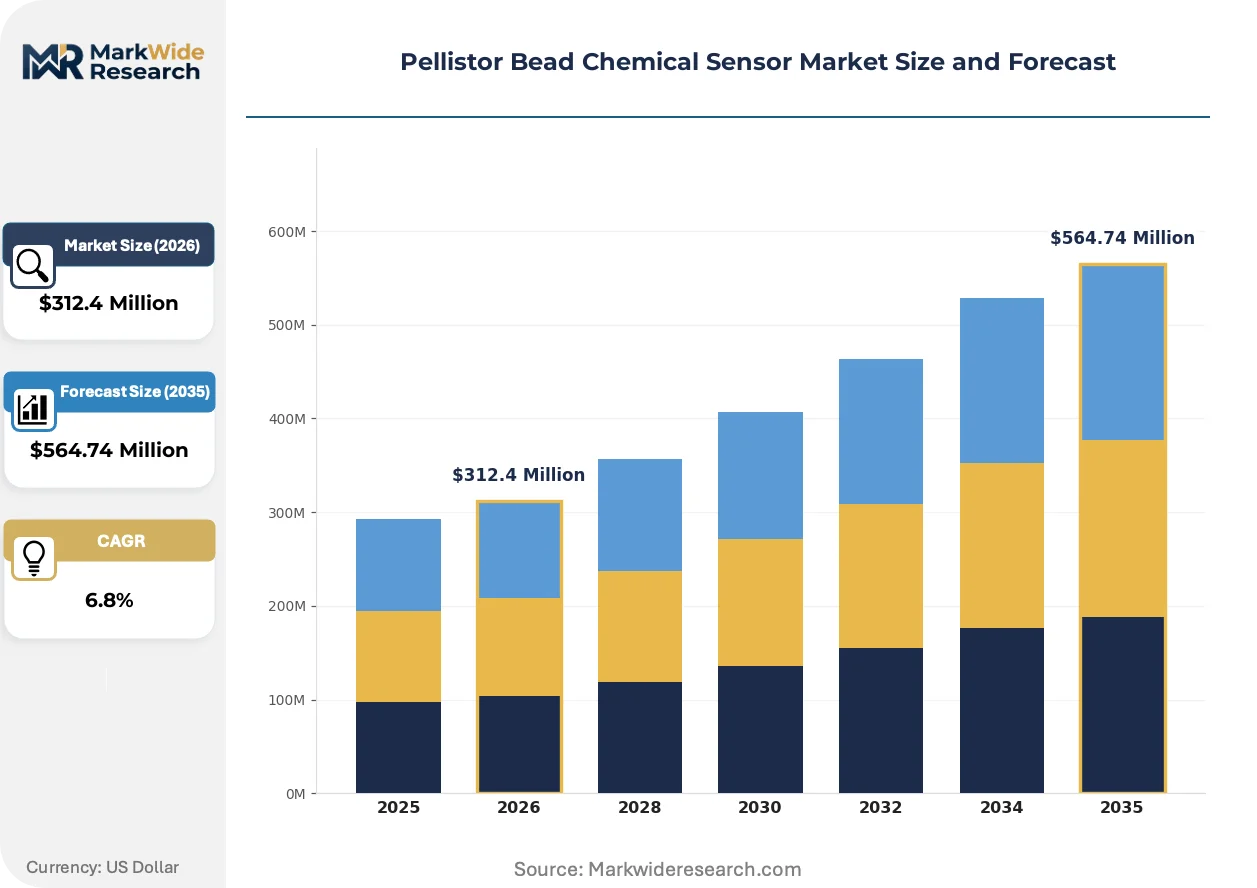
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
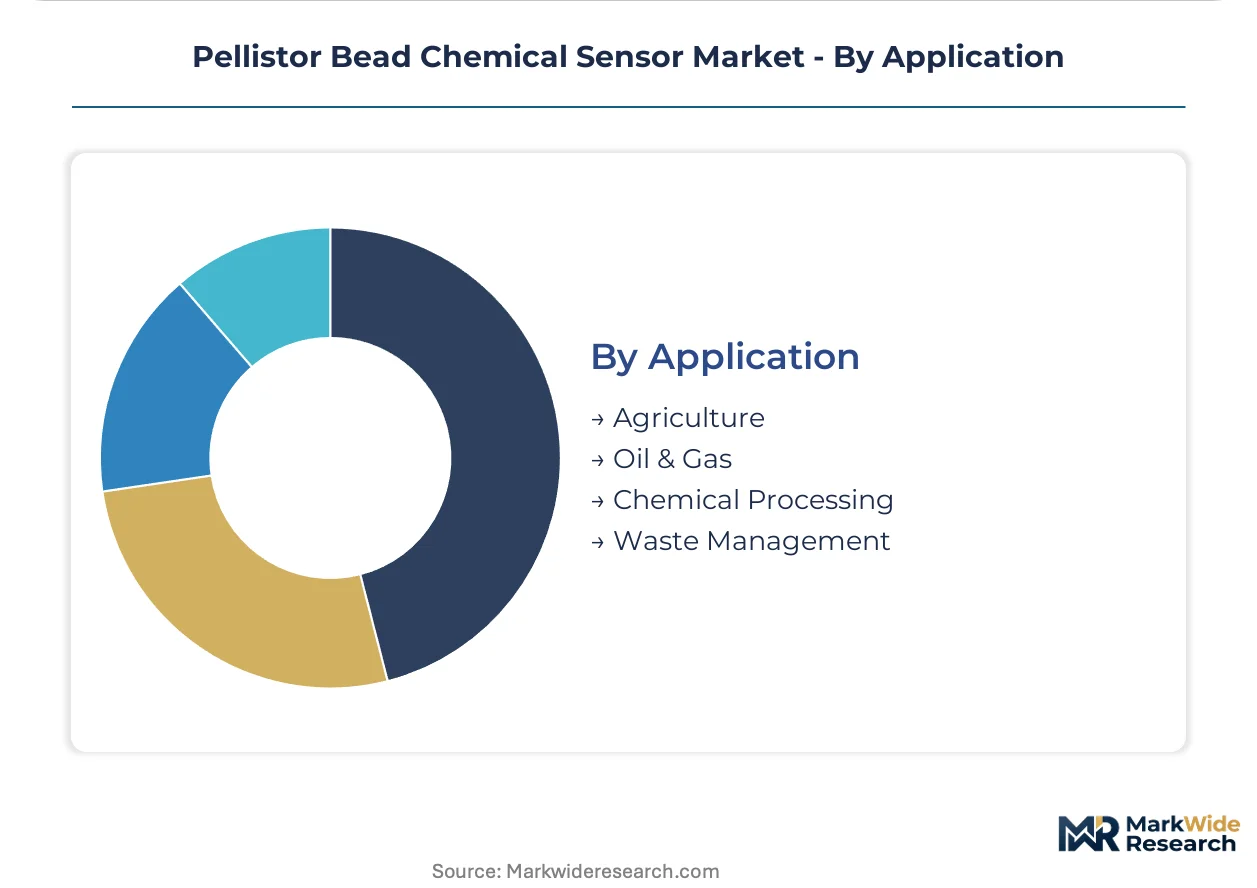
| Segmentation | Product Type: Single Bead, Multi-Bead, Customized Bead, Smart Bead End User: Industrial, Automotive, Healthcare, Environmental Monitoring Technology: Electrochemical, Thermal Conductivity, Optical, Catalytic Application: Agriculture, Oil & Gas, Chemical Processing, Waste Management |
| Companies Covered | Honeywell Analytics, MSA Safety, SICK, AirTest Technologies, Smiths Detection, Pepperl+Fuchs, General Electric, Siemens, Figaro Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pellistor Bead Chemical Sensor Market Evolving Landscape
Sensor architecture is bifurcating between cost-optimized commodity beads for standard combustible detection and premium smart variants with embedded diagnostics. This divergence is compressing mid-tier positioning while rewarding vertical integration into sensing element production.
MEMS-based micro-hotplate pellistor designs are electrifying the miniaturization trajectory for portable and wearable safety equipment. Oilfield services contractors in Texas and Alberta are piloting these reduced-power configurations for personal gas monitors. The shift is compressing form-factor constraints and enabling battery-operated deployments previously impossible with traditional heated-bead architectures.
EPA methane emissions standards are tightening fugitive detection thresholds for upstream oil and gas operations. The rulemaking is forcing sensor sensitivity upgrades across wellhead and compressor station networks. US onshore producers are responding with accelerated replacement cycles for sub-100 ppm detection limits.
Certification-driven procurement now dominates hazardous area equipment selection. European chemical operators prioritize ATEX and IECEx dual-certified beads that reduce inventory complexity. Germany's Ruhr industrial cluster exhibits this pattern most acutely, with integrated energy-chemical sites bundling sensor specifications across maintenance categories.
Pellistor Bead Chemical Sensor Market Segmentation

Pellistor bead architectures diverge sharply between commodity combustible detection and premium smart variants with embedded diagnostics. End-use concentration in hazardous area installations drives specification fragmentation across industrial safety procurement channels. Technology selection hinges on cross-sensitivity tolerance, response time thresholds, and integration legacy in existing control systems.
Product Type:
Volume deployment concentrates in standardized bead configurations for cost-sensitive industrial contracts, while premium smart variants command margin expansion through predictive maintenance capabilities.
- Multi-Bead:Dual-sensor redundancy architectures satisfy offshore platform safety codes and chemical plant explosion protection mandates. Demand clusters in Germany's Ruhr industrial corridor where BASF and Bayer facilities drive replacement cycles for legacy detection networks. OSHA permissible exposure limits in US manufacturing sustain mandatory refresh demand for these configurations.
- Smart Bead:Embedded temperature compensation and drift-correction algorithms enable predictive maintenance contracts that extend customer lifetime value. Japanese sensor specialists are improving selectivity for methane and hydrogen sulfide through catalytic bead innovations. These variants are gaining traction fastest in hydrogen refueling station safety infrastructure.
- Single Bead:Baseline combustible detection for cost-constrained installations in India's unorganized manufacturing sector.
- Customized Bead:Application-specific formulations for specialized hydrocarbon discrimination requirements in petrochemical refining.
Mature deployment sits with Multi-Bead configurations. Newer deployment is concentrated in Smart Bead variants.
End User:
Application risk profiles dictate procurement sophistication, with hazardous area installations demanding certified architectures that filter non-compliant suppliers from tender processes.
- Industrial:Manufacturing facilities and chemical processing plants deploy pellistor networks for combustible gas detection under mandatory safety mandates. REACH compliance is recalibrating cost-of-entry calculus for European manufacturers, forcing reformulation of catalytic bead compositions. Germany's chemical corridor exhibits acute certification-driven procurement patterns.
- Oil & Gas:Upstream operations face EPA methane emissions standards tightening fugitive detection thresholds across wellhead and compressor station networks. US onshore producers are responding with accelerated replacement cycles for sub-100 ppm detection limits. Offshore platforms require multi-bead redundancy per safety codes.
- Automotive:Hydrogen fuel cell vehicle safety systems and battery manufacturing leak detection.
- Healthcare:Anesthetic gas monitoring and laboratory safety applications with stringent calibration requirements.
- Environmental Monitoring:Landfill methane capture mandates in Germany and the Netherlands drive biogas monitoring deployment.
Industrial end-use anchors revenue concentration. Environmental Monitoring is expanding most quickly from regulatory methane capture requirements.
Technology:
Detection principle selection trades sensitivity against selectivity, with catalytic methods dominating flammable gas applications despite cross-sensitivity limitations.
- Catalytic:Platinum-group metal deposition on refractory oxide beads heated to 450–550°C enables combustible gas oxidation with resistance changes proportional to concentration. Palladium price volatility creates input cost pressure compressing margin pools for non-integrated manufacturers. ATEX certification timelines for modified bead chemistries delay product launches by 8–14 months in European markets.
- Electrochemical:Alternative detection for toxic gas species where pellistor cross-sensitivity creates false-positive risks.
- Thermal Conductivity:High-concentration methane detection in biogas processing applications.
- Optical:Infrared alternatives exploiting hydrogen versus hydrocarbon discrimination gaps in standard pellistor designs.
Catalytic technology dominates mature hazardous area installations. Electrochemical methods are gaining share fastest where selectivity requirements exceed pellistor capabilities.
Application:
Sector-specific safety codes and emissions regulations shape sensor specification requirements across divergent operating environments.
- Oil & Gas:Upstream, midstream, and downstream operations command the largest revenue share among end-use segments. EPA methane emissions standards are forcing sensor sensitivity upgrades with accelerated replacement cycles. MEMS-based micro-hotplate designs are electrifying miniaturization for portable safety equipment in Texas and Alberta oilfield services.
- Chemical Processing:ATEX and IECEx dual-certified beads reduce inventory complexity for European operators. ECHA substance restrictions under REACH mandate specific material compositions that filter non-compliant suppliers.
- Waste Management:Landfill methane capture regulations in Germany and the Netherlands drive pellistor deployment for biogas monitoring and leak detection.
- Agriculture:Grain silo combustible dust monitoring and livestock facility ammonia detection.
Oil & Gas applications anchor installed base concentration. Waste Management is climbing the fastest from landfill methane capture mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial corridor tax incentives and Bavarian chemical park status are concentrating European pellistor manufacturing capacity. Special economic zones in Gujarat and Maharashtra attract sensor assembly investments through duty exemptions. China's Yangtze River Delta offers 15% corporate tax reductions for hazardous area equipment producers.
United States
OSHA permissible exposure limits drive mandatory detector replacement cycles across Texas and Louisiana petrochemical corridors. EPA methane emissions standards tighten fugitive detection thresholds for upstream operations. Houston-Galveston-Brazoria metro anchors the largest concentration of oilfield services procurement.
Germany
REACH substance restrictions force catalytic bead reformulations throughout North Rhine-Westphalia chemical facilities. ECHA mandates filter non-compliant vendors from industrial safety tenders. BASF Ludwigshafen and Bayer Leverkusen sites drive replacement demand for legacy detection networks.
China
GB standards alignment with IECEx protocols accelerates domestic certification for hazardous area equipment. MIIT industrial safety modernization programs mandate combustible gas detection in chemical parks. Yangtze River Delta chemical clusters in Jiangsu and Zhejiang provinces dominate sensor procurement volume.
India
Factory Act enforcement expansion and BIS standards alignment open replacement demand for unorganized sector installations. PLI scheme incentives for electronic components attract sensor assembly investments. Gujarat's Dahej and Mundra industrial corridors concentrate petrochemical safety equipment procurement.
Japan
METI hydrogen economy safety codes create first-mover positioning for hydrogen-optimized bead formulations. JIS standards for fuel cell infrastructure mandate specific sensor architectures. Nagoya-Tokyo industrial corridor hosts specialized catalytic bead R&D from domestic sensor specialists.
Pellistor Bead Chemical Sensor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-driven procurement channels. Market structure tilts toward tiered consolidation where ATEX and IECEx dual-certification capabilities filter non-compliant participants. Three archetypes dominate: vertically integrated sensing element producers, channel-controlled safety equipment distributors, and specialized catalytic bead innovators. Competitive moves center on backward integration into platinum-group metal supply chains and predictive maintenance service bundling.
Among diversified industrial conglomerates, Honeywell Analytics and Siemens occupy positions spanning sensing element production through system integration. MSA Safety anchors the channel-controlled archetype with deep presence in North American oilfield services procurement. Japanese specialists Figaro Engineering exemplify the catalytic bead innovation archetype, representing focused R&D investment in selectivity improvements for methane and hydrogen sulfide detection.
| Leading Market Players |
|---|
| Honeywell Analytics |
| MSA Safety |
| SICK |
| AirTest Technologies |
| Smiths Detection |
| Pepperl+Fuchs |
| General Electric |
| Siemens |
| Figaro Engineering |
| Others |
Value Network & Pricing Analysis
Specialized electrochemist concentration in Japan's Nagoya-Tokyo corridor feeds labor-cost differentials that widen pricing spreads between premium smart-bead architectures and commodity combustible detection tiers. Catalytic bead R&D expertise competes with battery and fuel cell sectors, compressing margin pools for manufacturers without captive production of sensing elements.
Pricing Analysis
Short lead-time premiums for ATEX-certified beads command pricing advantages over spot inventory carrying modified chemistries awaiting ECHA approval. Three-tier pricing structure across premium smart variants, standard multi-bead configurations, and economy single-bead units reflects certification grade and volume scale differentiation. Cost compression in economy tiers intensifies from palladium price volatility, while industrial end-users in Germany's chemical corridor show least price sensitivity for predictive maintenance bundling.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for electronic components are reshaping sourcing patterns for sensor assembly investments. Manufacturing concentrates in China, Germany, and Japan, with platinum-group metals drawing from South African and Russian mining operations. Palladium and alumina refractory oxide dependencies create single-source vulnerability for non-integrated producers. Distribution runs through channel-controlled safety equipment distributors with deep presence in oilfield services procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pellistor bead market sits in a technology-transition phase where MEMS-based micro-hotplate designs are displacing traditional heated-bead architectures for portable applications.
For Market Incumbents: Deepen backward integration into platinum-group metal supply chains to buffer palladium price volatility compressing margin pools. Expand capacity in Gujarat's Dahej industrial corridor to capture India's Factory Act enforcement expansion. Prioritize hydrogen-optimized bead formulations before METI safety codes solidify first-mover positions. For New Entrants and Emerging Players: The price-point gap between premium smart-bead predictive maintenance bundles and economy single-bead commoditized units offers white-space targeting. India's unorganized manufacturing sector presents the most penetrable geography for cost-optimized configurations. Enter through BIS standards alignment partnerships with domestic distributors lacking ATEX certification capabilities. For Investors and Strategic Acquirers: The window for entry favors vertically integrated sensing element producers with captive catalytic bead R&D. Long-term viability hinges on hydrogen economy safety infrastructure buildout across Germany and Japan. Watch for EPA methane emissions threshold tightening as the inflection signal accelerating replacement cycles for sub-100 ppm detection limits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Platinum-Group Metals | Captive palladium supply buffers commodity volatility for Honeywell Analytics and Siemens margin structures. |
| Hydrogen-Optimized Bead Formulation Development | METI safety codes in Japan create first-mover positioning for Figaro Engineering selectivity improvements. |
| Predictive Maintenance Service Bundling | Smart-bead self-diagnostic algorithms extend customer lifetime value for MSA Safety channel control. |
| MEMS Micro-Hotplate Manufacturing Scale-Up | Reduced-power configurations enable battery-operated deployments for Texas oilfield services contractors. |
| ATEX/IECEx Dual-Certification Investment | Dual-certified beads reduce inventory complexity for BASF and Bayer facilities in Germany's Ruhr corridor. |
Research Methodology
Trade databases, ECHA substance restriction filings, and SEC 10-K disclosures from diversified industrial conglomerates formed the secondary backbone. Primary interviews with plant managers at BASF Ludwigshafen and Bayer Leverkusen, procurement leads at Texas oilfield services contractors, and technical R&D directors from Japanese sensor specialists combined with secondary validation. Bottom-up and top-down triangulation anchored market sizing across catalytic bead architectures and end-use segments.
Bottom-up unit economics modeled bead production costs, platinum-group metal inputs, and certification timelines against top-down industrial safety equipment spending patterns. Segmentation dimensions included product type, end-user industry, technology principle, and application sector across the projection horizon. CAGRs derived from replacement cycle analysis under OSHA and EPA regulatory frameworks, with hydrogen economy infrastructure buildout and landfill methane capture mandates as industry-specific forecast inputs.
Inputs from ATEX certification bodies and MIIT industrial safety programs were available through the study window; gaps in real-time palladium spot pricing granularity introduce uncertainty bands around margin compression scenarios. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Bitumen and Asphalt Testing Services Market
Testing Equipment
Paint Tester Market
Testing Equipment
Chemical Detection Equipment Market
Testing Equipment
Material Testing Market
Testing Equipment
HPLC Market
Testing Equipment
Global Lab Automation in Analytical Chemistry Market
Testing Equipment
Laboratory Filtration Equipment and Supplies Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Rheology Controller Market
Testing Equipment
Gas Calorimeter Market
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
Chemical Testing Services Market