
 Europe Non-Destructive Testing Market | 2026-2036
Europe Non-Destructive Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Non-Destructive Testing Market Foresight
The EU Green Deal is broadening the addressable market for non-destructive testing across carbon-intensive manufacturing sectors. Bureau Veritas SA leverages its pan-European laboratory network to capture recurring inspection contracts from energy transition assets. DEKRA SE anchors its growth in automotive battery plant certifications, where weld integrity protocols are tightening. TÜV Rheinland AG competes through specialized electromagnetic testing capabilities for offshore wind installations.
Non-destructive testing encompasses inspection methodologies that evaluate material properties, component integrity, and structural performance without impairing future usefulness, employing ultrasonic pulse-echo systems with frequency ranges from 0.5 to 25 MHz to detect subsurface discontinuities in metals and composites. Its primary industrial purpose centers on preventing catastrophic failure in safety-critical infrastructure while minimizing operational downtime. Ultrasonic testing leads the product type landscape due to its portability and sensitivity to planar defects in thick-section welds. The oil and gas end user segment sustains premium pricing for radiographic testing services in pipeline integrity management, though aerospace quality control applications are expanding fastest as OEMs internalize more inspection capacity.
EMA's Medical Device Regulation and the EU AI Act are converging to mandate validated NDT data integrity for implantable device manufacturing, while REACH compliance pressures chemical processors to adopt non-invasive corrosion monitoring. The F-Gas Regulation is simultaneously redirecting refrigerant system inspection budgets toward leak detection technologies. Stakeholders must monitor how CSRD disclosure requirements expand third-party verification mandates across EU manufacturing supply chains.
Market Dynamics
EU Green Deal carbon border adjustments are forcing steel and chemical producers toward continuous in-service material verification, compressing inspection cycles from annual to quarterly frequencies across the continent's heavy manufacturing belt.
Growth Catalysts
- REACH compliance pressures:Chemical processors across the Rhine-Ruhr corridor now deploy ultrasonic corrosion monitoring to avoid invasive sampling that triggers regulatory scrutiny. Non-invasive testing preserves operational permits while satisfying ECHA documentation requirements.
- France and Germany:Aerospace OEMs internalize radiographic and phased-array ultrasonic capacity for airframe inspection cycles, building captive NDT laboratories rather than outsourcing to service bureaus. This insourcing wave expands equipment procurement budgets.
- Offshore wind installation protocols:North Sea lease operators mandate electromagnetic acoustic testing for subsea weld integrity, creating recurring revenue streams for specialized service providers. Tightening certification standards from Germanischer Lloyd drive testing frequency upward.
Market Restraints
- Qualified technician scarcity:Germany's industrial corridor faces acute shortages of EN 473-certified ultrasonic inspectors, constraining service capacity expansion despite equipment availability. Training pipelines lag replacement demand by 18-24 months.
- Isotope supply concentration:Radiographic testing depends on cobalt-60 and iridium-192 sources controlled by a handful of Eastern European suppliers, exposing inspection schedules to geopolitical disruption risks and price volatility.
- Equipment import dependency:High-frequency phased-array systems rely on specialized piezoelectric transducers manufactured primarily in East Asia, creating lead time vulnerabilities for European service providers.
Strategic Opportunities
- Poland and Czech Republic:Automotive battery plant construction outpaces local NDT service infrastructure, opening territory for mobile inspection units and training partnerships with technical universities in Wrocław and Brno.
- CSRD disclosure mandates:Supply chain verification requirements expand third-party inspection contracts as manufacturers document material integrity for Scope 3 carbon reporting. Auditors now require NDT-backed traceability.
- Digital radiography convergence:Real-time imaging systems merge with cloud-based defect classification algorithms, enabling remote interpretation services that decouple expert labor from physical inspection sites.
Industry Challenges
- EN ISO 9712 recertification timelines:Method-specific inspector qualifications expire on staggered schedules, forcing operators to maintain redundant certification programs or risk service interruptions during renewal windows.
- Legacy film radiography integration:Analog archive systems resist digitization, complicating compliance with EU AI Act data integrity standards for implantable device manufacturing traceability.
- Cross-border equipment calibration:National metrology institutes apply divergent uncertainty budgets to ultrasonic reference blocks, creating friction for service providers operating across Benelux and German borders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Non-Destructive Testing Market |
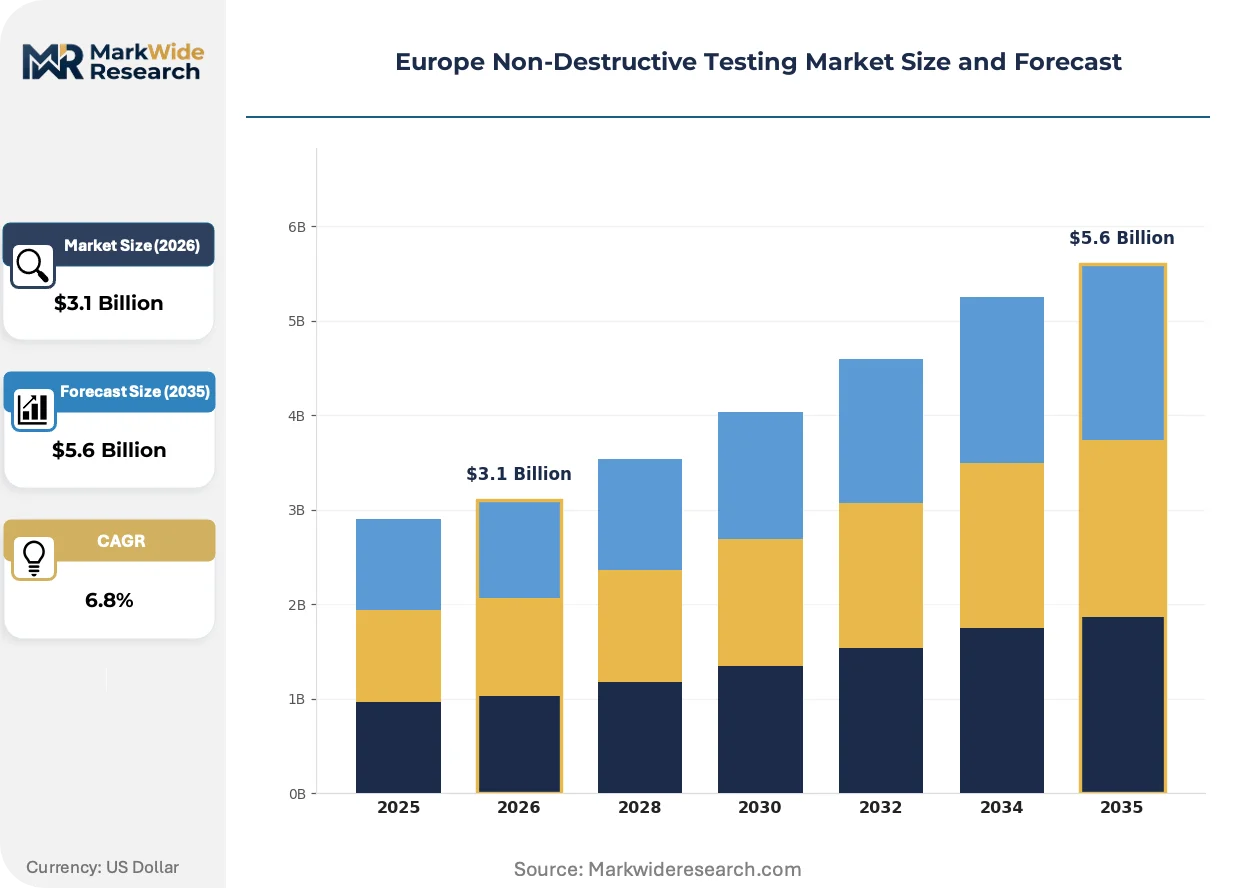
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Testing, Radiographic Testing, Magnetic Particle Testing, Liquid Penetrant Testing End User: Aerospace, Construction, Manufacturing, Oil & Gas Technology: Electromagnetic, Laser, Infrared, Vibration Application: Quality Control, Structural Integrity, Process Monitoring, Maintenance |
| Companies Covered | General Electric Company, Ashtead Group plc, Intertek Group plc, TÜV Rheinland AG, MISTRAS Group, Bureau Veritas SA, Olympus Corporation, DEKRA SE, Applus Services SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Non-Destructive Testing Market Shifts & Advancements
Computational advances in signal processing and embedded sensor networks are compressing defect detection thresholds while expanding the addressable inspection surface area across European manufacturing assets.
Phased-array ultrasonic testing is converging with machine learning-based defect classification to enable real-time weld quality assessment during automated production cycles. Automotive battery manufacturers in Stuttgart and Munich deploy these integrated systems for laser-welded cell tab connections. The technology is converging with predictive maintenance platforms to shift inspection from scheduled intervals to condition-based triggers.
EU AI Act validation requirements are mandating algorithmic transparency for automated NDT decision systems used in medical device manufacturing. EMA's Medical Device Regulation simultaneously tightens data integrity standards for implantable component traceability. German and Swiss precision manufacturers now invest in explainable AI architectures to satisfy dual regulatory scrutiny from notified bodies.
After-sales service unbundling separates hardware ownership from inspection labor across the European oil and gas sector. Pipeline operators in Rotterdam and Antwerp now lease radiographic crawler units while contracting interpretation services on per-image pricing. Dutch and Belgian infrastructure managers lead this consumption-pattern shift, compressing capital deployment timelines for integrity management programs.
Europe Non-Destructive Testing Market Segmentation
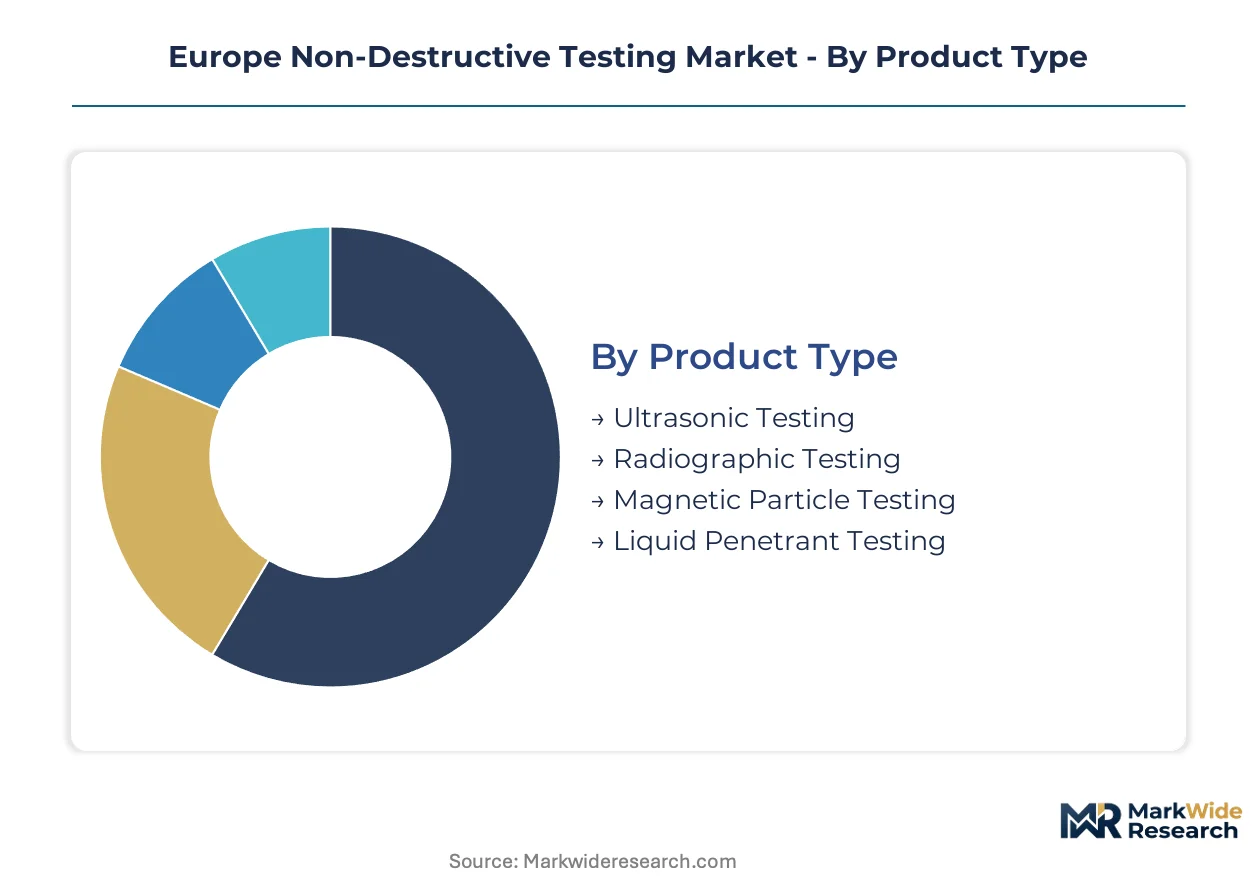
Segmentation in the Europe Non-Destructive Testing Market reveals how inspection methodologies align with distinct buyer priorities across safety-critical industries. Procurement decisions diverge sharply between sectors prioritizing defect sensitivity versus those demanding rapid throughput or regulatory documentation compliance.
Product Type:
Equipment selection hinges on defect geometry, material thickness, and access constraints rather than cost alone.
- Ultrasonic Testing:Phased-array systems with 0.5–25 MHz transducers detect planar defects in thick-section welds without surface preparation. German automotive OEMs and North Sea wind operators deploy portable units for in-field inspection of turbine tower welds and battery cell tab connections.
- Radiographic Testing:Gamma-ray and X-ray systems image volumetric discontinuities in castings and pipeline girth welds. Rotterdam and Antwerp pipeline operators sustain premium service pricing for crawler-based radiography in hydrocarbon infrastructure integrity management.
- Magnetic Particle Testing:Surface-breaking defect detection for ferromagnetic components in rail and heavy machinery manufacturing.
- Liquid Penetrant Testing:Cost-effective surface crack identification for aerospace castings and maintenance operations across France's industrial corridor.
Ultrasonic Testing leads on scale; Radiographic Testing leads on momentum in carbon-intensive sectors facing EU Green Deal verification mandates.
End User:
Industry-specific certification requirements and failure-cost profiles determine method adoption and service frequency.
- Aerospace:EASA and OEM specifications mandate phased-array ultrasonic and digital radiography for airframe and engine component traceability. French and German manufacturers internalize captive NDT laboratories to compress inspection cycles and protect proprietary process data.
- Oil & Gas:Pipeline integrity management drives recurring radiographic and ultrasonic corrosion mapping contracts. North Sea lease operators face tightening Germanischer Lloyd certification standards for subsea weld verification.
- Manufacturing:Automotive battery plants in Stuttgart and Munich adopt real-time laser weld inspection for cell tab connections.
- Construction:Structural steel verification and concrete integrity assessment for major infrastructure projects across the Rhine-Ruhr corridor.
Aerospace dominates absolute expenditure; Oil & Gas shows steepest expansion trajectory as carbon border adjustments compress inspection intervals.
Technology:
Underlying physics determines suitability for specific defect types, environmental conditions, and automation integration.
- Electromagnetic:Eddy current and alternating current field measurement systems excel at detecting surface and near-surface cracks in conductive materials. Offshore wind installation protocols now mandate electromagnetic acoustic testing for subsea pipeline and monopile weld integrity across North Sea lease blocks.
- Laser:Shearography and laser ultrasonics enable non-contact inspection of complex geometries and high-temperature components. Stuttgart automotive suppliers deploy laser-based systems for automated quality control of battery housing welds.
- Infrared:Thermographic detection of delaminations, moisture ingress, and thermal pattern anomalies in composites and building envelopes.
- Vibration:Structural health monitoring through modal analysis and acoustic emission for rotating machinery and civil infrastructure.
Electromagnetic methods anchor current revenue; Laser technology is climbing fastest as battery manufacturing automation intensifies.
Application:
Use-case positioning shifts inspection from reactive defect detection toward predictive and integrated quality systems.
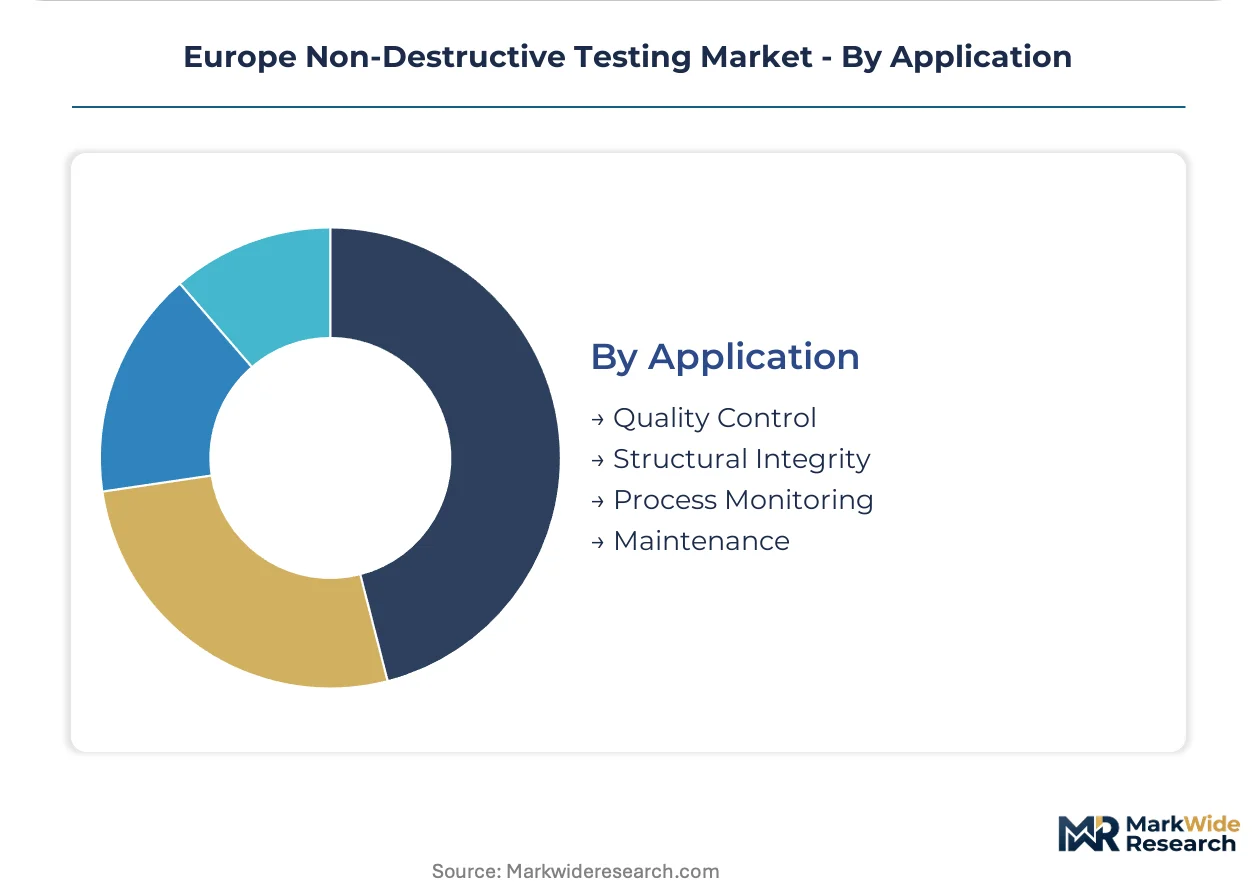
- Quality Control:In-line inspection during manufacturing prevents downstream failure costs. EMA's Medical Device Regulation and EU AI Act convergence now mandates validated NDT data integrity for implantable device manufacturing, forcing Swiss and German precision manufacturers to upgrade traceability systems.
- Maintenance:Condition-based inspection triggers replace fixed schedules in predictive maintenance platforms. REACH compliance pressures chemical processors across the Rhine-Ruhr corridor toward ultrasonic corrosion monitoring to avoid invasive sampling.
- Structural Integrity:Lifecycle assessment of bridges, pressure vessels, and wind turbine foundations under EU Green Deal verification requirements.
- Process Monitoring:Real-time feedback for automated welding and additive manufacturing processes in automotive battery production.
Quality Control commands the largest installed base; Maintenance is gaining share fastest as CSRD disclosure mandates expand third-party verification contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EN 473-certified technicians concentrate in Germany's industrial corridor, creating service capacity bottlenecks that radiate across neighboring markets. France and the United Kingdom maintain specialized aerospace inspector pools. Poland and Czech Republic face acute training pipeline gaps as battery plant construction accelerates.
Germany
Automotive OEMs in Stuttgart and Munich internalize phased-array ultrasonic capacity for battery weld inspection. The EU AI Act mandates validated data integrity protocols for manufacturing traceability. North Rhine-Westphalia's chemical processors deploy continuous corrosion monitoring to satisfy REACH documentation requirements without invasive sampling.
France
EASA specifications drive airframe inspection cycle compression at Toulouse and Bordeaux aerospace clusters. The EU Green Deal's carbon border adjustments force steel producers in Lorraine toward quarterly material verification frequencies. Île-de-France hosts Europe's densest concentration of digital radiography service bureaus serving medical device manufacturers.
United Kingdom
North Sea oil and gas operators face tightening Germanischer Lloyd certification standards for subsea weld integrity. The CSRD expands third-party verification mandates for supply chain carbon disclosure. Aberdeen and Liverpool maintain specialized electromagnetic testing capacity for offshore pipeline infrastructure.
Netherlands
Rotterdam and Antwerp pipeline operators pioneer after-sales service unbundling, leasing radiographic crawler units while contracting interpretation separately. The F-Gas Regulation redirects refrigerant system inspection budgets toward leak detection technologies. Dutch infrastructure managers lead consumption-pattern shifts in integrity management procurement.
Poland
Automotive battery plant construction in Wrocław and Poznań outpaces local NDT service infrastructure. ECHA compliance pressures create demand for non-invasive testing to preserve operational permits. Technical universities in Kraków and Wrocław partner with mobile inspection units to address technician certification gaps.
Europe Non-Destructive Testing Market Competitive Landscape
Capital-heavy equipment manufacturers compete with asset-light inspection service providers across divergent margin structures. The vendor base stratifies between integrated technology suppliers and specialized testing bureaus. Three archetypes dominate: diversified industrial conglomerates with captive NDT divisions, pan-European certification houses with laboratory networks, and regional specialists in single modalities. Competitive moves center on geographic expansion through training partnerships and technology licensing arrangements that decouple hardware from labor revenue.
Among diversified industrial conglomerates, General Electric Company and Olympus Corporation occupy positions spanning equipment manufacture through service provision. TÜV Rheinland AG exemplifies the pan-European certification house archetype, anchoring specialized capabilities in electromagnetic testing for offshore installations. DEKRA SE sits within the automotive-focused tier, leveraging battery plant certification relationships across German manufacturing corridors.
| Leading Market Players |
|---|
| General Electric Company |
| Ashtead Group plc |
| Intertek Group plc |
| TÜV Rheinland AG |
| MISTRAS Group |
| Bureau Veritas SA |
| Olympus Corporation |
| DEKRA SE |
| Applus Services SA |
| Others |
Supply & Pricing Matrix
Pan-European certification houses with sovereign-backed laboratory networks anchor supply discipline through long-term equipment leasing arrangements, compressing price competition in radiographic testing while fragmenting margins for mobile ultrasonic service providers.
Pricing Analysis
Bundled equipment-and-interpretation contracts dominate aerospace and oil and gas procurement, while unbundled per-image pricing gains traction in Dutch and Belgian pipeline integrity management. Three-tier pricing structure across premium, standard, and economy levels separates EN 473 Level 3-certified interpretation from automated screening and basic flaw detection. Cost compression in economy-tier ultrasonic services is intensifying because Polish battery plant construction outpaces technician supply. Automotive OEMs in Stuttgart and Munich show least price sensitivity for real-time phased-array integration, while construction contractors in the Rhine-Ruhr corridor negotiate aggressively on radiographic crawler rates.
Supply Chain Analysis
Dual-sourcing requirements from Germanischer Lloyd and EASA force North Sea operators and aerospace OEMs to qualify multiple electromagnetic testing equipment vendors, diluting single-source pricing power despite concentrated manufacturing. High-frequency piezoelectric transducers draw from Japanese and South Korean component specialists, while cobalt-60 and iridium-192 isotope supply rests on Eastern European enrichment facilities. Single-source vulnerability in isotope logistics exposes inspection schedules to geopolitical disruption. Distribution runs through pan-European certification networks with regional service hubs in Germany, France, and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Non-Destructive Testing Market operates as a stable compounder where regulatory inspection mandates under EU Green Deal and CSRD create recurring revenue visibility across carbon-intensive manufacturing.
For Market Incumbents: Extend captive laboratory capacity in automotive battery corridors to preempt insourcing trends by OEMs. Deepen electromagnetic testing capabilities for offshore wind as Germanischer Lloyd tightens subsea weld certification. Vertical integration into phased-array transducer manufacturing reduces East Asian supply dependency. For New Entrants and Emerging Players: The gap between premium EN 473 Level 3 interpretation and economy-tier automated screening offers entry points for mobile inspection units in Poland and Czech Republic. Target automotive battery plant construction in Wrocław and Poznań where local service infrastructure lags demand. Partner with technical universities in Kraków and Brno to compress technician certification timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among regional ultrasonic specialists without offshore wind or medical device certification exposure. Five-to-ten-year viability hinges on regulatory inspection frequency expansion rather than cyclical capital spending. Watch CSRD Scope 3 disclosure enforcement as the inflection signal for third-party verification contract growth.| Strategic Initiative | Industry Significance |
|---|---|
| Training Partnership Expansion | Technical universities in Wrocław and Brno address Germany's EN 473 technician shortage. |
| Electromagnetic Capability Buildout | Specialized testing for North Sea offshore wind installations meets Germanischer Lloyd mandates. |
| Digital Radiography Platform Integration | Cloud-based defect classification enables remote interpretation decoupled from physical sites. |
| Automotive Battery Plant Certification | Real-time laser weld inspection captures Stuttgart and Munich OEM internalization budgets. |
| CSRD Verification Service Launch | Third-party material integrity documentation supports manufacturer Scope 3 carbon reporting. |
Research Methodology
Direct dialogue with NDT service bureau operators, EN 473 certification body administrators, automotive quality control directors, and offshore wind project engineers grounded qualitative assessments in operational reality. Secondary validation drew from ECHA REACH documentation databases, Germanischer Lloyd certification standards, EU Green Deal implementation timelines, and customs records of piezoelectric transducer imports. Bottom-up equipment procurement tracking and top-down inspection service revenue estimates were triangulated against regulatory mandate expansion schedules.
Segmented outputs across product type, end user, technology, and application dimensions were modeled over the projection horizon. CAGRs were derived from inspection frequency compression rates under carbon border adjustments and battery plant construction pipelines. Forecast inputs incorporated EN ISO 9712 recertification cycle impacts and phased-array automation adoption curves in automotive manufacturing.
The model assumes a particular technology adoption path; alternative pathways for laser-based shearography would alter the outlook if battery weld inspection standards shift toward non-contact methods. Deviation in EU AI Act validation timelines for automated defect classification would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Lab Automation in Analytical Chemistry Market
Testing Equipment
Nitrogen Tester Market
Testing Equipment
Flammability Tester Market
Testing Equipment
Total Reflection X Ray Fluorescence (TXRF) Spectrometer Market
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Combustion Testing Equipment Market
Testing Equipment
Global Trace Metal Analysis Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
Stack Emissions Real-Time Speciation and Compliance Test Systems Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Heavy Metal Testing Market
Testing Equipment
Electrical Testing Equipment Market
Testing Equipment
Digital Shore Durometer Market