
 Chemical Detector Market | 2026-2036
Chemical Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Detector Market Outlook
The EU Green Deal's industrial emissions monitoring mandate is expanding compliance obligations across European chemical processing facilities. Honeywell International Inc. leverages its distributed sensor architecture to anchor large-scale plant safety contracts in refining and petrochemical complexes. Bruker specializes in high-resolution mass spectrometry detection for defense and homeland security applications. Thermo Fisher Scientific Inc. dominates laboratory-grade analytical detection with deep integration into environmental monitoring networks.
A chemical detector is an instrument engineered to identify, quantify, or alarm against the presence of hazardous chemical substances through sensitivity thresholds measured in parts per million or parts per billion, serving critical functions in industrial safety, environmental protection, and national security operations. Portable detectors command premium pricing in defense and emergency response channels where field-deployable rapid identification determines operational outcomes. Electrochemical technology sustains cost leadership in industrial gas monitoring, while infrared and photoionization segments capture higher margins in specialized leak detection and air quality testing applications across manufacturing and environmental monitoring end users.
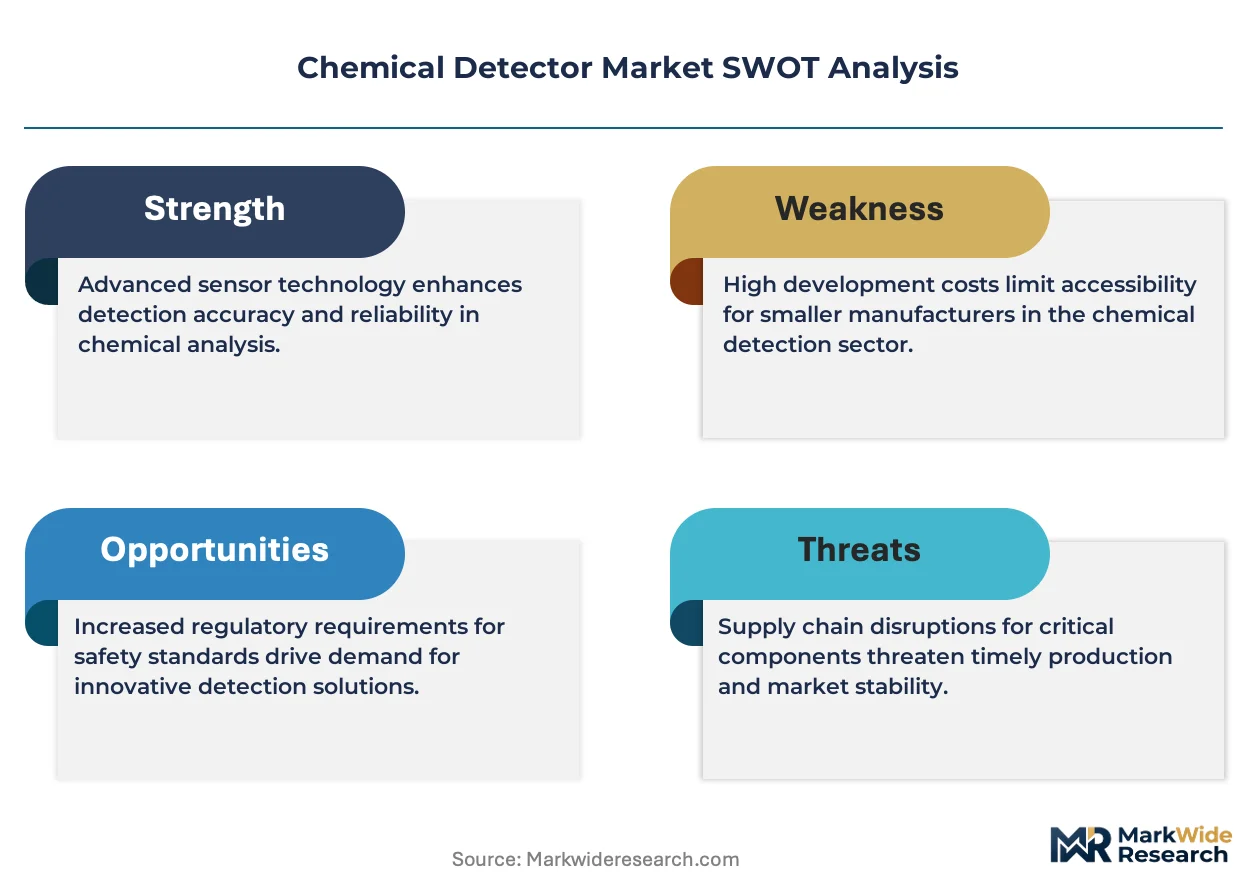
EPA enforcement of Clean Air Act amendments tightens permissible exposure limits, forcing manufacturing facilities to upgrade fixed detector networks or face operational penalties. REACH and OSHA process safety management standards collectively shape product certification requirements and procurement specifications across North American and European industrial buyers. Stakeholders must weigh sensor miniaturization investments against the durability demands of hazardous material detection deployments in extreme environments.
Market Dynamics
Defense procurement programs across NATO member states are expanding adoption of portable detection systems, while tightening REACH compliance in Europe accelerates replacement cycles for legacy industrial monitors. This dual-pressure environment concentrates demand in Germany's chemical manufacturing corridor along the Rhine.
Growth Catalysts
- EU Green Deal industrial emissions mandate:The mandate expands compliance obligations across European chemical processing facilities, forcing facility upgrades and new detector installations.
- Electrochemical sensor miniaturization:Advances in electrochemical technology enable field-deployable rapid identification capabilities that determine operational outcomes in defense and emergency response channels.
- Rhine chemical manufacturing corridor concentration:Germany's dense cluster of petrochemical and specialty chemical production sustains concentrated demand for fixed and portable detection infrastructure.
Market Restraints
- Precious metal input volatility:Platinum and palladium price swings in electrochemical sensor electrodes compress margin predictability for manufacturers serving industrial gas monitoring segments.
- Single-source infrared component dependence:German and Japanese suppliers dominate photonics components for infrared detection systems, creating geographic concentration risk in specialized leak detection supply chains.
- REACH substance restriction friction:ECHA's candidate list expansions for restricted substances complicate material selection in sensor housings and membrane materials, extending product development timelines.
Strategic Opportunities
- India petrochemical capacity expansion:Reliance Industries and Indian Oil Corporation are building world-scale refining and chemical complexes that lack mature fixed detector networks, creating greenfield installation demand.
- Photoionization-infrared convergence:Hybrid architectures combining PID sensitivity with IR selectivity are capturing higher margins in air quality testing applications across semiconductor fabrication facilities.
- EPA Clean Air Act enforcement tightening:Permissible exposure limit reductions are forcing manufacturing facilities to upgrade fixed detector networks or face operational penalties, accelerating replacement demand.
Industry Challenges
- Cross-disciplinary calibration expertise scarcity:Technicians must integrate electrochemistry, spectroscopy, and embedded systems knowledge to maintain multi-technology detector fleets, constraining service capacity expansion.
- ATEX/IECEx certification timeline compression:Hazardous area equipment approvals for European and international markets require 12-18 month validation cycles that lag product development velocity.
- Legacy 4-20mA integration complexity:Plant safety systems built on analog signal architectures resist digital retrofitting, forcing parallel maintenance of obsolete and modern detector networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Detector Market |
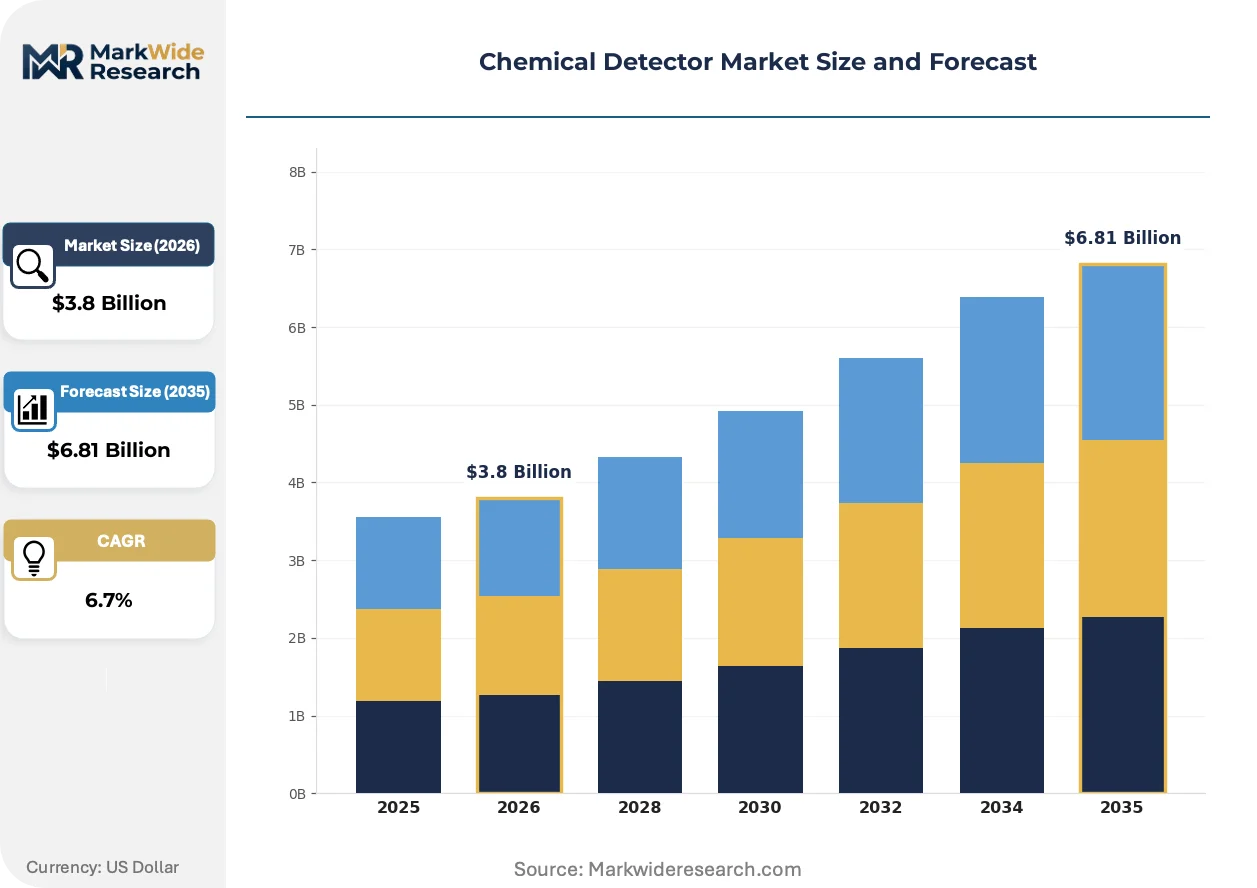
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Multi-Gas Detectors, Single-Gas Detectors Technology: Electrochemical, Infrared, Laser, Photoionization End User: Manufacturing, Environmental Monitoring, Government, Defense Application: Hazardous Material Detection, Safety Monitoring, Air Quality Testing, Leak Detection |
| Companies Covered | Thermo Fisher Scientific Inc., Honeywell International Inc., Bruker, Smiths Detection Group Ltd., FLIR Systems, Inc., MSA, Agilent Technologies, Inc., Emerson Electric Co., Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Detector Market Strategic Shifts
Sensor architecture convergence and regulatory enforcement intensification are compressing product lifecycles while expanding performance requirements. Detection systems must now deliver laboratory-grade analytical precision in field-deployable form factors.
Artificial intelligence-driven spectral analysis is rewriting threat identification protocols. Machine learning algorithms trained on mass spectrometry libraries enable real-time compound classification without human spectroscopist interpretation. Defense and homeland security agencies in the United States and United Kingdom are accelerating procurement of AI-embedded portable units. This capability compression is collapsing the traditional separation between field screening and laboratory confirmation, forcing incumbents to acquire or develop algorithmic competencies.
REACH authorization list expansions are tightening substance restrictions across European manufacturing supply chains. ECHA's rolling updates to SVHC classifications force reformulation of sensor membranes, electrolytes, and housing materials on 24-36 month cycles. Industrial gas monitor suppliers serving German and French chemical processors face the steepest compliance velocity, with product re-registration costs now embedded in annual operating budgets.
Defense agencies are unbundling detector procurement from integrated platform contracts. Separate acquisition of chemical detection modules for vehicles, drones, and dismounted personnel is fragmenting historically concentrated buying power. This disaggregation is most visible in NATO member state tendering, where national defense procurement offices now issue standalone detector solicitations distinct from armored vehicle or CBRN platform awards. Component suppliers gain direct channel access previously blocked by systems integrators.
Chemical Detector Market Segmentation
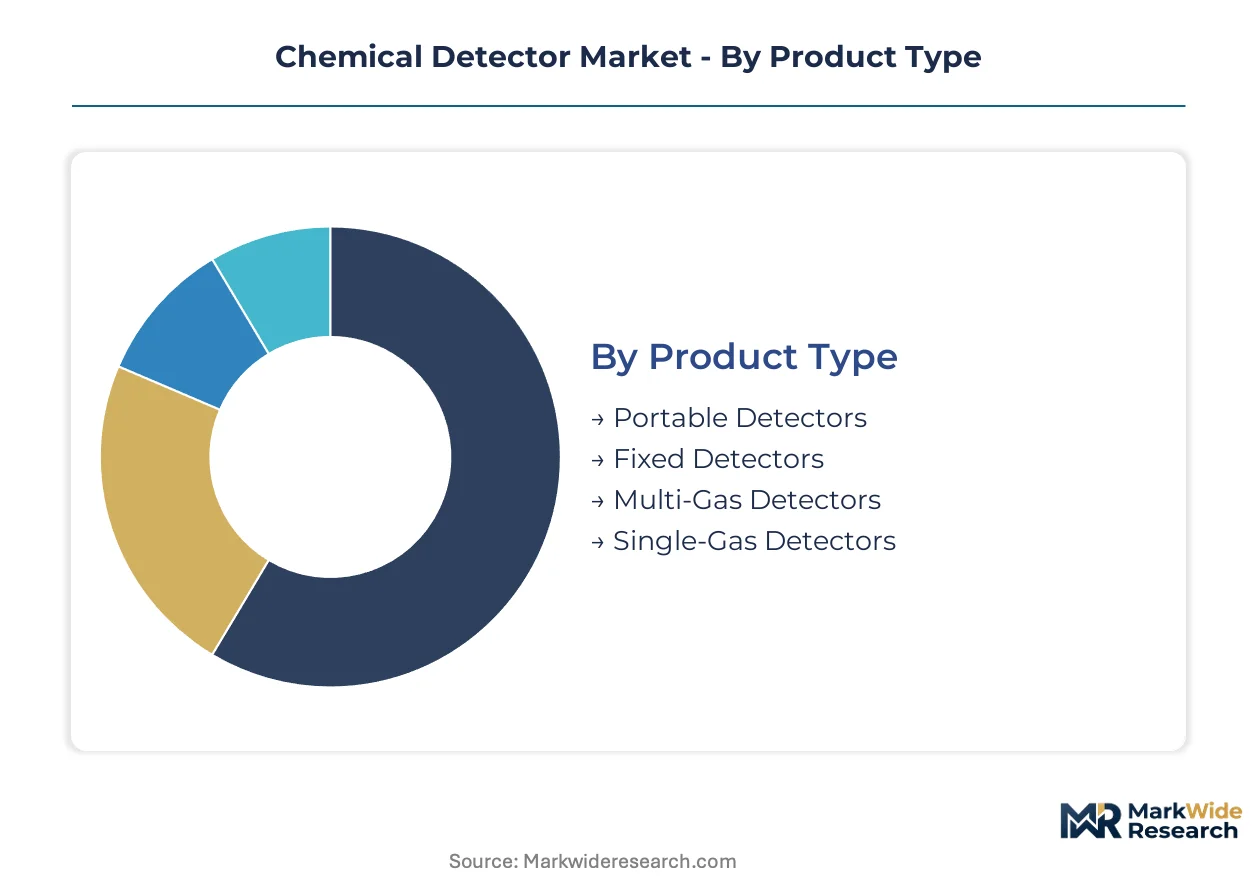
Segmentation in chemical detection reflects divergent engineering trade-offs between field mobility and analytical precision. Procurement patterns split between integrated plant safety systems requiring permanent installation and rapid-response units demanding battery-powered portability. Understanding these structural divisions clarifies where technology investments concentrate and which sensor architectures capture premium pricing.
Product Type:
Standalone portable units dominate defense and emergency response procurement, while fixed installations anchor industrial compliance infrastructure. Embedded multi-sensor networks are displacing single-point detectors in large-scale manufacturing complexes.
- Portable Detectors:Battery-operated units weighing under 2 kilograms integrate electrochemical and photoionization sensors for field-deployable threat identification. NATO defense procurement programs across Germany, France, and the United Kingdom are expanding orders for dismounted personnel and vehicle-mounted applications where rapid compound classification determines operational safety.
- Fixed Detectors:Permanently installed sensor arrays connect to plant distributed control systems through 4-20mA or digital Ethernet protocols. Germany's Rhine chemical manufacturing corridor sustains concentrated demand for these units as REACH compliance deadlines force replacement of legacy analog monitoring networks in petrochemical and specialty chemical facilities.
- Multi-Gas Detectors:Simultaneous monitoring of four to six target compounds reduces sensor headcount in complex process environments.
- Single-Gas Detectors:Dedicated hydrogen sulfide or carbon monoxide units serve confined space entry protocols in municipal wastewater and oilfield operations.
Fixed detectors lead volumes today; portable detectors are gaining share fastest.
Technology:
Cost structures stratify sharply between mature electrochemical platforms and precision photonics systems. Margin concentration follows selectivity requirements, with regulatory enforcement tightening permissible detection thresholds across industrial applications.
- Electrochemical:Amperometric cells using platinum or palladium catalyst electrodes deliver parts-per-million sensitivity at sub-$500 unit costs. Industrial gas monitoring in manufacturing facilities across the United States and Germany relies on this technology for compliance with OSHA process safety management and EPA Clean Air Act exposure limits.
- Infrared:Non-dispersive and tunable diode laser absorption spectroscopy achieve parts-per-billion selectivity for specific molecular bonds. Leak detection applications in semiconductor fabrication facilities and LNG terminals command premium pricing where false-positive tolerance approaches zero.
- Laser:Cavity ring-down and quantum cascade architectures enable standoff detection at hundred-meter ranges for perimeter security.
- Photoionization:Ultraviolet lamp ionization of volatile organic compounds provides broadband detection with minimal calibration drift in environmental monitoring deployments.
Electrochemical platforms anchor volume production; infrared systems capture the steepest margin expansion.
End User:
Procurement authority fragments across operational safety managers, regulatory compliance officers, and defense acquisition offices with divergent performance specifications and budget cycles.
- Manufacturing:Petrochemical, pharmaceutical, and specialty chemical producers operate the largest installed base of fixed detection infrastructure. German chemical processors along the Rhine and Gulf Coast refineries in the United States are accelerating replacement cycles as EU Green Deal emissions mandates and EPA enforcement actions tighten permissible exposure limits.
- Environmental Monitoring:Government laboratories and contracted analytical services deploy laboratory-grade mass spectrometry and chromatography systems. Thermo Fisher Scientific's integration into United States and European environmental networks sustains demand for high-precision reference instrumentation.
- Government:Homeland security and customs agencies procure portable units for border screening and critical infrastructure protection.
- Defense:CBRN reconnaissance units require ruggedized detectors certified to MIL-STD-810 for temperature, shock, and electromagnetic interference.
Manufacturing dominates current procurement volumes; defense channels show the most aggressive expansion trajectory.
Application:
Use-case specificity determines sensor configuration, with life-safety applications demanding redundant architectures and environmental testing prioritizing analytical traceability.
- Hazardous Material Detection:Emergency responders require broad-spectrum identification of unknown substances at incident scenes. AI-embedded spectral analysis is collapsing the traditional separation between field screening and laboratory confirmation in United States and United Kingdom defense and homeland security procurement.
- Safety Monitoring:Continuous personnel protection in confined spaces and process areas depends on real-time alarm thresholds. OSHA and REACH compliance obligations force manufacturing facilities to maintain 24/7 coverage with documented calibration records.
- Air Quality Testing:Ambient monitoring networks and indoor environmental assessments track volatile organic compound and particulate levels.
- Leak Detection:Fugitive emissions identification in valves, flanges, and storage vessels supports LDAR (Leak Detection and Repair) regulatory programs.
Safety monitoring commands the largest installed base; hazardous material detection is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The chemical detector industry traces its industrial-scale origins to post-war German chemical engineering clusters along the Rhine, where BASF and Bayer's process safety demands spawned the first generation of fixed gas monitoring systems for petrochemical complexes.
United States
Defense procurement programs at the Department of Defense and Department of Homeland Security drive portable detector demand for CBRN reconnaissance and border screening applications. EPA enforcement of Clean Air Act amendments tightens permissible exposure limits, forcing Gulf Coast refineries and Ohio River Valley chemical processors to upgrade fixed detector networks. Houston's petrochemical corridor sustains concentrated demand for multi-gas detection infrastructure.
Germany
The Rhine chemical manufacturing corridor between Ludwigshafen and Leverkusen anchors European demand for fixed industrial monitors as REACH compliance deadlines accelerate replacement cycles. ECHA's rolling SVHC classification updates force 24-36 month reformulation cycles for sensor membranes and housing materials. Bavaria's semiconductor fabrication facilities command premium pricing for infrared leak detection systems with near-zero false-positive tolerance.
China
World-scale petrochemical capacity expansion at Zhejiang Petrochemical and Hengli Group creates greenfield demand for fixed detector networks lacking mature safety infrastructure. MEE enforcement of dual carbon goals tightens industrial emissions monitoring obligations across Yangtze River Delta chemical processors. Shanghai's Pudong district concentrates procurement authority for environmental monitoring networks serving municipal air quality testing stations.
India
Reliance Industries' Jamnagar refinery expansion and Indian Oil Corporation's Paradip complex buildouts lack installed fixed detector infrastructure, creating installation demand for electrochemical and infrared systems. The country's national environmental regulator tightens permissible exposure limits for hazardous chemical manufacturing under evolving factory safety codes. Gujarat's Dahej PCPIR chemical investment region concentrates new plant construction requiring integrated safety monitoring systems.
United Kingdom
Defense and Security Equipment International procurement channels drive demand for portable detectors serving dismounted CBRN reconnaissance units. The Health and Safety Executive enforces process safety management standards tightening calibration documentation requirements for manufacturing facilities. The Thames Valley corridor between London and Bristol hosts specialist detector service providers supporting multi-technology fleet maintenance.
Chemical Detector Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology sophistication tiers, with infrared and mass spectrometry systems capturing steeper margins than electrochemical commodity units. The vendor base organizes into three distinct tiers: diversified industrial conglomerates with integrated safety portfolios, specialized analytical instrument manufacturers, and defense-focused detection module suppliers. Consolidation pressure intensifies as AI-embedded spectral analysis capabilities force algorithmic competency acquisitions. Technology licensing partnerships and geographic expansion through local service subsidiaries represent the dominant competitive moves reshaping channel access.
Among diversified industrial conglomerates, Honeywell International Inc. and Siemens exemplify scale-driven positioning across integrated plant safety contracts, while Thermo Fisher Scientific Inc. anchors the laboratory-grade analytical tier through environmental network integration. Bruker occupies a specialized position representing high-resolution detection archetypes for defense and security applications. These three companies illustrate how technology specialization and vertical integration depth separate premium-tier positioning from commodity electrochemical suppliers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Honeywell International Inc. |
| Bruker |
| Smiths Detection Group Ltd. |
| FLIR Systems, Inc. |
| MSA |
| Agilent Technologies, Inc. |
| Emerson Electric Co. |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
Family-owned German sensor specialists and private-equity-rolled-up industrial conglomerates anchor supply-side pricing discipline through captive electrochemical cell production and long-term platinum supply contracts. Their consolidated ownership structures enable coordinated margin defense against commodity electrochemical competitors while funding infrared component R&D premiums demanded by semiconductor fabrication buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates military-grade MIL-STD-810 certified units from industrial ATEX-compliant monitors and basic electrochemical commodity detectors. Price differentiation hinges on certification tier complexity and after-sales calibration service bundling. Cost compression in economy electrochemical tiers is intensifying because Chinese manufacturers are flooding municipal wastewater safety budgets with sub-$400 hydrogen sulfide units. Defense procurement offices show least price sensitivity; municipal wastewater authorities exhibit maximum budget constraint.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston feed hub-and-spoke patterns serving petrochemical corridors and defense logistics networks. Manufacturing concentrates in Germany, the United States, and Japan for precision photonics and electrochemical cells. Raw material dependencies span platinum and palladium catalysts for electrodes, germanium substrates for infrared optics, and fluoropolymer membranes for sensor housings. Single-source vulnerability in Japanese tunable diode laser suppliers creates chokepoint exposure for semiconductor leak detection tiers. Distribution runs through authorized service subsidiaries for calibration-dependent maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chemical detector market reads as a late-cycle quality story where AI-embedded spectral analysis capabilities are compressing procurement timelines toward premium-specification portable units with laboratory-grade field precision.
For Market Incumbents: To counter algorithmic competency fragmentation among defense procurement offices, anchor position through backward integration into platinum catalyst electrode production and capacity expansion in Bavaria's semiconductor service corridor. Prioritize ATEX/IECEx certification pre-investment to compress 12-18 month validation cycles ahead of EU Green Deal enforcement deadlines. For New Entrants and Emerging Players: Mid-sized Indian petrochemical operators building first-generation fixed detector networks at Reliance Industries and Indian Oil Corporation complexes represent the most penetrable buyer archetype. Capture share through project-based greenfield installation bundling with local calibration service partnerships, bypassing established European service infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among electrochemical commodity manufacturers facing REACH substance restriction friction and precious metal input volatility. Long-term viability favors targets with algorithmic spectral analysis capabilities and defense channel access. Watch EPA Clean Air Act enforcement intensity as the primary inflection signal for industrial replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Embedded Spectral Analysis Acquisition | Machine learning algorithm purchases collapse field-laboratory capability gaps for defense buyers. |
| Platinum Catalyst Electrode Backward Integration | In-house electrode production insulates margin from London Metal Exchange palladium volatility. |
| ATEX/IECEx Certification Pre-Investment | Early hazardous area approval accelerates tender participation for Rhine chemical corridor upgrades. |
| Indian Petrochemical Greenfield Service Partnership | Local calibration subsidiaries capture installation demand at Jamnagar and Paradip complex buildouts. |
| Photoionization-Infrared Hybrid Architecture Launch | PID-IR convergence captures premium positioning in semiconductor fabrication leak detection. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant safety managers, defense procurement officers, environmental compliance directors, and aftermarket service technicians with secondary validation through customs trade data, SEC 10-K filings, ECHA SVHC registration databases, and NATO tender documentation. Bottom-up sensor unit shipment estimates and top-down industrial safety spending allocations were triangulated against petrochemical capacity expansion announcements.
Comparable-period anchoring tied projection models to historical replacement cycle patterns across REACH compliance waves and EPA enforcement intensification phases. Segmentation dimensions spanned product mobility tier, detection technology architecture, end-use industry vertical, and regional regulatory enforcement cluster. CAGRs were derived from installed base aging analysis and greenfield capacity buildout pipelines, with electrochemical sensor miniaturization curves and AI-embedded unit procurement trajectories serving as primary demand inputs.
Underlying measurement precision varies by segment; portable defense procurement and fixed industrial monitor volumes carry tighter precision than emerging environmental monitoring network deployments. Forecasts reflect documented assumptions around regulatory enforcement velocity and precious metal price stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Membrane Osmometer Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Global Chromatography Instruments Market
Testing Equipment
Fibrin Degradation Product (Fndp) Assays Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Viscometer Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Grease Analyzer Market