
 Flash Point Apparatus Market | 2026-2036
Flash Point Apparatus Market Size, Share, and Industry Trends Forecast 2026-2036
Flash Point Apparatus Market Foresight
ASTM D93 certification is bifurcating the competitive landscape between automated and manual system suppliers. Anton Paar GmbH leverages its Austrian engineering base to dominate high-precision automated flash point testers for petroleum laboratories. Stanhope-Seta Ltd anchors its position through British heritage in Pensky-Martens and Tag closed cup instrumentation. ERALYTICS GmbH differentiates via Austrian-built rapid equilibrium closed cup systems that serve fuel analysis workflows.
A flash point apparatus measures the lowest temperature at which a liquid produces sufficient vapor to ignite momentarily under standardized test conditions, typically operating across ranges from ambient to 400°C with ignition detection via flame or electric arc. The device serves petroleum testing and chemical manufacturing by determining hazardous material classification for transport and storage safety. Automated flash point testers command premium positioning as laboratories pursue throughput gains and operator-error reduction, while manual flash point devices retain niche demand in emerging markets with constrained capital budgets. Closed cup method technology leads volume due to its alignment with global shipping regulations, whereas small scale closed cup systems gain traction in environmental safety applications requiring minimal sample volumes.
ASTM International and ISO shape product design through D93, D56, and 2719 test method specifications that determine instrument architecture and calibration protocols. EPA and OSHA requirements in the United States mandate flash point documentation for chemical inventory reporting and workplace hazard communication. Stakeholders must monitor evolving REACH amendments in Europe and potential GB standard harmonization in China, as regulatory divergence between jurisdictions could fragment certification requirements and complicate multinational instrument deployment strategies.
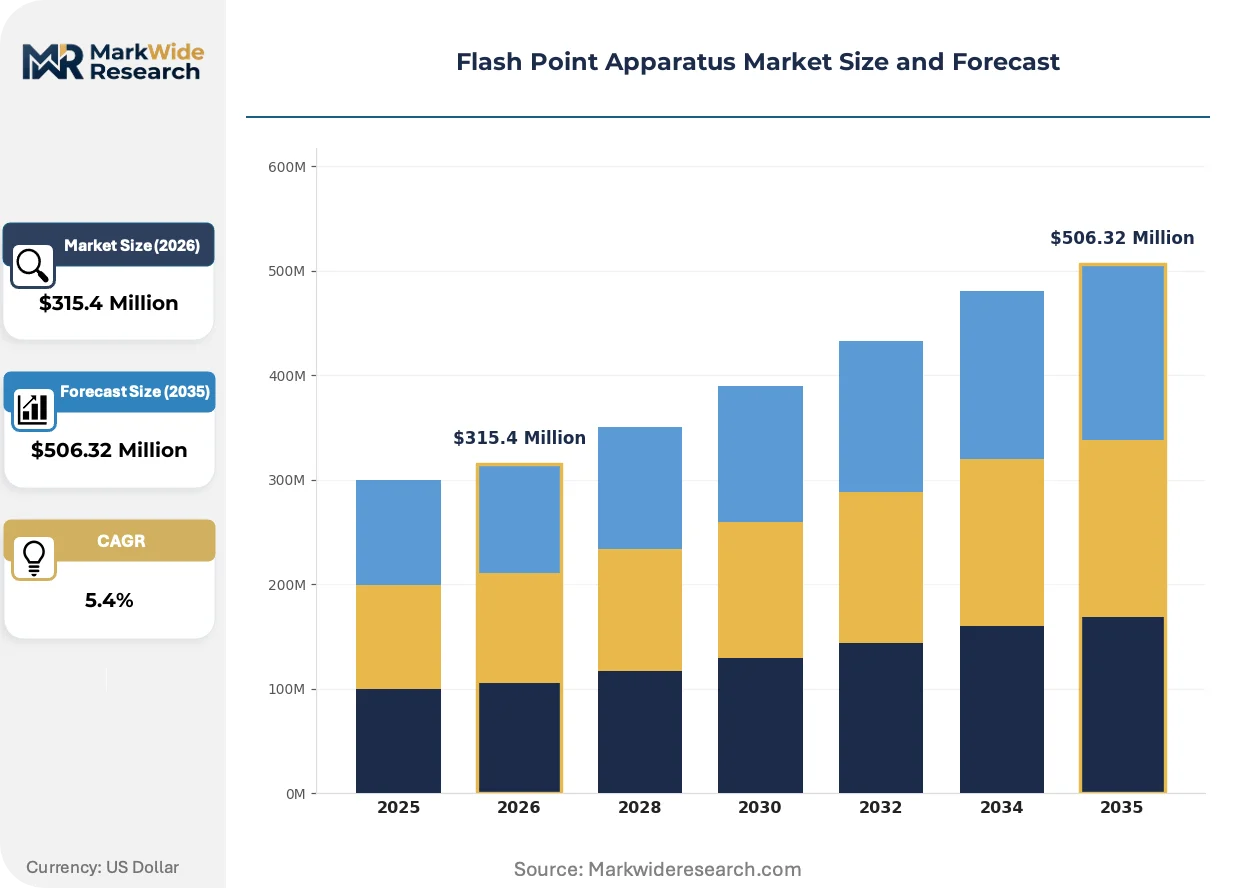
Market Dynamics
ASTM D93 and ISO 2719 qualification tightening is fragmenting supplier capabilities between automated precision systems and legacy manual equipment, compressing margins for mid-tier instrument manufacturers unable to bridge certification gaps.
Growth Catalysts
- ASTM D93 Certification Mandates:US petrochemical laboratories face OSHA hazard communication requirements that mandate closed cup flash point documentation, forcing replacement cycles for non-compliant manual systems.
- Middle East Refining Capacity Expansion:Saudi Arabia and Kuwait are commissioning new petrochemical complexes that require ASTM-qualified flash point testing for feedstock quality control and export certification.
- Automated Ignition Detection:Thermocouple-based electric arc systems are replacing gas flame ignition in high-throughput laboratories, eliminating operator variability in flash point determination.
Market Restraints
- Premium Sensor Cost Concentration:Platinum resistance temperature detectors and precision thermocouples are sourced from a limited supplier base in Germany and Japan, exposing instrument manufacturers to input cost volatility.
- Manual System Inventory Glut:Secondary markets in India and Southeast Asia are absorbing decommissioned European and North American manual flash point equipment, delaying new automated system purchases.
- ASTM D56 Open Cup Method Decline:Shipping regulation alignment with closed cup methods is rendering open cup flash point apparatus obsolete for transport classification, stranding R&D investments in Tag and Cleveland open cup designs.
Strategic Opportunities
- India BIS Laboratory Accreditation:India's Bureau of Indian Standards is expanding petroleum testing laboratory certification requirements, creating demand for ISO 2719-compliant closed cup systems in Mumbai and Vadodara refining clusters.
- Biofuel Blend Analysis Workflows:Fatty acid methyl ester and hydrotreated vegetable oil producers require modified rapid equilibrium closed cup methods that accommodate oxygenated fuel matrices outside traditional petroleum calibration ranges.
- Cloud-Connected Calibration Services:Instrument vendors are bundling remote calibration verification and ASTM traceable certificate generation as subscription services, shifting revenue from hardware sales to recurring instrumentation-as-a-service contracts.
Industry Challenges
- Cross-Method Technician Training:Laboratory operators must maintain proficiency across Pensky-Martens, Tag, and rapid equilibrium closed cup protocols simultaneously, stretching training budgets and certification renewal cycles.
- Legacy LIMS Integration Friction:Automated flash point testers from Austrian and German suppliers often require custom middleware development to communicate with incumbent laboratory information management systems in North American petroleum laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flash Point Apparatus Market |
| Market Size in 2026 | $315.4 Million |
| Market Size in 2035 | $506.32 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Flash Point Testers, Manual Flash Point Devices, Pensky-Martens Apparatus, Cleveland Open Cup Apparatus, Tag Closed Cup Apparatus Technology: Closed Cup Method, Open Cup Method, Small Scale Closed Cup, Rapid Equilibrium Closed Cup, Pensky-Martens Standards Application: Petroleum Testing, Chemical Manufacturing, Quality Assurance, Environmental Safety, Fuel Analysis, Laboratory Testing End User: Petrochemical Plants, Research Laboratories, Quality Control Facilities, Regulatory Authorities, Industrial Testing Centers |
| Companies Covered | Anton Paar GmbH, Stanhope-Seta Ltd, ERALYTICS GmbH, Grabner Instruments, PAC LP, Koehler Instrument Company, AD Systems, Cannon Instrument Company, Labtron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flash Point Apparatus Market Shifts & Advancements
Digital instrumentation architectures are displacing electromechanical control systems in flash point determination, compressing test cycle times while embedding compliance documentation directly into analytical workflows.
Microprocessor-controlled heating rate regulation is decomposing the historical trade-off between test precision and throughput. Petroleum testing laboratories in Rotterdam and Houston are deploying systems that modulate temperature ramp rates based on sample viscosity predictions. This capability is decomposing the market segmentation between premium automated systems and mid-tier semi-automated alternatives.
REACH amendments in Europe are tightening substance classification requirements for chemical mixtures, compelling formulators to document flash point data for downstream safety data sheet generation. Specialty chemical manufacturers in Germany and Belgium are responding by installing redundant closed cup systems to eliminate analytical downtime during peak regulatory filing periods.
Buyers are unbundling after-sales service contracts from initial instrument procurement, negotiating calibration and maintenance agreements separately through third-party metrology providers. This pattern is most pronounced in US Gulf Coast petrochemical clusters where independent service organizations hold ISO 17025 accreditation for ASTM D93 calibration verification, eroding vendor captive service revenue streams.
Flash Point Apparatus Market Segmentation
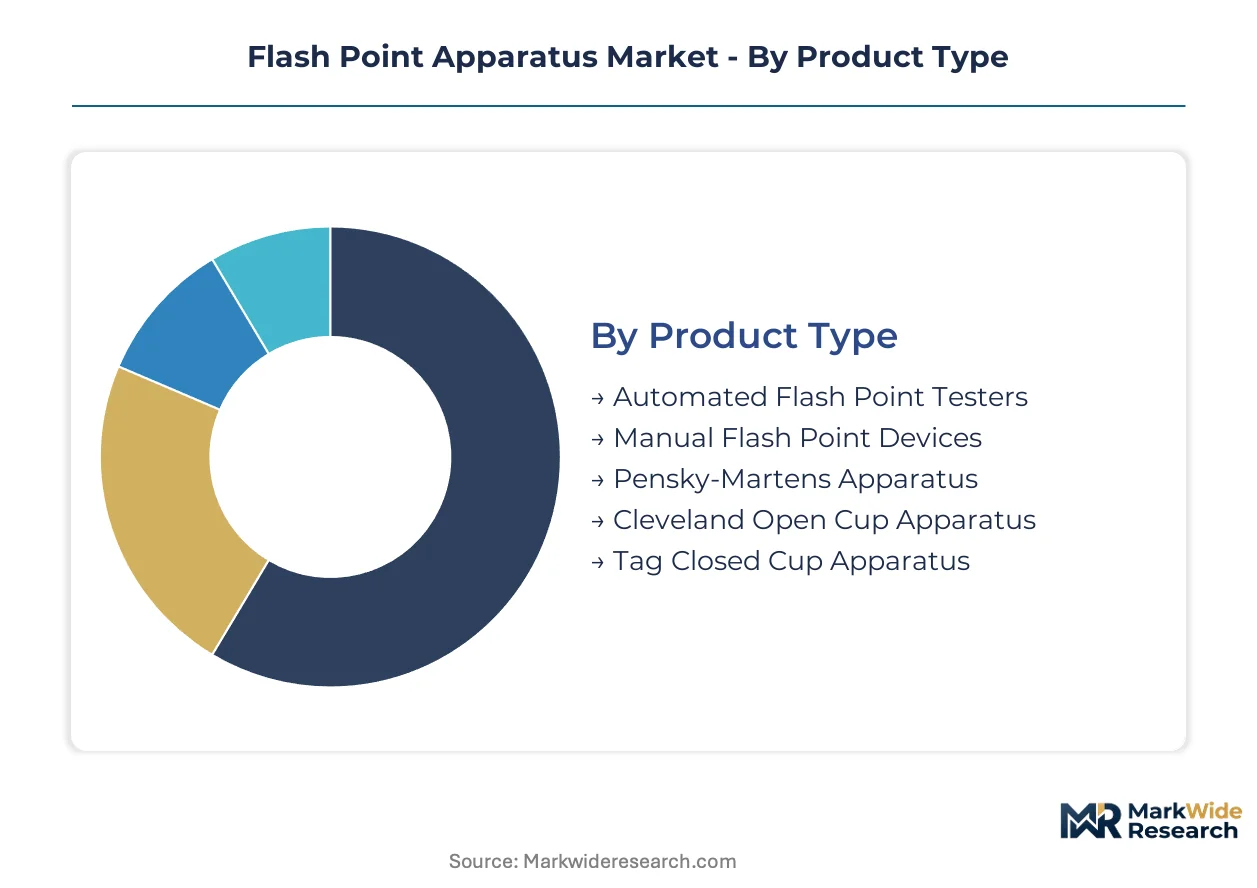
Flash point apparatus segmentation reveals how ASTM D93 and ISO 2719 compliance requirements fragment purchasing decisions across precision tiers. Regulatory alignment with closed cup methods is compressing demand into automated systems while stranding legacy open cup investments.
Product Type:
ASTM D93 certification mandates in the United States and REACH substance classification in Europe are bifurcating procurement between precision-automated and legacy-manual equipment tiers.
- Automated Flash Point Testers:Microprocessor-controlled systems with thermocouple-based electric arc ignition eliminate operator variability in flash point determination. Petrochemical plants in Saudi Arabia and Kuwait specify these for high-throughput feedstock quality control during refining capacity expansion.
- Manual Flash Point Devices:Electromechanical heating systems with gas flame ignition require skilled technician operation and extended test cycles. Secondary markets in India and Southeast Asia absorb decommissioned European and North American units, delaying new automated purchases in capital-constrained laboratories.
- Pensky-Martens Apparatus:Closed cup systems designed specifically for petroleum products with flash points above 40°C, serving diesel and lubricant testing workflows.
- Cleveland Open Cup Apparatus:Open cup designs for viscous materials and asphalt testing, now largely obsolete for transport classification under aligned shipping regulations.
- Tag Closed Cup Apparatus:Compact closed cup systems for lower flash point liquids, common in fuel and solvent analysis applications.
Established volume favors automated flash point testers; emerging adoption favors manual flash point devices in secondary markets.
Technology:
Shipping regulation harmonization with closed cup protocols is rendering open cup methods structurally uncompetitive for hazardous material classification.
- Closed Cup Method:Sealed chamber design prevents vapor loss and aligns with IATA, IMO, and DOT transport regulations globally. Petroleum testing laboratories in Rotterdam and Houston deploy these systems for export certification compliance.
- Rapid Equilibrium Closed Cup:Accelerated heating protocols with continuous vapor-liquid equilibrium monitoring reduce test duration by 60-70% versus traditional methods. Fatty acid methyl ester and hydrotreated vegetable oil producers in Germany and Belgium specify modified versions for oxygenated biofuel matrices.
- Open Cup Method:Atmospheric exposure design for Cleveland and Tag protocols, now restricted to non-transport applications like asphalt and residual fuel characterization.
- Small Scale Closed Cup:Minimal sample volume requirements suit environmental safety screening and waste characterization workflows.
- Pensky-Martens Standards:Specific temperature ramp rate and stirring specifications for viscous petroleum products above 40°C flash points.
Regulatory alignment concentrates procurement on closed cup method systems; biofuel diversification drives rapid equilibrium closed cup expansion.
Application:
Laboratory throughput requirements and regulatory filing intensity determine technology tier selection across use cases.
- Petroleum Testing:Crude oil, refined product, and lubricant characterization for refinery process control and export certification. Middle Eastern petrochemical complexes commission redundant systems to eliminate analytical downtime.
- Fuel Analysis:Gasoline, diesel, jet fuel, and biofuel blend testing for octane rating, cold flow properties, and combustion performance validation.
- Chemical Manufacturing:Solvent, resin, and coating formulation safety data sheet documentation under OSHA hazard communication and REACH classification requirements.
- Quality Assurance:Incoming raw material verification and finished product release testing in industrial chemical production.
- Environmental Safety:Waste stream characterization and spill response material classification for remediation contractors.
- Laboratory Testing:Third-party analytical services and research institution method development activities.
Petroleum testing anchors current installed base; fuel analysis climbs the fastest as biofuel mandates proliferate.
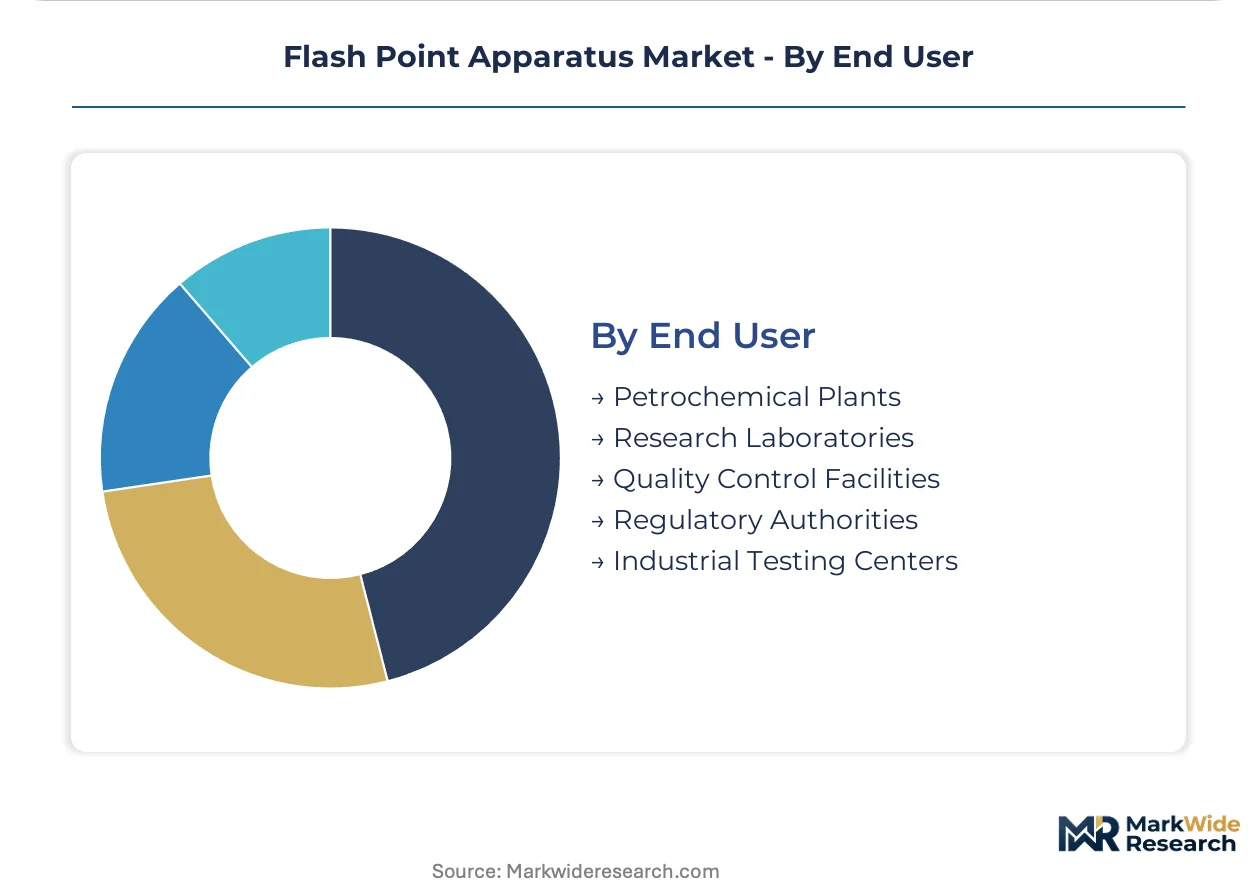
End User:
Capital intensity and regulatory exposure create distinct procurement patterns across facility types.
- Petrochemical Plants:Integrated refining and chemical manufacturing complexes with continuous process analytical requirements. Saudi Aramco and Kuwait Petroleum Corporation investments drive automated system specification.
- Research Laboratories:Method development and fundamental combustion science investigations requiring multi-protocol flexibility and precision calibration.
- Quality Control Facilities:Incoming inspection and finished product release testing for chemical distributors and specialty manufacturers.
- Regulatory Authorities:Government laboratories performing reference method validation and enforcement sampling analysis.
- Industrial Testing Centers:Third-party commercial laboratories serving multiple clients with high-throughput, standardized workflows.
Petrochemical plants concentrate premium automated procurement; industrial testing centers expand most quickly as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA hazard communication mandates in the United States and BIS laboratory accreditation expansion in India are redistributing flash point apparatus procurement toward jurisdictions with tightening regulatory enforcement.
United States
Petrochemical laboratories along the US Gulf Coast face OSHA mandates requiring ASTM D93-compliant closed cup documentation for chemical inventory reporting. EPA spill response protocols reinforce demand for redundant testing capacity. Houston and Baytown refining clusters commission automated systems to eliminate analytical downtime during peak regulatory filing periods.
Germany
Specialty chemical manufacturers in the Rhine-Ruhr industrial belt respond to REACH amendments tightening substance classification requirements for chemical mixtures. ECHA documentation deadlines drive redundant closed cup system installations. BASF and Lanxess supply chain clusters in Ludwigshafen and Leverkusen prioritize rapid equilibrium methods to accelerate safety data sheet generation.
Saudi Arabia
Saudi Aramco and SABIC expansion projects in Jubail and Yanbu commission ASTM-qualified flash point testing for feedstock quality control and export certification. SFDA chemical safety protocols align with international shipping regulations. Eastern Province petrochemical complexes specify automated ignition detection systems for high-throughput process analytical requirements.
India
BIS petroleum testing laboratory certification expansion in Mumbai and Vadodara refining clusters creates demand for ISO 2719-compliant closed cup systems. Reliance Industries and Indian Oil downstream investments drive instrument procurement. Maharashtra and Gujarat industrial corridors absorb decommissioned European manual equipment while greenfield facilities specify automated platforms.
China
Sinopec and CNPC refining capacity additions in Shandong and Guangdong provinces require flash point documentation under evolving GB standard harmonization. MEE environmental safety screening protocols expand small scale closed cup adoption for waste characterization. Yangtze River Delta chemical manufacturing clusters upgrade from manual to microprocessor-controlled heating rate regulation systems.
Flash Point Apparatus Market Competitive Landscape
Player mix skews toward precision instrumentation specialists with Austrian and German engineering heritage dominating premium automated tiers. Mid-tier semi-automated suppliers face margin compression from certification fragmentation between ASTM D93 and ISO 2719 requirements. Three archetypes anchor competitive positioning: high-precision automated system builders, heritage manual equipment fabricators, and rapid equilibrium method innovators. Dominant competitive moves include geographic expansion into Middle Eastern petrochemical corridors and technology licensing for biofuel matrix adaptation.
Among Austrian and German precision engineering specialists, Anton Paar GmbH, ERALYTICS GmbH, and Grabner Instruments occupy positions reflecting distinct automation philosophies. Anton Paar exemplifies the high-precision automated tier through its engineering base serving petroleum laboratories with thermocouple-based electric arc ignition systems. ERALYTICS represents rapid equilibrium method innovation with Austrian-built platforms addressing oxygenated fuel matrices outside traditional petroleum calibration ranges. Grabner Instruments anchors the heritage-technology vector with closed cup instrumentation expertise serving fuel analysis workflows. British heritage fabricator Stanhope-Seta Ltd occupies a distinct position through Pensky-Martens and Tag closed cup specialization. PAC LP and Koehler Instrument Company represent North American market presence with service network density advantages in US Gulf Coast petrochemical clusters.
| Leading Market Players |
|---|
| Anton Paar GmbH |
| Stanhope-Seta Ltd |
| ERALYTICS GmbH |
| Grabner Instruments |
| PAC LP |
| Koehler Instrument Company |
| AD Systems |
| Cannon Instrument Company |
| Labtron |
| Others |
Supply & Pricing Matrix
Thermocouple-based electric arc ignition replacing gas flame detection simultaneously concentrates supply geography in German and Japanese sensor corridors and compresses pricing economics for mid-tier instrument manufacturers. This substitution dynamic elevates input cost volatility for platinum resistance temperature detectors while fragmenting competitive positioning between precision-automated and legacy-manual equipment tiers.
Pricing Analysis
Cost-plus contracts with platinum and rare earth metal indexation dominate procurement between instrument manufacturers and precision sensor suppliers. Three-tier pricing structure across premium automated, standard semi-automated, and economy manual levels separates ASTM D93-certified systems from ISO 2719-equivalent alternatives from economy decommissioned units. Cost compression in mid-tier semi-automated systems is intensifying because certification fragmentation between ASTM and ISO standards strands R&D investments. Petrochemical plants in Saudi Arabia and Kuwait exhibit lowest price sensitivity due to continuous process analytical requirements, while secondary market buyers in India and Southeast Asia absorb decommissioned European equipment with highest price sensitivity.
Supply Chain Analysis
Germany and Japan anchor precision temperature sensor fabrication for platinum resistance detectors and thermocouple assemblies. Flash point apparatus manufacturing draws from Austrian engineering bases for automated system integration, Chinese machining clusters for mechanical housings, and British heritage fabricators for manual Pensky-Martens and Tag closed cup designs. Single-source vulnerability concentrates in German and Japanese platinum sensor suppliers, exposing instrument manufacturers to input cost volatility. Distribution runs through direct OEM sales to petrochemical complexes, third-party laboratory distributors in refining clusters, and secondary equipment brokers absorbing decommissioned manual systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated petrochemical complexes in the Middle East and Asia, consolidating procurement decisions around automated system specifications and compressing margins for mid-tier suppliers unable to meet ASTM D93 certification mandates.
For Market Incumbents: Compound certification portfolio breadth by securing simultaneous ASTM D93 and ISO 2719 qualification across automated product lines, defending against emerging rapid equilibrium method specialists. Deepen backward integration into precision thermocouple supply through captive partnerships with German and Japanese sensor manufacturers, reducing exposure to platinum price volatility. Anchor service network density in US Gulf Coast and Eastern Province petrochemical corridors to resist third-party metrology provider encroachment on calibration revenue streams. For New Entrants and Emerging Players: ASTM D93 fast-track certification for modified rapid equilibrium closed cup systems opens penetration pathways into biofuel blend analysis workflows outside traditional petroleum calibration ranges. Target fatty acid methyl ester and hydrotreated vegetable oil producers in Germany and Belgium with oxygenated fuel matrix adaptation as the most penetrable segment. Pursue technology licensing arrangements with established Austrian and German precision engineering specialists rather than direct hardware competition. For Investors and Strategic Acquirers: The market sits at a certification-consolidation phase that favors precision-automated system builders with established ASTM and ISO qualification portfolios. Long-term viability over the next decade hinges on recurring instrumentation-as-a-service revenue streams displacing transactional hardware sales. Watch cloud-connected calibration subscription attach rates as the signal indicating successful business model transition from equipment vendors to analytical service platforms.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM D93 Certification Investment | Qualification mandates from OSHA and BIS fragment competitive capabilities between automated precision tiers. |
| Backward Integration into Sensor Supply | Captive sourcing of platinum resistance detectors from German and Japanese suppliers reduces input cost volatility exposure. |
| Cloud-Connected Calibration Services | Remote verification and ASTM traceable certificate generation shift revenue from hardware to recurring service contracts. |
| Biofuel Matrix Adaptation | Modified rapid equilibrium methods for fatty acid methyl ester producers open workflows outside petroleum calibration ranges. |
| Service Network Expansion | ISO 17025-accredited calibration density in Houston and Jubail corridors resists third-party metrology provider encroachment. |
Research Methodology
Cross-validation between primary interviews with laboratory instrumentation procurement managers and secondary validation through ASTM International method documentation anchors the qualitative findings in this study. Conversations with petrochemical plant analytical directors, third-party testing laboratory operations heads, precision sensor supplier account managers, and regulatory affairs specialists at instrument manufacturers informed demand-side and supply-side dynamics. Secondary sources include customs and trade data for flash point apparatus imports, SEC 10-K filings for precision instrumentation companies, ASTM and ISO standard revision records, and BIS laboratory accreditation expansion announcements. Bottom-up triangulation across end-user procurement patterns and top-down validation through petrochemical capacity expansion databases ensured segmentation integrity.
Sensitivity analysis across platinum price volatility scenarios, ASTM D93 certification timeline variations, and Middle Eastern refining capacity completion schedules stress-tested projection robustness. The analytical framework models product type segmentation across automated, manual, Pensky-Martens, Tag, and Cleveland apparatus categories; technology segmentation across closed cup, rapid equilibrium, open cup, and small scale methods; and application segmentation across petroleum testing, fuel analysis, chemical manufacturing, and environmental safety workflows. CAGRs derive from regression analysis against petrochemical capital expenditure cycles and laboratory accreditation expansion rates. Industry-specific forecast inputs include thermocouple cost curves and biofuel mandate proliferation trajectories.
Underlying assumptions cover sustained OSHA hazard communication enforcement, REACH amendment continuity, and Middle Eastern refining capacity commissioning schedules, with deviation risk concentrated in regulatory divergence between ASTM and ISO jurisdictions and platinum supply disruption from German and Japanese sensor manufacturers. Recalibration cycles align with material shifts in ASTM method revision timelines and petrochemical complex operational startup dates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Bitumen and Asphalt Testing Services Market
Testing Equipment
Hydrometer Market
Testing Equipment
Corrosion Testing Services Market
Testing Equipment
Nitrogen Tester Market
Testing Equipment
Global Life Science and Chemical Instrumentation Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Analytical Gel Permeation Chromatography Market
Testing Equipment
Cyclic Corrosion Test Chamber Market
Testing Equipment
Lubricant Testing Machine Market
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
Global Rheometer and Viscometer Market
Testing Equipment
Global Chiral Chromatography Column Market
Testing Equipment
North America Dissolved Gas Analyzer Market
Testing Equipment
Ambient Temperature Gel Permeation Chromatography Market