
 Chemisorption Analyzer Market | 2026-2036
Chemisorption Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Chemisorption Analyzer Market Analysis
A shift from single-source procurement to multi-vendor qualification is recalibrating how research institutions and industrial labs secure chemisorption analyzers. Micromeritics Instrument Corporation dominates the North American installed base through its direct service infrastructure. Anton Paar leverages its Austrian manufacturing footprint to anchor European supply relationships with pharmaceutical quality-control departments. Thermo Fisher Scientific competes by extending its broader analytical portfolio into bundled lab-instrument contracts.
A chemisorption analyzer quantifies the quantity and energy of gas uptake on solid surfaces through temperature-programmed methods, typically operating from cryogenic conditions to 1100°C with detection thresholds below one micromole of adsorbed species. Its primary commercial purpose lies in characterizing catalyst active-site density and metal dispersion for petroleum refining and chemical synthesis optimization. Benchtop analyzers occupy the highest volume position due to their footprint efficiency in crowded university laboratories, while automatic analyzers capture expanding demand from pharmaceutical firms automating high-throughput catalyst screening. Temperature Programmed Desorption leads the technology dimension because of its direct correlation with catalytic activity metrics that process engineers require.
EPA method compliance for stationary-source emissions testing and REACH substance registration requirements in Europe are elevating documentation standards for surface-area and pore-structure measurements in environmental and materials applications. FDA process analytical technology guidelines for pharmaceutical manufacturing further tighten instrument validation protocols that vendors must satisfy. Stakeholders should monitor how evolving battery-material regulations in China and South Korea redirect analytical demand from traditional petrochemical catalysts toward solid-state electrolyte and cathode precursor characterization.
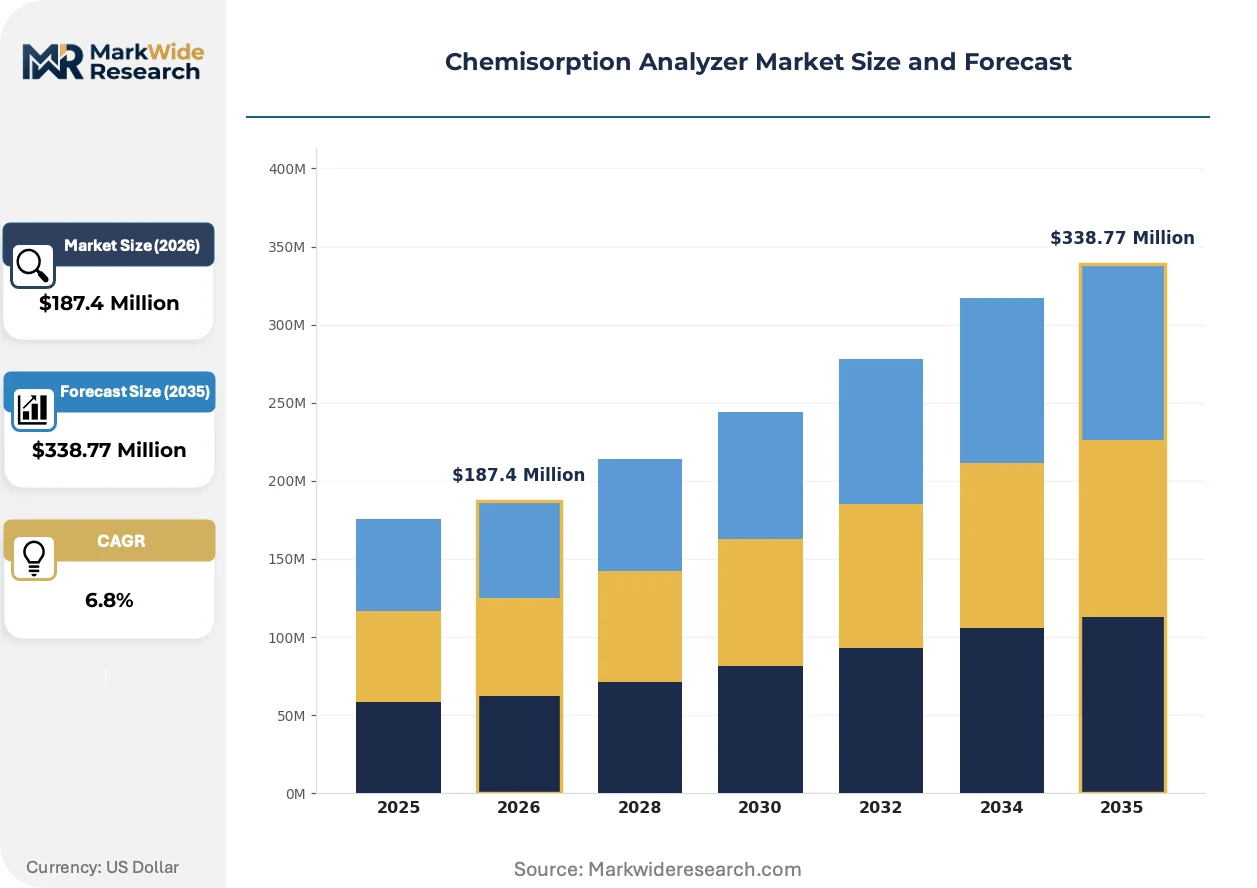
Market Dynamics
Refinery modernization programs and battery-material R&D labs are pulling procurement toward automated, high-throughput chemisorption systems that compress catalyst screening cycles from weeks to days. This operational tempo shift is restructuring vendor-customer relationships around validation speed rather than instrument longevity.
Growth Catalysts
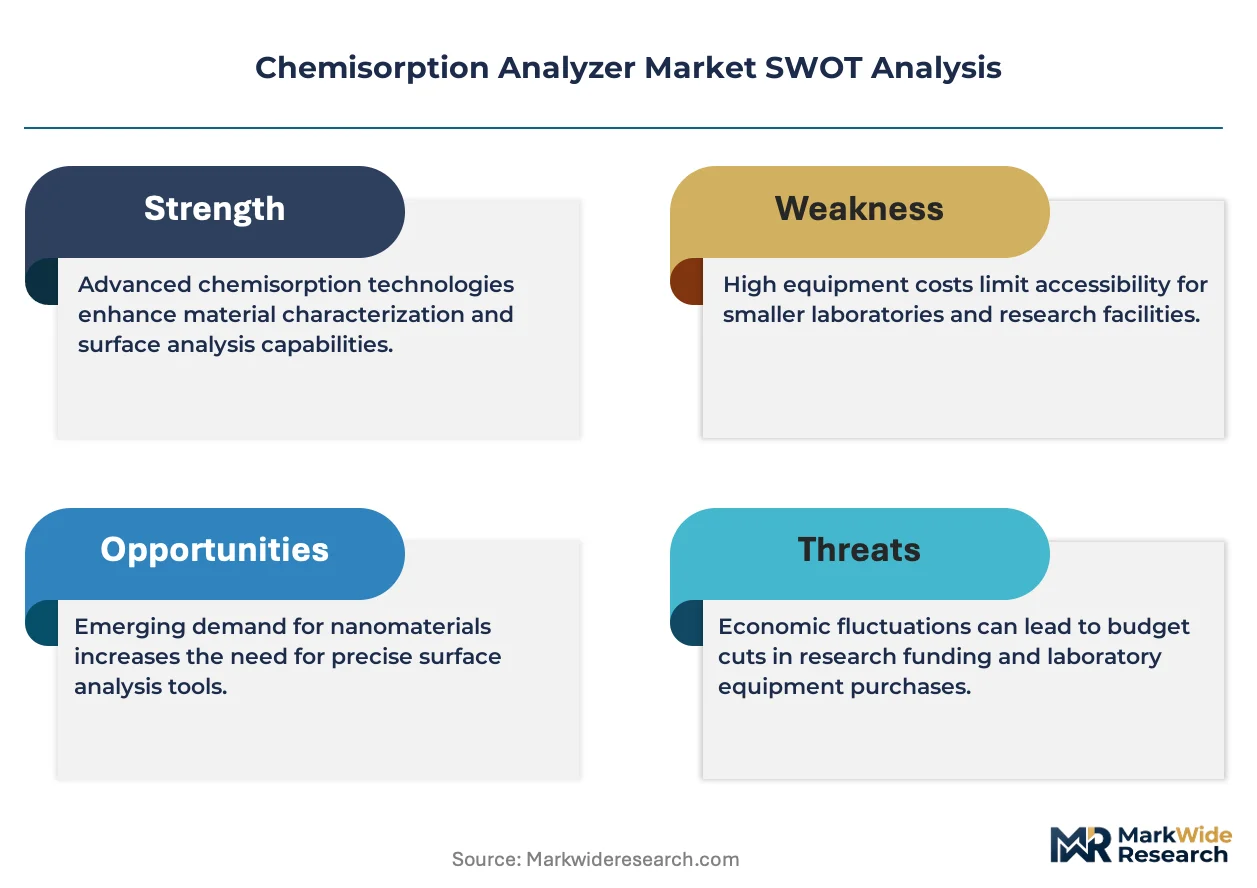
- REACH substance registration:European chemical manufacturers must document surface-area metrics for nanomaterial filings, forcing upgrades from legacy BET analyzers to temperature-programmed chemisorption systems.
- Solid-state battery electrolyte development:Cathode precursor labs in China and South Korea require metal dispersion data at sub-micromole sensitivity for lithium-metal anode optimization.
- FCC catalyst regeneration:US petroleum refiners facing EPA Method 202 compliance for particulate emissions are investing in active-site density characterization to extend catalyst cycles.
Market Restraints
- Helium supply concentration:Cryogenic chemisorption analysis depends on helium for pre-treatment cooling, with sourcing risks concentrated in Qatar and Algeria export infrastructure.
- Instrument capital intensity:Automated multi-station analyzers carry price tags that exclude mid-tier contract research organizations from ownership, limiting addressable demand.
- Technical labor scarcity:Temperature-programmed reduction protocol development requires surface chemistry PhDs, a credential pool concentrated in Germany, Japan, and select US National Lab clusters.
Strategic Opportunities
- India pharmaceutical API synthesis:CDSCO's tightened impurity profiling guidelines for generic drug manufacturing are creating first-time demand for metal catalyst residue detection in Mumbai and Hyderabad production corridors.
- AI-driven spectral interpretation:Machine learning deconvolution of TPD peak profiles is converging with cloud-based LIMS platforms, enabling remote diagnostic services that unbundle hardware from analytics revenue.
- Green hydrogen electrolyzer catalysts:Proton-exchange membrane stack manufacturers require iridium dispersion data for membrane electrode assembly qualification, opening a channel beyond traditional petrochemical buyers.
Industry Challenges
- Multi-vendor validation complexity:Research institutions running parallel qualification programs against Micromeritics, Anton Paar, and Quantachrome systems face protocol harmonization costs that delay procurement decisions.
- Legacy TCD calibration drift:Thermal conductivity detector baseline instability in aging installed bases forces unplanned downtime during critical catalyst batch release windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemisorption Analyzer Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Analyzers, Portable Analyzers, Automatic Analyzers, Semi-Automatic Analyzers Application: Materials Testing, Catalyst Research, Surface Characterization, Environmental Analysis End User: Chemical Industry, Pharmaceutical Industry, Academic Institutions, Research Labs Technology: Temperature Programmed Desorption, Static Method, Dynamic Method, Flow Method |
| Companies Covered | BEL Japan Inc., Surface Measurement Systems, Micromeritics Instrument Corporation, Hiden Analytical, Porous Media Inc., Quantachrome Instruments, Kunash Instruments, Anton Paar, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemisorption Analyzer Market Emerging Trajectories
Instrument architecture is pivoting from standalone hardware to connected analytical nodes that feed real-time dispersion data into process control loops. This connectivity imperative is rewiring vendor roadmaps around software subscription attach rates.
Mass spectrometry detection is integrating with conventional TCD-based chemisorption analyzers to enable simultaneous identification of desorbed species during temperature-programmed oxidation protocols. Battery-material labs in South Korea are adopting these hybrid configurations fastest, compressing the time from sample loading to metal oxidation state assignment. The structural consequence is a bifurcation in vendor portfolios between premium MS-coupled systems and cost-optimized TCD-only units.
EPA's proposed updates to stationary source emission testing protocols are tightening documentation requirements for catalyst surface area verification in refinery FCC units. This regulatory friction is elevating third-party validation services that certify analyzer calibration traceability. US Gulf Coast refiners are responding by consolidating procurement under service contracts that bundle hardware with compliance documentation.
Research consortia are unbundling after-sales service from capital purchase, contracting independent metrology firms for annual calibration rather than OEM service departments. This behavior shift is most visible in German university clusters where shared instrument facilities pool maintenance budgets across multiple departments. The channel disruption pressures traditional vendors to unbundle service pricing or risk displacement by certified third-party providers.
Chemisorption Analyzer Market Segmentation
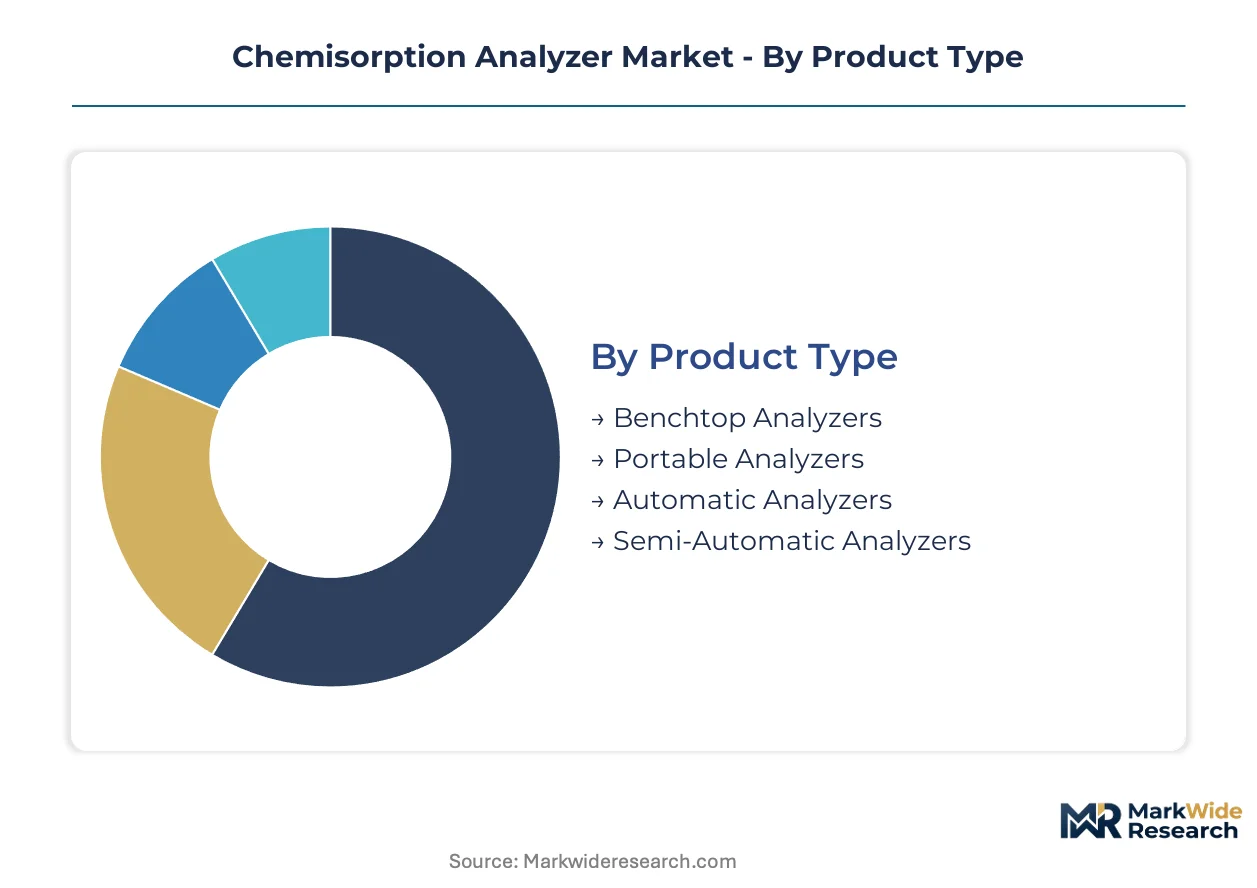
Chemisorption analyzer procurement patterns diverge sharply across product configurations and analytical protocols. Understanding where technical specifications align with operational constraints reveals why certain segments command premium positioning while others compete on accessibility.
Product Type:
Supply concentration in benchtop manufacturing favors vendors with established university distribution channels over specialized industrial automation houses.
- Benchtop Analyzers:Compact footprint systems dominate crowded academic laboratory environments where space constraints override throughput requirements. Demand concentrates in German university clusters and US National Lab facilities facing shared-instrument facility consolidation.
- Automatic Analyzers:Multi-station configurations with robotic sample handling compress catalyst screening cycles from weeks to days. Pharmaceutical quality-control departments in Mumbai and Hyderabad production corridors are scaling procurement for high-throughput metal dispersion validation.
- Portable Analyzers:Field-deployable units with reduced thermal range serve refinery turnaround teams requiring on-site FCC catalyst assessment.
- Semi-Automatic Analyzers:Hybrid systems balance operator intervention with programmable temperature ramps for mid-tier contract research organizations.
Today's leader: Benchtop Analyzers. Tomorrow's challenger: Automatic Analyzers.
Application:
Cost tier differentiation separates capital-intensive catalyst research from standardized materials testing workflows.
- Catalyst Research:Active-site density quantification and metal dispersion mapping for petroleum refining optimization. South Korean battery-material labs require sub-micromole sensitivity for solid-state electrolyte precursor characterization.
- Surface Characterization:Pore-structure documentation for REACH nanomaterial registration filings. European chemical manufacturers upgrade from legacy BET systems to temperature-programmed protocols.
- Materials Testing:Routine surface-area verification for quality-control release gates in cement and activated carbon production.
- Environmental Analysis:EPA Method 202 compliance documentation for refinery FCC particulate emissions testing.
Surface Characterization commands premium pricing through regulatory compliance mandates. Catalyst Research expands most quickly via battery-material R&D redirection.
End User:
Volume concentration in chemical industry procurement reflects refinery modernization cycles and catalyst regeneration program scaling.
- Chemical Industry:Petrochemical producers and specialty chemical manufacturers operating continuous process units. US Gulf Coast refiners bundle analyzer procurement with third-party validation service contracts.
- Pharmaceutical Industry:FDA process analytical technology guideline compliance drives instrument validation protocol investments. CDSCO impurity profiling requirements in India create first-time demand for metal catalyst residue detection.
- Academic Institutions:Shared instrument facilities across German university clusters pool maintenance budgets and consolidate vendor relationships.
- Research Labs:National laboratory clusters in Japan and the United States concentrate surface chemistry PhD expertise for temperature-programmed protocol development.
Chemical Industry anchors current procurement volume. Pharmaceutical Industry represents the steepest expansion trajectory through tightening regulator documentation requirements.
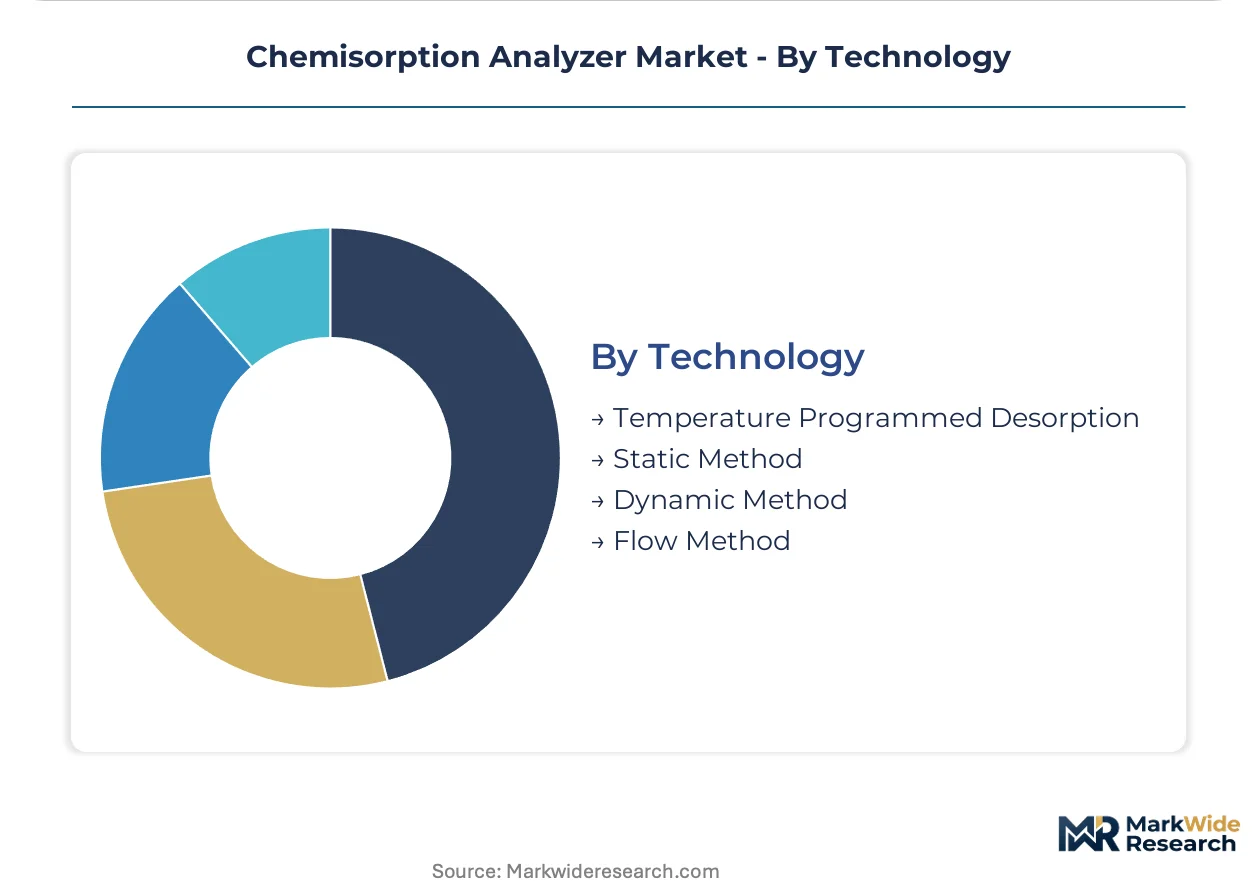
Technology:
Customer type stratification separates research institutions requiring spectral deconvolution from industrial labs prioritizing throughput speed.
- Temperature Programmed Desorption:Direct correlation with catalytic activity metrics drives process engineer preference. Mass spectrometry detection integration enables simultaneous desorbed species identification during oxidation protocols.
- Dynamic Method:Continuous flow configurations with thermal conductivity detection serve high-volume catalyst screening operations.
- Static Method:Equilibrium-based measurement protocols for fundamental surface chemistry research requiring precise adsorption isotherm construction.
- Flow Method:Pulsed chemisorption techniques for rapid metal dispersion assessment in production quality-control environments.
Temperature Programmed Desorption holds technology leadership. Flow Method gains share fastest through industrial automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting chemisorption analyzer procurement toward jurisdictions where compliance documentation costs less to fulfill. Manufacturers migrate validation work to countries with streamlined chemical registration frameworks while maintaining sales presence in high-standard markets.
United States
EPA Method 202 compliance for refinery FCC particulate emissions drives active-site density characterization demand. The agency's proposed stationary source testing updates tighten catalyst surface-area verification requirements. Gulf Coast refiners in Texas and Louisiana consolidate procurement under bundled service contracts with third-party validation providers.
Germany
REACH substance registration mandates nanomaterial surface-area documentation for chemical manufacturers. ECHA filing requirements force upgrades from legacy BET analyzers to temperature-programmed systems. University clusters in Bavaria and North Rhine-Westphalia pool maintenance budgets across shared instrument facilities.
China
Solid-state battery electrolyte development pulls metal dispersion analysis toward sub-micromole sensitivity thresholds. MEE enforcement of dual carbon goals accelerates refinery catalyst regeneration program investments. Cathode precursor labs in the Yangtze River Delta scale analytical capacity for lithium-metal anode optimization.
South Korea
MFDS battery-material regulations redirect analytical demand from petrochemical catalysts toward solid-state electrolyte characterization. Government-funded consortia in the Seoul Capital Area adopt mass spectrometry-coupled TPD systems fastest. Busan-Ulsan industrial complexes compress sample-to-result cycles for membrane electrode assembly qualification.
India
CDSCO tightened impurity profiling guidelines for generic drug manufacturing create first-time metal catalyst residue detection demand. Pharmaceutical API synthesis corridors in Mumbai and Hyderabad initiate instrument procurement for quality-control release gates. Contract research organizations face capital barriers to automated multi-station analyzer ownership.
Chemisorption Analyzer Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue battery-material specialization and cloud-connected service models. The vendor base stratifies between direct-service infrastructure holders and portfolio bundlers. Three archetypes dominate: analytical conglomerates extending platform ecosystems, precision instrument specialists defending regional installed bases, and automation-focused challengers targeting high-throughput screening contracts. Competitive moves concentrate on unbundling service pricing from hardware sales and integrating AI-driven spectral interpretation into subscription offerings.
Among analytical conglomerates, Thermo Fisher Scientific exemplifies portfolio bundling into broader lab-instrument contracts. Micromeritics Instrument Corporation anchors North American positioning through direct service infrastructure density. Anton Paar occupies a position within European supply relationships, leveraging Austrian manufacturing proximity to pharmaceutical quality-control departments. BEL Japan Inc. represents Asia-Pacific specialization in surface characterization instrumentation.
| Leading Market Players |
|---|
| BEL Japan Inc. |
| Surface Measurement Systems |
| Micromeritics Instrument Corporation |
| Hiden Analytical |
| Porous Media Inc. |
| Quantachrome Instruments |
| Kunash Instruments |
| Anton Paar |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
Helium procurement costs for cryogenic pre-treatment cooling cascade through three distinct pricing tiers, with Qatar and Algeria export infrastructure bottlenecks compressing margins at the economy end while premium MS-coupled systems absorb input volatility through software subscription bundling.
Pricing Analysis
Input-cost pass-through from helium supply concentration and thermal conductivity detector component sourcing stratifies pricing across premium MS-coupled systems, standard TCD-only units, and economy benchtop configurations. Price differentiation hinges on certification tier for EPA Method 202 compliance documentation and after-sales service bundling intensity. Pricing pressure stems from research consortia unbundling calibration services from capital purchase, forcing OEMs to decouple hardware from recurring revenue. Mid-tier contract research organizations exhibit highest price sensitivity, while pharmaceutical quality-control departments prioritize validation speed over capital expenditure.
Supply Chain Analysis
ISO 17025 calibration traceability certification gates entry for thermal conductivity detector suppliers and mass spectrometry module integrators, filtering vendor participation before assembly begins. Manufacturing concentrates in Austria, Japan, and the United States for precision thermal components and detection subsystems. Raw material dependencies include high-purity helium for cryogenic cooling, platinum-rhodium thermocouples for temperature accuracy, and fused silica tubing for gas flow path integrity. Single-source vulnerability concentrates in Qatar helium liquefaction capacity. Distribution runs through direct-service infrastructure for North American refinery accounts and pharmaceutical quality-control departments in European university clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance documentation costs in Europe run three to four times higher than CDSCO filing requirements in India, creating a geographic-arbitrage window for manufacturers migrating validation work to Mumbai and Hyderabad production corridors while maintaining sales presence in high-standard markets.
For Market Incumbents: Lock in service contract renewals at US Gulf Coast refiners by bundling EPA Method 202 compliance documentation with hardware refresh cycles, countering third-party metrology firm displacement. Deepen backward integration into thermal conductivity detector manufacturing to offset platinum-rhodium supply volatility from South African mining concentration. Prioritize AI-driven spectral interpretation R&D to defend software subscription attach rates against cloud-based LIMS platform unbundling. For New Entrants and Emerging Players: CDSCO tightened impurity profiling guidelines in India open a window for automated analyzer penetration in Mumbai and Hyderabad pharmaceutical API synthesis corridors, where capital barriers exclude mid-tier contract research organizations from incumbent-dominated procurement. Target battery-material labs in South Korea's Seoul Capital Area with mass spectrometry-coupled TPD configurations, the fastest-adopting segment for hybrid detection systems. Lead with outcome-based pricing models that unbundle hardware from per-sample analytical fees. For Investors and Strategic Acquirers: Consolidation pressure builds where shared instrument facilities in German university clusters pool maintenance budgets across multiple departments, fragmenting vendor relationships and creating rollup opportunities for service-capability aggregators. Five-to-ten year viability favors precision instrument specialists with captive calibration laboratory networks over analytical conglomerates dependent on portfolio bundling. Watch for battery-material regulation harmonization between China's MEE and South Korea's MFDS as inflection signal redirecting R&D procurement from petrochemical catalysts toward solid-state electrolyte characterization.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Spectral Interpretation Development | Machine learning deconvolution of TPD peak profiles enables remote diagnostic services unbundling hardware from analytics revenue. |
| Helium Recovery System Integration | Captive helium recycling infrastructure insulates production from Qatar export infrastructure bottlenecks and price volatility. |
| Third-Party Validation Service Partnership | CDSCO compliance documentation bundling captures pharmaceutical API synthesis demand in Mumbai and Hyderabad corridors. |
| Mass Spectrometry Detection Module Launch | Hybrid TPD-MS configurations compress sample-to-result cycles for South Korean battery-material labs. |
| Cloud-Based LIMS Platform Integration | Real-time dispersion data feeds into process control loops, rewiring vendor roadmaps around software subscription attach rates. |
Methodological Framework
Direct dialogue with instrument procurement managers at US Gulf Coast refiners, pharmaceutical quality-control directors in Mumbai and Hyderabad, university shared-facility administrators in Bavaria, and surface chemistry PhD researchers at Japanese National Labs grounded qualitative findings in operational constraints. Secondary validation drew from EPA Method 202 protocol documentation, ECHA REACH substance registration filings, CDSCO impurity profiling guideline updates, and SEC 10-K disclosures from analytical instrumentation conglomerates. Bottom-up triangulation against top-down macroeconomic drivers ensured segmentation integrity across product configurations and analytical protocols.
Segment-level demand curves for benchtop, automatic, portable, and semi-automatic analyzer configurations converged with technology adoption patterns for temperature-programmed desorption, dynamic method, static method, and flow method protocols across the projection horizon. End-use intensity modeling incorporated catalyst research, surface characterization, materials testing, and environmental analysis application splits. CAGRs derived from instrument replacement cycles, regulatory compliance deadline clustering, and battery-material R&D investment trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under helium supply disruption scenarios or abrupt battery-material regulation redirection in China and South Korea. Model assumptions reflect EPA stationary source testing protocol updates, REACH nanomaterial registration enforcement intensity, and solid-state electrolyte commercialization timelines. A model refresh is warranted upon material change in dual carbon goal enforcement by China's MEE or MFDS battery-material regulation harmonization initiatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Membrane Osmometer Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Process Analytical Technology Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
CHS (Carbon Hydrogen Sulfur) Analyzers Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Water Test Kits Market
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
Chemical Detection Equipment Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
Particle Size Analysis Market
Testing Equipment
Viscometer Market
Testing Equipment
Brittleness Tester Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Laboratory Balances and Scales Market