
 Process Analytical Technology Market | 2026-2036
Process Analytical Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Process Analytical Technology Market Intelligence
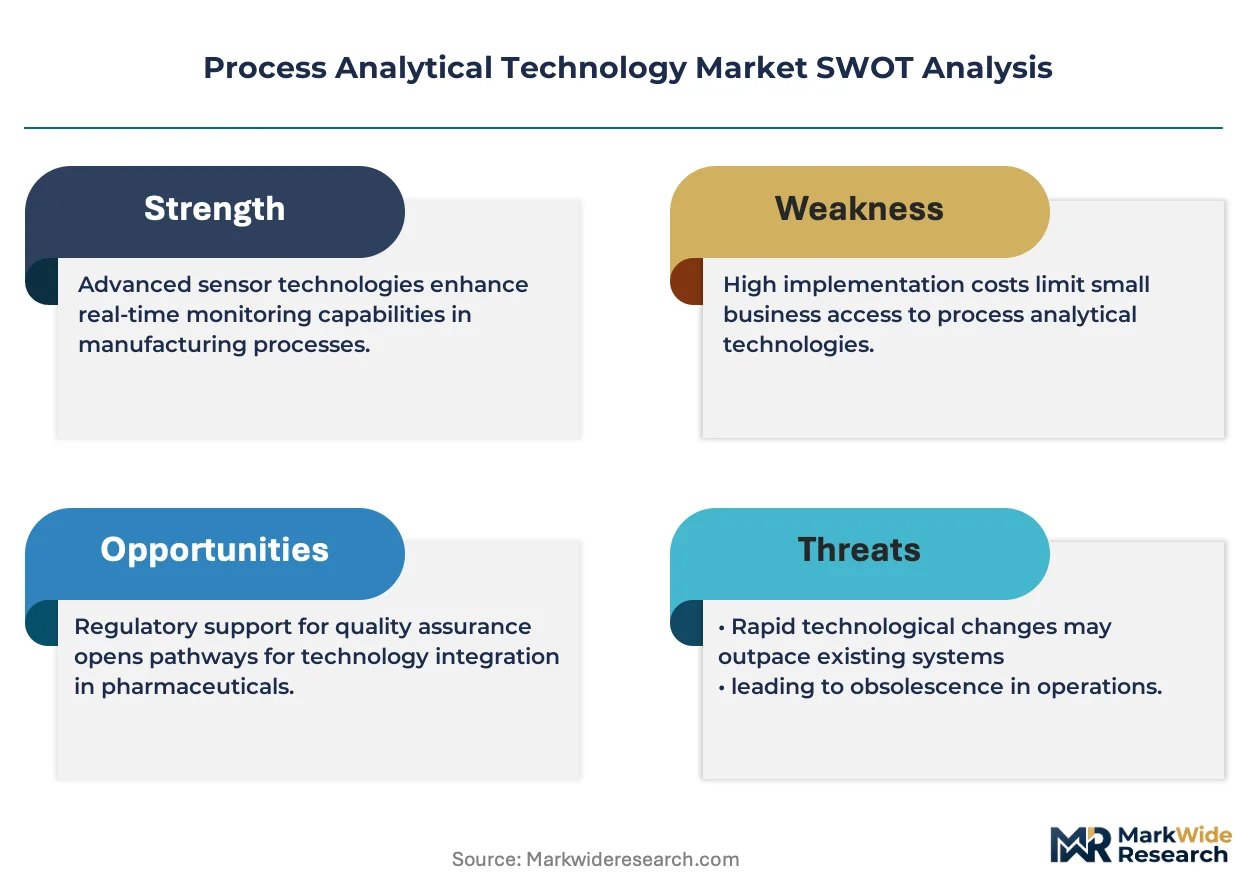
ISO 17025 accreditation is unwinding competitive access for analytical instrument vendors serving regulated industries. Thermo Fisher Scientific leverages its chromatography portfolio to anchor pharmaceutical manufacturing contracts across North America and Europe. Danaher Corporation sustains instrumentation density through its operating company structure, while Waters Corporation dominates mass spectrometry platforms for bioprocess monitoring.
Process Analytical Technology encompasses real-time chemical and physical measurement systems—spectroscopic, chromatographic, and electrochemical sensors—deployed directly within production streams to enable immediate quality attribute determination without offline laboratory delay. Spectroscopy platforms lead installed value due to their non-destructive sampling and fiber-optic probe adaptability, while mass spectrometry commands premium positioning for molecular specificity in biopharmaceutical applications. Chromatography retains mature share in chemical production settings where separation resolution requirements exceed inline spectroscopic capability.
FDA's Quality by Design framework and EMA's process validation guidance create compliance baselines that mandate analytical instrumentation with documented measurement uncertainty and electronic record integrity. The EPA's emissions monitoring requirements extend PAT sensor deployment into chemical production environmental compliance applications. Stakeholders must evaluate whether platform consolidation or specialized best-of-breed architectures offer superior lifecycle economics as biologics manufacturing scales toward continuous processing paradigms.
Market Dynamics
Continuous bioprocessing mandates real-time quality verification without offline laboratory delays, compressing the validation timeline for spectroscopic and chromatographic sensor platforms across pharmaceutical manufacturing networks.
Growth Catalysts
- FDA Quality by Design:The framework mandates documented measurement uncertainty for critical quality attributes, compelling pharmaceutical manufacturers to deploy inline spectroscopic probes for immediate release decisions.
- EMA process validation guidelines:European regulatory requirements for continued process verification accelerate capital allocation toward electrochemical sensor arrays in sterile drug substance production.
- Single-use bioreactor expansion:Disposable manufacturing platforms in mammalian cell culture create demand for fiber-optic Raman probes that withstand gamma sterilization cycles without calibration drift.
Market Restraints
- Reference standard scarcity:Certified reference materials for complex biologics—monoclonal antibodies, antibody-drug conjugates—create bottlenecks in spectroscopic model development and regulatory submission timelines.
- Optical component concentration:German and Swiss suppliers dominate high-precision gratings and detector arrays, exposing instrument manufacturers to extended lead times during semiconductor fab capacity constraints.
- Mass spectrometry footprint:Vacuum system requirements and vibration sensitivity limit inline deployment in existing production suites without structural facility modifications.
Strategic Opportunities
- Continuous direct compression:Solid oral dosage manufacturing shifts from batch to continuous processing, creating demand for near-infrared transmission probes integrated with powder feed control systems.
- India pharmaceutical corridor:CDSCO's alignment with ICH Q8-Q12 guidelines opens procurement pathways for PAT-qualified vendors in Hyderabad and Ahmedabad generic API clusters.
- Raman-chromatography fusion:Hybrid platforms combining spatially resolved spectroscopy with microfluidic separation enable real-time impurity profiling in peptide synthesis workflows.
Industry Challenges
- Multivariate analysis expertise:Chemometric model development requires specialized skill sets spanning spectroscopy, process engineering, and regulatory documentation that outpace current university training pipelines.
- Legacy DCS integration:Proprietary communication protocols in established distributed control systems obstruct seamless data flow from smart sensors to manufacturing execution systems without middleware investments.
- Method transfer complexity:Relocating validated PAT methods between manufacturing sites triggers extensive equivalence studies under ICH Q12 lifecycle management requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Analytical Technology Market |
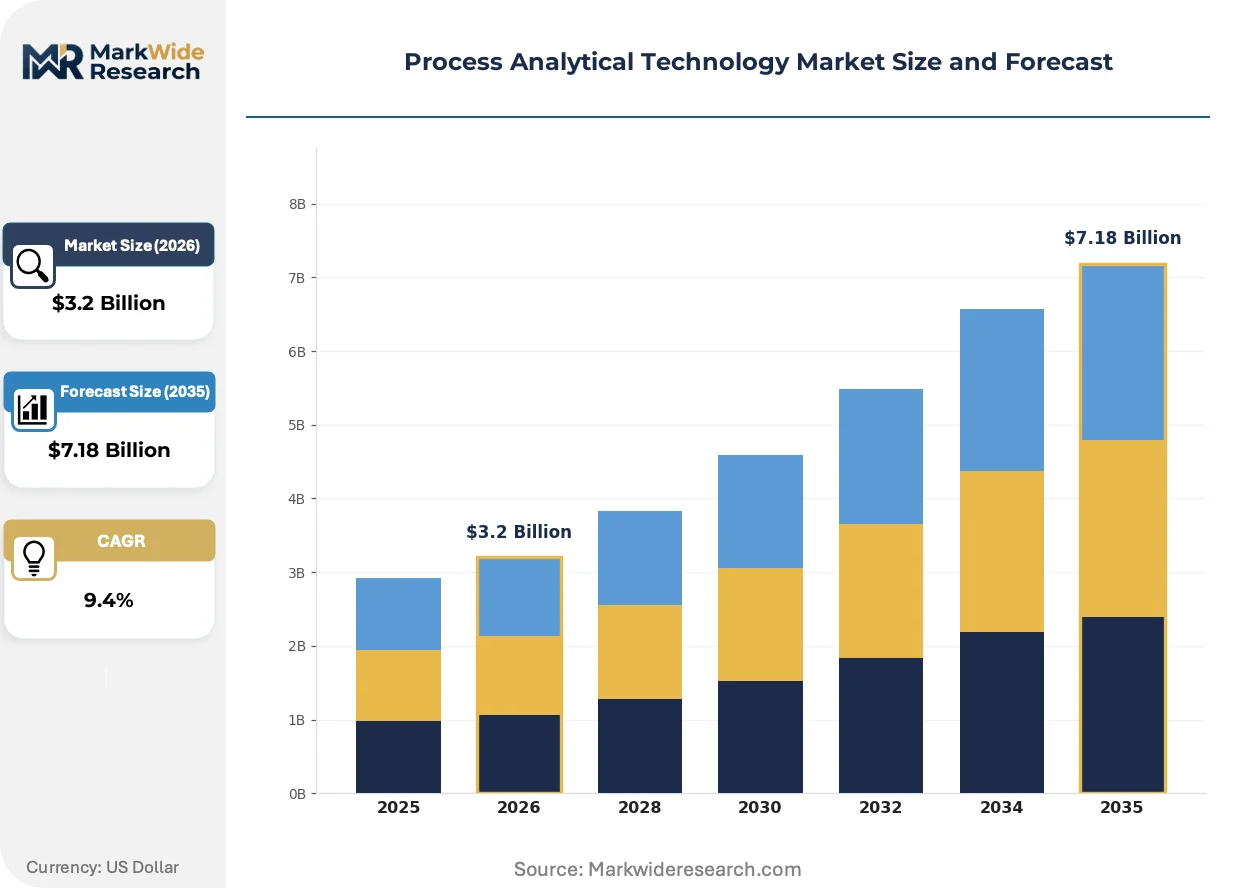
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $7.18 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectroscopy, Chromatography, Sensor Technology, Mass Spectrometry Application: Pharmaceutical Manufacturing, Chemical Production, Food Processing, Biotechnology End User: OEMs, Research Institutions, Analytical Laboratories, Contract Manufacturers Technology: UV-Vis Spectroscopy, Near-Infrared, Raman Spectroscopy, Fluorescence |
| Companies Covered | Waters Corporation, Siemens AG, Thermo Fisher Scientific, Bruker Corporation, ABB Ltd., Agilent Technologies, Mettler-Toledo International, PerkinElmer, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Analytical Technology Market Strategic Shifts & Innovations
Raman spectroscopy platforms are compressing the gap between laboratory reference methods and production-floor measurement, enabled by compact laser sources and machine learning-based spectral preprocessing.
Compact Raman systems with 785 nm and 1064 nm excitation options are supplanting traditional high-performance liquid chromatography for identity verification in raw material dispensing operations. Generic drug manufacturers in North America and Europe adopt these platforms to eliminate quarantine inventory holding periods. The shift compresses working capital cycles and reduces laboratory headcount in quality control functions.
EMA's revised Annex 1 guidance on sterile manufacturing elevates environmental monitoring to critical process parameter status, mandating continuous viable and non-viable particle detection. This regulatory pressure accelerates replacement of periodic grab-sampling with laser-induced breakdown spectroscopy for in-situ elemental contamination screening. Aseptic fill-finish operations in Ireland and Belgium deploy these systems to satisfy inspector expectations for real-time environmental control.
Biopharmaceutical procurement teams now unbundle hardware acquisition from method development and lifecycle support services, treating these as separate contract vehicles with distinct vendor qualification requirements. This pattern fragments the traditional turnkey supplier relationship and opens entry points for specialized chemometric consultancies in Boston and Basel. Contract manufacturing organizations lead this behavior shift as they seek competitive differentiation through faster technology transfer timelines.
Process Analytical Technology Market Segmentation
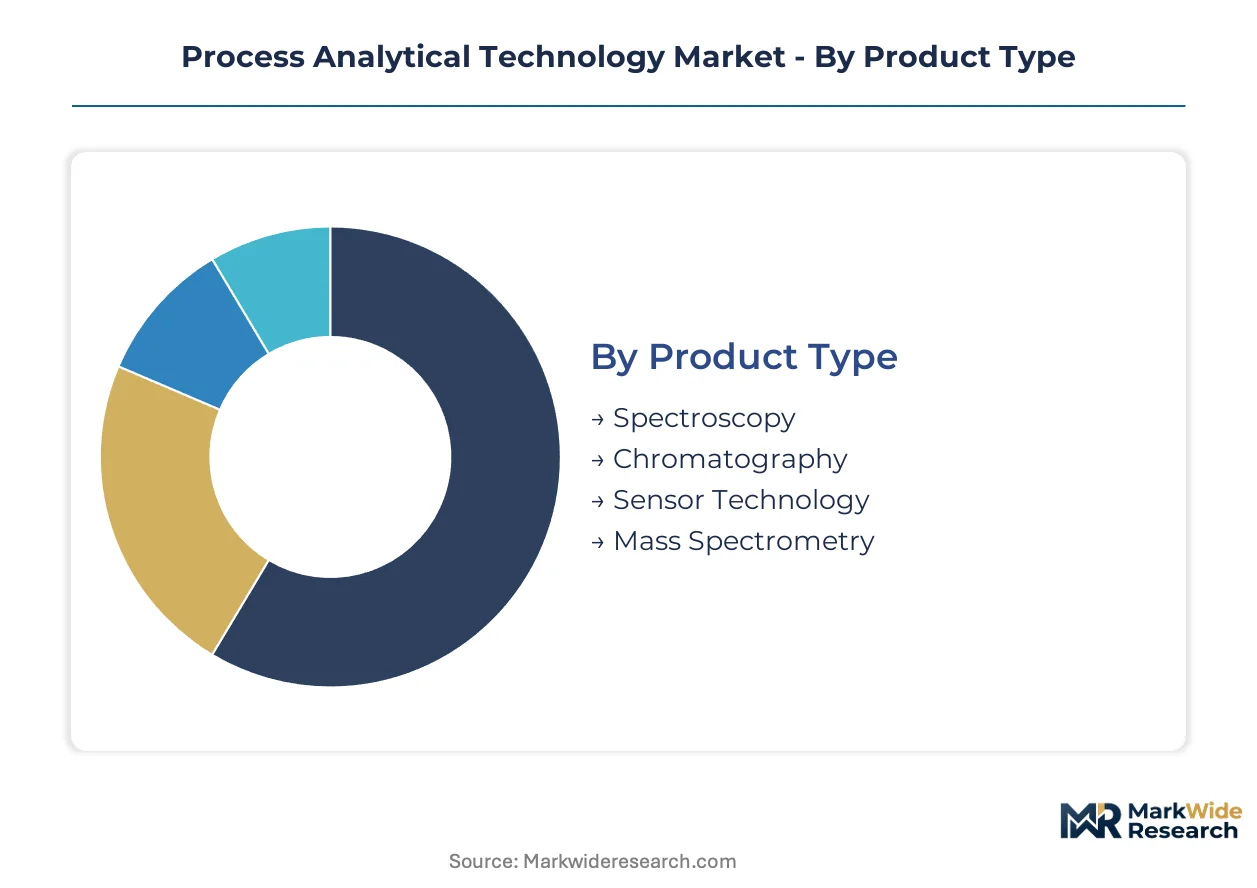
Process Analytical Technology deployment patterns vary sharply across measurement modalities and manufacturing contexts. Channel economics differ substantially between capital-intensive spectroscopy platforms and consumable-heavy sensor arrays.
Product Type:
Spectroscopy platforms flow through direct sales channels anchored by pharmaceutical engineering firms, while chromatography and mass spectrometry concentrate in distributor networks serving analytical laboratories.
- Spectroscopy:Non-destructive measurement systems utilizing fiber-optic probes for real-time chemical composition analysis. Demand concentrates in German pharmaceutical corridors around Frankfurt and Ludwigshafen, driven by FDA Quality by Design mandates for immediate release testing without offline delays.
- Chromatography:Separation-based analytical platforms including HPLC and gas chromatography systems with high resolution for complex mixtures. Chemical production facilities in Belgium and the Netherlands deploy these where separation requirements exceed inline spectroscopic capability, constrained by longer analysis cycles.
- Sensor Technology:Electrochemical and optical sensor arrays for continuous process monitoring.
- Mass Spectrometry:High-specificity molecular identification systems with vacuum-based detection.
Spectroscopy dominates installed base. Mass spectrometry is where expansion concentrates.
Application:
Cost tiers stratify sharply between validated pharmaceutical environments requiring ISO 17025 documentation and chemical production settings with less stringent measurement uncertainty requirements.
- Pharmaceutical Manufacturing:Regulated drug substance and drug product production with mandatory critical quality attribute monitoring. Biopharmaceutical facilities in Ireland and Switzerland lead procurement, compelled by EMA process validation guidelines for continued verification protocols.
- Chemical Production:Petrochemical and specialty chemical processing with environmental compliance overlays. US Gulf Coast refineries deploy PAT sensors under EPA emissions monitoring requirements, integrating with existing distributed control systems.
- Food Processing:Inline quality verification for beverage and dairy operations.
- Biotechnology:Cell culture and fermentation monitoring for monoclonal antibody production.
Pharmaceutical manufacturing commands premium pricing tiers. Biotechnology applications are climbing the fastest.
End User:
Volume concentration shifts toward contract manufacturers as biopharmaceutical firms outsource production, fragmenting traditional direct OEM relationships.
- OEMs:Original equipment manufacturers integrating PAT modules into complete production lines.
- Research Institutions:Academic and government laboratories developing chemometric models and validation protocols. MIT and ETH Zurich anchor method development pipelines, though multivariate analysis expertise scarcity constrains throughput.
- Analytical Laboratories:Third-party testing facilities supporting regulatory submissions.
- Contract Manufacturers:CDMOs and CMOs unbundling hardware procurement from lifecycle support services. Lonza and Catalent facilities in Singapore and Basel drive demand for gamma-sterilizable Raman probes compatible with single-use bioreactors.
Contract manufacturers represent the steepest expansion trajectory. Analytical laboratories retain stable replacement demand.
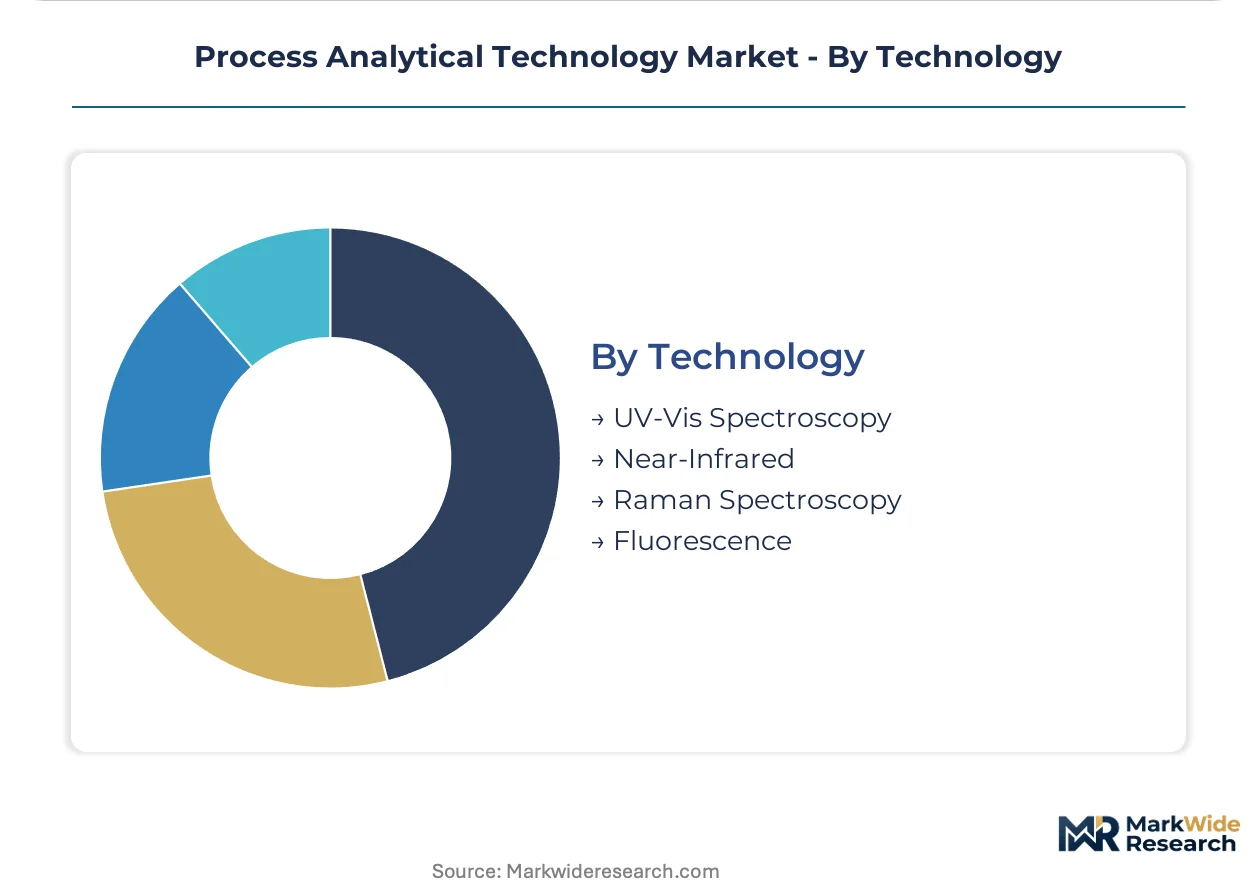
Technology:
Maturity gradients separate established UV-Vis platforms from emerging Raman systems with machine learning preprocessing capabilities.
- UV-Vis Spectroscopy:Mature absorption-based measurement for concentration determination in liquid streams. Generic drug manufacturers in India adopt these for raw material identity verification, eliminating quarantine inventory under CDSCO-aligned ICH guidelines.
- Near-Infrared:Diffuse reflectance and transmission probes for solid dosage and powder processing. Continuous direct compression lines in North America integrate NIR with feed control systems, displacing traditional batch testing.
- Raman Spectroscopy:Molecular fingerprinting through inelastic light scattering with minimal sample preparation. Aseptic fill-finish operations in Belgium deploy 1064 nm excitation systems for real-time environmental monitoring under revised EMA Annex 1 guidance.
- Fluorescence:High-sensitivity detection for trace-level impurity quantification.
UV-Vis holds mature installed density. Raman spectroscopy is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Quality by Design mandates and EMA process validation guidelines are redirecting capital toward pharmaceutical manufacturing corridors with established analytical infrastructure. Biopharmaceutical firms prioritize locations with dense instrumentation vendor ecosystems and regulatory precedent for real-time release testing.
United States
Biopharmaceutical contract manufacturers in Massachusetts and North Carolina are deploying Raman probes for monoclonal antibody production. FDA's Quality by Design framework compels documented measurement uncertainty for critical quality attributes. Greater Boston anchors method development pipelines, though multivariate analysis expertise scarcity constrains technology transfer velocity.
Germany
Chemical producers in Ludwigshafen and Frankfurt leverage chromatography platforms where separation resolution exceeds spectroscopic capability. EMA process validation guidelines accelerate capital allocation toward electrochemical sensor arrays in sterile drug substance production. The pharmaceutical corridor around Hesse and Baden-Württemberg concentrates demand for fiber-optic probe adaptability.
Switzerland
Swissmedic's alignment with ICH Q8-Q12 guidelines positions Basel as a procurement hub for PAT-qualified vendors serving biologics manufacturing. Continuous bioprocessing mandates compress validation timelines for spectroscopic platforms across the Rhine corridor. Lonza facilities drive demand for gamma-sterilizable probes compatible with single-use bioreactor expansion.
India
Generic API manufacturers in Hyderabad and Ahmedabad adopt UV-Vis systems for raw material identity verification under CDSCO-aligned ICH guidelines. CDSCO's regulatory convergence eliminates quarantine inventory holding periods, compressing working capital cycles. The pharmaceutical clusters in Telangana and Gujarat represent the steepest procurement expansion trajectory among emerging markets.
Belgium
Aseptic fill-finish operations deploy 1064 nm Raman systems for real-time environmental monitoring under revised EMA Annex 1 guidance. The country's national pharmaceutical regulator elevates viable and non-viable particle detection to critical process parameter status. Laser-induced breakdown spectroscopy replaces periodic grab-sampling for in-situ elemental contamination screening in Flanders.
Process Analytical Technology Market Key Industry Players
Player mix skews toward diversified instrumentation conglomerates with chromatography and spectroscopy portfolios. The vendor base concentrates around three strategic tiers: full-line analytical platform providers, specialized sensor technology developers, and contract manufacturing integrators. Competitive positioning hinges on ISO 17025 accreditation depth and pharmaceutical manufacturing contract density. Consolidation pressure intensifies as biopharmaceutical procurement teams unbundle hardware acquisition from lifecycle support services.
Within the full-line instrumentation tier, Thermo Fisher Scientific and Danaher Corporation exemplify divergent organizational architectures for sustaining instrumentation density. Waters Corporation occupies a position among mass spectrometry specialists serving bioprocess monitoring applications. These three entities anchor the competitive structure, with each representing distinct approaches to platform consolidation versus specialized best-of-breed lifecycle economics.
| Leading Market Players |
|---|
| Waters Corporation |
| Siemens AG |
| Thermo Fisher Scientific |
| Bruker Corporation |
| ABB Ltd. |
| Agilent Technologies |
| Mettler-Toledo International |
| PerkinElmer |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Scale economies in high-precision optical component fabrication concentrate manufacturing among German and Swiss suppliers, compressing price floors for spectroscopy platforms while elevating margins for gamma-sterilizable probe assemblies. This concentration shapes procurement leverage across pharmaceutical manufacturing networks.
Pricing Analysis
Certification level (ISO 17025/FDA-grade) creates the primary spread between premium and standard tiers. Three-tier pricing structure across validated pharmaceutical, chemical production, and generic manufacturing levels dominates, with FDA-grade documentation commanding substantial premiums over CDSCO-aligned ICH tiers. Cost compression in standard-grade sensor arrays is intensifying because Indian generic manufacturers consolidate procurement volumes. Contract manufacturers exhibit highest price sensitivity due to unbundled hardware and service contracts, while biopharmaceutical OEMs prioritize measurement uncertainty documentation over unit economics.
Supply Chain Analysis
Germany and Switzerland anchor high-precision grating and detector array production for Raman and mass spectrometry platforms. German optical specialists and Swiss MEMS foundries supply fiber-optic probe adaptability and vacuum system components that feed from semiconductor fab capacity. Single-source vulnerability in gamma-sterilizable probe membranes exposes instrument manufacturers to extended lead times. Distribution runs through pharmaceutical engineering firms for spectroscopy platforms and analytical laboratory distributors for chromatography systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multivariate analysis expertise scarcity constrains technology transfer velocity and fragments vendor relationships across biopharmaceutical manufacturing networks. This capability gap rewards players who control chemometric model development pipelines.
For Market Incumbents: Consolidate chemometric consultancy capabilities in Boston and Basel to defend against specialized service unbundling. Deepen backward integration into fiber-optic probe manufacturing to reduce German optical component dependency. Lock in ISO 17025 accreditation depth across manufacturing sites to maintain pharmaceutical contract density against emerging entrants. For New Entrants and Emerging Players: Anchor in Indian generic API clusters around Hyderabad and Ahmedabad where CDSCO-aligned ICH guidelines eliminate incumbent quarantine inventory advantages. Target UV-Vis raw material identity verification as the most penetrable segment given lower certification barriers. Pursue direct sales partnerships with CDMO procurement teams seeking faster technology transfer timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among chemometric consultancies with embedded validation protocol expertise. Long-term viability rests on controlling model development pipelines rather than hardware manufacturing. Signal to watch: biopharmaceutical procurement teams completing unbundling of lifecycle support services from hardware acquisition.| Strategic Initiative | Industry Significance |
|---|---|
| Chemometric Capability Acquisition | Controls FDA submission timelines for Raman probe deployments at Lonza facilities. |
| Gamma-Sterilizable Probe Manufacturing Scale-Up | Reduces dependency on German suppliers for single-use bioreactor compatibility. |
| ISO 17025 Accreditation Expansion | Unlocks EMA process validation contracts across sterile drug substance production. |
| Indian CDMO Partnership Development | Captures CDSCO-aligned procurement expansion in Telangana and Gujarat clusters. |
| Legacy DCS Integration Middleware Launch | Resolves data flow obstruction between smart sensors and manufacturing execution systems. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across biopharmaceutical manufacturing, contract manufacturing, and analytical instrumentation domains. Primary interviews with PAT implementation managers, regulatory affairs specialists at FDA and EMA, CDMO procurement directors, and chromatography platform engineers combined with secondary validation from FDA Quality by Design guidance documents, EMA process validation guidelines, SEC 10-K instrumentation disclosures, and ISO 17025 accreditation registries. Bottom-up installation base modeling and top-down pharmaceutical capital expenditure triangulation anchored value estimates.
Across the analysis window, projections incorporate measurement modality segmentation, application tier stratification, and regional regulatory cluster differentiation. CAGRs derive from patent filing trajectories, announced manufacturing capacity expansions, and regulatory guidance revision schedules. Continuous bioprocessing adoption curves and single-use bioreactor deployment rates inform biopharmaceutical demand assumptions.
Material uncertainties — semiconductor fab capacity constraints, reference standard scarcity for complex biologics, and ICH Q12 method transfer equivalence study delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory convergence timelines and chemometric training pipeline expansion. Recalibration cycles align with material shifts in FDA guidance revisions and EMA Annex 1 updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
United States Material Testing Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Paper Moisture Meter Market
Testing Equipment
Sample Preparation Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Adhesive Tester Market
Testing Equipment
Chemical Detector Market
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Global Chiral Chromatography Column Market
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Elemental Analysis Market
Testing Equipment
Laboratory Centrifuge and Accessories Market
Testing Equipment
Solid Density Tester Market