
 U-Tube Viscometer Market | 2026-2036
U-Tube Viscometer Market Size, Share, and Industry Trends Forecast 2026-2036
U-Tube Viscometer Market Analytics
Equipment leasing and pay-per-test service contracts is tilting competitive dynamics toward asset-light entrants. Anton Paar leverages its Austrian manufacturing base to sustain premium positioning in high-precision glass instruments. Cannon Instrument anchors North American demand through deep calibration service networks. PSL Rheotek specializes in automated digital systems for high-throughput pharmaceutical workflows.
A U-tube viscometer measures fluid kinematic viscosity by timing flow between two calibrated bulbs through a vertical capillary, typically operating at temperatures from 20°C to 150°C with bath-controlled thermal stability. Laboratories represent the mature core application where replacement cycles dominate purchasing patterns. Oil and gas quality control represents the fastest-growing application segment as refiners tighten feedstock characterization protocols. Digital delivery mode instruments command margin premiums over manual glass units due to embedded temperature compensation and automated data logging.
FDA cGMP guidelines and EMA ICH Q2(R1) validation standards shape instrument qualification requirements in pharmaceutical settings. ISO 3104 and ASTM D445 govern petroleum testing protocols that determine product acceptance across international trade. ASTM D446 and ISO 3105 calibrate capillary dimensions that manufacturers must certify for regulatory compliance. Stakeholders should monitor evolving pharmacopeial harmonization between USP, EP, and JP chapters that could unify or fragment qualification burdens across major markets.
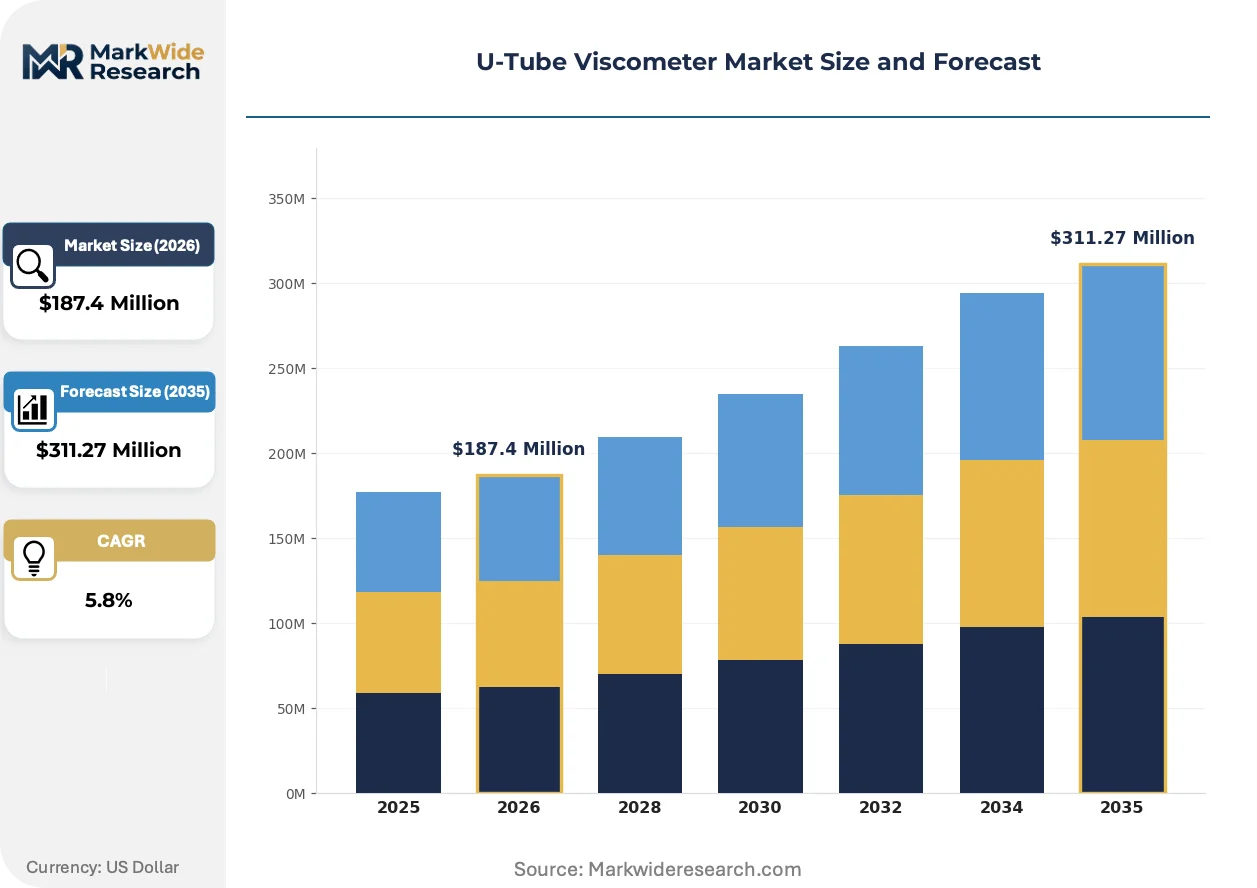
Market Dynamics
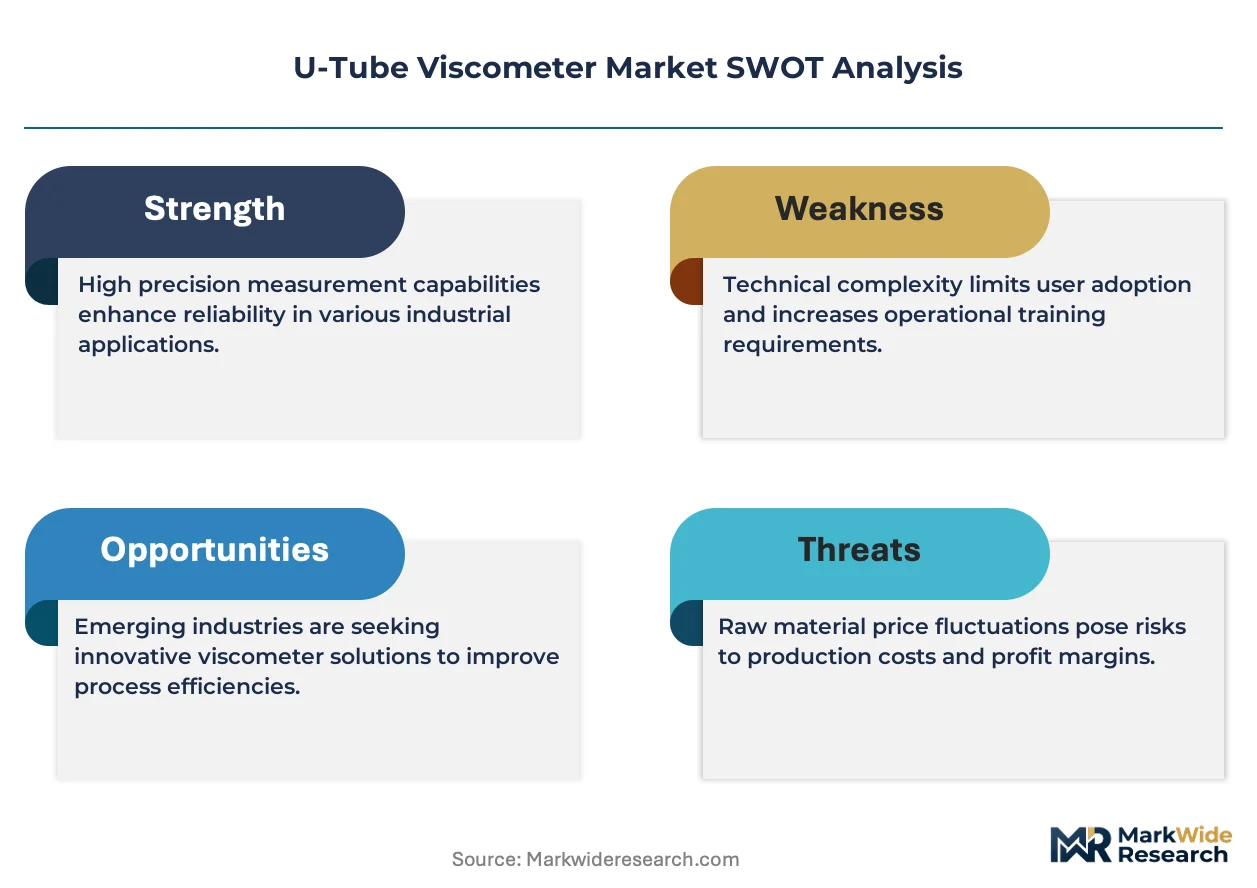
Equipment leasing and pay-per-test service contracts are compressing capital expenditure cycles for laboratory procurement, tilting competitive dynamics toward asset-light entrants and fragmenting traditional instrument ownership models across pharmaceutical and petroleum testing verticals.
Growth Catalysts
- FDA cGMP and EMA ICH Q2(R1) mandates:Tightened purity verification requirements in pharmaceutical quality control labs drive instrument replacement and qualification spending.
- Refinery feedstock characterization protocols:Oil and gas quality control departments accelerate kinematic viscosity testing to meet tightening product acceptance standards.
- Embedded temperature compensation:Digital delivery mode instruments with automated data logging command procurement preference over manual glass units in high-throughput workflows.
Market Restraints
- Borosilicate glass supply concentration:Specialty glass feedstock for precision capillary manufacturing concentrates among limited European and Japanese suppliers, exposing production schedules to input volatility.
- ASTM D446 and ISO 3105 certification burden:Mandatory capillary dimension calibration and documentation requirements extend qualification timelines and inflate compliance costs for new market entrants.
- Rotational viscometer substitution:Alternative viscosity measurement technologies with broader shear-rate ranges capture share in non-standard fluid applications.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO-aligned quality control infrastructure buildout creates instrument procurement demand among domestic generic API producers.
- Automated digital-robotic convergence:Integration of sample handling robotics with digital viscometry opens high-throughput contract testing service models.
- Equipment-as-a-service channels:Leasing and per-test billing models penetrate mid-tier laboratories previously priced out of precision instrument ownership.
Industry Challenges
- Metrology technician scarcity:Qualified personnel for capillary calibration and thermal bath maintenance remain concentrated among aging specialist workforces in Germany and Japan.
- Legacy LIMS integration complexity:Digital viscometer data streams require custom middleware development to interface with established laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | U-Tube Viscometer Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Automatic, Digital Application: Laboratories, Oil & Gas, Food Processing, Chemical Manufacturing End User: Research Institutes, Pharmaceutical Companies, Quality Control Labs, Educational Institutions Delivery Mode: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Anton Paar, Grupo Selecta, Xylem, Koehler Instrument, Hindustan Apparatus, Cannon Instrument, Thermo Fisher Scientific, PCE Instruments, PSL Rheotek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
U-Tube Viscometer Market Evolving Landscape
Digital automation and regulatory harmonization are compressing traditional instrument replacement cycles while reshaping how viscosity data is captured, validated, and integrated into enterprise quality systems across pharmaceutical and petroleum testing environments.
Microprocessor-controlled thermal baths with embedded Peltier elements are rendering obsolete water-jacketed analog temperature control systems. Pharmaceutical quality control laboratories in Germany and Switzerland are adopting these units at accelerated replacement cycles. The elimination of manual temperature logging and bath maintenance is rendering obsolete the service revenue models of traditional calibration providers.
REACH restrictions on borosilicate glass manufacturing inputs are tightening supply chain compliance documentation requirements for European instrument assemblers. Manufacturers must now certify raw material provenance through smelter and supplier audits. German and Austrian producers are responding by qualifying alternative glass feedstock sources and accelerating in-house capillary drawing capabilities.
Service contract unbundling is fragmenting traditional instrument-sales-plus-maintenance bundles into separately priced calibration, repair, and software update lines. Mid-tier contract testing laboratories in the United States are driving this disaggregation to match cash outflows with test volume revenues. The shift is most visible in independent petroleum testing facilities seeking to minimize fixed cost exposure during feedstock price volatility periods.
U-Tube Viscometer Market Segmentation
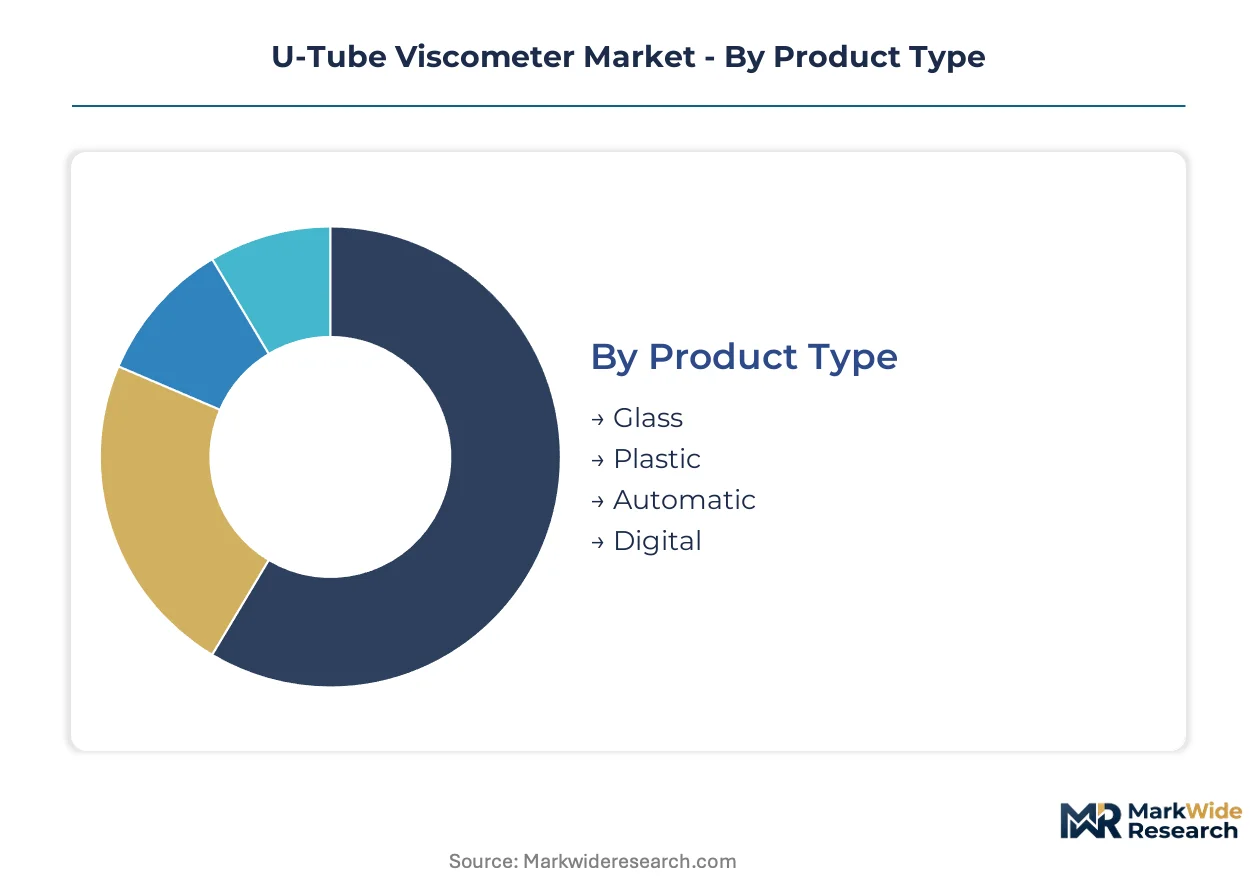
U-tube viscometer procurement patterns diverge sharply across material specifications, automation levels, and end-user sophistication. Segment boundaries determine margin capture, replacement cycles, and regulatory qualification burdens for manufacturers.
Product Type:
Mature glass instruments anchor established laboratories while automated systems capture emerging digital workflows.
- Glass:Borosilicate construction delivers thermal stability from 20°C to 150°C with capillary precision certified to ASTM D446. Pharmaceutical quality control labs in Germany and Switzerland sustain replacement demand as FDA cGMP mandates tighten instrument qualification protocols.
- Automatic:Microprocessor-controlled thermal baths with embedded Peltier elements eliminate manual temperature logging. High-throughput pharmaceutical workflows in North American contract testing facilities drive accelerated procurement cycles.
- Plastic:Disposable polystyrene variants serve educational demonstrations and single-use contamination-sensitive applications.
- Digital:Embedded temperature compensation and automated data logging command procurement preference over manual units.
Glass handles the majority of throughput; Automatic is the fastest mover on share.
Application:
Cost tier separation distinguishes capital-intensive petroleum testing from budget-constrained educational use.
- Laboratories:Mature core segment where replacement cycles dominate purchasing patterns. ISO 3104 and ASTM D445 compliance requirements sustain instrument refresh rates among established analytical facilities.
- Oil & Gas:Refinery feedstock characterization protocols accelerate kinematic viscosity testing to meet tightening product acceptance standards. International trade verification drives premium instrument specification.
- Food Processing:Viscosity monitoring for sauce, beverage, and dairy consistency control.
- Chemical Manufacturing:Process control and raw material incoming inspection applications.
Laboratories absorb the largest equipment volume; Oil & Gas is expanding most quickly on share.
End User:
Customer type determines specification stringency from research-grade precision to educational durability.
- Quality Control Labs:FDA cGMP and EMA ICH Q2(R1) validation standards shape instrument qualification requirements. Tightened purity verification mandates drive replacement spending among pharmaceutical manufacturers.
- Pharmaceutical Companies:CDSCO-aligned infrastructure buildout in India creates procurement demand among domestic generic API producers.
- Research Institutes:Custom capillary dimension requirements for non-standard fluid characterization.
- Educational Institutions:Cost-sensitive procurement favoring manual glass units for undergraduate instruction.
Quality Control Labs command the dominant procurement volume; Pharmaceutical Companies are climbing the fastest on share.
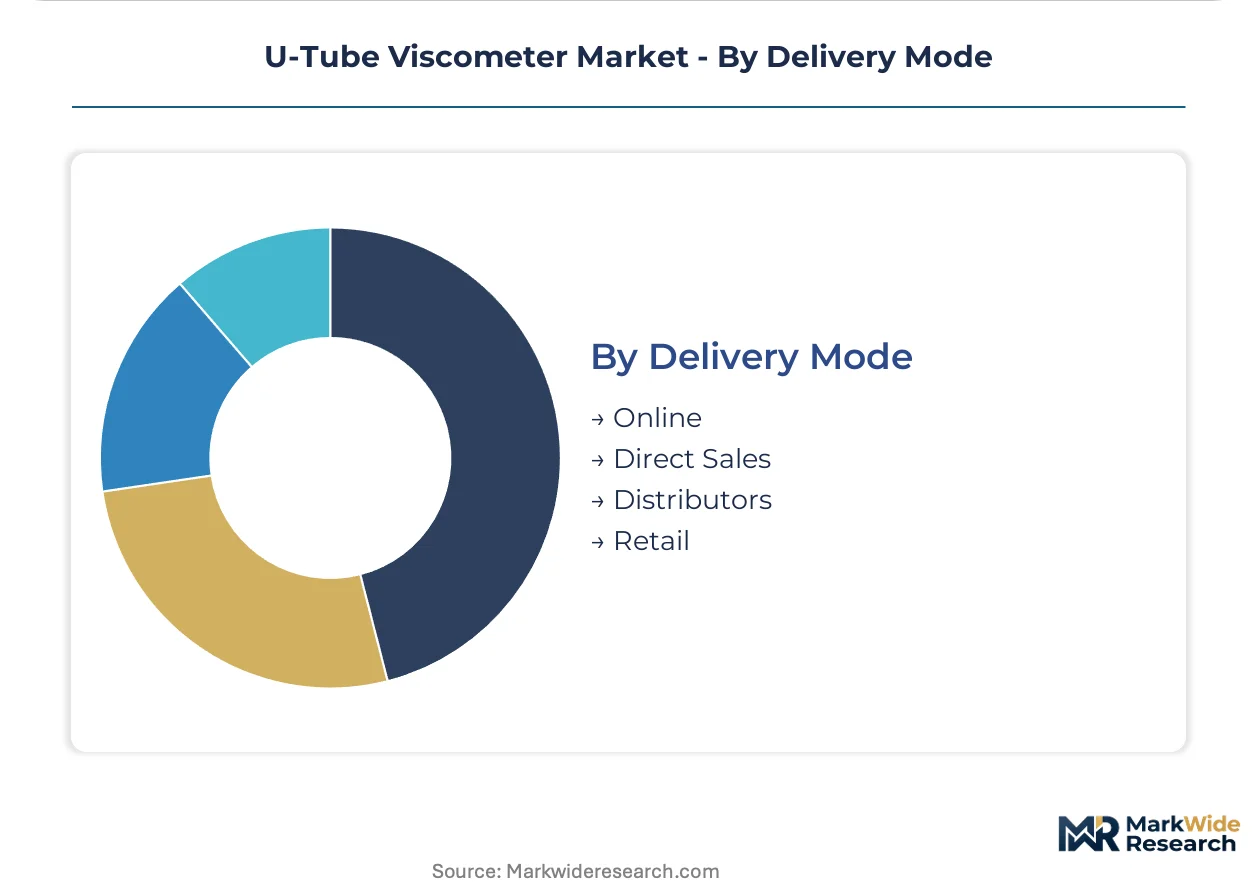
Delivery Mode:
Supply concentration shapes channel economics from direct manufacturer relationships to fragmented retail distribution.
- Direct Sales:Premium instrument manufacturers in Austria and Germany maintain captive relationships with large pharmaceutical and petroleum testing accounts. Deep calibration service networks anchor long-term contracts.
- Distributors:Regional stocking and technical support penetration across mid-tier laboratories previously priced out of precision instrument ownership.
- Online:Specification-driven procurement for standardized replacement capillaries and consumables.
- Retail:Limited educational and entry-level instrument availability through scientific supply catalogs.
Direct Sales captures the highest value transactions; Distributors are gaining share fastest among mid-tier accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in precision laboratory instruments favor net-importing markets with stringent regulatory verification regimes. Germany, the United States, and Japan dominate procurement volumes while India and China expand domestic manufacturing capacity to reduce import dependency.
United States
Pharmaceutical quality control labs in New Jersey and North Carolina drive replacement demand as FDA cGMP mandates tighten instrument qualification protocols. The US Pharmacopeia (USP) Chapter 911 governs viscometer performance verification requirements. Houston-area petroleum testing facilities anchor oil and gas application demand through refinery feedstock characterization contracts.
Germany
REACH restrictions on borosilicate glass manufacturing inputs are tightening supply chain compliance documentation requirements for European instrument assemblers. The country's national chemical regulator enforces raw material provenance certification through smelter audits. Bavarian and Baden-Württemberg precision glass workshops are accelerating in-house capillary drawing capabilities to qualify alternative feedstock sources.
Japan
Metrology technician scarcity for capillary calibration and thermal bath maintenance concentrates among aging specialist workforces in Osaka and Nagoya industrial clusters. METI standards govern laboratory instrument import certification procedures. Tokyo-area pharmaceutical manufacturers sustain premium glass instrument demand through tightened purity verification mandates aligned with PMDA guidelines.
India
CDSCO-aligned quality control infrastructure buildout creates instrument procurement demand among domestic generic API producers in Gujarat and Maharashtra. The country's national pharmaceutical regulator mandates equipment qualification documentation for export-oriented manufacturing facilities. Hyderabad and Bangalore contract testing laboratories are adopting equipment-as-a-service models to minimize fixed cost exposure.
Switzerland
Swissmedic oversight of pharmaceutical manufacturing equipment validation sustains premium instrument specification among Basel-area biologics producers. Microprocessor-controlled thermal bath adoption accelerates replacement cycles in German-speaking cantons. Zurich and Geneva quality control facilities command margin premiums for automated digital systems with embedded temperature compensation.
U-Tube Viscometer Market Competitive Landscape
On the supply side, the industry is consolidating around Austrian and German precision manufacturers with captive calibration service networks. Three strategic archetypes dominate: premium glass instrument specialists with vertical manufacturing control, automated digital system providers serving high-throughput pharmaceutical workflows, and regional distributors penetrating mid-tier laboratories through leasing arrangements. M&A activity targets calibration service capabilities while portfolio diversification extends into consumables and per-test billing models.
Within the premium-tier vector, Anton Paar exemplifies Austrian manufacturing-base positioning sustained through precision glass instrument specialization. Cannon Instrument anchors North American demand architecture through deep calibration service networks. PSL Rheotek occupies a position representing automated digital system convergence for pharmaceutical quality control workflows.
| Leading Market Players |
|---|
| Anton Paar |
| Grupo Selecta |
| Xylem |
| Koehler Instrument |
| Hindustan Apparatus |
| Cannon Instrument |
| Thermo Fisher Scientific |
| PCE Instruments |
| PSL Rheotek |
| Others |
Value Network & Pricing Analysis
Overcapacity in German precision glass workshops is compressing capillary tube margins while simultaneously accelerating backward integration among Austrian instrument assemblers seeking supply security against REACH documentation burdens.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on ASTM D446 certification grade and embedded temperature compensation capability, with digital-automated units commanding substantial premiums over manual glass alternatives. Pricing pressure stems from equipment-as-a-service penetration among mid-tier contract testing laboratories. Educational institutions exhibit highest price sensitivity, while pharmaceutical quality control labs demonstrate lowest elasticity due to FDA cGMP qualification requirements.
Supply Chain Analysis
Specialty borosilicate glass feedstock draws from concentrated European and Japanese smelter operations, with German and Austrian producers accelerating in-house capillary drawing capabilities. Critical dependencies include precision bore tubing, Peltier thermal elements, and microprocessor control modules. Single-source vulnerability in pharmaceutical-grade glass certification exposes production schedules to regulatory audit delays. Distribution runs through direct manufacturer relationships with large accounts, supplemented by regional distributors penetrating mid-tier laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pharmaceutical contract testing conglomerates consolidating instrument procurement across multi-site networks, compressing vendor margins and demanding unbundled service contracts.
For Market Incumbents: Pre-empt rotational viscometer substitution by embedding automated sample handling robotics into digital U-tube platforms. Accelerate captive calibration service network expansion in India to defend against CDSCO-aligned infrastructure buildout. Deepen backward integration into precision glass feedstock to offset REACH supply chain documentation burdens.
For New Entrants and Emerging Players: Establish a beachhead in Indian generic API producer quality control labs through equipment-as-a-service financing models. Target petroleum testing facilities in Houston seeking to minimize fixed cost exposure during feedstock price volatility. Penetrate via distributor partnerships offering unbundled calibration and repair lines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated digital system providers with embedded software update streams and per-test billing capabilities. Five-to-ten year viability favors manufacturers with in-house capillary drawing and certified calibration laboratory assets. Monitor pharmacopeial harmonization progress between USP, EP, and JP chapters as inflection signal for qualification burden consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Glass | Mitigates REACH supply chain documentation exposure for Austrian and German assemblers. |
| Automated Sample Handling Robotics | Opens high-throughput contract testing service models in North American pharmaceutical workflows. |
| Equipment-as-a-Service Launch | Penetrates mid-tier laboratories previously priced out of precision instrument ownership. |
| Calibration Service Network Expansion | Anchors long-term contracts with large pharmaceutical and petroleum testing accounts. |
| Pharmacopeial Harmonization Monitoring | Anticipates unified or fragmented qualification burdens across FDA, EMA, and PMDA jurisdictions. |
Research Methodology
A standing panel of metrology laboratory directors, pharmaceutical quality control managers, petroleum testing facility engineers, and precision glass manufacturing specialists provided ongoing calibration against secondary data. Primary fieldwork combined structured interviews with instrument procurement officers and aftermarket service heads. Secondary validation drew from FDA cGMP guidance documents, EMA ICH Q2(R1) validation standards, ASTM D445 and D446 protocol specifications, and ISO 3104/3105 calibration requirements. Bottom-up segment sizing triangulated against top-down trade flow analysis.
Scenario bracketing around regulatory harmonization timelines and borosilicate glass supply volatility shaped projection boundaries across the analysis window. Segmentation dimensions modeled include product type, automation level, application vertical, end-user sophistication, and geographic regulatory cluster. CAGRs were derived from instrument replacement cycle analysis and procurement pattern elasticity. Industry-specific inputs incorporated pharmaceutical manufacturing capacity expansion in India and refinery feedstock characterization protocol tightening.
Stress conditions across REACH enforcement intensity, metrology technician retirement rates, and rotational viscometer price-performance improvement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory qualification burden evolution and equipment-as-a-service adoption curves. Cross-checking against customs trade data for precision laboratory instrument imports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Chlorine Meter Market
Testing Equipment
Water Test Kits Market
Testing Equipment
Europe Process Analytics Market
Testing Equipment
North America Dissolved Gas Analyzer Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Oxidation Stability Analyzer Market
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Global Adsorption Equipment Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
Combustion Testing Equipment Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Water Testing Equipment Market
Testing Equipment
Flammability Tester Market