
 Air Cargo Software Market | 2026-2036
Air Cargo Software Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cargo Software Market Analysis
Germany's cargo hub modernization around Frankfurt and Leipzig-Halle is reconfiguring how European carriers source air cargo software. IBS Software leverages its heritage in aviation IT to sustain long-term contracts with full-service airlines seeking integrated operations platforms. AltexSoft competes through specialized engineering services for mid-tier freight forwarders building custom cargo management systems. Innowise anchors its position in Eastern European markets with hybrid deployment expertise serving logistics operators transitioning from on-premise legacy stacks.
Air cargo software encompasses digital platforms that automate freight booking, capacity allocation, unit load device tracking, and customs documentation across airline and logistics networks, typically integrating with IATA ONE Record standards and real-time messaging protocols like Cargo-IMP and Cargo XML. Freight forwarding software dominates current revenue as consolidation among global forwarders drives demand for multi-carrier rate management and shipment visibility. Cloud-based deployment represents the fastest-expanding segment, though on-premise systems retain strongholds among flag carriers with stringent data sovereignty requirements. AI-enabled cargo management systems are capturing disproportionate R&D investment as airlines deploy predictive analytics for yield optimization and irregular operations recovery.
IATA operational standards, EU F-Gas Regulation emissions tracking mandates, and Germany's KBA oversight of ground transport interfaces collectively shape product roadmaps and certification requirements for vendors serving European carriers. The EU AI Act introduces new compliance layers for automated cargo scheduling and pricing algorithms, compelling software providers to embed explainability features and audit trails. Stakeholders must monitor how regulatory fragmentation between EU emissions frameworks and national aviation authority interpretations affects cross-border software deployment timelines and integration costs.
Market Dynamics
Freight forwarders are consolidating multi-modal shipment management onto unified digital platforms, forcing software vendors to integrate real-time messaging protocols with emissions tracking modules mandated by tightening environmental regulations.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain carriers must deploy sensor networks for refrigerant leak detection and temperature integrity documentation, accelerating IoT platform procurement.
- Freight forwarder consolidation:Large logistics groups demand single-pane visibility across ocean, air, and ground modes, pulling integrated cargo management suites into enterprise IT stacks.
- AI-enabled yield optimization:Airlines deploy predictive analytics for capacity allocation and dynamic pricing, embedding machine learning modules into core operations software.
Market Restraints
- Data sovereignty requirements:Flag carriers in Germany and France mandate on-premise hosting for customs and security data, constraining cloud-native vendor expansion.
- Legacy system entrenchment:Decades-old Cargo-IMP messaging infrastructure at major European hubs creates technical debt that complicates API-first platform migration.
- Integration cost volatility:Custom middleware development for airline-specific ERP configurations drives implementation timelines and budgets beyond initial forecasts.
Strategic Opportunities
- Eastern European logistics modernization:Polish and Romanian freight operators are replacing Soviet-era tracking systems, creating demand for hybrid cloud deployment expertise.
- EU AI Act explainability mandates:Automated cargo scheduling algorithms require embedded audit trails, opening specialized compliance tooling markets for software vendors.
- Blockchain-IoT convergence:Pharmaceutical shippers seek immutable chain-of-custody records for temperature-sensitive cargo, merging distributed ledger with sensor telemetry platforms.
Industry Challenges
- Aviation IT talent scarcity:Specialized knowledge of IATA ONE Record standards and Cargo XML messaging protocols concentrates among veteran developers approaching retirement.
- Multi-standard certification complexity:Vendors must simultaneously satisfy Germany's KBA ground transport interface rules, EU emissions frameworks, and airline-specific security audits.
- Legacy stack integration friction:Real-time data synchronization between modern cloud platforms and mainframe-based weight-and-balance systems requires expensive custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cargo Software Market |
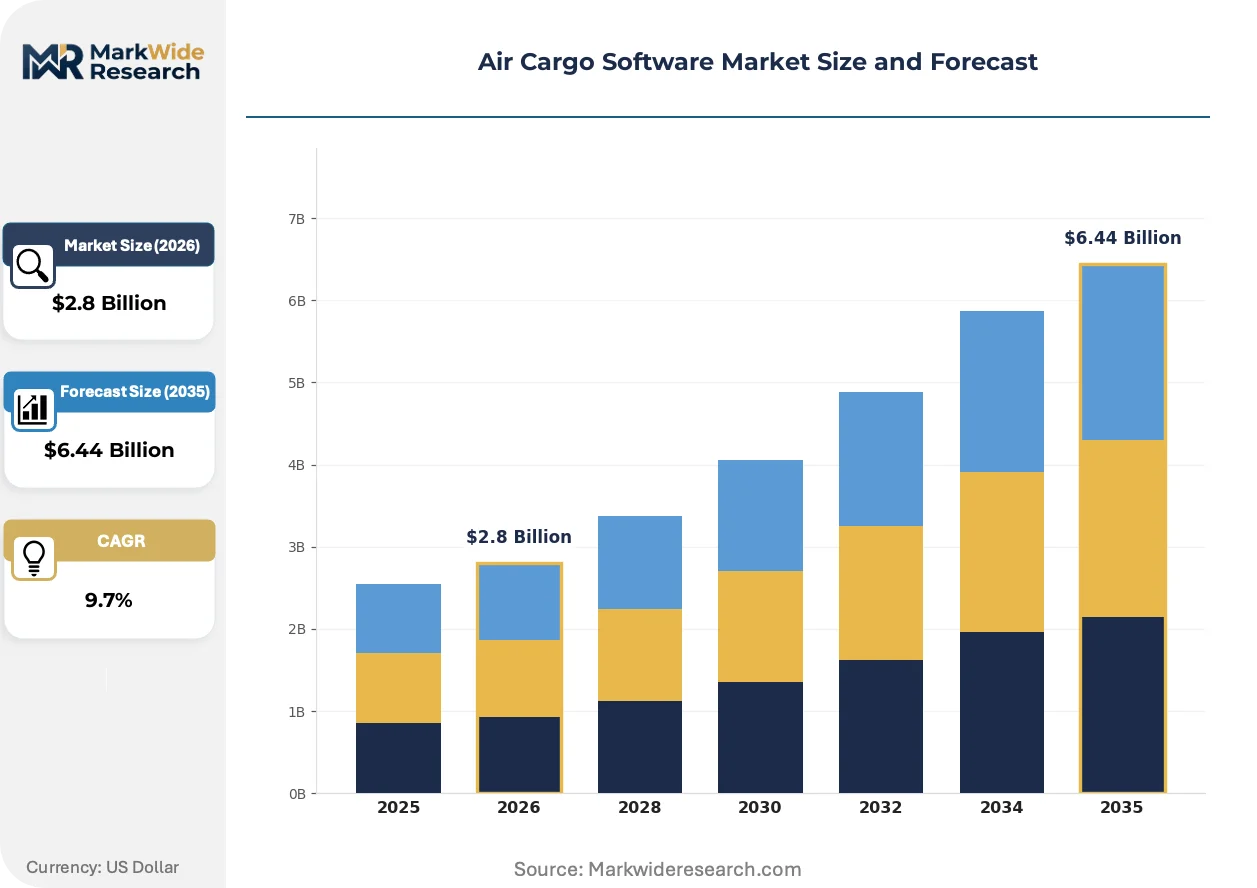
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freight Forwarding Software, Cargo Management Systems, Tracking Solutions, Airline Operations Software Deployment: On-premise, Cloud-based, Hybrid, Managed Services End User: Airlines, Freight Forwarders, Ground Handlers, Logistics Operators Technology: AI, IoT, Blockchain, Data Analytics |
| Companies Covered | FreightPOP, Inc., Stfalcon, IBS Software, Ardas, AltexSoft, OLINTEK, Innowise, DreamzTech Solutions, COAX Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cargo Software Market Emerging Trajectories
Digital infrastructure is fragmenting across deployment models as carriers balance regulatory compliance against scalability demands, while sensor networks and algorithmic decision-making penetrate deeper into cargo operations.
Edge computing architectures are hybridizing with centralized cloud platforms to process sensor telemetry from unit load devices during flight. Regional carriers operating short-haul European routes adopt these distributed systems to maintain cold-chain visibility without satellite connectivity gaps. This architecture is hybridizing traditional batch-data workflows with real-time streaming analytics, compressing response times for temperature excursions from hours to minutes.
Germany's KBA oversight of ground transport interfaces now requires standardized data exchange formats between air cargo terminals and trucking fleets. The regulation forces software vendors to rebuild customs integration modules around mandated API specifications rather than proprietary protocols. Full-service airlines with extensive European road feeder networks face the steepest reconfiguration costs and timeline pressures.
Pharmaceutical shippers are unbundling visibility services from freight contracts, procuring temperature monitoring as standalone software subscriptions rather than bundled logistics fees. This disintermediation redirects procurement decisions from carrier sales teams to supply chain IT departments with distinct vendor evaluation criteria. German and Dutch pharmaceutical clusters exhibit the most advanced adoption of this decoupled purchasing model.
Air Cargo Software Market Segmentation
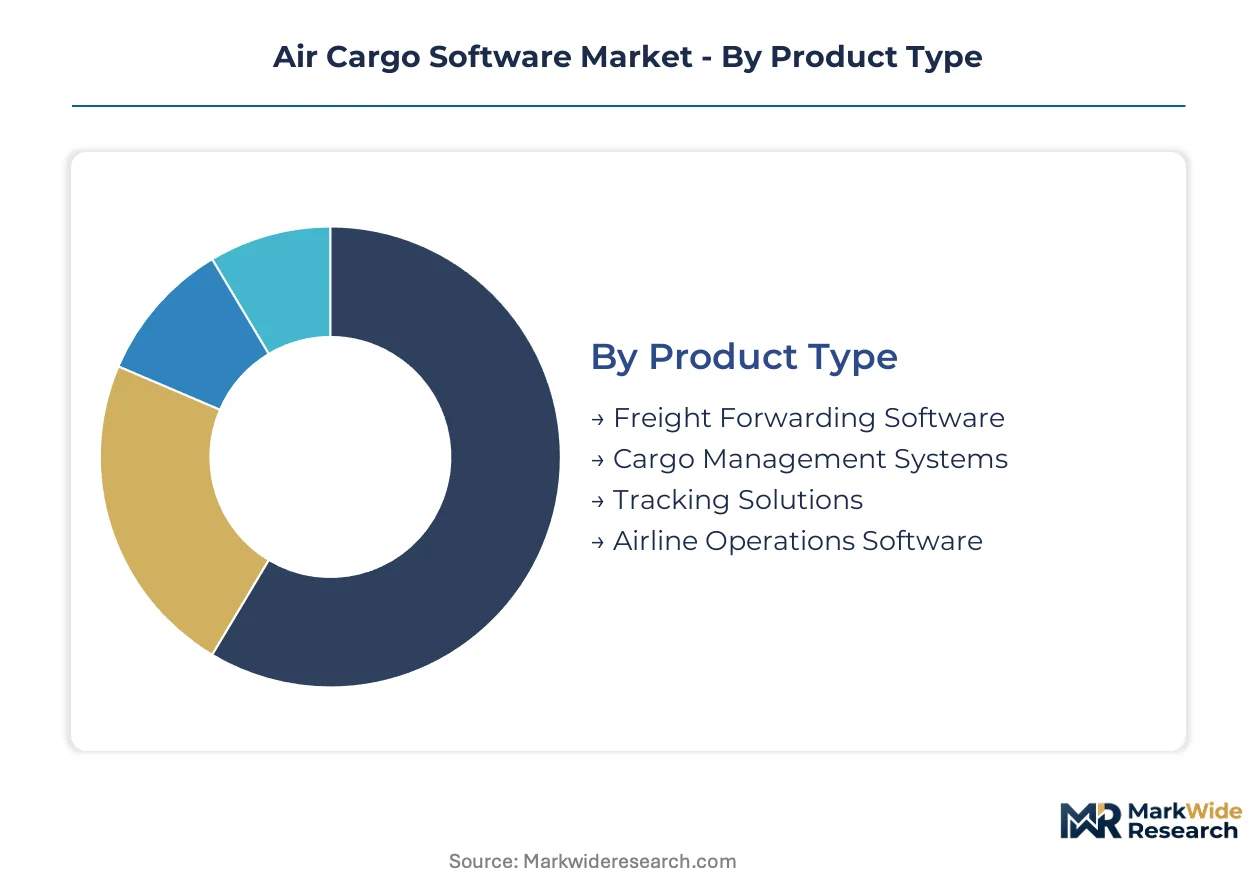
Air cargo software procurement patterns diverge sharply across deployment models and end-user operational requirements. Each segmentation dimension captures distinct purchasing authority centers, from airline IT departments prioritizing data sovereignty to freight forwarders seeking API-first multi-carrier platforms.
Product Type:
Cost tier structures software procurement decisions, with enterprise-grade suites commanding substantially higher implementation budgets than point solutions.
- Freight Forwarding Software:Multi-carrier rate management platforms consolidate ocean, air, and ground bookings through unified interfaces. Global logistics groups in Germany and the Netherlands drive consolidation onto these systems as they absorb regional forwarders and demand single-pane visibility.
- Cargo Management Systems:Core operational platforms automate capacity allocation, weight-and-balance calculations, and unit load device tracking. Flag carriers with extensive European networks prioritize these systems for IATA ONE Record compliance and real-time messaging protocol integration.
- Tracking Solutions:Sensor-telemetry platforms for cold-chain monitoring and ULD geolocation.
- Airline Operations Software:Integrated suites spanning passenger and cargo revenue management.
Freight Forwarding Software holds installed capacity. Cargo Management Systems is rotating up the share rankings.
Deployment:
Application environment determines regulatory compliance pathways and total cost of ownership trajectories for European carriers.
- Cloud-based:Scalable SaaS architectures enable rapid feature deployment and reduced infrastructure overhead. Mid-tier freight forwarders and logistics startups adopt these platforms fastest, though German flag carriers resist migration due to KBA data sovereignty requirements for customs interfaces.
- On-premise:Dedicated hardware installations within carrier data centers satisfy stringent security audits and national aviation authority mandates. French and German legacy operators maintain these deployments for core revenue management systems despite higher maintenance burdens.
- Hybrid:Split architectures processing sensitive customs data on-premise while leveraging cloud analytics for non-critical operations.
- Managed Services:Outsourced infrastructure and application management hosted by specialized aviation IT providers.
On-premise retains anchor tenant status among flag carriers. Cloud-based is climbing the fastest as vendor security certifications mature.
End User:
Customer type dictates functional requirements, integration complexity, and procurement cycle length across the value chain.
- Freight Forwarders:Logistics intermediaries requiring multi-carrier rate shopping, shipment consolidation, and customs documentation automation. Consolidation among global forwarders in Rotterdam and Hamburg pulls integrated suites into enterprise IT stacks with 18-36 month implementation timelines.
- Airlines:Full-service and cargo-only carriers seeking yield optimization, network planning, and regulatory compliance modules. Lufthansa Cargo and Air France-KLM anchor demand for AI-enabled capacity allocation and emissions tracking aligned with EU F-Gas Regulation mandates.
- Ground Handlers:Terminal operators managing warehouse management, build-up/break-down, and truck dock coordination.
- Logistics Operators:Integrated supply chain providers spanning warehousing, last-mile delivery, and freight brokerage.
Airlines hold installed capacity. Freight Forwarders is rotating up the share rankings.
Technology:
Maturity curves for enabling technologies determine R&D allocation and partnership strategies among software vendors.
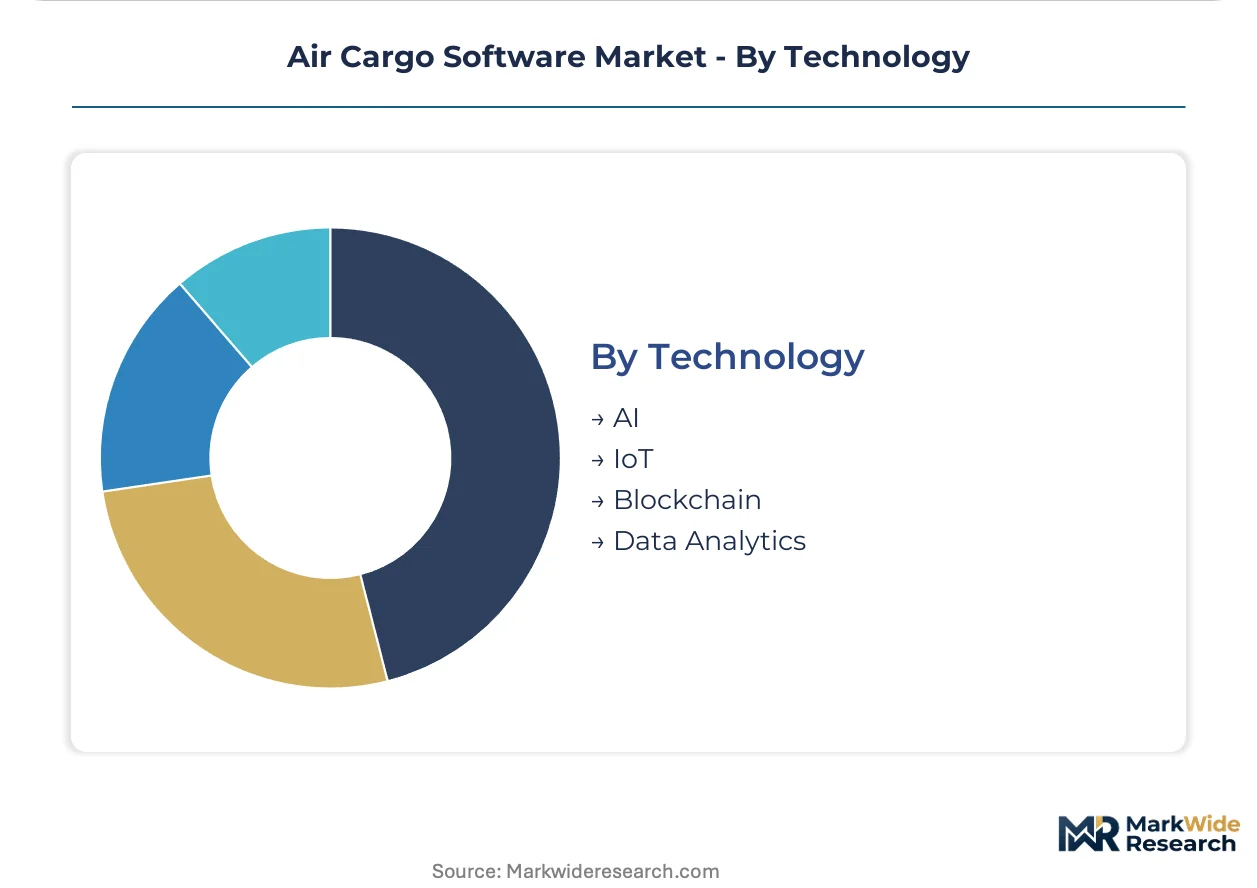
- AI:Predictive analytics for demand forecasting, dynamic pricing, and irregular operations recovery. EU AI Act explainability mandates now require embedded audit trails for automated cargo scheduling algorithms, compelling vendors to rebuild decision engines with interpretable model architectures.
- IoT:Sensor networks for temperature monitoring, refrigerant leak detection, and ULD geolocation. Pharmaceutical shippers in Frankfurt and Basel deploy these systems for F-Gas Regulation compliance and immutable chain-of-custody documentation.
- Blockchain:Distributed ledger platforms for document verification and smart contract automation.
- Data Analytics:Business intelligence tools for performance benchmarking and network optimization.
Data Analytics holds installed capacity. AI is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software vendors cluster around major cargo hubs where regulatory complexity and freight volume intersect. Frankfurt, Leipzig-Halle, and Amsterdam anchor European procurement decisions for integrated cargo management platforms.
Germany
Frankfurt and Leipzig-Halle cargo hubs drive ground handling coordination software procurement. KBA oversight mandates standardized data exchange formats between air terminals and trucking fleets. Pharmaceutical clusters in Frankfurt-Rhine-Main deploy temperature monitoring systems for F-Gas Regulation compliance.
Netherlands
Rotterdam and Amsterdam logistics groups consolidate multi-modal operations onto unified platforms. EU AI Act explainability requirements shape vendor selection for automated scheduling algorithms. Schiphol cargo handlers integrate customs modules with road feeder networks under Dutch customs authority specifications.
United States
Freight forwarders in Chicago and Memphis demand API-first multi-carrier rate management. FAA messaging standards govern Cargo-IMP to Cargo XML migration timelines. Dallas-Fort Worth cargo operators invest in predictive analytics for irregular operations recovery.
United Kingdom
London Heathrow handlers modernize warehouse management systems for post-Brexit customs complexity. UK Border Force data requirements constrain cloud deployment options for security-sensitive operations. East Midlands cargo cluster adopts hybrid architectures processing customs data on-premise with cloud analytics.
Poland
Freight operators replace Soviet-era tracking systems with hybrid cloud deployment expertise. EU F-Gas Regulation drives cold-chain sensor network procurement for pharmaceutical exports. Warsaw and Krakow logistics hubs attract software vendors serving Eastern European modernization cycles.
Air Cargo Software Market Vendor Landscape
Aviation IT heritage specialists and engineering services boutiques split the market between integrated suites and custom builds. Tier structure reflects deployment model specialization rather than scale concentration. Full-service platform vendors and modular point-solution developers represent distinct strategic archetypes. Partnerships with ground handling networks and acquisitions of sensor-telemetry capabilities dominate competitive moves.
Within the heritage aviation IT tier, IBS Software occupies a position exemplifying long-term airline contract structures. AltexSoft and Innowise represent the engineering services archetype, with the former anchoring mid-tier freight forwarder custom development and the latter sitting within Eastern European hybrid deployment expertise. These three vendors illustrate how geographic origin and company structure correlate with strategic positioning across cloud-native and on-premise implementation vectors.
| Leading Market Players |
|---|
| FreightPOP, Inc. |
| Stfalcon |
| IBS Software |
| Ardas |
| AltexSoft |
| OLINTEK |
| Innowise |
| DreamzTech Solutions |
| COAX Software |
| Others |
Supply Flow & Price Mechanics
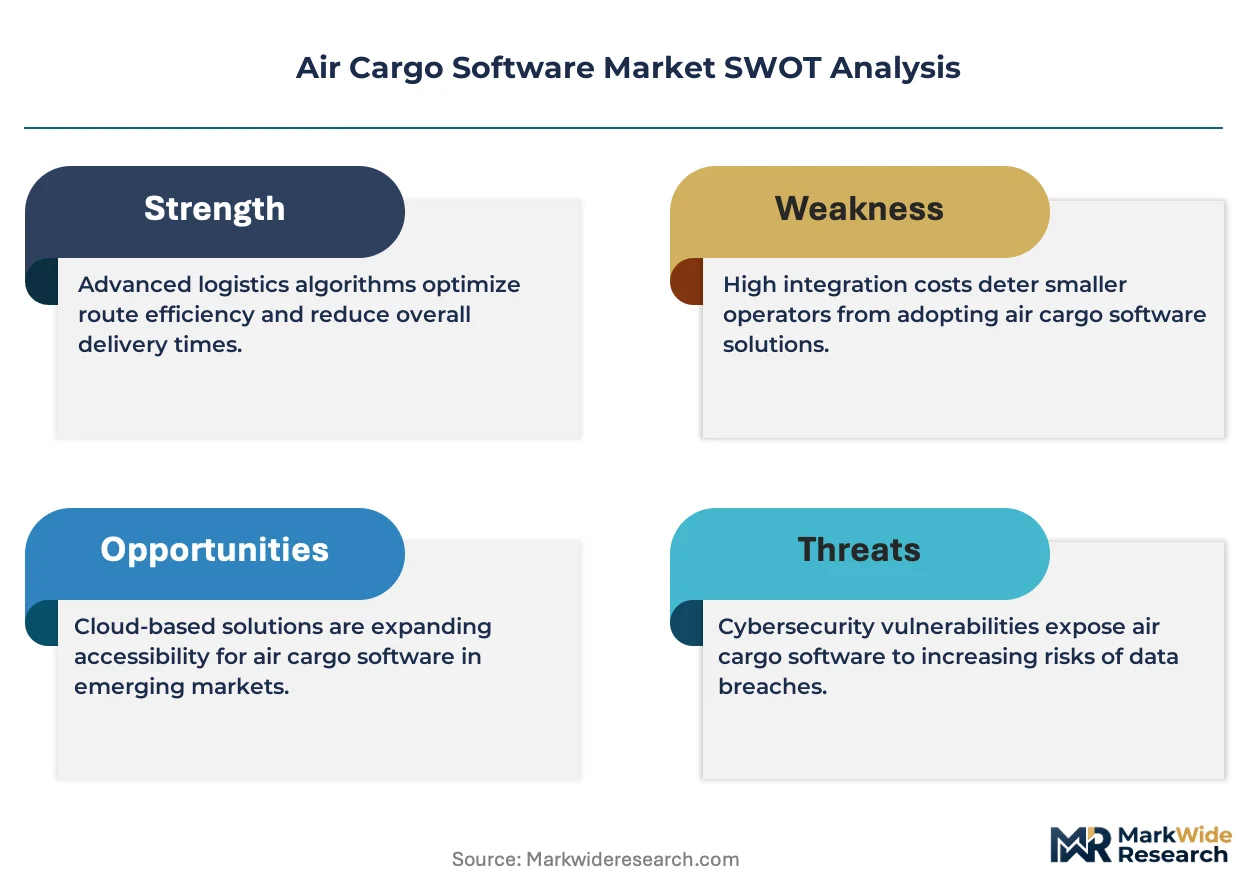
The Frankfurt-Leipzig cargo corridor concentrates procurement power among German freight forwarders consolidating onto unified platforms, compressing vendor margins while amplifying price differentiation between cloud-native entrants and legacy system providers with KBA-certified on-premise installations.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure for cold-chain monitoring modules, separating premium sensor-telemetry suites with full refrigerant leak detection from standard tracking solutions lacking emissions documentation capabilities. Certification grade and customization level drive price differentiation, with KBA-compliant ground transport interfaces commanding substantial premiums over generic API configurations. Pricing pressure stems from mid-tier freight forwarders demanding SaaS-tiered subscription models that undercut traditional perpetual licensing. Logistics startups and Polish freight operators exhibit the highest price sensitivity, while Lufthansa Cargo and Air France-KLM anchor the least sensitive tier with long-term enterprise contracts.
Supply Chain Analysis
Extended payment terms from German flag carriers and supply-chain finance facilities from Dutch logistics groups shape vendor working capital requirements across the software ecosystem. Development talent concentrates in Germany, Poland, and India, with aviation IT expertise anchored in Frankfurt and Warsaw engineering clusters. Raw material dependencies include cloud infrastructure from hyperscalers, sensor hardware from East Asian manufacturers, and specialized IATA messaging protocol libraries. Single-source vulnerability sits with veteran developers possessing Cargo-IMP and ONE Record standards knowledge approaching retirement. Distribution runs through direct enterprise sales teams serving major carriers, supplemented by systems integrators penetrating mid-tier forwarder markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated freight forwarders in Rotterdam and Hamburg, forcing vendors to accept compressed margins and accelerated implementation timelines as procurement authority shifts from airline IT departments to logistics group enterprise architects.
For Market Incumbents: Harden cloud-native platform security certifications to satisfy German KBA data sovereignty requirements while embedding explainability features for EU AI Act compliance. Defensive consolidation through acquisition of Eastern European engineering boutiques with hybrid deployment expertise offsets margin pressure from freight forwarder procurement consolidation. Prioritize backward integration into sensor-telemetry hardware to capture pharmaceutical shipper demand for unbundled visibility subscriptions. For New Entrants and Emerging Players: Pursue white-space opportunities in Polish and Romanian freight operator modernization cycles, where Soviet-era tracking system replacement creates demand for hybrid cloud expertise without incumbent lock-in. Target mid-tier forwarders in the Netherlands seeking API-first multi-carrier platforms with faster deployment than legacy aviation IT vendors. Go-to-market through systems integrator partnerships accelerates penetration of ground handler warehouse management modernization at London Heathrow and East Midlands. For Investors and Strategic Acquirers: Engineering services boutiques with IATA ONE Record implementation track records and Eastern European delivery footprints represent the most viable acquisition archetype for platform vendors seeking hybrid deployment capabilities. Long-term viability hinges on regulatory compliance tooling moats deepening around EU AI Act explainability mandates and F-Gas emissions documentation requirements. Monitor pharmaceutical shipper procurement decentralization from carrier sales teams to supply chain IT departments as the inflection signal for standalone visibility platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies Cargo-IMP legacy messaging with ONE Record APIs for German flag carrier compliance. |
| Acquisition of Specialist Firm | Captures Eastern European hybrid deployment expertise serving Polish freight modernization. |
| Strategic Partnership | Links sensor-telemetry vendors with pharmaceutical shippers in Frankfurt-Rhine-Main clusters. |
| Product Launch | Introduces EU AI Act-compliant explainability modules for automated cargo scheduling algorithms. |
| Geographic Expansion | Establishes delivery presence in Romanian logistics hubs replacing Soviet-era tracking infrastructure. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline cargo IT directors, freight forwarder platform engineers, ground handling operations managers, and pharmaceutical supply chain architects. Secondary validation drew from IATA operational standard filings, EU F-Gas Regulation implementation guidelines, KBA ground transport interface specifications, and customs integration protocol documentation. Bottom-up triangulation across vendor implementation pipelines and top-down reconciliation against cargo volume forecasts anchored market size estimates.
Calibration against historical adoption curves for cloud migration in aviation IT and regulatory compliance investment cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user operational category, technology enablement layer, and regional regulatory cluster. CAGRs were derived from trend extrapolation of freight forwarder consolidation patterns and AI-enabled yield optimization R&D allocation trajectories, cross-referenced with sensor-telemetry platform procurement cycles in pharmaceutical cold-chain applications.
Macroeconomic conditions sit as an overlay; deviation in European logistics capital expenditure cycles and cloud infrastructure cost trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and legacy system replacement rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Account-Based Advertising Software Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
Petcare Software Market
Software & Services
Solar Rooftop Design Software Market
Software & Services
Chatbot Builder Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Transient Analysis Software Market
Software & Services
Talent Acquisition Software Market
Software & Services
Application Platform As a Service Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Global Construction Punch List Software Market
Software & Services
Virtual Client Computing Software Market
Software & Services
Cloud-Based Payroll Software Market
Software & Services
PCB Design Software Market
Software & Services
Employee Wellness Software Market
Software & Services
Cloud Communication Platform Software Market