
 Global Municipal Software Market | 2026-2036
Global Municipal Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Municipal Software Market Foresight
Subscription-based software-defined feature layers is decoupling perpetual licensing from municipal procurement cycles. Tyler Technologies leverages vertical integration across public safety and tax collection modules to sustain deployment flexibility. OpenGov anchors cloud-native budgeting and transparency workflows for mid-sized city governments. Springbrook Software specializes in utility billing and fund accounting for smaller municipal authorities.
Municipal software encompasses integrated digital platforms that automate administrative, financial, and operational functions for local government entities, typically incorporating GIS mapping interfaces, multi-fund accounting engines, and API-driven interoperability with state and federal reporting systems. Cloud-based deployment models are capturing the fastest expansion as legacy on-premises systems face obsolescence, while citizen engagement solutions concentrate margin pools where open-data mandates require real-time transparency dashboards. Asset management segments dominate installed base value given the capital intensity of infrastructure lifecycle tracking across water, road, and building portfolios.
EPA environmental compliance frameworks and ISO 37120 smart city indicators shape product roadmaps for vendors serving North American and European municipalities, while Japan's METI promotes digital government standards that accelerate procurement of integrated platforms. GDPR and sector-specific data residency requirements in Europe constrain cloud architecture choices for vendors handling citizen financial records. Stakeholders must weigh interoperability commitments against the fragmentation risk posed by municipally customized implementations that resist standardization.
Market Dynamics
Cloud migration is compressing municipal procurement cycles from multi-year capital appropriations to annual operating expenditures, forcing incumbent vendors to restructure pricing architectures around consumption-based billing rather than perpetual licenses.
Growth Catalysts
- EPA environmental reporting mandates:Water utilities in the United States face escalating documentation requirements for contaminant tracking, accelerating replacement of spreadsheet-based compliance with automated sensor-to-report platforms.
- ISO 37120 smart city indicators:European municipalities pursuing certification under this framework must deploy standardized data collection infrastructure for urban service benchmarking, creating procurement pull for integrated analytics modules.
- Japan METI digital government standards:The ministry's interoperability protocols for local government systems are consolidating previously fragmented software procurement across prefectural boundaries.
Market Restraints
- GDPR data residency requirements:European municipalities handling citizen financial records must maintain sovereign cloud infrastructure, doubling deployment costs versus North American equivalents.
- Legacy system technical debt:COBOL-based tax administration platforms in older US cities resist API integration, forcing expensive middleware layers for interoperability.
- Specialized talent scarcity:Municipal IT departments lack personnel conversant in both public sector accounting standards and contemporary DevOps practices, elongating implementation timelines.
Strategic Opportunities
- India smart city mission:The country's urban transformation program is funding integrated command-and-control centers across 100 municipalities, opening greenfield deployment opportunities without legacy displacement costs.
- Predictive maintenance convergence:Machine learning models trained on infrastructure sensor data are enabling shift from scheduled to condition-based asset renewal, extending capital planning horizons.
- Subscription bundling innovation:Vendors are packaging citizen engagement, permitting, and billing modules into unified SaaS suites, reducing procurement friction for mid-sized city governments.
Industry Challenges
- Interoperability certification delays:State-level variations in financial reporting formats prevent standardized API development, forcing vendors to maintain jurisdiction-specific code branches.
- Cybersecurity skill gaps:Municipal IT departments struggle to recruit personnel capable of securing distributed IoT sensor networks against ransomware targeting critical infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Municipal Software Market |
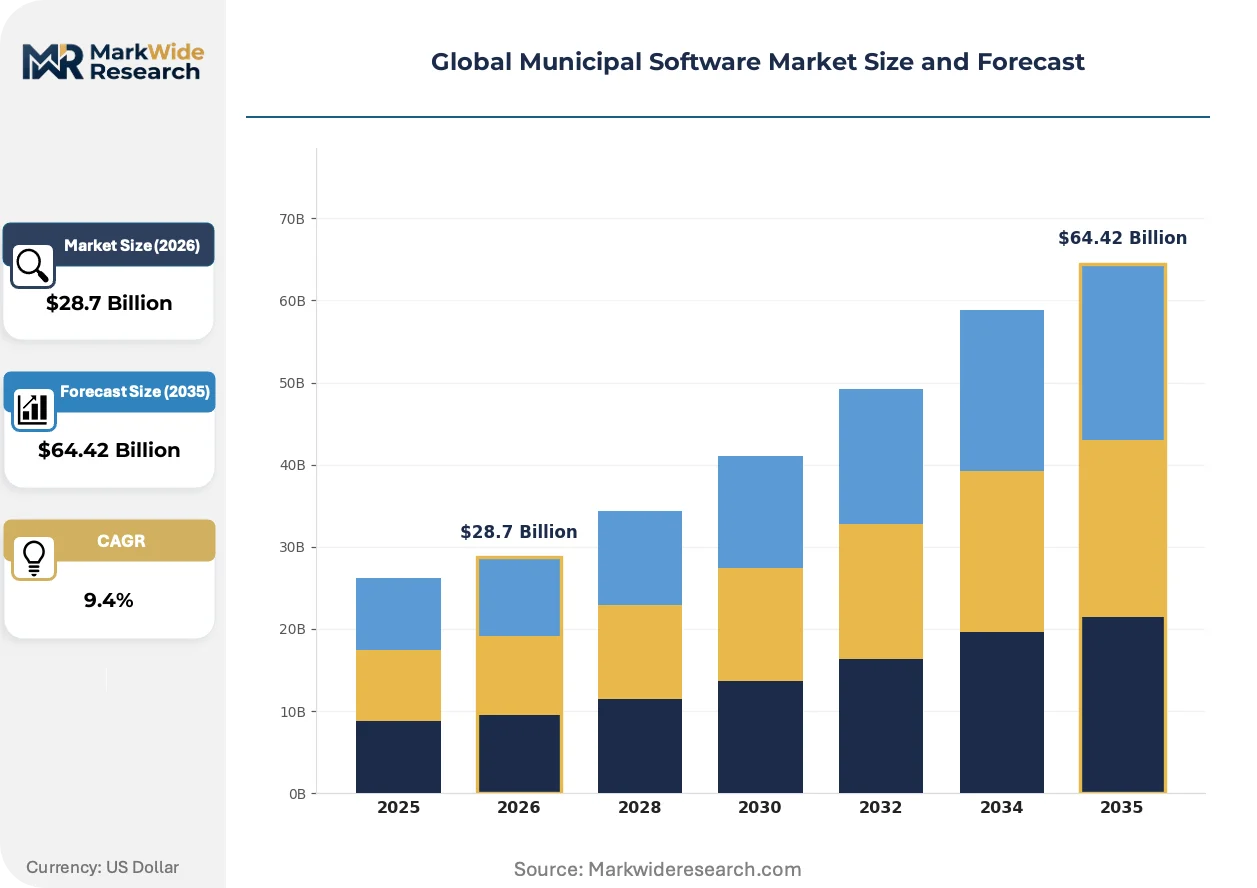
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $64.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Citizen Engagement, Asset Management, Tax Collection, Permit Management, Public Safety, Regulatory Compliance Deployment Model: On-Premises, Cloud-Based, Hybrid Cloud, Software as a Service, Private Cloud, Community Cloud End User Type: City Governments, Local Authorities, Municipal Utilities, Public Transportation Agencies, Educational Boards, Cultural Organizations Application Area: Urban Planning, Waste Management, Emergency Response, Public Health Monitoring, Infrastructure Maintenance, Traffic Management |
| Companies Covered | Red Wing Software, TownSuite, Tyler Technologies, OpenGov, Caselle, Sage, MIP Fund Accounting, Springbrook Software, AccuFund, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Municipal Software Market Shifts & Advancements
Artificial intelligence is penetrating municipal operations through predictive models that anticipate infrastructure failure before physical symptoms manifest, compressing maintenance response windows from weeks to hours.
Digital twin technology is rewriting how US water utilities manage distribution networks. Metropolitan districts in California and Texas are deploying real-time hydraulic simulations that mirror physical pipe conditions. These virtual replicas enable scenario testing for main break responses without service disruption, compressing emergency planning cycles from quarterly tabletop exercises to continuous optimization.
EU CSRD sustainability disclosure requirements are mandating granular carbon accounting across municipal building portfolios. German and Dutch city governments must now track embodied emissions in infrastructure procurement, forcing software vendors to integrate lifecycle assessment databases directly into capital planning modules. Public works departments are responding by embedding environmental cost calculations into routine project prioritization workflows.
Subscription contracting is displacing perpetual license purchases among mid-sized North American municipalities. Finance directors in cities between 50,000 and 250,000 residents are shifting capital budget line items to operating expenditures, preferring annual SaaS commitments that align with property tax collection cycles. This behavioral pivot is most visible in permitting and licensing software categories, where vendors now compete on implementation speed rather than customization depth.
Global Municipal Software Market Segmentation
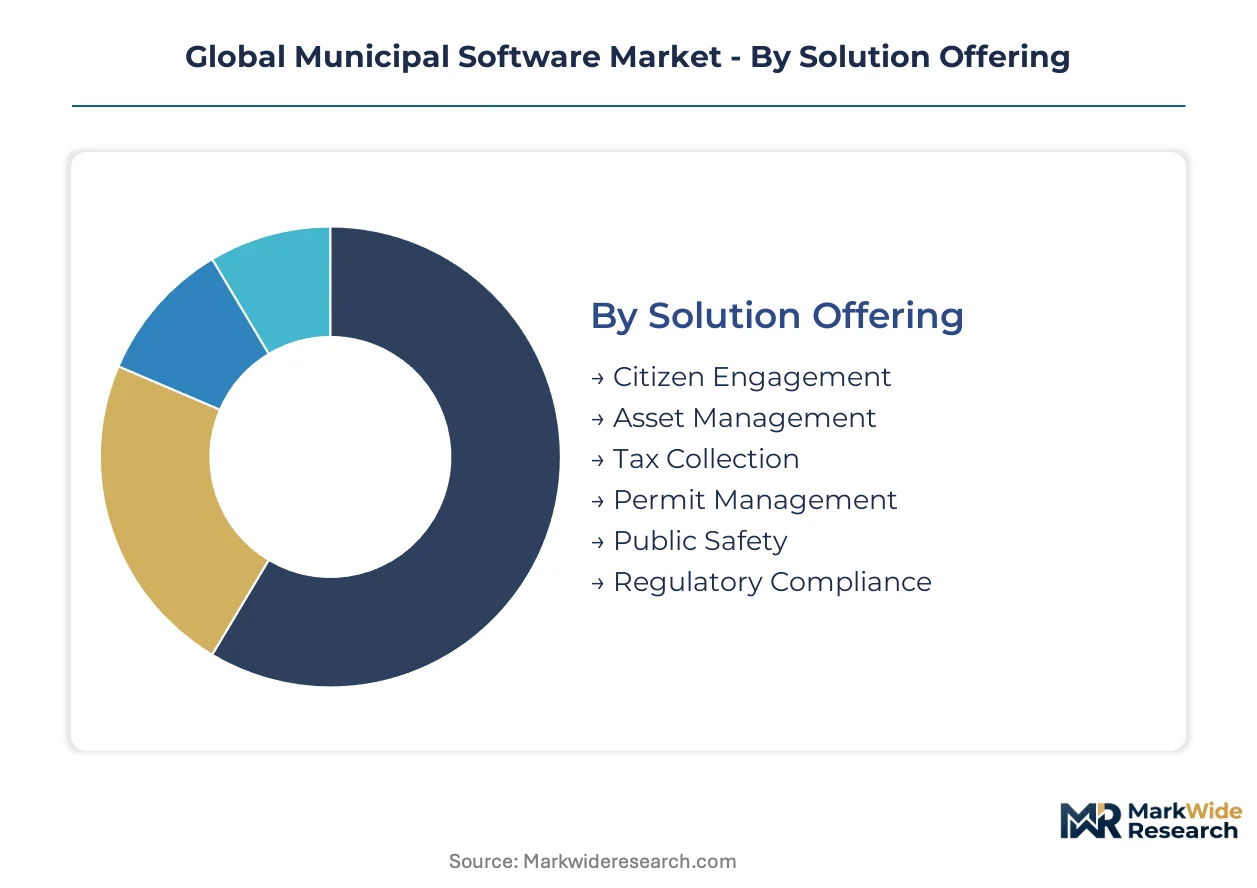
Municipal software procurement patterns diverge sharply by institutional scale and technical maturity. Segmentation reveals where integrated platforms displace point solutions versus where standalone modules persist.
Solution Offering:
Standalone modules dominate smaller municipalities with limited IT staff, while enterprise suites consolidate across digitally mature city governments.
- Asset Management:GIS-integrated platforms track infrastructure lifecycles across water, road, and building portfolios. German city governments pursuing ISO 37120 certification drive demand for sensor-connected predictive maintenance modules.
- Regulatory Compliance:Automated reporting engines ingest sensor data to generate EPA-aligned environmental documentation. United States water utilities face the steepest procurement pressure as contaminant tracking mandates intensify.
- Citizen Engagement:Cloud-native transparency dashboards serve open-data mandates.
- Tax Collection:Multi-fund accounting engines handle complex property assessment workflows.
- Permit Management:Digital workflow platforms accelerate building and business licensing approvals.
- Public Safety:Computer-aided dispatch and records management systems serve police and fire departments.
Volume placements concentrate in Asset Management; the faster expansion belongs to Regulatory Compliance.
Deployment Model:
Cost tier structures separate capital-intensive on-premises installations from operational-expenditure SaaS contracts preferred by mid-sized municipalities.
- Cloud-Based:Multi-tenant architectures enable rapid deployment without municipal data center investment. United States cities between 50,000 and 250,000 residents favor annual subscriptions aligned with property tax cycles.
- Software as a Service:Pre-configured modules reduce implementation timelines from years to months. Japanese prefectures consolidate procurement through METI-aligned interoperability standards.
- On-Premises:Legacy installations persist where data residency requirements restrict off-premise storage.
- Hybrid Cloud:Sensitive financial data remains local while citizen-facing services migrate to public infrastructure.
- Private Cloud:Dedicated instances serve municipalities with stringent security classifications.
- Community Cloud:Shared infrastructure pools costs across adjacent municipal authorities.
Deployment gravity favors SaaS for new procurement; hybrid architectures gain share among jurisdictions navigating GDPR constraints.
End User Type:
Application complexity varies by entity scale, with specialized utilities requiring deeper vertical functionality than general-purpose city governments.
- City Governments:Integrated platforms span finance, permitting, and citizen services. United States municipalities lead replacement of COBOL-based legacy systems with API-native alternatives.
- Municipal Utilities:Water and electricity providers demand asset-intensive modules with predictive maintenance capabilities. German utilities embed lifecycle carbon accounting to satisfy EU CSRD disclosure requirements.
- Local Authorities:County and regional governments coordinate multi-jurisdictional service delivery.
- Public Transportation Agencies:Fleet and route optimization systems integrate with traffic management infrastructure.
- Educational Boards:Student information and facility management modules serve K-12 districts.
- Cultural Organizations:Grant tracking and event permitting tools support library and museum operations.
Procurement volume clusters in City Governments; Municipal Utilities demonstrate the steepest technology refresh cycles.
Application Area:
Maturity gradients separate established domains with standardized data models from emerging areas requiring custom integration.
- Infrastructure Maintenance:Digital twin technology enables real-time hydraulic simulation for water distribution networks. Metropolitan districts in California and Texas deploy virtual replicas for main break scenario testing.
- Public Health Monitoring:Syndromic surveillance platforms aggregate clinic data for outbreak detection. The COVID-19 pandemic accelerated permanent procurement of integrated health dashboards in United States counties.
- Urban Planning:Zoning and land-use modules support comprehensive plan updates.
- Waste Management:Route optimization and container sensor networks improve collection efficiency.
- Emergency Response:Computer-aided dispatch coordinates multi-agency incident management.
- Traffic Management:Signal optimization and congestion pricing systems integrate with connected vehicle infrastructure.
Revenue concentration sits with Infrastructure Maintenance; Public Health Monitoring climbs the fastest as pandemic-era investments institutionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors municipal software innovation through its open-data initiatives and civic tech procurement programs. City governments across the United States, Germany, and Japan are expanding adoption of cloud-based asset management and citizen engagement platforms. Demand concentrates where EPA-aligned environmental reporting mandates intersect with ISO 37120 smart city standards.
United States
Water utilities in California and Texas deploy digital twin technology for real-time hydraulic simulation of distribution networks. EPA contaminant tracking mandates are accelerating replacement of spreadsheet-based compliance with automated sensor-to-report platforms. Metropolitan districts in Los Angeles and Houston lead infrastructure lifecycle tracking adoption.
Germany
German city governments pursuing ISO 37120 certification drive demand for standardized data collection infrastructure. EU CSRD sustainability disclosure requirements mandate granular carbon accounting across municipal building portfolios. The Rhine-Ruhr metropolitan region embeds lifecycle assessment databases into capital planning workflows.
Japan
Japanese prefectures consolidate procurement through METI-aligned interoperability protocols for local government systems. The Kanto region including Tokyo deploys integrated command-and-control centers for urban service benchmarking. Cloud-native budgeting platforms capture share among mid-sized municipal authorities.
India
The Smart Cities Mission funds integrated command-and-control centers across 100 municipalities without legacy displacement costs. State-level urban transformation programs prioritize greenfield deployment of API-native alternatives to paper-based systems. Maharashtra and Gujarat lead procurement of predictive maintenance modules for water infrastructure.
United Kingdom
British local authorities navigate GDPR data residency requirements through sovereign cloud infrastructure deployments. The Greater London Authority mandates real-time transparency dashboards for open-data compliance. Manchester and Birmingham accelerate permitting and licensing software replacement cycles.
Global Municipal Software Market Competitive Landscape
Capital-heavy platform developers compete with asset-light vertical specialists across the municipal software value chain. The vendor base organizes around three strategic tiers: enterprise suite providers with multi-module integration, point-solution specialists dominating single-function categories, and emerging SaaS-native entrants compressing implementation timelines. Dominant competitive moves include subscription-based pricing restructuring and API interoperability certification investments.
Within the enterprise suite tier, Tyler Technologies and OpenGov occupy positions representing vertical integration breadth and cloud-native workflow specialization respectively. Springbrook Software exemplifies the utility-billing point-solution archetype serving smaller municipal authorities. These three anchors illustrate how procurement scale and technical maturity stratify competitive positioning across city government segments.
| Leading Market Players |
|---|
| Red Wing Software |
| TownSuite |
| Tyler Technologies |
| OpenGov |
| Caselle |
| Sage |
| MIP Fund Accounting |
| Springbrook Software |
| AccuFund |
| Others |
Supply & Pricing Matrix
Cloud-native multi-tenant architectures are compressing deployment economics while concentrating development talent in North American and European software hubs, simultaneously lowering marginal delivery costs and tightening vendor pricing power around subscription retention metrics.
Pricing Analysis
Outcome-linked pricing tied to uptime guarantees and citizen service completion rates anchors enterprise municipal contracts. Three-tier pricing structure across premium, standard, and economy levels separates ISO 37120-certified analytics suites from basic compliance modules and entry-level SaaS offerings. Pricing pressure stems from mid-sized cities consolidating vendor relationships to reduce procurement overhead. Finance directors in the 50,000-250,000 resident segment demonstrate highest price sensitivity; large metropolitan utilities with EPA mandates show lowest.
Supply Chain Analysis
Cross-border data transmission costs and sovereign cloud infrastructure requirements inflate deployment expenses for European implementations. Software development concentrates in the United States, Germany, and India, with Indian engineering centers feeding back-end development for global platforms. Raw material dependencies include specialized GIS mapping data licenses, cybersecurity certification services, and API interoperability testing frameworks. Single-source vulnerability runs through hyperscaler cloud infrastructure providers. Distribution runs through direct municipal sales teams supplemented by systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
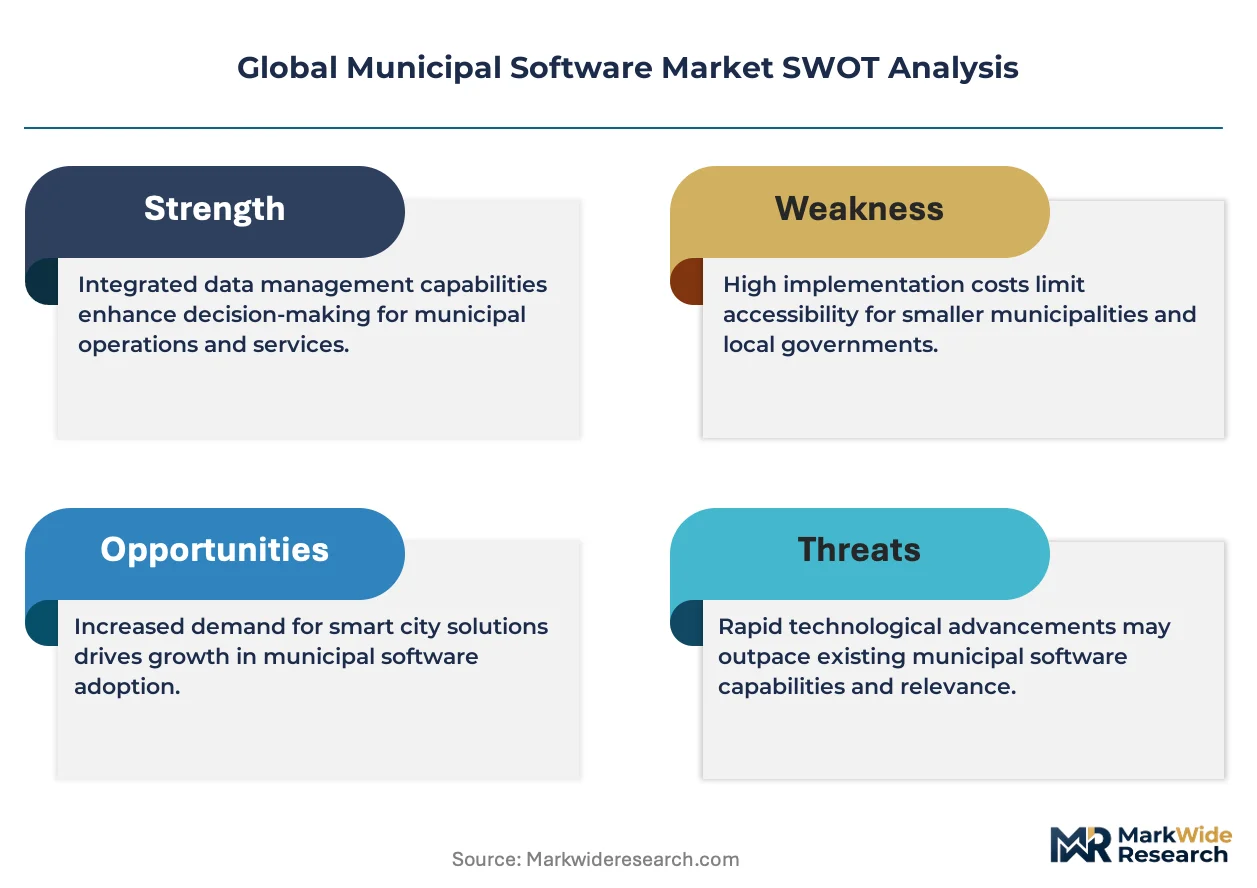
This market operates as a cost-of-compliance story where EPA environmental reporting mandates and ISO 37120 certification requirements create substantial barrier-to-entry moats for vendors with established regulatory alignment.
For Market Incumbents: Acquire predictive maintenance algorithm libraries and digital twin simulation engines to deepen infrastructure lifecycle capabilities. Defend against SaaS-native entrants by accelerating API interoperability certification across state-level financial reporting variations. Prioritize backward integration into sensor hardware partnerships for water utility deployments. For New Entrants and Emerging Players: EPA contaminant tracking mandates in the United States open a window for specialized compliance modules targeting spreadsheet-dependent water utilities. White-space exists in mid-sized city governments between 50,000-150,000 residents seeking rapid-deployment permitting solutions. Pursue channel partnerships with municipal IT consultants as primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by enterprise suite providers seeking vertical capability fill-ins. Long-term viability favors vendors with demonstrated EPA compliance automation and ISO 37120 certification traction. Monitor municipal procurement cycle acceleration from capital to operating expenditure as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates citizen engagement, permitting, and billing workflows into unified SaaS suites for mid-sized cities. |
| Acquisition of Specialist Firm | Adds predictive maintenance capabilities and digital twin expertise to infrastructure asset management portfolios. |
| Strategic Partnership | Secures sensor hardware integration for EPA-aligned water utility compliance automation. |
| Geographic Expansion | Captures greenfield deployment opportunities in India's Smart Cities Mission municipalities. |
| Product Launch | Introduces ISO 37120-certified analytics modules for European smart city certification requirements. |
Research Methodology
SEC filings, EPA enforcement databases, and ISO certification registries formed the secondary backbone, supplemented by municipal procurement records and cloud infrastructure spending disclosures. Primary interviews with municipal CIOs, public works directors, water utility compliance officers, and SaaS procurement specialists validated segmentation assumptions. Bottom-up vendor revenue estimates and top-down municipal IT spending analysis enabled triangulation across deployment models and end-user segments.
Historical trendline analysis tracked subscription pricing evolution and cloud migration penetration across the analysis window. Segmentation modeling incorporated solution type, deployment architecture, municipality scale tier, and regional regulatory framework. CAGRs derived from curve-fitting observed adoption rates against infrastructure replacement cycles and compliance mandate timelines. Forecast inputs included EPA rulemaking schedules and ISO 37120 certification adoption curves.
The model assumes a particular technology adoption path; alternative pathways for on-premises-to-cloud migration would alter the outlook. Forecasts reflect assumptions about regulatory enforcement intensity and municipal budget recovery trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Content Creation Software Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Global Digital Adoption Platform Software Market
Software & Services
Driver and Staff Management Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Global Chromatography Software Market
Software & Services
OCR Scanning Software Market
Software & Services
Digital Painting Software Market
Software & Services
Mobile Application Development Platform (MADP) Market
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Global Open API Market
Software & Services
Email Applications Market
Software & Services
Electronic Design Automation Software Market