
 Configuration Management (CM) Tools Market | 2026-2036
Configuration Management (CM) Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Configuration Management (CM) Tools Market Outlook
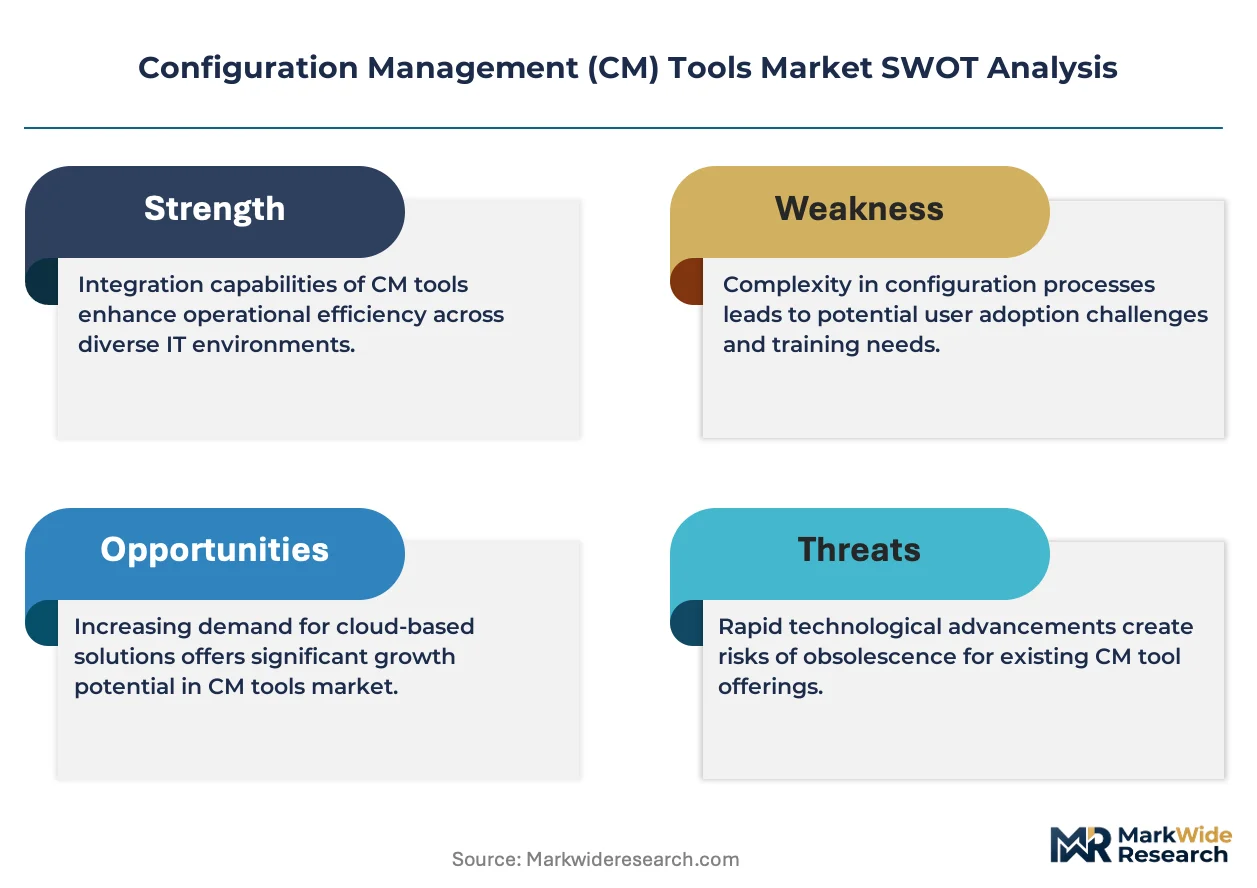
The gap between infrastructure-as-code and traditional manual provisioning is narrowing as GitOps pipelines become the default delivery mechanism for enterprise software. Puppet leverages declarative language models to sustain configuration consistency across heterogeneous server fleets. Ansible competes through agentless architecture that reduces deployment friction in hybrid cloud environments. Chef anchors its position with policy-driven automation tailored to compliance-heavy sectors.
Configuration management tools enforce desired-state consistency across IT infrastructure through automated drift detection, idempotent execution engines, and version-controlled policy definitions, ensuring operational reliability at scale. Agent-based deployment dominates in regulated industries requiring persistent endpoint monitoring, while agentless architectures are capturing share in ephemeral cloud workloads where installation overhead is prohibitive. Cloud-based delivery models are expanding fastest among mid-market enterprises seeking to bypass capital-intensive on-premises orchestration layers.
FDA 21 CFR Part 11 mandates audit-trail integrity for software systems in pharmaceutical manufacturing, directly elevating demand for change-management functionality with immutable logging. NIST SP 800-53 and ISO 27001 frameworks shape procurement criteria for federal contractors and enterprises managing controlled unclassified information. Stakeholders must evaluate how emerging EU Cyber Resilience Act certification requirements will reshape vendor qualification timelines and interoperability standards.
Market Dynamics
GitOps pipelines are compressing deployment cycles from weeks to hours, forcing incumbent vendors to rearchitect around immutable infrastructure primitives or cede ground to cloud-native challengers.
Growth Catalysts
- EU AI Act compliance mandates:Financial services institutions in Frankfurt and Paris must demonstrate algorithmic auditability, driving procurement of policy-as-code platforms with embedded logging. The NIS2 Directive amplifies this pressure across critical infrastructure operators.
- Container orchestration density:Kubernetes-native configuration controllers now manage ephemeral workloads at scale where agent-based tools impose unacceptable overhead. Platform engineering teams standardize on declarative reconciliation loops.
- Germany's industrial automation corridor:Manufacturing conglomerates in Baden-Württemberg and Bavaria consolidate fragmented DevOps tooling, creating procurement pools exceeding single-vendor thresholds.
Market Restraints
- Specialized talent scarcity:Infrastructure-as-code expertise concentrates in Berlin, Munich, and Hamburg, inflating implementation costs for mid-market enterprises outside these clusters.
- Legacy agent persistence:Regulated pharmaceutical manufacturers under FDA 21 CFR Part 11 require persistent endpoint monitoring that conflicts with ephemeral cloud workload patterns, fragmenting vendor roadmaps.
- Certification timeline compression:EU Cyber Resilience Act pre-market conformity assessments extend vendor qualification cycles, delaying revenue recognition for new feature releases.
Strategic Opportunities
- Edge configuration management:Industrial IoT deployments in Stuttgart's automotive supply chain lack mature tooling for disconnected-node reconciliation, creating whitespace for purpose-built controllers.
- Policy-to-code convergence:The EU AI Act's technical documentation requirements are accelerating demand for automated compliance mapping between legal text and executable infrastructure policies.
- Managed service bundling:Mid-market enterprises in Cologne and Düsseldorf prefer consumption-based CMaaS models that bypass capital-intensive orchestration layer investments.
Industry Challenges
- Multi-cloud state synchronization:Platform teams struggle to maintain drift detection accuracy across AWS, Azure, and on-premises VMware estates with divergent API semantics.
- Immutable logging architecture:Pharmaceutical manufacturers must reconstruct audit trails from containerized microservices that spawn and terminate faster than traditional SIEM ingestion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Configuration Management (CM) Tools Market |
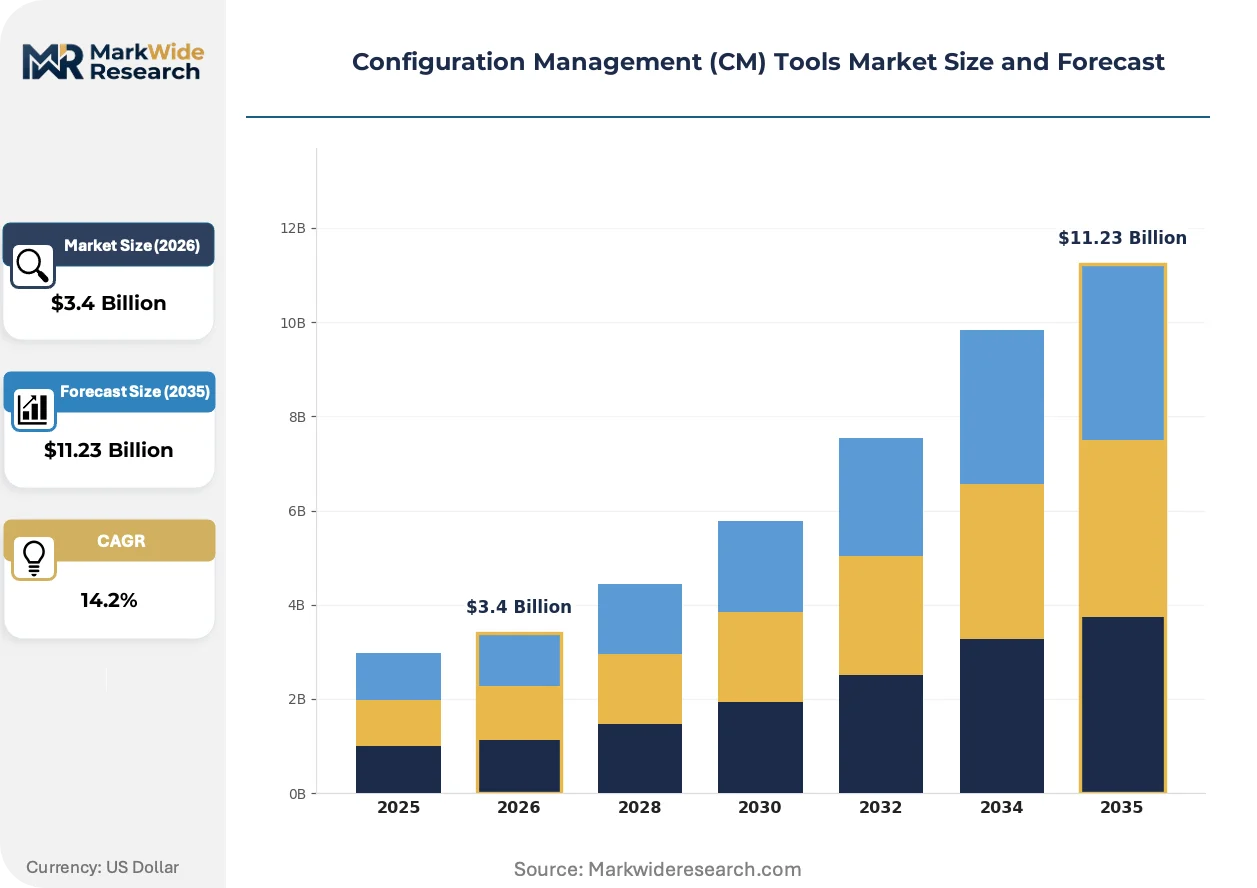
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: IT Departments, Managed Service Providers, Enterprises, Government Agencies Functionality: Software Configuration, Network Management, Change Management, Asset Management Technology: Agent-Based, Agentless, Automation Tools, Monitoring Solutions |
| Companies Covered | Puppet, Ansible, Chef, CFEngine, SaltStack, BMC Helix, ManageEngine ServiceDesk Plus, Deepser, GitLab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Configuration Management (CM) Tools Market Strategic Shifts
Immutable infrastructure primitives are displacing mutable configuration patterns, compressing the window between code commit and production deployment while elevating security posture through reduced attack surface.
GitOps controllers with built-in drift detection and automated reconciliation loops are rendering obsolete manual configuration review boards and ticket-driven change management. Large German automotive manufacturers now deploy infrastructure changes hundreds of times daily. The structural consequence is collapsing demand for traditional CMDB-centric workflow tools that cannot match reconciliation velocity.
REACH chemical substance tracking requirements and the EU AI Act's technical documentation mandates are forcing CM vendors to embed material traceability and algorithmic auditability into infrastructure policy engines. Industrial chemical manufacturers must now map every software dependency to substance declarations. The pharmaceutical sector responds by demanding policy-as-code platforms with immutable logging that satisfies both ECHA and FDA submission requirements.
Platform engineering teams now specify outcome-based infrastructure reliability contracts rather than purchasing discrete configuration management licenses. German financial services institutions in Frankfurt bundle CM capabilities within internal developer platform subscriptions. This procurement compression is most visible among DAX-listed enterprises consolidating vendor relationships under single platform engineering budgets.
Configuration Management (CM) Tools Market Segmentation
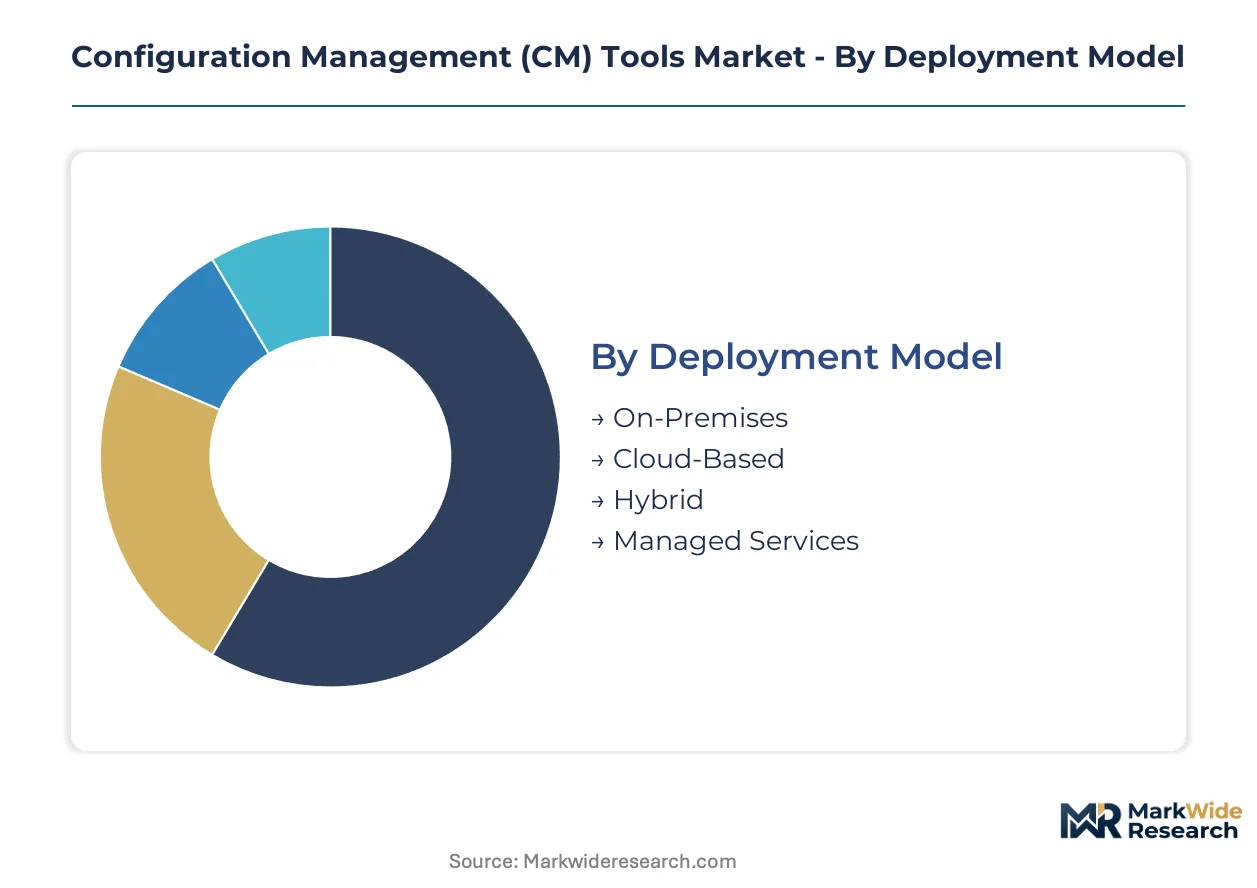
Segmentation in configuration management tools reveals divergent procurement cycles across deployment architectures and operational functions. Cloud-native delivery compresses vendor evaluation timelines to weeks, while regulated on-premises implementations extend qualification periods to quarters.
Deployment Model:
Cloud-based deployments turn over fastest with monthly subscription renewals, while on-premises licenses cycle slowest through multi-year capital approval processes.
- On-Premises:Perpetual licensing with dedicated orchestration layers dominates pharmaceutical manufacturing under FDA 21 CFR Part 11. German automotive suppliers in Baden-Württemberg maintain these installations for air-gapped production environments where external connectivity is prohibited.
- Cloud-Based:SaaS delivery with API-first reconciliation loops captures mid-market financial services in Frankfurt seeking to bypass capital expenditure committees. The EU AI Act's auditability mandates accelerate procurement of hosted policy-as-code platforms with embedded logging.
- Hybrid:Split-state management across on-premises VMware and AWS/Azure estates addresses workload sovereignty requirements in multi-jurisdictional enterprises.
- Managed Services:CMaaS consumption models appeal to Cologne and Düsseldorf enterprises lacking internal platform engineering capacity.
On-premises deployments anchor the volume base while cloud-based delivery gains share at the steepest rate.
End User:
Procurement authority concentrates differently across customer types, with government agencies imposing the most extensive certification overhead.
- IT Departments:Internal platform engineering teams at DAX-listed conglomerates consolidate fragmented tooling under single vendor relationships. NIST SP 800-53 compliance requirements shape federal contractor procurement in the US.
- Enterprises:Multi-division manufacturing groups in Bavaria standardize on declarative reconciliation loops to compress deployment cycles from weeks to hours.
- Managed Service Providers:Third-party operators bundle configuration management into broader infrastructure outsourcing contracts.
- Government Agencies:Federal and state entities mandate immutable logging architectures that satisfy ISO 27001 and controlled unclassified information frameworks.
Enterprise IT departments dominate current spending while managed service providers are expanding most quickly.
Functionality:
Application breadth varies sharply, with change management commanding premium pricing due to compliance integration requirements.
- Change Management:Immutable audit trails with version-controlled policy definitions serve pharmaceutical manufacturers facing simultaneous FDA and ECHA submission requirements. Stuttgart automotive suppliers deploy these capabilities hundreds of times daily.
- Software Configuration:Desired-state enforcement across containerized microservices addresses the reconciliation velocity demands of GitOps pipelines.
- Network Management:Device configuration standardization supports heterogeneous server fleets in hybrid cloud estates.
- Asset Management:CMDB-centric tracking persists in regulated industries despite collapsing demand from platform engineering teams.
Software configuration functions constitute the largest installed base whereas change management is climbing the fastest.
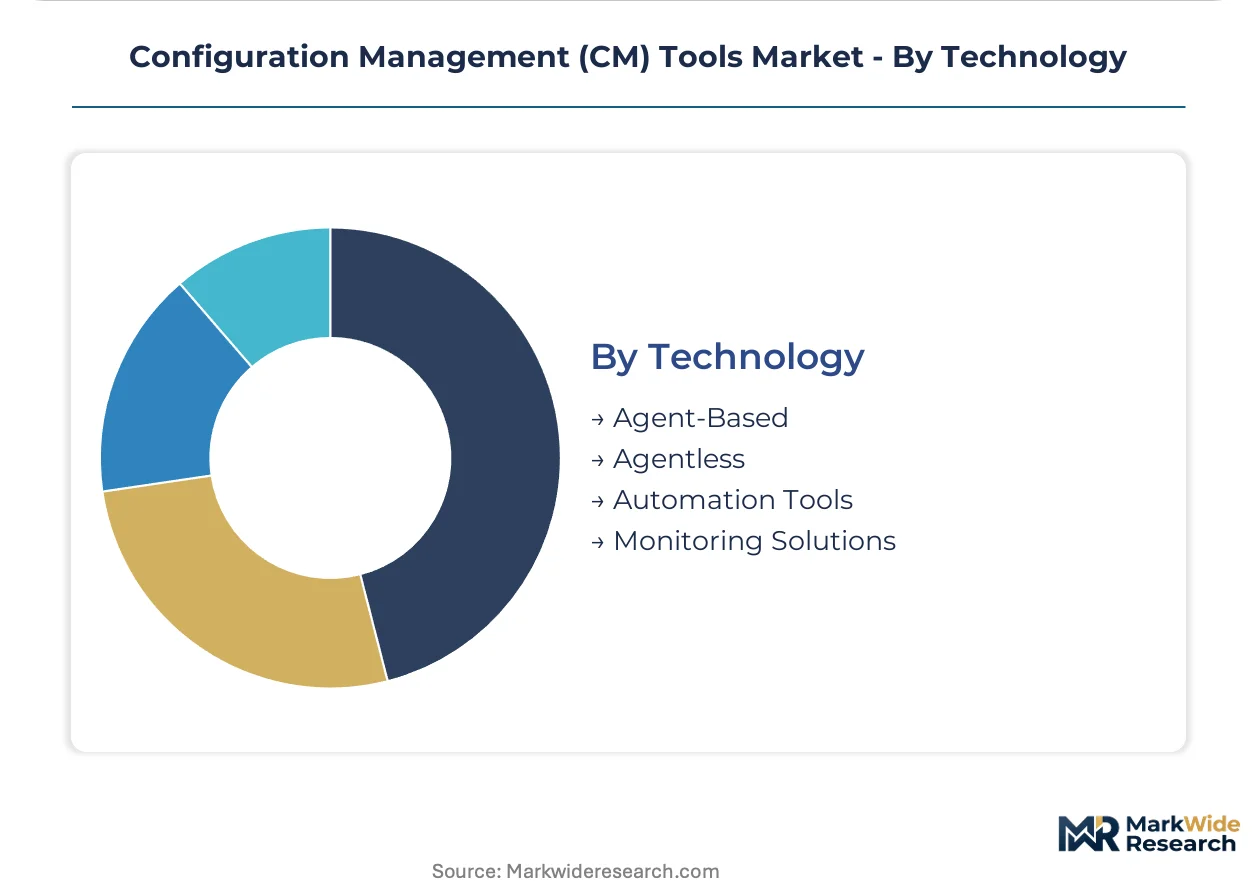
Technology:
Architecture choices determine operational overhead, with agentless models reducing deployment friction in ephemeral workloads.
- Agent-Based:Persistent endpoint monitoring satisfies regulated pharmaceutical manufacturers requiring continuous drift detection. The persistence conflicts with Kubernetes-native patterns, fragmenting vendor development roadmaps.
- Automation Tools:Declarative language models enable idempotent execution across heterogeneous environments without installation overhead.
- Agentless:API-driven configuration eliminates deployment friction in cloud-native environments where ephemeral workloads spawn and terminate rapidly.
- Monitoring Solutions:Drift detection with automated reconciliation loops renders manual review boards obsolete.
Agent-based technology retains the deepest installed footprint while agentless architectures are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform engineering teams in Frankfurt, Stuttgart, and Munich concentrate procurement authority for configuration management tooling, with financial services and automotive manufacturing driving differentiated demand patterns across national markets.
United States
Federal contractors and pharmaceutical manufacturers anchor demand for agent-based tools with immutable logging architectures. FDA 21 CFR Part 11 mandates audit-trail integrity for software systems in drug manufacturing, elevating procurement of change-management platforms with version-controlled policy definitions. Boston's biotech cluster and the FDA's Maryland headquarters proximity shape vendor qualification timelines for compliance-heavy deployments.
Germany
Industrial automation conglomerates in Baden-Württemberg and Bavaria consolidate fragmented DevOps tooling under single-vendor relationships. The EU AI Act and NIS2 Directive tighten algorithmic auditability requirements for Frankfurt financial institutions, accelerating hosted policy-as-code adoption. Stuttgart automotive suppliers deploy GitOps controllers hundreds of times daily, compressing demand for traditional CMDB-centric workflow tools.
United Kingdom
London's financial services sector drives cloud-native configuration management procurement for algorithmic trading infrastructure. The Financial Conduct Authority's operational resilience requirements intersect with ISO 27001 frameworks, shaping vendor selection criteria for drift detection capabilities. Edinburgh's fintech cluster and Manchester's growing platform engineering presence expand addressable market beyond the capital.
France
Paris-based banking groups under ECB supervision must demonstrate NIS2 Directive compliance for critical infrastructure operations. ANSM pharmaceutical oversight and EMA proximity in Lyon create dual regulatory pressure for immutable logging in life sciences manufacturing. Toulouse's aerospace supply chain and Sophia Antipolis technology park generate specialized demand for air-gapped configuration controllers.
Japan
Tokyo's financial institutions and Osaka manufacturing groups adopt hybrid deployment models balancing cloud velocity with on-premises sovereignty. METI's cybersecurity framework and JIS standards shape procurement specifications for multi-cloud state synchronization. Nagoya's automotive engineering concentration and Fukuoka's growing SaaS sector represent divergent buyer archetypes within the national market.
Configuration Management (CM) Tools Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that segments into three tiers: infrastructure incumbents with deep installed bases, cloud-native challengers with Kubernetes-native architectures, and compliance-focused specialists serving regulated verticals. Consolidation pressure intensifies as platform engineering teams bundle configuration management into broader internal developer platform subscriptions. Dominant competitive moves include M&A activity targeting GitOps workflow capabilities and strategic partnerships with hyperscale cloud providers to embed reconciliation engines within managed Kubernetes services.
Within the infrastructure incumbent tier, Puppet and Chef occupy positions anchored by declarative language models and policy-driven automation heritage. Ansible exemplifies the agentless architecture archetype that reduces deployment friction in hybrid cloud environments. SaltStack sits within the specialized controller segment addressing high-velocity reconciliation demands. These three companies represent divergent technical bets on how configuration state should be enforced across heterogeneous server fleets and ephemeral container workloads.
| Leading Market Players |
|---|
| Puppet |
| Ansible |
| Chef |
| CFEngine |
| SaltStack |
| BMC Helix |
| ManageEngine ServiceDesk Plus |
| Deepser |
| GitLab |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure hyperscalers in the United States anchor upstream compute and storage provisioning, concentrating margin capture in the SaaS delivery tier where policy-as-code platforms command recurring subscription premiums. German automotive manufacturers and Frankfurt financial institutions absorb these costs through operational expenditure budgets that bypass capital committee approval cycles.
Pricing Analysis
Annual subscription contracts with CPI indexation dominate enterprise procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by compliance certification depth and reconciliation velocity. Price differentiation hinges on ISO 27001 audit readiness and EU AI Act technical documentation automation. Cost compression in the mid-market tier intensifies as Cologne and Düsseldorf enterprises demand consumption-based CMaaS models. Managed service providers exhibit highest price sensitivity; DAX-listed platform engineering teams show lowest sensitivity due to bundled internal developer platform budgets.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for semiconductor-dependent orchestration hardware. Software supply chains draw from open-source repositories hosted in the United States, Germany, and Ireland, with critical dependencies on Kubernetes control plane components and cryptographic libraries. Single-source vulnerability concentrates in cloud-native reconciliation engines maintained by foundation-backed projects. Distribution runs through hyperscale marketplaces and direct enterprise sales teams, with channel partners capturing mid-market share in Baden-Württemberg and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering consolidation across DAX-listed enterprises fragments procurement authority, creating specialized niches for compliance-focused specialists and edge-native challengers that incumbent vendors cannot address without roadmap divergence.
For Market Incumbents: Harden defensive positions by embedding immutable logging architectures that satisfy simultaneous FDA 21 CFR Part 11 and EU Cyber Resilience Act requirements, then acquire GitOps workflow capabilities to neutralize cloud-native challengers. Certification investment in ECHA material traceability modules protects pharmaceutical manufacturing accounts from specialized entrants. Vertical integration into managed Kubernetes services through hyperscaler partnerships secures reconciliation engine placement. For New Entrants and Emerging Players: Build out purpose-built controllers for Stuttgart's automotive supply chain edge deployments, where disconnected-node reconciliation lacks mature tooling. The whitespace concentrates in industrial IoT configurations for air-gapped production environments. Target mid-market financial services in Frankfurt with hosted policy-as-code platforms that compress EU AI Act compliance timelines. A channel partnership route through regional systems integrators accelerates credentialing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed infrastructure automation platforms possessing deep pharmaceutical manufacturing installed bases but lacking Kubernetes-native architectures. Long-term viability across the analysis window favors targets with embedded compliance engines that translate regulatory text into executable policy. The signal to watch is qualification timeline compression under EU Cyber Resilience Act pre-market assessments, which would elevate acquisition premiums for certified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| GitOps Workflow Acquisition | Accelerates reconciliation velocity for Stuttgart automotive suppliers deploying infrastructure changes daily. |
| EU Cyber Resilience Act Certification | Unlocks Frankfurt financial services procurement pools requiring pre-market conformity assessments. |
| Edge Configuration Controller Development | Addresses whitespace in Baden-Württemberg industrial IoT deployments with disconnected-node requirements. |
| Hyperscaler Marketplace Integration | Embeds reconciliation engines within AWS and Azure managed Kubernetes services for mid-market capture. |
| Policy-to-Code Automation Platform | Maps EU AI Act technical documentation requirements directly to executable infrastructure policies. |
Study Parameters
A spread of perspectives from platform engineering directors, IT procurement officers at DAX-listed enterprises, compliance leads in pharmaceutical manufacturing, and channel partners in Germany's industrial automation corridor converged on the working assumptions. These primary insights combined with secondary validation from SEC filings of publicly traded software vendors, hyperscaler capex disclosures, EU regulatory documentation in the Official Journal, and NIST SP 800-53 implementation guides. Bottom-up sizing of deployment models and top-down cross-checks against enterprise IT spending benchmarks established analytical coherence.
Demand-supply-balance framing anchored the forecast framework across the analysis window, with segmentation dimensions spanning deployment architecture, organization size, vertical regulatory intensity, and regional adoption pattern. CAGRs derived from slope consistency checks against historical infrastructure software category growth and forward-looking platform engineering budget trajectories. Industry-specific inputs included GitOps pipeline adoption velocity in German automotive manufacturing and EU AI Act implementation timelines for financial services.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native challengers or accelerated EU Cyber Resilience Act enforcement would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Organizational Change Management Software Market
Software & Services
Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Global Online Community Management Software Market
Software & Services
Android Emulator Market
Software & Services
Library Management Software Market
Software & Services
Global Auction Software Market
Software & Services
Runtime Software Market
Software & Services
Account-Based Data Software Market
Software & Services
Global Document Management Software Market
Software & Services
Royalty Management Software and Services Market
Software & Services
Europe Human Resource (HR) Technology Market
Software & Services
Balance Sheet Management Software Market
Software & Services
B2B Price Optimization and Management Software Market
Software & Services
Queue Manager Market
Software & Services
Application Lifecycle Management (ALM) Market