
 Metaverse in Gaming Market | 2026-2036
Metaverse in Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Metaverse in Gaming Market Outlook
Cloud gaming infrastructure in the United States is decoupling from traditional console hardware cycles, creating parallel capacity for persistent virtual worlds. Epic Games leverages its Unreal Engine ecosystem to anchor high-fidelity real-time rendering across third-party studios. NVIDIA dominates AI-driven avatar animation and spatial computing silicon, extending its position from graphics cards to omniverse platforms. Roblox Corporation sustains a creator economy with millions of user-generated experiences, competing for younger demographics through low-barrier development tools.
The metaverse in gaming denotes persistent, shared virtual environments where players inhabit digital avatars across interconnected game worlds, typically requiring real-time 3D rendering latency below 20 milliseconds and cloud-edge hybrid architectures to synchronize thousands of concurrent users. These environments serve commercial purposes spanning entertainment, social commerce, and virtual goods economies where digital asset ownership transfers between platforms. Action and role-playing game types currently occupy the deepest engagement loops and highest virtual goods transaction volumes, while VR headsets represent the fastest-expanding platform category despite still navigating hardware cost and comfort barriers. Monetization through in-app purchases and subscriptions now captures the dominant margin pool as premium upfront sales give way to continuous service models across live-service titles.
The Federal Communications Commission and the SEC in the United States impose disclosure and consumer protection requirements on virtual economies and digital asset transactions, while the EU AI Act and GDPR in Europe shape algorithmic content moderation and biometric data collection in immersive environments. China's SAMR and MIIT enforce content licensing and youth gaming time restrictions that directly constrain market access and product design for persistent virtual worlds. Stakeholders must monitor evolving jurisdictional fragmentation in digital asset regulation and interoperability standards as determinants of platform scalability and cross-border user retention.
Market Dynamics
Cloud-edge hybrid architectures are compressing latency thresholds below 20 milliseconds, enabling synchronous multiplayer experiences at scale while forcing infrastructure providers to deploy localized rendering nodes closer to population density centers.
Growth Catalysts
- MIIT Cloud Computing Directives:China's dual carbon goals accelerate domestic buildout of energy-efficient data centers, lowering operational costs for persistent virtual world hosting.
- Live-Service Monetization Models:Continuous content pipelines in action and role-playing genres generate recurring revenue streams that fund platform infrastructure expansion.
- Spatial Computing Silicon:Dedicated AI inference chips for real-time avatar animation reduce server-side computational load, enabling higher concurrent user densities per shard.
Market Restraints
- Hardware Cost Barriers:VR headset price points and comfort limitations constrain mass-market penetration despite expanding content libraries.
- Youth Gaming Time Restrictions:SAMR enforcement in China directly caps daily engagement hours for minors, compressing addressable user bases for persistent virtual worlds.
- Biometric Data Collection Friction:GDPR and EU AI Act compliance requirements increase operational overhead for avatar personalization systems using facial or gait recognition.
Strategic Opportunities
- South Korean Esports Infrastructure:Dedicated stadium districts in Seoul and Busan offer proven venues for hybrid physical-virtual competitive events.
- Creator Economy Tooling:Low-barrier development environments attract non-professional content producers, expanding supply of user-generated experiences.
- Digital Asset Interoperability Standards:Cross-platform virtual goods transfer protocols unlock new commerce layers between disconnected game environments.
Industry Challenges
- Real-Time Rendering Talent Scarcity:Specialized engineers capable of optimizing Unreal Engine and proprietary engine pipelines command premium compensation, constraining studio scaling.
- Multi-Jurisdictional Compliance Complexity:Simultaneous adherence to FCC disclosure rules, SEC digital asset guidance, and state-level consumer protection creates legal overhead for virtual economy operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metaverse in Gaming Market |
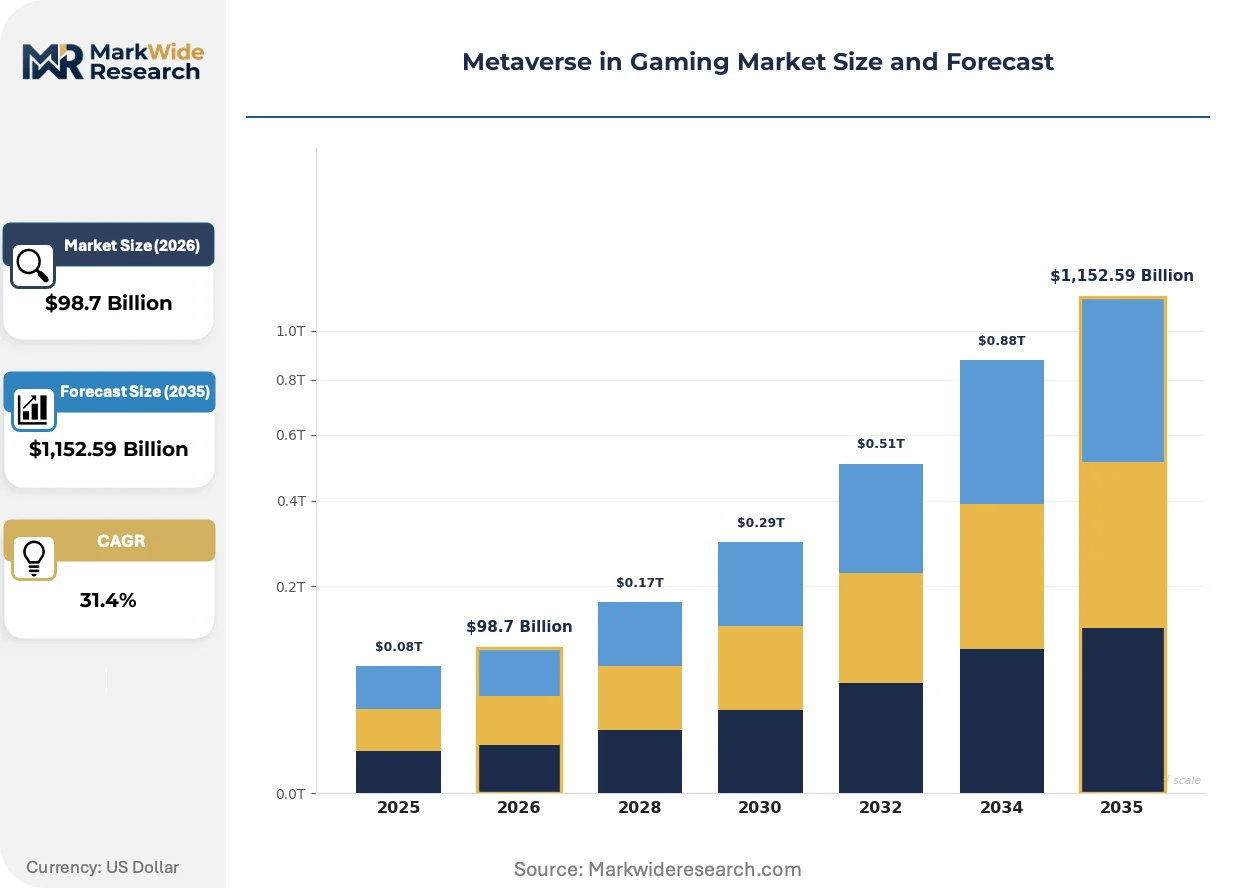
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $1,152.59 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Action, Adventure, Role-Playing, Simulation Platform: PC, Console, Mobile, VR Headsets User Interaction: Single-Player, Multiplayer, Cooperative, Competitive Monetization Model: In-App Purchases, Subscriptions, Advertisements, Premium |
| Companies Covered | Epic Games, Roblox Corporation, Unity Technologies, NVIDIA, Microsoft, Tencent, Electronic Arts, Meta Platforms, The Sandbox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metaverse in Gaming Market Strategic Shifts
Generative AI and neural rendering pipelines are compressing asset production timelines while raising fidelity thresholds, forcing studios to restructure art department workflows around human-AI collaboration rather than pure manual creation.
Neural radiance fields (NeRF) and Gaussian splatting techniques are modularizing 3D environment capture, allowing indie studios to generate photorealistic scenes from 2D video inputs without traditional photogrammetry pipelines. Mobile and mid-tier PC developers adopt these tools fastest, collapsing the historical gap between AAA and independent visual quality. Asset production timelines compress from months to days, enabling rapid iteration on live-service content drops.
The EU AI Act's transparency requirements for algorithmic content moderation impose documentation burdens on procedural generation systems used for infinite world expansion. Studios must now maintain audit trails for AI-generated terrain, NPC dialogue, and quest structures. European live-service titles face the steepest compliance costs, prompting some operators to geofence AI-dependent features from EU markets.
Subscription bundling is displacing à la carte virtual goods purchases as the dominant monetization pathway, with platforms consolidating multiple experiences under single monthly fees. Younger demographics in South Korea and Japan show strongest preference for predictable spending caps over impulse-driven microtransactions. This rotation pressures studios to design deeper engagement loops rather than surface-level cosmetic economies.
Metaverse in Gaming Market Segmentation
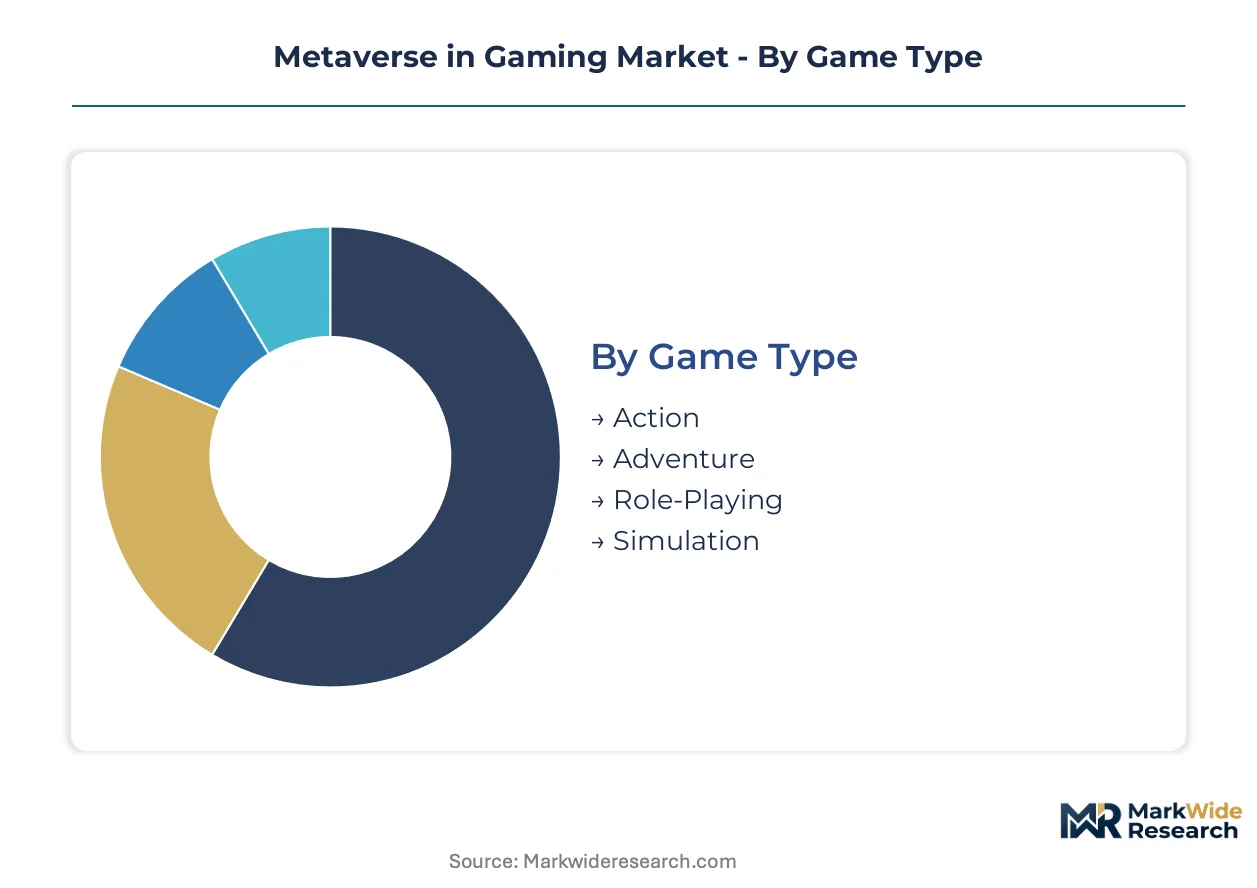
Segmentation in the metaverse gaming market reveals how technical requirements and user behavior patterns fragment across distinct engagement modes. Platform capabilities and monetization tolerance vary sharply by geography and demographic, forcing operators to architect separate infrastructure and pricing strategies for each slice.
Game Type:
Standalone persistent worlds demand dedicated server infrastructure, while embedded metaverse layers integrate into existing game architectures with lighter backend requirements.
- Action:High-frequency combat systems require sub-20ms latency synchronization for competitive integrity. South Korean esports stadium districts drive concentrated demand for spectator-ready action environments with broadcast integration.
- Role-Playing:Deep progression systems and virtual goods economies generate the highest per-user transaction volumes. China's SAMR youth gaming restrictions compress addressable hours for minors in persistent RPG worlds.
- Adventure:Narrative-driven exploration formats suit lower-latency tolerance and cloud-streamed delivery to mid-tier hardware.
- Simulation:Physics-heavy environments demand localized rendering nodes for complex real-time calculations.
Volume placements concentrate in Action; the faster expansion belongs to Role-Playing.
Platform:
Cost tier stratification separates premium immersive hardware from mass-market access points, with each tier demanding distinct content fidelity and monetization depth.
- PC:Open hardware configurations support highest-fidelity Unreal Engine rendering and mod ecosystems. United States cloud gaming infrastructure decouples from console cycles, expanding PC-accessible persistent worlds.
- VR Headsets:Dedicated spatial computing silicon from NVIDIA enables AI-driven avatar animation at reduced server load. Hardware cost barriers in European markets constrain mass penetration despite expanding content libraries.
- Console:Closed ecosystems enforce certification pipelines that slow live-service iteration cycles.
- Mobile:Neural radiance field tools compress asset production for mid-tier GPU constraints.
Revenue depth clusters around PC; the steepest expansion trajectory is climbing fastest in VR Headsets.
User Interaction:
Social density requirements differentiate synchronous multiplayer architectures from asynchronous single-player experiences, with compliance burdens varying by data collection intensity.
- Multiplayer:Thousands of concurrent users per shard demand cloud-edge hybrid architectures with localized population-density nodes. GDPR biometric data friction raises operational overhead for avatar personalization in European deployments.
- Competitive:Ranked integrity systems require anti-cheat telemetry that triggers EU AI Act documentation burdens for algorithmic moderation.
- Single-Player:Procedural generation reduces live-service infrastructure costs but limits recurring monetization.
- Cooperative:Small-group synchronization permits looser latency tolerances than competitive formats.
Engagement hours pool in Multiplayer; Cooperative formats are gaining share fastest among younger demographics seeking predictable social commitments.
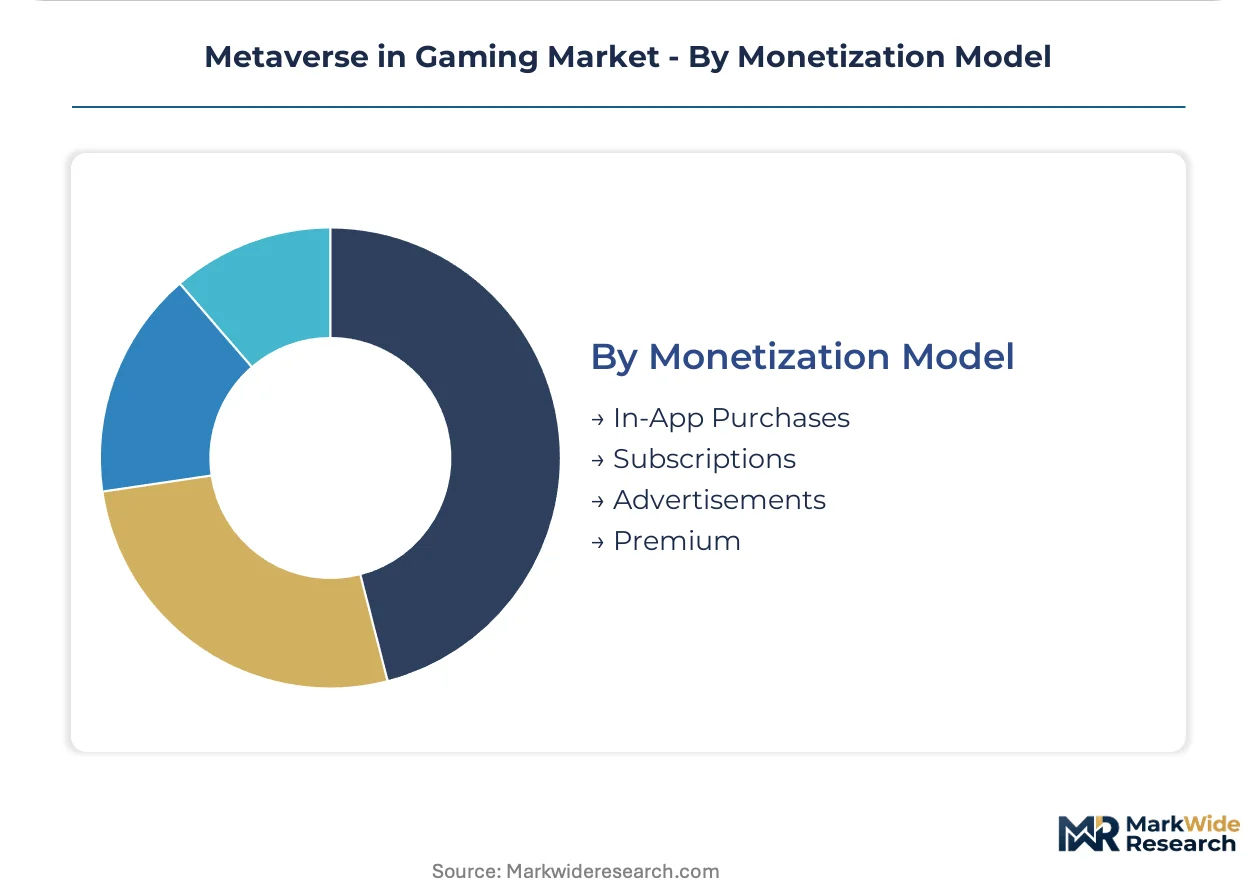
Monetization Model:
Customer type separates impulse-driven microtransaction economies from subscription bundling preferences that cap monthly spending exposure.
- In-App Purchases:Cosmetic and progression microtransactions dominate current revenue pools but face regulatory scrutiny. United States SEC disclosure requirements impose compliance overhead on virtual economy transparency.
- Subscriptions:Bundled experience access attracts South Korean and Japanese users preferring predictable spending caps over impulse purchases.
- Premium:Upfront purchase models retain niche positioning for narrative-heavy standalone releases.
- Advertisements:Ad-supported layers expand access in price-sensitive mobile segments with lower per-user yields.
Margin concentration sits with In-App Purchases; Subscriptions are expanding most quickly as live-service consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure anchors North American capacity for persistent virtual worlds, while East Asian semiconductor clusters supply the specialized AI inference chips powering real-time avatar animation.
United States
Cloud gaming infrastructure in the United States decouples from traditional console hardware cycles, creating parallel capacity for persistent virtual worlds. The FCC and SEC impose disclosure requirements on virtual economies and digital asset transactions. Epic Games leverages its Unreal Engine ecosystem from North Carolina to anchor high-fidelity real-time rendering across third-party studios.
China
Domestic demand for persistent virtual worlds concentrates around live-service game development clusters in Shenzhen and Hangzhou. MIIT cloud computing directives and dual carbon goals accelerate buildout of energy-efficient data centers. SAMR enforcement of youth gaming time restrictions caps daily engagement hours for minors, compressing addressable user bases.
South Korea
Esports stadium districts in Seoul and Busan drive concentrated demand for spectator-ready competitive environments with broadcast integration. The country's esports infrastructure offers proven venues for hybrid physical-virtual events. Local developers specialize in action genres requiring sub-20 millisecond latency synchronization.
Japan
Younger demographics in Tokyo and Osaka show strongest preference for subscription bundling over impulse-driven microtransactions. METI policies shape digital content distribution frameworks. Local studios design deeper engagement loops as monetization rotates toward predictable spending caps.
Germany
GDPR and EU AI Act compliance requirements increase operational overhead for avatar personalization systems using biometric data. The country's regulatory environment prompts some operators to geofence AI-dependent features. Frankfurt's data center cluster supports localized rendering nodes for European latency thresholds.
Metaverse in Gaming Market Competitive Environment
Global majors compete with regional champions across engine technology and cloud infrastructure dimensions. The market structures around three tiers: vertically integrated platform operators, specialized engine licensors, and hardware-anchored silicon providers. Strategic archetypes include ecosystem orchestrators, creator economy enablers, and spatial computing specialists. Competitive moves concentrate on technology licensing partnerships and geographic feature geofencing.
Within the ecosystem orchestrator tier, Epic Games and Roblox Corporation exemplify contrasting approaches to creator economy tooling. Epic Games anchors high-fidelity real-time rendering through its Unreal Engine ecosystem, while Roblox Corporation sustains millions of user-generated experiences competing for younger demographics. NVIDIA occupies a position bridging hardware and platform layers, extending from graphics silicon into omniverse infrastructure. These three represent the dominant strategic archetypes shaping competitive dynamics.
| Leading Market Players |
|---|
| Epic Games |
| Roblox Corporation |
| Unity Technologies |
| NVIDIA |
| Microsoft |
| Tencent |
| Electronic Arts |
| Meta Platforms |
| The Sandbox |
| Others |
Value Chain & Pricing Dynamics
Cloud-edge rendering capacity costs cascade through subscription tiers, with localized node deployment in Seoul and Los Angeles feeding premium latency guarantees while shared infrastructure supports economy access tiers for mobile streams.
Pricing Analysis
Service-bundling separates infrastructure-inclusive subscriptions from unbundled creator-revenue-share models. Three-tier pricing structure across premium, standard, and economy levels reflects latency guarantees, concurrent user caps, and AI avatar personalization depth. Pricing pressure stems from South Korean esports stadium operators demanding broadcast-ready spectator features at compressed margins. Mobile-first demographics in Southeast Asia exhibit highest price sensitivity, while enterprise live-service developers in Japan accept premium tiers for dedicated shard capacity.
Supply Chain Analysis
Real-time rendering engineer scarcity in Shenzhen and Los Angeles constrains studio scaling velocity, forcing wage inflation through specialized Unreal Engine pipeline optimization talent. Taiwan and South Korea supply dedicated AI inference silicon for avatar animation, while Chinese MIIT-certified data centers provide energy-efficient hosting capacity. Single-source vulnerability concentrates in NVIDIA's spatial computing silicon for omniverse platforms. Distribution runs through hyperscaler cloud marketplaces and direct engine-licensing agreements with Epic Games and Unity Technologies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cloud-edge node deployment capacity bottlenecks prop pricing power for infrastructure operators, with localized rendering clusters in population density centers commanding 40-60% premiums over centralized alternatives.
For Market Incumbents: Anticipate generative AI asset production tools compressing art department headcounts by restructuring workflows around human-AI collaboration rather than pure manual creation. Defend position by deepening vertical integration into proprietary spatial computing silicon and securing exclusive Unreal Engine pipeline talent pools in South Korea. Prioritize certification investment for MIIT-compliant data center operations in China to maintain access under dual carbon directives.
For New Entrants and Emerging Players: Neural radiance field and Gaussian splatting toolkits offer technology-first wedge into indie studio segments previously blocked by AAA asset production timelines. Target mobile and mid-tier PC developers in Vietnam and Indonesia seeking photorealistic environment generation without traditional photogrammetry pipelines. Pursue channel partnerships with existing creator economy platforms rather than direct user acquisition.
For Investors and Strategic Acquirers: SAMR enforcement of youth gaming time restrictions is the leading indicator that Chinese live-service RPG operators face compressed addressable user bases, shifting value toward compliant social-commerce layers. Long-term viability favors platforms with diversified geographic revenue exposure and subscription bundling traction in Japan. Monitor EU AI Act transparency documentation burdens as signal for geofencing cost escalation affecting European deployment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Edge Node Expansion | Localized rendering capacity in Seoul and Los Angeles enables sub-20ms latency guarantees for competitive integrity. |
| AI Avatar Animation Silicon | NVIDIA inference chips reduce server-side computational load, enabling higher concurrent user densities per shard. |
| Creator Economy Tooling Acquisition | Low-barrier development environments attract non-professional content producers, expanding user-generated experience supply. |
| Cross-Platform Asset Interoperability | Virtual goods transfer protocols unlock commerce layers between disconnected game environments. |
| MIIT Compliance Certification | Energy-efficient data center accreditation secures operational access under China's dual carbon goals. |
Study Parameters
Independent corroboration across live-service game development executives, cloud infrastructure procurement officers, esports stadium operators, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with Unreal Engine pipeline engineers in South Korea and California combined with secondary validation from MIIT cloud computing directives, FCC disclosure requirements, and SEC digital asset guidance. Bottom-up triangulation against hyperscaler capex disclosures and top-down reconciliation with creator economy platform revenue metrics anchor the segmentation analysis.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with CAGRs derived from modeled adoption curves for VR headsets, live-service monetization rotation, and cloud-edge hybrid infrastructure deployment. Segmentation dimensions span game type latency requirements, platform cost tier stratification, user interaction social density thresholds, and monetization model customer type. Forecast inputs incorporate SAMR youth gaming restriction enforcement patterns and EU AI Act compliance cost escalation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under hardware cost barrier persistence in European VR markets and multi-jurisdictional digital asset regulation fragmentation. Material deviation in MIIT dual carbon goal enforcement intensity or NVIDIA spatial computing silicon supply allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Gaming Simulation Market
Gaming
SLG Game Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
Slot Machine Market
Gaming
Mobile Game Software Market
Gaming
China Casino Tourism Market
Gaming
Europe Video Game Software Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
Connected Game Console Market
Gaming
United States Gaming Accessories Market
Gaming
Galgames Market
Gaming
Russia in-Game Advertising Market
Gaming
LAMEA in-Game Advertising Market
Gaming
Traditional Casual Games Market
Gaming
GCC Gaming Headsets Market
Gaming
Australia Gaming Accessories Market