
 Europe Video Game Software Market | 2026-2036
Europe Video Game Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Video Game Software Market Insights
Market Context
Proprietary game engines is shifting from licensed middleware toward in-house render stacks, compressing third-party tool margins. CD Projekt Red leverages its REDengine to sustain direct distribution through GOG Galaxy, bypassing platform fees. Epic Games anchors its position through Unreal Engine licensing while competing on storefront economics. Paradox Interactive specializes in grand-strategy DLC pipelines that dominate niche PC audiences.
Technical Definition and Structural Segments
Europe Video Game Software comprises executable code, runtime assets, and live-service infrastructure delivered across PC, console, mobile, and cloud gaming platforms, requiring real-time rendering pipelines, netcode synchronization, and digital rights management for commercial distribution. The primary purpose is interactive entertainment consumption, with secondary applications in edutainment and esports broadcasting infrastructure. Subscription monetization models are capturing recurring revenue pools as platform holders extend cloud gaming infrastructure. Mobile in-app purchases lead transaction volume across casual gamer demographics, while premium console titles retain margin concentration among hardcore audiences. Free-to-play economies occupy the growth frontier through battle-pass mechanics and cosmetic microtransactions.
Regulatory Frame and Outlook
The EU AI Act and GDPR impose algorithmic transparency and data-processing constraints on adaptive difficulty systems and player-behavior analytics across European jurisdictions. The Digital Services Act and national regulators like France's CNIL shape content moderation duties and age-verification protocols for online multiplayer environments. Stakeholders must monitor emerging platform-antitrust rulings from the European Commission that could unbundle storefront payment systems from hardware ecosystems.
Market Dynamics
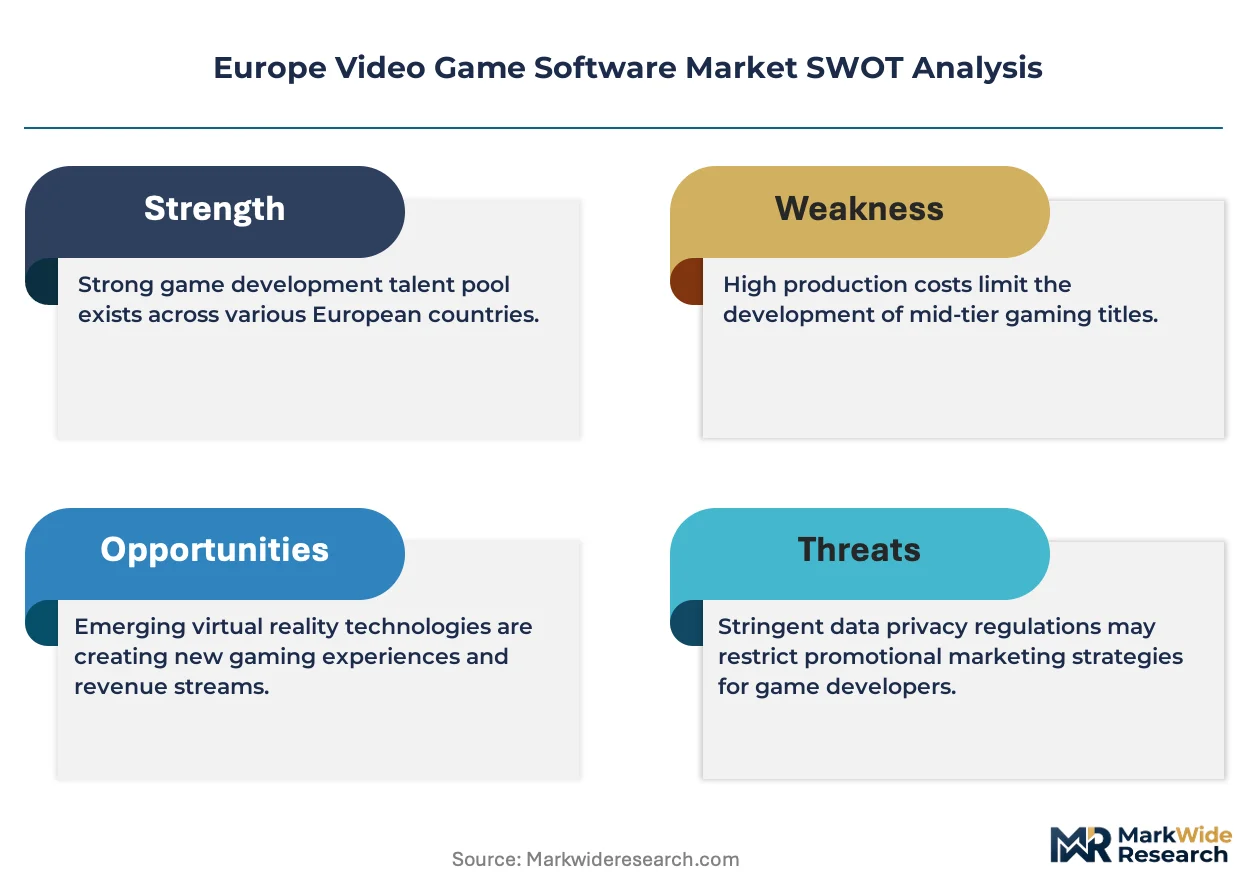
Cloud gaming infrastructure deployment is compressing distribution margins while the EU AI Act imposes algorithmic transparency mandates on adaptive difficulty systems and player analytics, forcing publishers to reengineer live-service architectures.
Growth Catalysts
- Cloud Gaming Infrastructure:Hyperscale data center expansion across Germany and France reduces latency for casual gamer segments. Platform holders are bundling subscription tiers with telecom partnerships to lower customer acquisition costs.
- EU AI Act Compliance:Mandatory algorithmic disclosure requirements for recommendation engines and loot-box mechanics are standardizing player-protection protocols. Publishers investing early in explainable AI systems gain regulatory goodwill.
- Nordic Subscription Adoption:Sweden and Denmark demonstrate the highest per-capita penetration of game-pass services. Local publishers are pivoting from unit sales to recurring revenue pipelines.
Market Restraints
- Third-Party Engine Dependency:Royalty stacking from Unreal Engine and Unity licensing erodes indie developer margins. Middleware concentration limits pricing autonomy for mid-tier studios.
- GDPR Analytics Constraints:Cross-border data transfer restrictions complicate player-behavior modeling for live-service titles. Consent-management overhead extends development timelines.
- Silicon Supply Bottlenecks:TSMC capacity allocation for console SOCs creates hardware scarcity cycles. Semiconductor foundry concentration in Taiwan amplifies geopolitical risk exposure.
Strategic Opportunities
- Polish Indie Export Pipeline:Warsaw and Krakow development clusters specialize in narrative-driven PC titles with low localization overhead. EU Creative Europe MEDIA funding subsidizes prototype development.
- AI-NPC Procedural Generation:Large language model integration with traditional quest design converges with emergent storytelling. Early adopters in the CRPG segment differentiate through reactive dialogue systems.
- Portugal Mobile Publishing:Lisbon-based studios leverage timezone overlap with Brazil for Portuguese-language market access. Low operational costs relative to Northern Europe attract venture backing.
Industry Challenges
- Netcode Engineering Scarcity:Real-time multiplayer synchronization expertise concentrates in Stockholm and Helsinki studios. Compensation inflation for latency-optimization specialists compresses project budgets.
- Age-Verification Implementation:France's CNIL mandates biometric or parental-consent workflows for minor-accessible titles. Technical integration with national identity systems fragments deployment pipelines.
- Legacy Console Certification:First-party platform holder technical requirements consume 6-12 month submission cycles. Patch approval latency constrains live-service update velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Video Game Software Market |
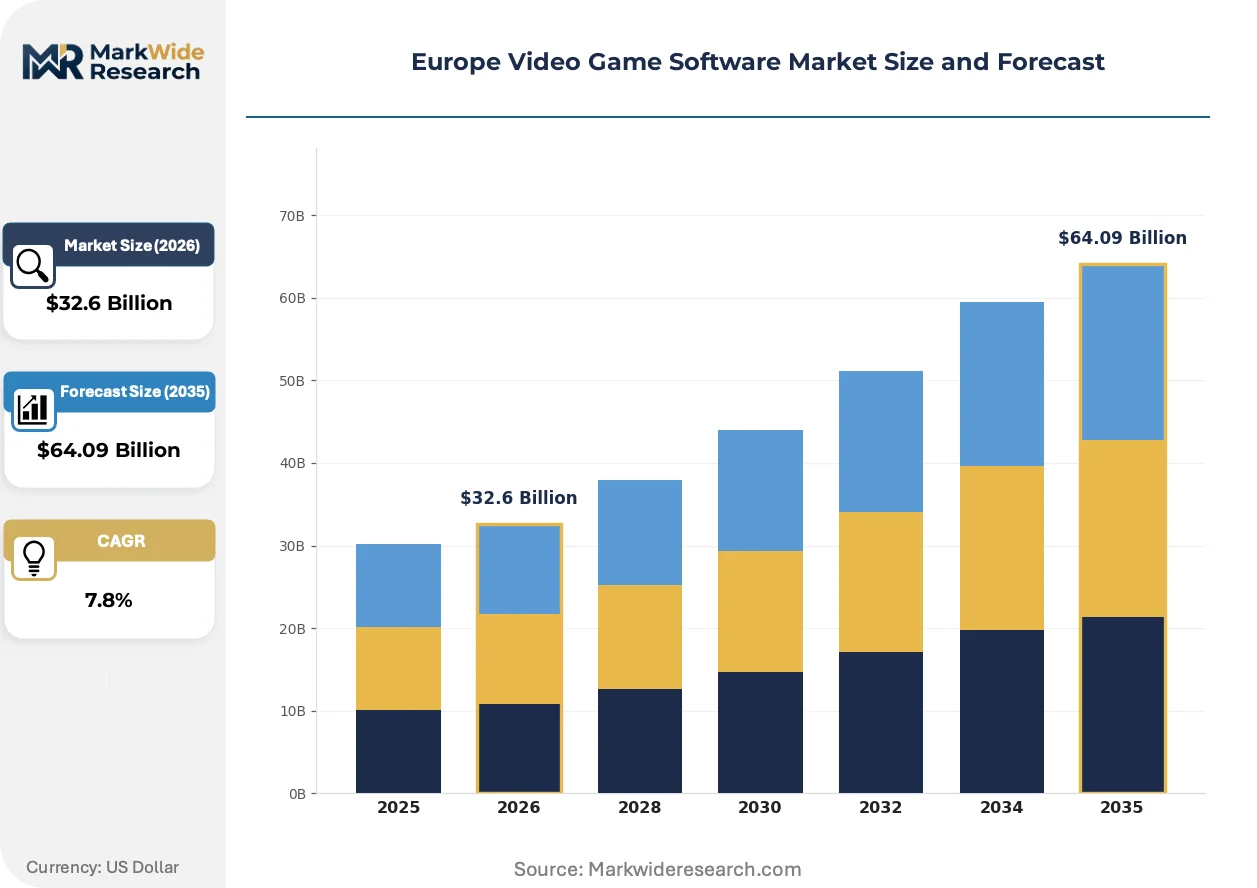
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $64.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: PC, Console, Mobile, Cloud Gaming Genre: Action, Strategy, Role-Playing, Simulation Monetization Model: Free-to-Play, Premium, Subscription, In-App Purchases Target Audience: Casual Gamers, Hardcore Gamers, Children, Adults |
| Companies Covered | Ubisoft Entertainment, CD Projekt Red, Paradox Interactive, Microsoft Studios, Sony Interactive Entertainment, Electronic Arts, Take-Two Interactive, Epic Games, Bandai Namco Entertainment, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Video Game Software Market Trends and Innovations
Generative AI tools are displacing traditional asset pipelines while regulatory pressure on dark patterns reshapes monetization design. Publishers are reconfiguring studio structures around cloud-native development and subscription-first release strategies.
Neural rendering via DLSS and FSR temporal upscaling is converging with real-time ray tracing to reduce hardware entry barriers. Mid-tier GPU owners in Spain and Italy now access premium visual fidelity previously reserved for flagship silicon. This compression democratizes high-fidelity gaming across Southern European price-sensitive demographics.
The EU AI Act's risk-classification framework for manipulative design patterns is forcing loot-box and battle-pass disclosures. Publishers must document probability algorithms and spending intervention triggers. Nordic regulators are extending these mandates to social casino mechanics, compelling Finnish and Swedish studios to rebuild progression economies.
Subscription fatigue among core gamers is fragmenting library commitments across multiple services. German and French households now maintain 2.3 concurrent game-pass memberships on average, below the 3.1 peak. This saturation pressures publishers to negotiate exclusive windowing deals rather than day-one multi-platform releases.
Europe Video Game Software Market Segmentation
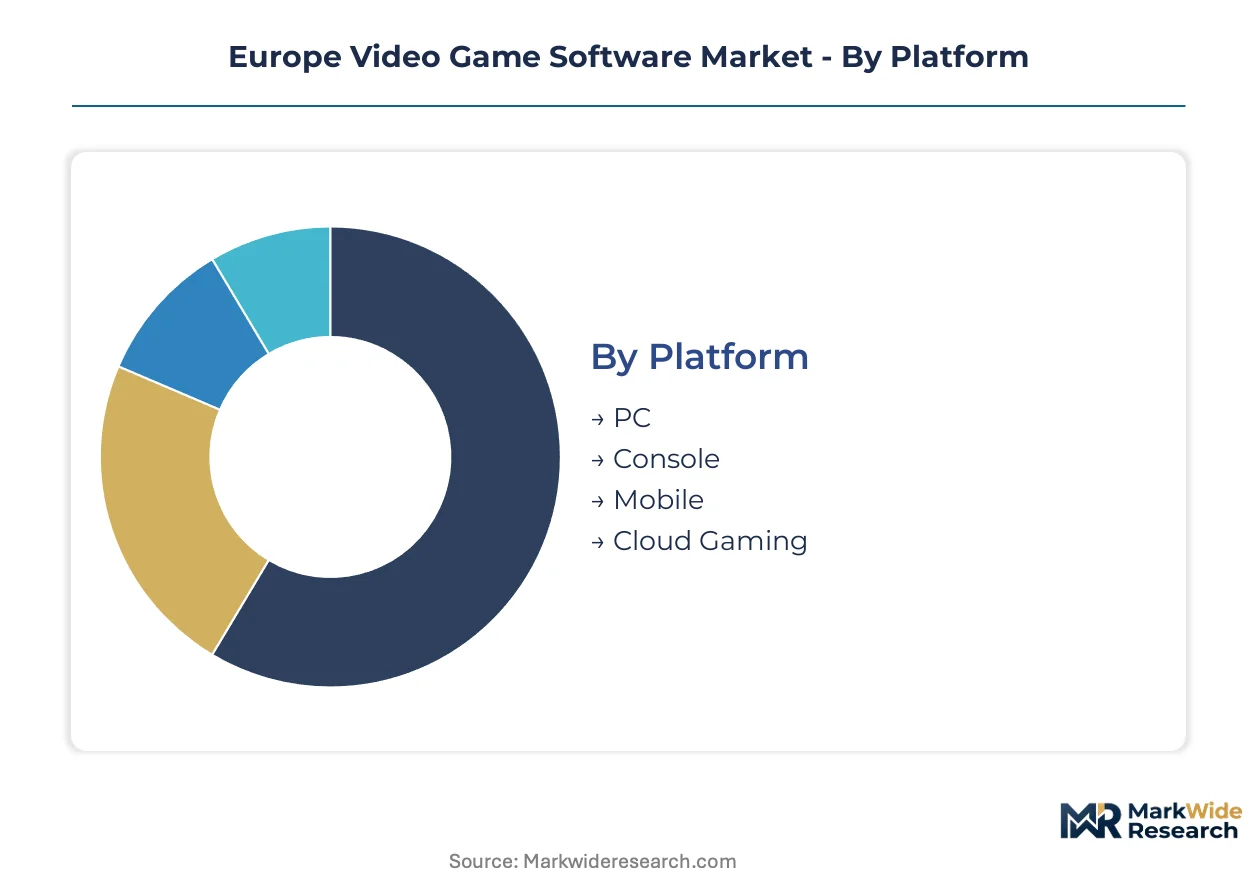
Platform choice dictates technical architecture and monetization feasibility across European markets. Genre preferences cluster around national gaming cultures, from German simulation enthusiasm to Polish RPG affinity. Monetization model selection now carries regulatory weight under the EU AI Act and national consumer protection frameworks.
Platform:
Hardware ownership patterns and connectivity infrastructure separate buyers into distinct spending tiers across the region.
- PC:Open hardware ecosystems support modding communities and direct distribution via Steam and GOG Galaxy. German and Polish markets concentrate demand for high-fidelity rigs with discrete GPUs, driven by esports participation and simulation genre preferences.
- Console:Closed ecosystems from Sony, Microsoft, and Nintendo enforce certification cycles and 30% platform fees. UK and French households dominate unit sales, with subscription bundling through Xbox Game Pass and PlayStation Plus accelerating recurring revenue capture.
- Mobile:Touch-native input schemes and ARM-based SoCs enable hyper-casual session design. Italian and Spanish demographics drive in-app purchase volume through gacha mechanics and rewarded video advertisements.
- Cloud Gaming:Hyperscale data center proximity reduces latency for browser-based and smart TV deployments. Nordic markets lead adoption via fiber infrastructure and telecom partnership bundles.
Volume sits with Mobile; growth tilts toward Cloud Gaming.
Genre:
Development budget scale and audience retention mechanics vary sharply across creative categories.
- Action:High-budget cinematic productions demand motion-capture pipelines and physics-based combat systems. French and UK studios specialize in third-person cover shooters with live-service roadmaps.
- Strategy:Paradox Interactive and Creative Assembly anchor grand-strategy and real-time tactics subgenres. Paradox's DLC-heavy monetization dominates niche PC audiences in Germany and Scandinavia.
- Role-Playing:Branching narrative structures and character progression systems require extensive localization. CD Projekt Red's Warsaw-based production of open-world RPGs exemplifies Polish export specialization.
- Simulation:German markets concentrate demand for vehicle, farming, and city-builder subgenres. Giants Software and Colossal Order capture recurring revenue through expansion packs and modding platform integration.
Revenue concentrates in Action; the steepest expansion trajectory belongs to Role-Playing.
Monetization Model:
Regulatory scrutiny intensity and player lifetime value calculations diverge across revenue architectures.
- Free-to-Play:Zero-entry-price models fund development through cosmetic microtransactions and battle-pass seasonality. Finnish and Swedish studios pioneered progression economy design now facing Nordic regulator intervention on dark pattern disclosures.
- Premium:Upfront unit sales sustain single-player narrative experiences with limited post-launch support. Polish and Czech indie studios favor this model for narrative-driven PC exports with low localization overhead.
- Subscription:Recurring access fees to content libraries shift revenue recognition from point-of-sale to retention metrics. Xbox Game Pass and PlayStation Plus compete for household budget share in UK and German markets.
- In-App Purchases:Microtransaction granularity enables whale monetization in mobile gacha and social casino verticals. Portugal-based publishers leverage timezone overlap with Brazil for Portuguese-language market access.
Transaction volume flows through In-App Purchases; regulatory pressure is reshaping Free-to-Play fastest.
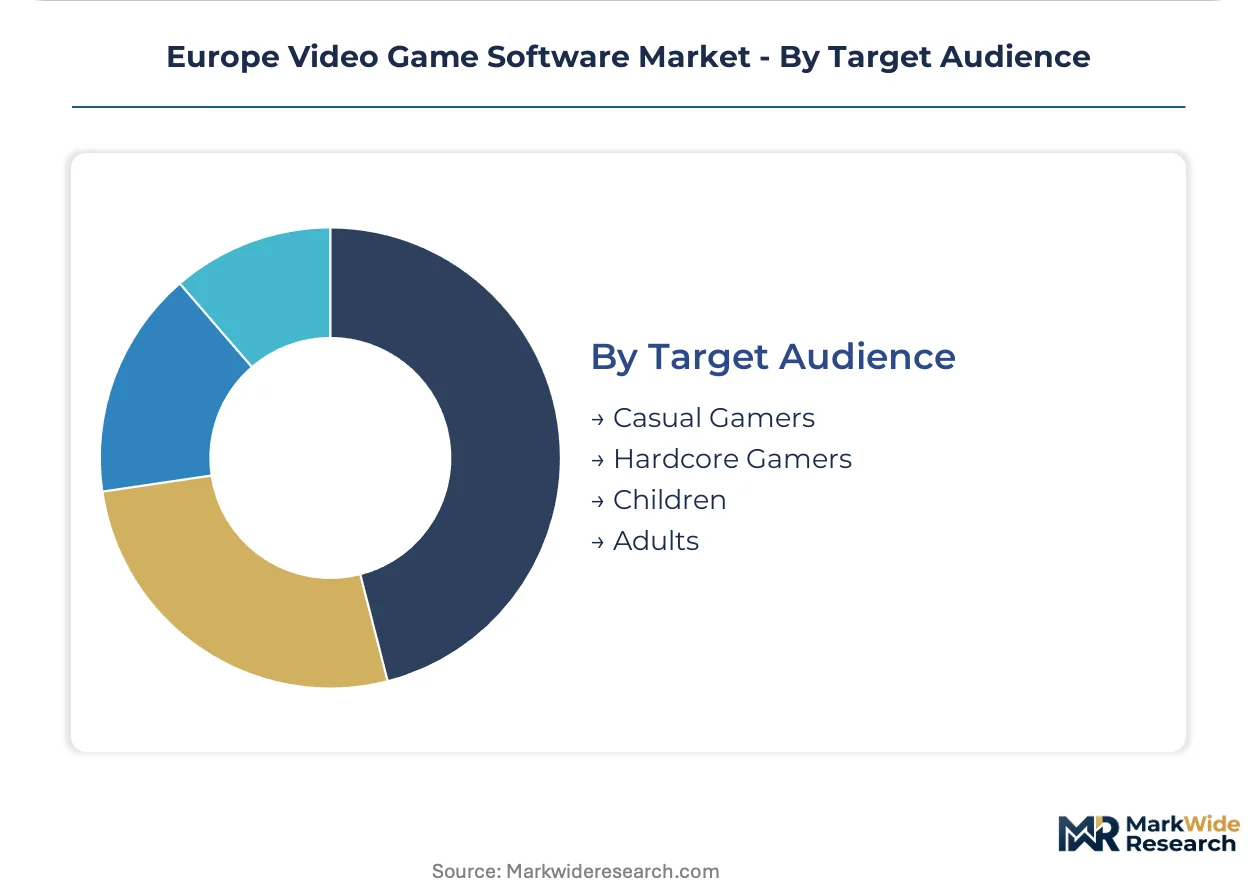
Target Audience:
Session length expectations and spending elasticity separate demographic segments with distinct acquisition costs.
- Casual Gamers:Fragmented session patterns and low switching costs favor mobile hyper-casual and cloud gaming access. French and Italian demographics demonstrate highest cloud gaming adoption rates among this cohort.
- Hardcore Gamers:High engagement hours and community participation justify premium hardware and subscription stacking. German and UK markets show highest per-capita spending on multiple concurrent game-pass memberships.
- Children:Age-verification mandates under France's CNIL and GDPR parental consent requirements complicate onboarding flows. Publishers must integrate biometric or national identity system workflows.
- Adults:Disposable income concentration supports premium pricing and collector's edition physical goods. Nordic markets demonstrate highest subscription penetration among this demographic.
Spending intensity clusters with Hardcore Gamers; regulatory friction is accelerating fastest for Children.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German households concentrate per-capita spending on premium PC hardware and subscription stacking, while French cloud gaming adoption leads Southern European penetration rates. Nordic markets demonstrate the highest game-pass penetration globally, and Polish development clusters anchor Eastern European export capacity.
Germany
Simulation genre enthusiasm and esports participation drive demand for high-fidelity PC rigs with discrete GPUs. The KBA and federal media regulators enforce age-verification protocols for online multiplayer titles. Cologne and Hamburg host major development studios specializing in vehicle and farming simulation subgenres.
United Kingdom
Console unit sales dominate hardware ownership, with Xbox Game Pass and PlayStation Plus competing for household budget share. The Information Commissioner's Office applies GDPR constraints to player-behavior analytics and cross-border data transfers. London and Manchester clusters focus on third-person action titles with live-service roadmaps.
France
Cloud gaming adoption accelerates fastest among casual gamer demographics across Paris and Lyon metro areas. CNIL mandates biometric or parental-consent workflows for minor-accessible titles under strict data protection interpretations. Paris-based studios specialize in cinematic action productions with motion-capture pipelines.
Sweden
Per-capita game-pass penetration exceeds all European markets, driving publisher pivots from unit sales to recurring revenue. The Swedish Consumer Agency extends EU AI Act mandates to social casino mechanics and dark pattern disclosures. Stockholm studios concentrate netcode engineering expertise for multiplayer synchronization.
Poland
Narrative-driven PC RPG exports sustain low localization overhead for English-speaking markets. EU Creative Europe MEDIA funding subsidizes prototype development for Warsaw and Krakow development clusters. CD Projekt Red's REDengine exemplifies in-house render stack investment bypassing third-party platform fees.
Europe Video Game Software Market Competitive Landscape
Technology licensing dominates the current landscape as publishers renegotiate engine royalty structures and platform distribution terms. The market exhibits tiered concentration: integrated platform holders extract storefront economics, specialized engine licensors capture middleware rents, and regional indie clusters compete on narrative differentiation. Three archetypes define competitive positioning: vertically integrated conglomerates with captive hardware ecosystems, specialized engine developers monetizing through SaaS-style licensing, and regional narrative specialists leveraging EU subsidy programs. M&A activity targets live-service expertise and AI tooling capabilities, while strategic partnerships between telecom operators and cloud gaming platforms reshape distribution economics.
Among integrated platform holders, Microsoft Studios and Sony Interactive Entertainment exemplify the hardware-captive ecosystem model. CD Projekt Red occupies a distinctive position as a regional specialist that vertically integrated into direct distribution through GOG Galaxy. Epic Games sits within the engine-licensing tier, competing simultaneously on storefront economics and middleware revenue. These three represent divergent responses to platform fee compression and regulatory pressure on alternative payment systems.
| Leading Market Players |
|---|
| Ubisoft Entertainment |
| CD Projekt Red |
| Paradox Interactive |
| Microsoft Studios |
| Sony Interactive Entertainment |
| Electronic Arts |
| Take-Two Interactive |
| Epic Games |
| Bandai Namco Entertainment |
| Others |
Pricing and Supply Chain Analysis
Engine licensing royalties from Unreal Engine and Unity flow downstream through three distinct pricing tiers, with indie studios absorbing the steepest cost compression while premium publishers negotiate volume discounts. Middleware concentration in middleware licensing reshapes margin distribution across development budget scales.
Pricing Analysis
Volume concentrates in free-to-play microtransaction pools while margins cluster in premium console unit sales and subscription recurring revenue. Three-tier pricing structure across premium collector's editions, standard digital releases, and economy-tier subscription access separates spending tiers. Pricing pressure stems from platform holder fee compression and regulatory mandates on loot-box probability disclosures. Casual mobile gamers exhibit highest price sensitivity; hardcore PC builders demonstrate lowest elasticity for flagship hardware bundles.
Supply Chain Analysis
Domestic-content mandates under the EU AI Act and GDPR data-localization requirements are reshaping server infrastructure sourcing toward European data center operators. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States; game engine middleware development clusters in Sweden, Poland, and the United Kingdom. Raw material dependencies span advanced node silicon wafers, rare earth elements for GPU manufacturing, and cobalt for battery supply in handheld devices. Single-source vulnerability in TSMC foundry capacity creates hardware scarcity cycles. Distribution runs through platform-holder digital storefronts with 30% revenue shares.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as EU AI Act compliance costs force sub-scale publishers toward acquisition or exit. Algorithmic transparency mandates and live-service infrastructure investments favor capital-rich integrated players.
For Market Incumbents: Anticipate regulatory escalation on dark pattern disclosures by pre-positioning explainable AI documentation and player-spending intervention triggers. Deepen backward integration into proprietary render stacks to escape third-party engine royalty stacking. Prioritize cloud gaming infrastructure partnerships with telecom operators to lock in distribution economics before saturation. For New Entrants and Emerging Players: Direct-to-consumer storefront routes via Steam and Epic Games Store bypass platform certification cycles and fee structures for PC-first releases. Polish and Portuguese development clusters offer lowest localization overhead for English-speaking and Brazilian markets respectively. Target narrative-driven indie RPG segments where AI-NPC procedural generation creates differentiation without AAA motion-capture budgets. For Investors and Strategic Acquirers: Early EU AI Act compliance certification is the leading indicator that a studio has secured regulatory goodwill and reduced future reengineering liabilities. Long-term viability favors publishers with captive subscription bases and recurring revenue pipelines over unit-sales-dependent single-player specialists. Monitor Nordic regulator extensions of dark pattern mandates to social casino mechanics as a signal for forced monetization model pivots.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Engine Development | CD Projekt Red's REDengine demonstrates how in-house render stacks bypass 30% platform fees through direct distribution. |
| Cloud Gaming Infrastructure Partnership | Telecom bundling in Nordic markets compresses customer acquisition costs for subscription tier expansion. |
| AI-NPC Procedural Generation Integration | Large language model deployment in CRPG segments differentiates through reactive dialogue without branching script overhead. |
| EU AI Act Compliance Pre-Certification | Early algorithmic disclosure investment secures regulatory goodwill ahead of mandatory loot-box probability transparency. |
| Regional Cluster Expansion | Warsaw and Krakow development hubs leverage EU Creative Europe MEDIA funding to subsidize prototype pipelines. |
Research Methodology
Independent corroboration across live-service operations directors, platform partnership leads, and regulatory compliance officers underwrites the qualitative findings on EU AI Act implementation timelines. Secondary validation draws from European Commission antitrust filings, national data protection authority enforcement actions, hyperscaler cloud infrastructure capex disclosures, and platform holder revenue share documentation. Bottom-up project pipeline analysis triangulates against top-down subscription penetration metrics across Nordic, German, and French household surveys.
Comparable historical reference periods anchor the projection framework across the analysis window, with CAGRs derived from segment-level subscription growth trajectories and cloud infrastructure deployment curves. Modeled dimensions span platform hardware ownership, genre development budget tiers, monetization model regulatory exposure, and regional connectivity infrastructure maturity. Forecast inputs incorporate telecom partnership density, age-verification technical implementation costs, and engine licensing royalty rate negotiations.
The model holds under sustained EU regulatory enforcement and stable semiconductor supply; deviation in Taiwan geopolitical stability or platform antitrust unbundling rulings would shift publisher margin assumptions. Forecasts reflect documented assumptions on subscription fatigue saturation points and cloud gaming latency reduction curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Global Game Testing Service Market
Gaming
Game Engine Management Market
Gaming
Racing Games Market
Gaming
Lottery Market
Gaming
Australia Gaming Accessories Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Global Online Gambling and Betting Market
Gaming
Game Applications Market
Gaming
North America in-Game Advertising Market
Gaming
United Kingdom Online Gambling Market
Gaming
Simulation Video Game Market
Gaming
North America Casino Gambling Market
Gaming
Latin America Gaming Headsets Market
Gaming
China Casino Tourism Market
Gaming
Game API Market
Gaming
Gaming Peripheral Market