
 Global Broadcast Switcher Market | 2026-2036
Global Broadcast Switcher Market Size, Share, and Industry Trends Forecast 2026-2036
Global Broadcast Switcher Market Foresight
South Korea is fragmenting the Asia-Pacific supply base for broadcast switcher components as domestic foundries expand mixed-signal capacity. Sony Corporation leverages its imaging sensor heritage to anchor premium production switcher lines. Grass Valley sustains North American installed base loyalty through deep service networks. Blackmagic Design Pty. Ltd. competes aggressively on price-performance in the content creator tier.
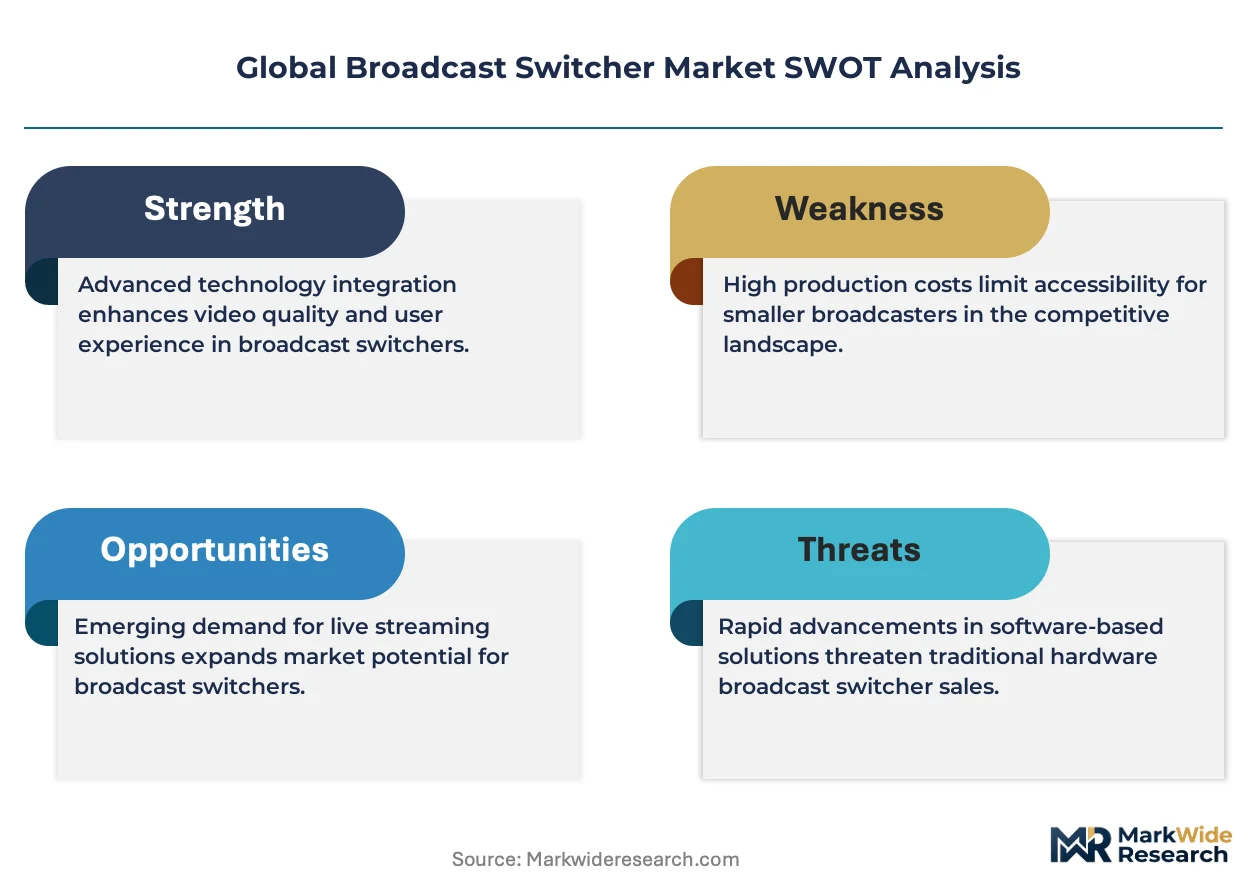
A broadcast switcher is a multi-input video processing device that selects, transitions, and composites live video signals using crosspoint matrices ranging from 8x2 to 512x512 configurations, serving as the central nervous system of live television and streaming production. Production switchers command the largest margin pools due to their integrated effects engines and multi-layer compositing requirements. IP-Based switchers represent the fastest-expanding technology segment as SMPTE ST 2110 adoption displaces baseband SDI routing in greenfield installations. Routing switchers remain a mature workhorse category with replacement-driven demand concentrated in legacy broadcast facilities.
The FCC mandates ATSC 3.0 transition timelines that force broadcaster capital allocation toward compatible switcher infrastructure. EMA and CE marking requirements under the EU Radio Equipment Directive shape product certification costs for European deployments. China's MIIT enforces GB standards for electromagnetic compatibility that filter market access for imported broadcast equipment. Stakeholders must monitor IP interoperability certification progress and regional spectrum policy divergence to time infrastructure refresh decisions effectively.
Market Dynamics
The broadcast switcher market pivots on the collision between IP-native production architectures and the installed base of SDI-dependent facilities, forcing capital allocation decisions that favor modular upgrade paths over wholesale replacement cycles.
Growth Catalysts
- SMPTE ST 2110 adoption:IP-based routing standards enable software-defined switching that reduces cabling density and facility footprint for live production centers.
- ATSC 3.0 mandates:The FCC's next-generation broadcast standard compels US stations to refresh infrastructure with switchers capable of 4K HDR and advanced audio routing.
- Live streaming proliferation:Esports venues, houses of worship, and corporate event spaces now require broadcast-grade switching for multi-platform distribution.
Market Restraints
- FPGA supply concentration:Xilinx and Intel dominate programmable logic for real-time video processing, creating single-source vulnerability for mid-tier manufacturers.
- SDI-to-IP transition friction:Hybrid facilities face interoperability gaps between baseband and packetized workflows, extending depreciation timelines.
- Specialized technician scarcity:IP networking expertise remains scarce among traditional broadcast engineers, slowing deployment velocity.
Strategic Opportunities
- India studio buildout:Regional language channel expansion and OTT original production drive demand for cost-optimized production switchers in Mumbai and Hyderabad.
- Remote production models:Distributed switching over managed IP networks allows centralized control of geographically dispersed events, reducing on-site crew requirements.
- EU Green Deal alignment:Energy efficiency certifications under evolving CE marking frameworks create preference for low-power switcher architectures in facility tenders.
Industry Challenges
- Multi-vendor integration complexity:ST 2110 implementations require precise PTP timing synchronization across cameras, switchers, and storage from different suppliers.
- Certification timeline compression:New product introductions must navigate simultaneous FCC, CE, and MIIT electromagnetic compatibility testing for multi-region launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Broadcast Switcher Market |
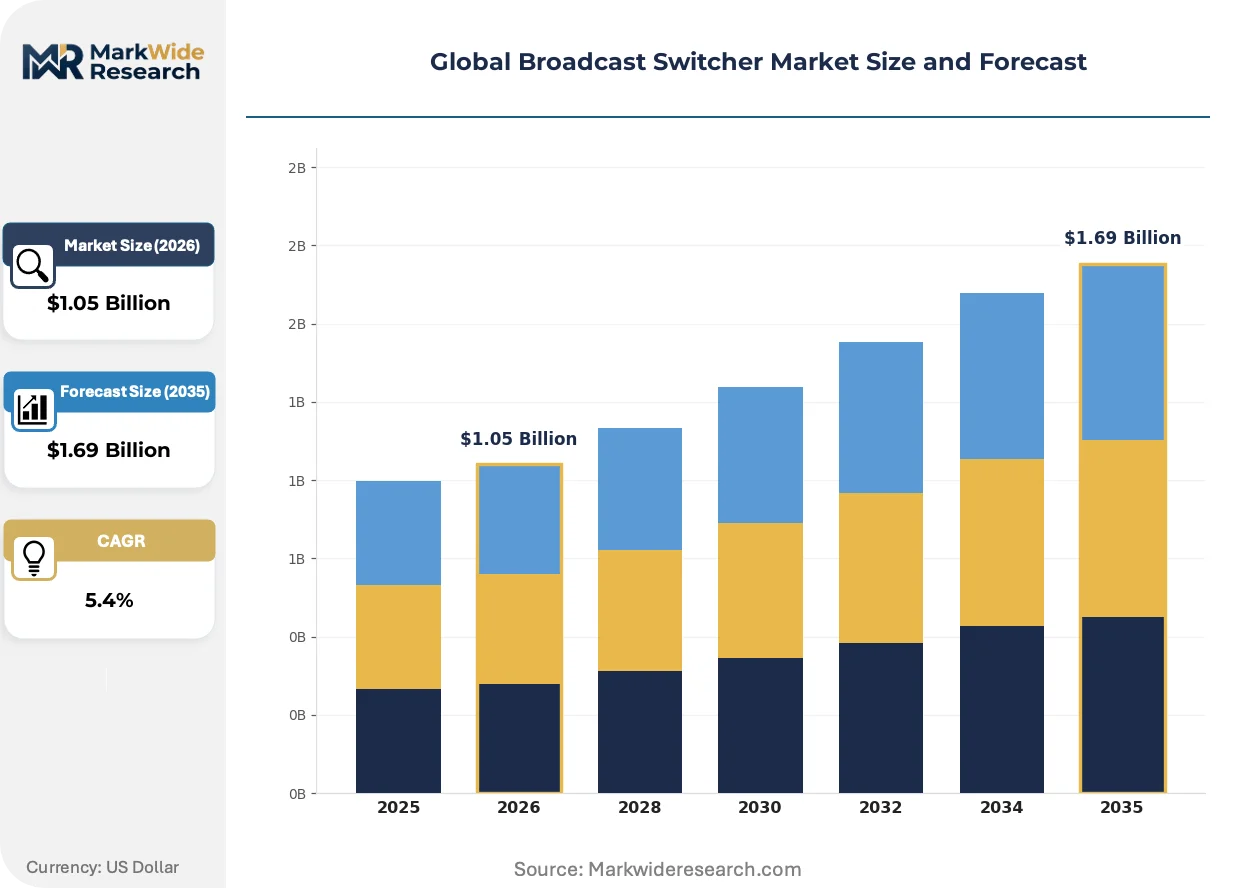
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mixers, Routing Switchers, Production Switchers, Control Panels, Video Servers Technology: SDI, IP-Based, Analog, HD-SDI, 4K UHD, Fiber Optic Application: Live Event Production, Studio Broadcasting, Remote Broadcasting, Sports Coverage, News Production, Education Streaming End User: Broadcasters, Content Creators, Video Production Houses, Government Agencies, Event Organizers |
| Companies Covered | Sony Corporation, Ross Video Ltd., Grass Valley, Panasonic Corporation, Blackmagic Design Pty. Ltd., Evertz Microsystems Limited, FOR-A Company Limited, NewTek Inc., Broadcast Pix Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Broadcast Switcher Market Shifts & Advancements
Production workflows are fragmenting across on-premise, cloud-hybrid, and fully remote configurations, forcing switcher architectures to accommodate signal paths that span facility boundaries and operator locations.
Software-defined production switching is migrating from proprietary hardware appliances to containerized applications running on commercial-off-the-shelf servers. Mid-market broadcasters and corporate video departments adopt this model fastest, drawn by OpEx flexibility and elastic capacity scaling. The technology is migrating from high-end broadcast facilities toward tier-two markets, compressing margins for traditional hardware-centric vendors while expanding addressable market volume.
The EU Radio Equipment Directive's 2024 amendments tighten electromagnetic emissions thresholds for professional video equipment. Manufacturers now face retesting costs for existing product lines and redesign cycles for new platforms. German and French system integrators report extended procurement timelines as certification documentation requirements expand.
Service contracts now unbundle hardware maintenance from software support, with buyers preferring subscription access to feature updates over perpetual licenses. This restructuring concentrates recurring revenue with vendors who operate direct customer success functions. The shift is most visible among US regional broadcast groups consolidating vendor relationships under enterprise agreements.
Global Broadcast Switcher Market Segmentation
Segmentation in broadcast switchers reveals divergent service intensity patterns across product tiers. After-sales support contracts vary dramatically between mission-critical production switchers and commodity routing hardware.
Product Type:
After-sales-service intensity clusters heavily around production switchers and control panels, where firmware updates and calibration cycles generate recurring vendor revenue.
- Production Switchers:Multi-layer compositing engines with integrated effects processing dominate premium installations. Demand concentrates in live sports venues across the United States and Germany, driven by 4K HDR production mandates and operator training requirements.
- Routing Switchers:Crosspoint matrices from 64x64 to 512x512 configurations handle signal distribution in facility cores. Replacement cycles in legacy US broadcast centers accelerate under FCC spectrum repack timelines, though IP migration extends depreciation for hybrid facilities.
- Mixers:Audio-follow-video architectures for small-format production carry lighter service burdens.
- Control Panels:Tactile interfaces with customizable macro banks require periodic hardware refurbishment.
- Video Servers:Playout and recording subsystems integrate loosely with switching cores.
By volume, routing switchers lead. By growth pace, production switchers are expanding most quickly.
Technology:
Cost tier stratification separates IP-native platforms from legacy baseband infrastructure, with hybrid SDI-IP configurations occupying a transitional pricing band.
- IP-Based:SMPTE ST 2110 packetized workflows enable software-defined routing on commercial servers. Greenfield installations in China and South Korea favor these architectures for facility footprint reduction, though PTP synchronization complexity elevates integration costs.
- 4K UHD:12G-SDI and 25GbE transport handles 2160p60 with HDR metadata. Studio modernization in Germany and Japan drives replacement demand as production pipelines upgrade from HD infrastructure.
- SDI:Coaxial baseband remains entrenched in installed facilities.
- HD-SDI:3G-SDI infrastructure serves tier-two broadcasters with constrained capital.
- Fiber Optic:Long-haul camera connectivity for remote production.
- Analog:Residual presence in legacy educational and government facilities.
By volume, SDI retains the largest installed base. By growth pace, IP-Based switchers are gaining share fastest.
Application:
Volume concentration in studio broadcasting contrasts with customer-type fragmentation across emerging use cases.
- Live Event Production:Multi-camera switching for concerts, corporate events, and houses of worship requires portable control surfaces. Demand clusters in US metropolitan markets and Chinese tier-one cities, propelled by streaming platform content requirements.
- Sports Coverage:Slo-mo replay integration and multi-feed distribution demand specialized production switchers. Stadium infrastructure projects in Germany and Qatar drive specification intensity for 4K HDR workflows.
- Studio Broadcasting:Fixed-installation production centers with redundant signal paths.
- Remote Broadcasting:Distributed production over managed IP networks.
- News Production:Fast-turnaround switching with MOS integration.
- Education Streaming:Cost-optimized configurations for university media departments.
By volume, studio broadcasting leads. By growth pace, live event production shows the steepest expansion trajectory.
End User:
Customer-type maturity separates broadcasters with depreciated SDI plants from content creators building IP-native facilities.
- Broadcasters:National networks and affiliate groups with regulatory compliance obligations. Capital allocation in the United States responds to FCC ATSC 3.0 mandates, while China's provincial broadcasters modernize under MIIT technical standards.
- Video Production Houses:Independent facilities serving advertising and branded content. Mumbai and Hyderabad clusters in India drive demand for mid-tier production switchers as regional OTT production expands.
- Content Creators:YouTube-native studios and esports venues.
- Event Organizers:Rental and staging companies with mobile production units.
- Government Agencies:Municipal access channels and legislative broadcast systems.
By volume, broadcasters lead. By growth pace, video production houses are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: US broadcasters prioritize ATSC 3.0-compliant 4K HDR infrastructure, while Chinese and South Korean facilities favor IP-native greenfield builds that skip SDI transitional stages entirely.
United States
FCC spectrum repack mandates and ATSC 3.0 transition timelines drive equipment refresh cycles across network affiliates and independent stations. The FCC's next-generation broadcast standard compels capital allocation toward switchers with advanced audio routing and HDR metadata handling. Facility modernization concentrates in Atlanta, Los Angeles, and New York broadcast centers where network origination infrastructure requires redundant signal paths.
Germany
Studio infrastructure modernization for 4K UHD production and live sports venue upgrades anchor demand in Europe's largest broadcast equipment market. The EU Radio Equipment Directive's tightened electromagnetic emissions thresholds under 2024 amendments extend certification timelines and elevate retesting costs for deployed product lines. System integrators in Munich and Hamburg report elongated procurement cycles as documentation requirements expand.
China
Provincial broadcaster modernization under MIIT technical standards and OTT original production expansion fuel switcher procurement. MIIT enforces GB standards for electromagnetic compatibility that filter market access for imported broadcast equipment. Production facility buildout clusters in Beijing, Shanghai, and Shenzhen where state media groups and streaming platforms commission IP-native installations.
South Korea
Domestic foundry expansion in mixed-signal semiconductor capacity is fragmenting the Asia-Pacific supply base for broadcast switcher components. The country's national broadcast regulator shapes technical standards for terrestrial and cable transmission infrastructure. Seoul and Suwon host design and integration centers where local vendors develop ST 2110-compatible switching platforms for regional export.
India
Regional language channel expansion and OTT original production drive demand for cost-optimized production switchers. TRAI licensing frameworks for broadcast distribution and cable digitization mandates influence capital allocation timelines for facility operators. Mumbai and Hyderabad production clusters serve advertising, Bollywood, and streaming content creation with mid-tier switching configurations.
Global Broadcast Switcher Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three distinct strata: imaging heritage conglomerates, broadcast-specialized independents, and price-disruptive content creator specialists. Consolidation pressure runs highest among mid-tier hardware vendors as software-defined switching migrates to containerized server architectures. Dominant competitive moves include geographic expansion through regional system integrator partnerships and backward integration into FPGA programming for real-time video processing.
Within the imaging heritage tier, Sony Corporation anchors premium production switcher lines leveraging sensor technology integration. Grass Valley sustains North American installed base loyalty through service network depth. Blackmagic Design Pty. Ltd. occupies a position exemplifying aggressive price-performance competition in the content creator and independent production tier.
| Leading Market Players |
|---|
| Sony Corporation |
| Ross Video Ltd. |
| Grass Valley |
| Panasonic Corporation |
| Blackmagic Design Pty. Ltd. |
| Evertz Microsystems Limited |
| FOR-A Company Limited |
| NewTek Inc. |
| Broadcast Pix Inc. |
| Others |
Supply & Pricing Matrix
Trans-Pacific container freight corridors linking Shenzhen and Los Angeles transmit cost volatility directly into component landed costs, compressing margin buffers for mid-tier manufacturers while amplifying price spreads between premium IP-native switchers and legacy SDI alternatives. This logistics pressure intersects with FPGA supply concentration to reshape procurement strategies across the vendor base.
Pricing Analysis
Geographic price spreads between North American and Asia-Pacific deployments reach two-to-three multiples for equivalent production switcher specifications, reflecting certification burden differentials under FCC versus MIIT electromagnetic compatibility regimes. Three-tier pricing structure across premium, standard, and economy levels separates Sony and Grass Valley service-integrated offerings from Blackmagic Design's hardware-centric models. Cost compression in the content creator tier intensifies as software-defined switching migrates to containerized server architectures. Video production houses in India exhibit highest price sensitivity, while US network affiliates prioritize total cost of ownership over unit acquisition.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for programmable logic and mixed-signal semiconductor procurement. Manufacturing concentration rests on Taiwan for advanced FPGA fabrication, South Korea for memory components, and China for PCB assembly and mechanical enclosures. Xilinx and Intel programmable logic devices represent single-source vulnerability for real-time video processing engines. Distribution runs through authorized distributor networks serving systems integrators in Munich, Atlanta, and Singapore, with direct enterprise relationships consolidating among top-tier broadcast groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workflow fragmentation across on-premise, cloud-hybrid, and remote production models fragments addressable demand into specialized niches, creating entry points for focused competitors alongside consolidation opportunities for scale players.
For Market Incumbents: Pre-empt software-defined switching displacement by accelerating backward integration into FPGA programming capabilities for real-time video processing. Consolidate service contract portfolios under enterprise agreements with US regional broadcast groups to lock in recurring revenue streams against Blackmagic Design's hardware-centric encroachment. Deepen certification investment for EU Radio Equipment Directive compliance to extend procurement timeline advantages. For New Entrants and Emerging Players: Mid-tier production switchers for India's Mumbai and Hyderabad studio clusters represent the most penetrable entry point, with regional OTT original production driving specification intensity below Sony-Grass Valley premium positioning. Target cost-optimized ST 2110-compatible platforms for European tier-two broadcasters facing Green Deal energy efficiency mandates. Pursue channel partnerships with German and French systems integrators navigating extended procurement cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from imaging heritage conglomerates seeking to divest non-core broadcast equipment divisions amid software-defined architecture transitions. Position for five-to-ten year viability around IP-native production workflow dominance, with SDI-to-IP transition velocity as the critical inflection signal. Monitor PTP synchronization standardization progress as integration complexity barrier indicator.| Strategic Initiative | Industry Significance |
|---|---|
| SMPTE ST 2110 Certification Investment | CE marking and FCC electromagnetic compatibility testing unlock multi-region deployment for greenfield IP-native facilities. |
| Software-Defined Platform Migration | Containerized switching applications on commercial servers expand addressable market into mid-market corporate video departments. |
| Regional Systems Integrator Partnership | Munich, Singapore, and Atlanta channel relationships compress sales cycles for complex multi-vendor ST 2110 installations. |
| Backward Integration into FPGA Programming | In-house real-time video processing development reduces Xilinx and Intel single-source vulnerability for premium production switchers. |
| Service Contract Unbundling | Subscription software support models concentrate recurring revenue with vendors operating direct customer success functions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, MIIT GB standard filings, and EU Radio Equipment Directive technical documentation. Primary interviews with broadcast engineering directors, systems integrator technical leads, and regional station group procurement officers informed demand-side validation. Secondary sources included SMPTE standards committee proceedings, semiconductor distributor bill-of-materials analyses, and facility construction permits for studio infrastructure projects. Bottom-up unit deployment estimates triangulated against top-down capital expenditure allocations across the analysis window.
Forecast inputs span product type segmentation across production, routing, and control panel categories; technology migration pathways from SDI through hybrid to IP-native architectures; and end-user differentiation between broadcasters, video production houses, and content creators. CAGRs derive from installed base depreciation modeling, greenfield facility commissioning schedules, and regulatory mandate compliance timelines. Industry-specific inputs incorporate ATSC 3.0 transition velocity, OTT original production commissioning rates, and remote production technical adoption curves.
Macroeconomic conditions sit as an overlay; deviation in capital expenditure cycles, semiconductor foundry capacity allocation, or trans-Pacific freight rates would shift the trajectory. Forecasts reflect documented assumptions regarding standards adoption timelines and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
AI Computing Hardware Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market