
 Pre Terminated Systems Market | 2026-2036
Pre Terminated Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Pre Terminated Systems Market Intelligence
Integrated support and maintenance services are broadening the scope of pre-terminated system sales beyond physical hardware. Corning Incorporated leverages its deep expertise in fiber optics to offer comprehensive solutions for high-bandwidth applications. CommScope Holding Company, Inc. competes by providing end-to-end network infrastructure for complex data center environments. Schneider Electric integrates these systems within its broader energy management and automation platforms.
Pre-terminated systems consist of cables and connectivity components assembled and tested in a controlled factory environment. These solutions, verified for performance metrics like insertion loss before deployment, are designed to accelerate installation and ensure reliability in critical network infrastructures. Fiber optic cables command the largest product share due to superior bandwidth capacity for modern networks. The data centers vertical shows the highest adoption rate, driven by the need for scalable and high-density connectivity.
Compliance with performance standards, such as TIA-942 for data center infrastructure in the United States, is essential for market access. In Europe, regulations like RoHS and the requirements for CE marking govern material composition and product safety, impacting manufacturing processes. Key vendors must now decide how to balance the efficiency of standardized products with increasing customer demand for tailored, application-specific configurations.
Market Dynamics
The central dynamic shaping the pre-terminated systems market is the relentless pace of hyperscale data center construction. This demand for accelerated, error-free deployment of high-density network infrastructure is driving a structural shift away from traditional field termination toward factory-verified solutions.
Growth Catalysts
- Ethernet Standards Evolution:The migration to 400G and 800G Ethernet in data centers requires high-density, low-loss fiber connectivity that factory-tested systems are uniquely positioned to provide, ensuring signal integrity for high-speed data transmission.
- Data Center Construction Boom:Concentrated development of hyperscale facilities in hubs like the United States, Germany, and Singapore creates large-scale, recurring demand for rapid and reliable network cabling deployments.
- Infrastructure Reliability Standards:Adherence to frameworks such as the TIA-942 standard for data center infrastructure compels operators to adopt proven, performance-verified components to ensure uptime and operational consistency.
Market Restraints
- Higher Upfront Cost:The initial capital expenditure for pre-terminated assemblies is greater than that for bulk cable and connectors, posing a barrier for smaller enterprises or projects with constrained budgets.
- Design Inflexibility:Once manufactured, cable lengths and connector configurations are fixed. This lack of on-site adaptability can create challenges in brownfield sites or projects where initial measurements were imprecise.
- Supply Chain Dependencies:The market relies on a concentrated group of specialized manufacturers for high-performance components like multi-fiber MPO connectors, creating potential bottlenecks and longer lead times.
Strategic Opportunities
- Edge Computing Infrastructure:The proliferation of edge data centers presents a new frontier, as these smaller, distributed sites require the same rapid deployment and reliability benefits that pre-terminated systems offer.
- Emerging Data Center Markets:Expansion into developing data center geographies, such as Brazil and India, offers significant growth potential as these regions build out their digital infrastructure to support cloud services.
- Smart Cabling Integration:Incorporating sensors and intelligence into connectivity components to feed data into Data Center Infrastructure Management (DCIM) platforms creates a new value proposition around network monitoring and management.
Industry Challenges
- Network Design Skill Gap:Effective deployment requires meticulous upfront planning and precise measurements, creating a demand for network architects with specialized design skills that are currently in short supply.
- Legacy System Integration:In brownfield data center upgrades, ensuring seamless interoperability between new pre-terminated systems and existing, field-terminated legacy infrastructure is a significant technical hurdle.
- Installation Logistics:Managing the just-in-time delivery and handling of precise-length, often bulky, cable assemblies on a complex construction site demands sophisticated project management and supply chain coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre Terminated Systems Market |
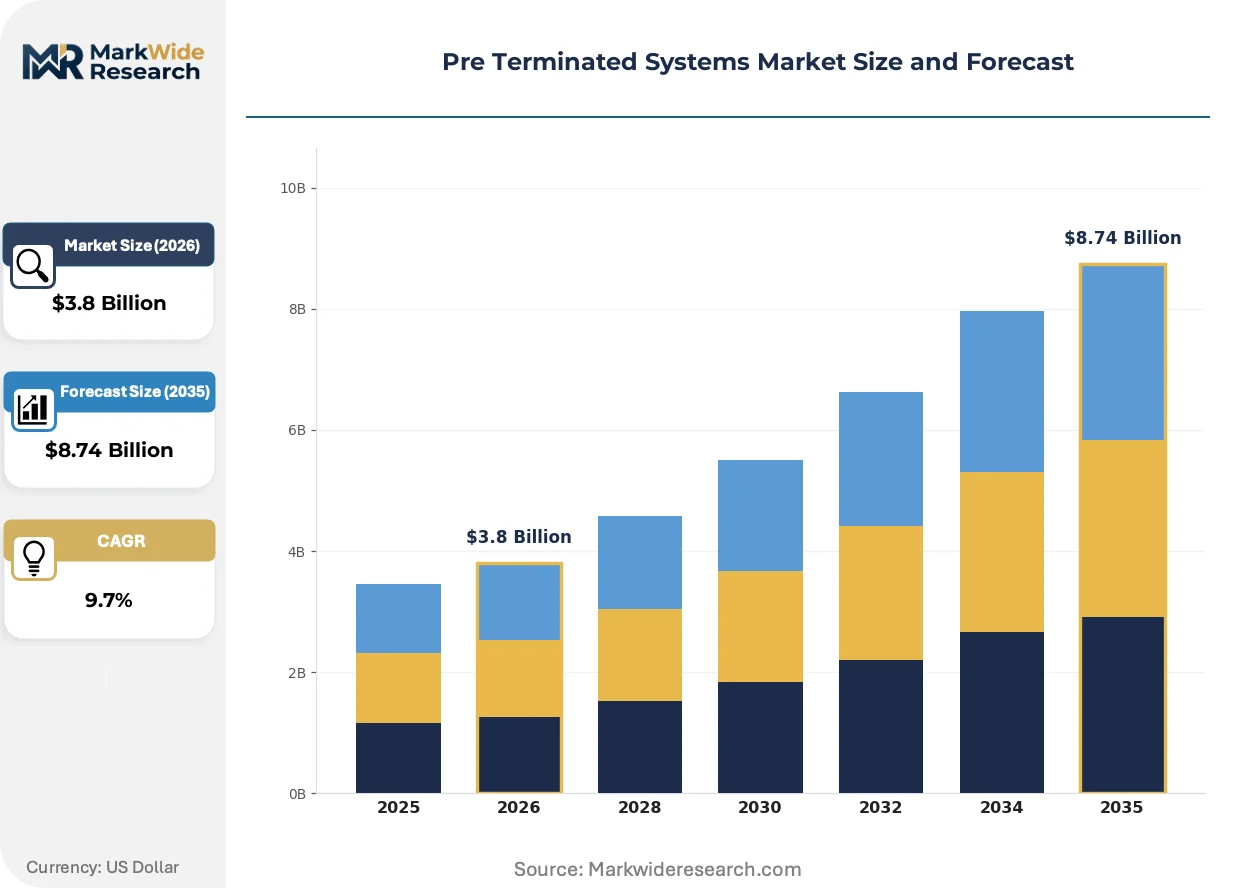
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Cables, Copper Cables, Connectors, Patch Panels Industry Vertical: Telecommunications, Data Centers, Networking, Broadcasting Installation Type: Indoor, Outdoor, Enterprise, Residential Service Type: Installation, Maintenance, Consulting, Support |
| Companies Covered | Siemens AG, Schneider Electric, AFL, Corning Incorporated, CommScope Holding Company, Inc., Amphenol Corporation, TE Connectivity Ltd., Prysmian Group, Leviton Network Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre Terminated Systems Market Strategic Shifts & Innovations
The evolution of pre-terminated systems is defined by a push toward deeper integration with both silicon and management platforms. This trend transforms cabling from a passive component into an active, intelligent part of the data center ecosystem, driven by demands for greater efficiency and performance.
Co-packaged optics (CPO) technology brings the optical interface directly onto the same package as the network switch ASIC. Hyperscale data center operators are the primary drivers for CPO adoption to reduce power consumption and latency. This technology is integrating the optical function with the core processing silicon, requiring new generations of ultra-high-density pre-terminated fiber assemblies to link CPO-enabled equipment.
European regulations, particularly the Corporate Sustainability Reporting Directive (CSRD), are influencing product design and material selection. The directive compels manufacturers to provide detailed lifecycle assessments and carbon footprint data for their products. Consequently, data center operators in the European Union increasingly favor suppliers that offer pre-terminated systems with transparent Environmental Product Declarations to meet their own compliance mandates.
A clear behavioral shift sees large-scale buyers moving from standard product procurement to collaborative co-design partnerships with vendors. This model supplants transactional orders with a process to develop bespoke assemblies tailored to specific rack architectures and thermal management strategies. This co-development approach is most visible within the hyperscale cloud sector in the United States, where custom solutions deliver critical performance and efficiency gains at scale.
Pre Terminated Systems Market Segmentation
Segmentation analysis for pre-terminated systems reveals how diverse technical requirements and operational demands shape product development and market penetration. This detailed breakdown highlights specific solutions tailored for various network infrastructures, customer environments, and service needs.
Product Type:
The product type segmentation highlights the balance between standardized components and specialized configurations required for high-performance networks.
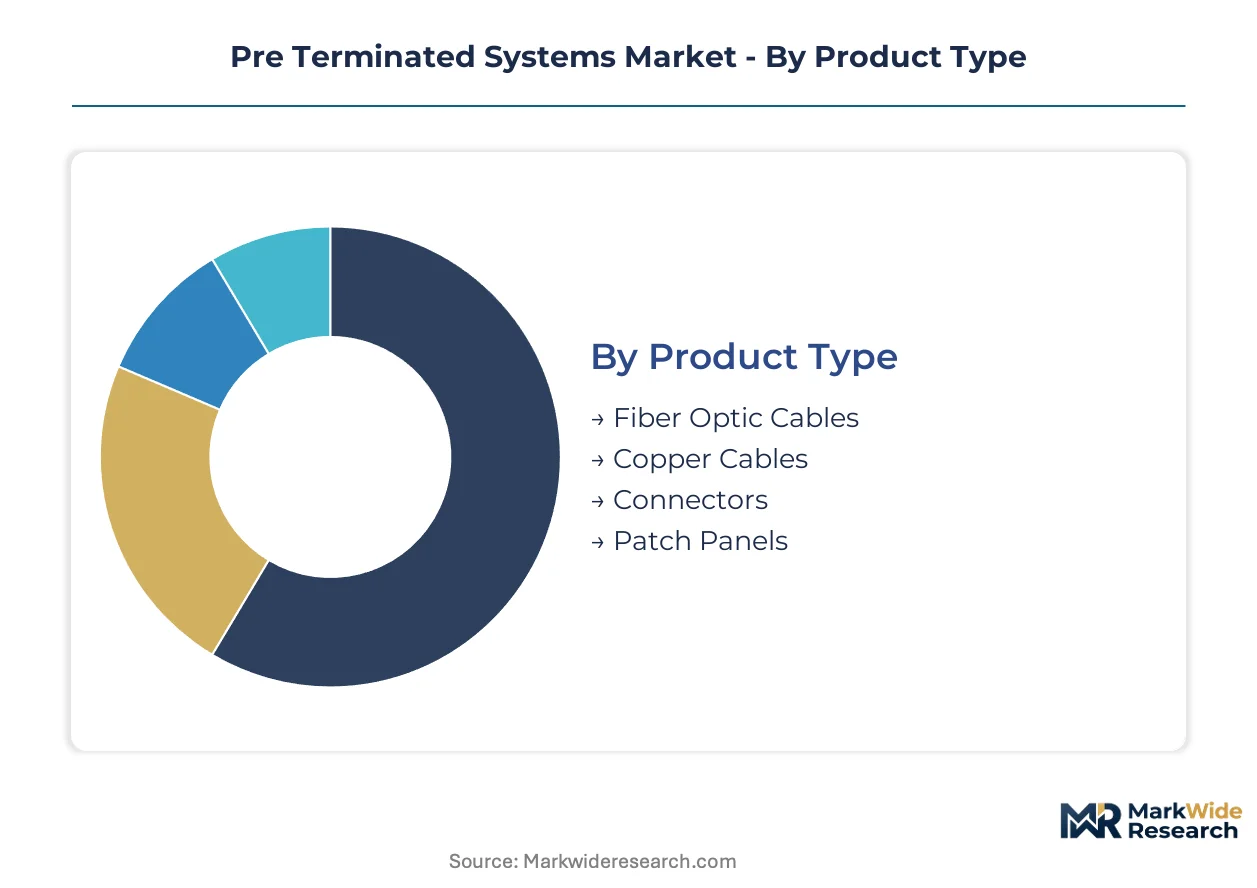
- Fiber Optic Cables:These systems consist of pre-terminated optical fibers, often multi-fiber push-on (MPO) or LC/SC connectors, factory-tested for insertion loss and return loss. Hyperscale data centers drive demand for these cables due to their superior bandwidth capacity and low-loss performance for 400G and 800G Ethernet standards.
- Connectors:Pre-terminated connectors, such as MPO, LC, and SC types, are factory-attached to cable assemblies, ensuring precise alignment and optimal optical performance. The transition to higher density network architectures in data centers necessitates reliable, pre-tested MPO connectors to meet stringent TIA-942 performance standards.
- Copper Cables:These include pre-terminated twisted-pair or coaxial cables, typically with RJ45 or other standard copper connectors, used for shorter distances and specific enterprise applications.
- Patch Panels:Pre-populated patch panels with integrated fiber or copper ports simplify network deployment by providing a ready-to-use interface for connecting active equipment.
Most installed capacity flows through Fiber Optic Cables. Expansion is steepest in Connectors.
Industry Vertical:
Demand across industry verticals reflects specific application requirements for bandwidth, latency, and environmental resilience.
- Data Centers:This vertical shows the highest adoption rate for pre-terminated systems, driven by the need for rapid deployment and high-density connectivity in hyperscale and enterprise facilities. The shift to 400G and 800G Ethernet standards necessitates factory-tested fiber optic solutions to ensure signal integrity.
- Telecommunications:Pre-terminated solutions support the build-out of 5G infrastructure and backbone networks, providing reliable, high-speed connectivity for central offices and remote sites. Global carriers leverage these systems for accelerated network upgrades and consistent performance.
- Networking:Enterprise networking environments utilize pre-terminated systems for their ease of installation and reliability in corporate campuses and large office buildings.
- Broadcasting:The broadcasting industry employs pre-terminated fiber optic cables for high-definition video transmission, ensuring low latency and high bandwidth for live event coverage and studio operations.
Data Centers represent the primary driver of new deployments. Telecommunications is rapidly expanding its adoption of pre-terminated solutions.
Installation Type:
Installation type differentiation centers on environmental conditions and the scale of deployment, impacting product ruggedization and assembly complexity.
- Indoor:Indoor installations typically occur within controlled data center environments, enterprise buildings, or communication rooms, where environmental factors are stable. These systems prioritize high density and low-loss performance, ensuring optimal connectivity for critical network infrastructure.
- Outdoor:Outdoor pre-terminated systems feature ruggedized cables and connectors designed to withstand harsh environmental conditions, including temperature extremes, moisture, and UV radiation. Telecommunications companies deploy these solutions for fiber-to-the-home (FTTH) and cellular backhaul projects, requiring durable and reliable field performance.
- Enterprise:Enterprise installations focus on structured cabling within office buildings and corporate campuses, emphasizing ease of installation and modularity for future network expansion.
- Residential:Residential applications involve deploying pre-terminated fiber optic cables to homes and multi-dwelling units, providing high-speed internet access with simplified installation processes.
Indoor installations command the largest segment by volume. Outdoor applications are witnessing the most significant uptake.
Service Type:
The service type segment illustrates how vendors extend their value proposition beyond hardware, offering critical support for system lifecycle management.
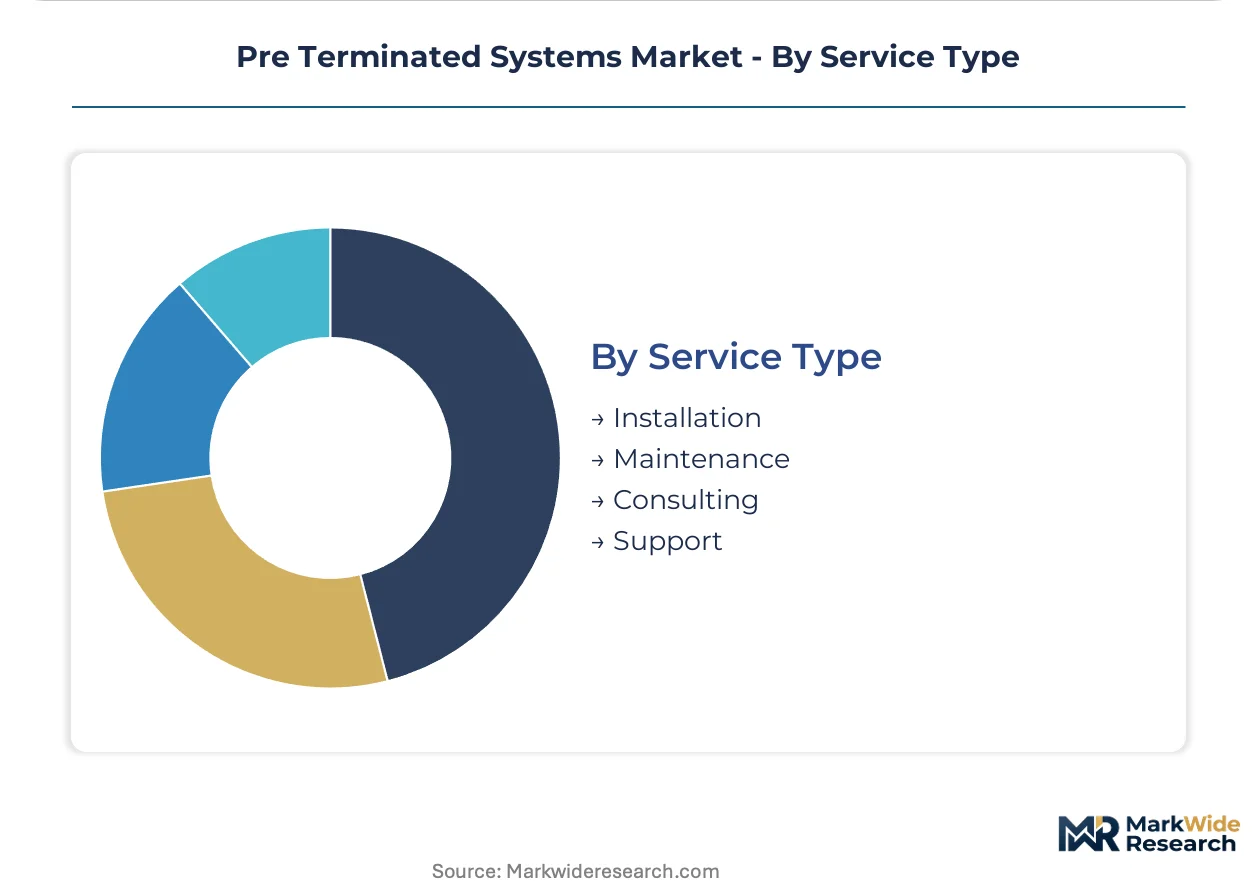
- Installation:Installation services encompass the physical deployment and connection of pre-terminated cable assemblies and components within a facility. Data center operators value these services for accelerating project timelines and ensuring proper system integration, particularly for complex hyperscale deployments.
- Maintenance:Maintenance services involve routine inspections, cleaning, and troubleshooting of pre-terminated systems to ensure continuous optimal performance and network uptime. Providers offer proactive and reactive maintenance to address potential issues before they impact critical data center operations.
- Consulting:Consulting services provide expert guidance on network design, system selection, and compliance with standards such as TIA-942 for data center infrastructure.
- Support:Support services offer technical assistance and problem resolution for pre-terminated systems, ensuring operational continuity for network administrators.
Installation services account for the largest share of service revenue. Maintenance services are gaining market share most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States significantly leads in pre-terminated systems adoption, while India demonstrates rapid expansion in its digital infrastructure development. These regional dynamics reflect varying stages of data center maturity and regulatory environments. Demand for pre-terminated systems is concentrating in major data center hubs globally.
United States
Hyperscale data center construction drives substantial demand for pre-terminated systems in the United States. Compliance with TIA-942 standards ensures performance verification for critical infrastructure components. Major data center clusters in Virginia, Texas, and California consistently deploy high-density, factory-tested cabling solutions.
Germany
German enterprises and cloud providers require pre-terminated systems for their secure and reliable data center operations. European regulations like RoHS and CE marking govern product material composition and safety, influencing manufacturing processes. Frankfurt remains a primary hub, with significant investment in new data center capacity.
Singapore
Singapore's strategic location and robust digital economy fuel demand for rapid deployment of pre-terminated fiber optics. The country's infocomm media development authority promotes high-speed connectivity and data center growth. Numerous colocation and cloud facilities in Singapore leverage these systems for scalable network expansion.
India
India's burgeoning digital economy and government initiatives like "Digital India" accelerate data center build-outs, increasing pre-terminated system adoption. The BIS (Bureau of Indian Standards) ensures quality and safety for telecom infrastructure components. Major cities like Mumbai, Chennai, and Hyderabad are witnessing extensive new data center development.
Japan
Japanese data centers prioritize high reliability and efficiency, driving the use of advanced pre-terminated solutions for 400G and 800G Ethernet. METI (Ministry of Economy, Trade and Industry) supports digital transformation and data center investments. Tokyo and Osaka remain key regions for data center expansion and network upgrades.
Pre Terminated Systems Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with a distinct tiered structure evident in the pre-terminated systems market. The market exhibits a moderate level of consolidation among top-tier providers, while numerous smaller players serve niche applications. Strategic archetypes include integrated solutions providers, component specialists, and regional assembly houses. Dominant competitive moves involve portfolio diversification and strategic partnerships to address complex data center requirements.
Specialists in high-bandwidth applications, Corning Incorporated and CommScope Holding Company, Inc. exemplify providers offering comprehensive solutions for complex network environments. Schneider Electric occupies a position as an integrated provider, embedding pre-terminated systems within broader energy management and automation platforms. These companies anchor their market presence through extensive product portfolios and established customer relationships in critical infrastructure sectors.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric |
| AFL |
| Corning Incorporated |
| CommScope Holding Company, Inc. |
| Amphenol Corporation |
| TE Connectivity Ltd. |
| Prysmian Group |
| Leviton Network Solutions |
| Others |
Cost & Logistics Intelligence
Silica commodity prices, a foundational input for fiber optic cables, influence cost structures across the pre-terminated systems market. This directly cascades into differentiated pricing tiers for both standard and high-performance solutions.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard pre-terminated components. The market typically employs a project-based pricing model for large-scale hyperscale deployments, with transactional pricing for smaller enterprise needs. Price differentiation stems from customization levels for bespoke solutions and adherence to performance certifications like TIA-942. Smaller enterprises exhibit higher price sensitivity compared to hyperscale operators, where performance and reliability are paramount.
Supply Chain Analysis
Direct sales channels handle hyperscale buyer demand, while distributors serve enterprise and smaller project needs. Supply concentration for critical components like MPO connectors is high in countries such as China and the United States. The supply chain draws from specialized optical fiber manufacturing in Japan and Germany. Single-source vulnerability for high-performance multi-fiber connectors presents a structural risk for the market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pre-terminated systems market functions as a stable compounder, driven by the relentless pace of hyperscale data center construction. This sustained demand ensures consistent expansion for high-density network infrastructure.
For Market Incumbents: To counter margin erosion from commoditization of standard pre-terminated products, incumbents should deepen portfolio diversification into integrated, software-enabled solutions. Strategic partnerships with hyperscale operators for co-design initiatives will secure large-volume, custom orders. Investing in R&D for co-packaged optics and advanced factory automation will maintain a technological edge. Certification investments for new Ethernet standards reinforce market leadership.
For New Entrants and Emerging Players: Capture white-space opportunities in edge computing infrastructure and emerging data center markets like India. These smaller, distributed sites represent the most penetrable segments due to their need for rapid deployment solutions. A focused go-to-market angle emphasizing standardized, cost-effective pre-terminated bundles can establish early market share. Reliability and ease of installation are key differentiators for these buyers.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated component specialists offering high-performance fiber and connector solutions. The long-term viability of this market is anchored in the fundamental need for scalable, reliable digital infrastructure. Niche providers with expertise in smart cabling integration or ultra-high-density fiber represent attractive acquisition targets. Increased M&A activity in co-packaged optics integration serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: High-density 800G fiber assemblies | Enables next-generation data center connectivity for hyperscale operators. |
| Strategic Partnership: Co-design initiatives with hyperscale cloud providers | Customizes solutions for specific rack architectures, optimizing performance and efficiency. |
| Geographic Expansion: Investment in manufacturing or distribution in India | Addresses growing demand from emerging data center markets and digital infrastructure build-outs. |
| Technology Licensing: Integration of smart cabling sensors | Transforms passive cabling into active components, feeding data to DCIM platforms. |
| Green Manufacturing Transition: Adoption of sustainable materials for cable jackets | Meets European CSRD requirements and customer demand for transparent environmental data. |
Research Approach
Coverage spans North America, Europe, and Asia Pacific, with primary inputs from each region. This analysis incorporates insights from direct interviews with data center architects, network engineers, procurement managers, and system integrators. Secondary validation draws from industry association reports, regulatory filings, and technical journals. A bottom-up and top-down triangulation approach ensures data consistency.
Rate-of-change decomposition forms the core of the forecasting framework, projecting market evolution across the analysis window. Segmentation dimensions include product type, industry vertical, installation type, service type, and regional adoption rates. Compound Annual Growth Rates were derived by extrapolating historical trends and integrating future growth drivers. Hyperscale data center build-out schedules and Ethernet standards roadmaps served as critical forecast inputs.
Supply chain disruptions, rapid technological shifts in optical components, and changes in data center investment cycles are the dominant revision risks. Forecasts reflect underlying assumptions regarding market dynamics and technological progression. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
AI Computing Hardware Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
System on Module (Som) Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
Hi-Fi System Market