
 Cold Start System Market | 2026-2036
Cold Start System Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Start System Market Analytics
Asset-light leasing models for fleet cold start infrastructure is rewriting competitive dynamics in the aftermarket. Bosch leverages its captive manufacturing of heating elements to sustain margin control across OEM channels. Denso Corporation anchors its position through specialized control module production for hybrid powertrains. BorgWarner Inc. differentiates via integrated thermal management systems that span electric and combustion architectures.
A cold start system comprises electrically or fuel-actuated heating elements, thermostatic regulators, and engine control modules designed to achieve minimum cranking temperatures in sub-zero conditions, typically rated for operation below minus twenty degrees Celsius. The assembly ensures reliable ignition, reduced engine wear, and compliant emissions profiles during initial combustion cycles. Electric and hybrid form categories now command the fastest expansion as electrified powertrains require supplemental thermal conditioning for battery and cabin systems. Control modules represent the highest-margin component segment due to embedded software complexity and calibration IP. Aftermarket installations face structural pressure from OEM-integrated designs that bundle cold start capability within broader thermal management platforms.
EPA tailpipe regulations and NHTSA cold weather reliability standards shape product specifications and certification pathways for domestic manufacturers. California Air Resources Board supplemental rules further constrain allowable pre-heat emissions and energy consumption profiles. Stakeholders must monitor how battery-electric vehicle thermal strategies absorb or displace traditional cold start hardware demand as powertrain architectures evolve.
Market Dynamics
Fleet electrification timelines are compressing the addressable market for traditional combustion-engine cold start hardware while simultaneously expanding demand for battery thermal conditioning systems in hybrid and electric architectures. This dual-phase transition is forcing suppliers to reconfigure product portfolios faster than OEM integration cycles typically permit.
Growth Catalysts
- EPA Phase 3 GHG Standards:Heavy-duty truck emissions rules mandate reliable cold-start performance across all operating temperatures, compelling fleet operators to upgrade legacy starting systems in existing vehicles rather than defer maintenance.
- Minnesota and Montana Fleet Concentrations:Interstate logistics corridors through the Upper Midwest and Northern Rockies experience sustained sub-zero operating windows, creating concentrated replacement demand for certified cold start hardware.
- Silicon Carbide Control Modules:Next-generation power electronics enable faster heating element response cycles, reducing energy draw from batteries and alternators during pre-heat sequences.
Market Restraints
- Nickel and Cobalt Price Volatility:Heating element alloys and battery thermal management components face input cost instability from concentrated mining jurisdictions, compressing margin visibility for component manufacturers.
- OEM Bundling Strategies:Integrated thermal management platforms from powertrain suppliers are absorbing standalone cold start system procurement, shrinking the independent aftermarket addressable base.
- Battery-Electric Powertrain Substitution:Zero-emission truck adoption eliminates conventional engine starting hardware entirely, though this displacement is partially offset by cabin and battery conditioning requirements.
Strategic Opportunities
- Alberta and Saskatchewan Oil Sands Logistics:Remote mining and extraction fleets in Western Canada operate in sustained extreme cold without grid access, creating demand for self-contained fuel-actuated heating systems with extended service intervals.
- NHTSA Cold Weather Reliability Rulemaking:Pending federal safety standards for commercial vehicle starting performance in adverse conditions would mandate hardware upgrades across federally regulated interstate fleets.
- Telematics-Enabled Predictive Pre-Heating:Integration of GPS route data with engine control modules allows automated cold start activation based on ambient temperature forecasts and departure schedules.
Industry Challenges
- Embedded Software Calibration Expertise:Control module development requires specialized thermal modeling engineers capable of optimizing heating algorithms across disparate engine architectures and fuel types.
- Multi-Agency Certification Timelines:Simultaneous EPA emissions validation, NHTSA safety approval, and CARB supplemental testing for California-operated fleets extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Start System Market |
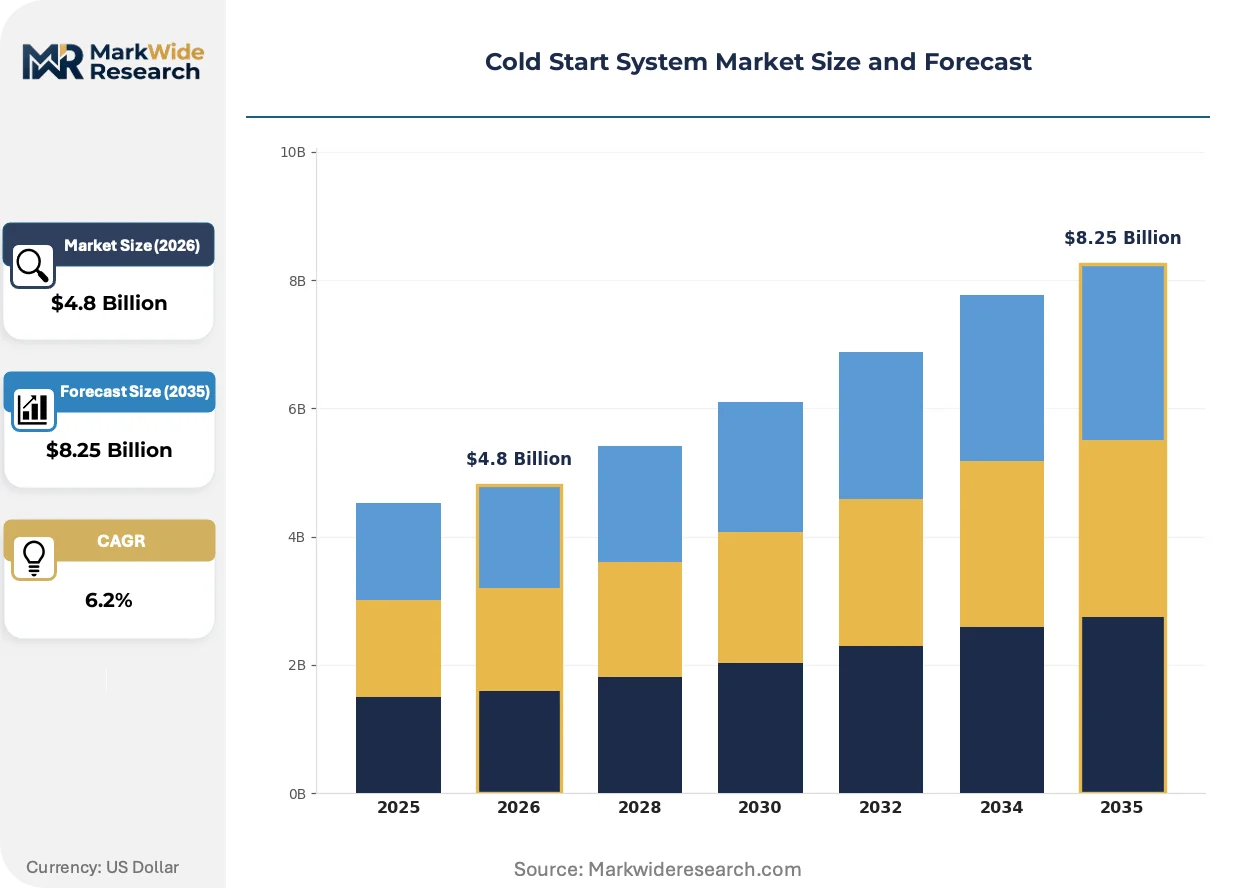
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Heating Element, Thermostat, Control Module, Fuel System Form: Electric, Gas, Hybrid, Diesel Vehicle Type: Passenger Cars, Commercial Trucks, Motorcycles, Light Vehicles Installation Type: OEM, Aftermarket, Retrofit, Integrated |
| Companies Covered | Bosch, Denso Corporation, Continental AG, Schaeffler AG, Robert Bosch GmbH, BorgWarner Inc., Delphi Automotive, Johnson Controls, Hitachi Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Start System Market Evolving Landscape
Electrification is bifurcating the cold start system market into legacy combustion-engine hardware and emerging thermal conditioning platforms for battery-dominant powertrains. Component suppliers are racing to develop architectures that serve both segments without duplicating engineering resources.
Carbon fiber-reinforced polymer heating element housings are replacing aluminum castings in next-generation fuel-actuated systems. Tier 1 suppliers to North American heavy-duty OEMs have adopted these composites for 2027 model year platforms. The material shift is rendering obsolete legacy foundry-dependent supply chains that cannot achieve comparable thermal conductivity-to-weight ratios at equivalent cost structures.
NHTSA cold weather reliability standards under development will mandate minimum cranking performance thresholds for commercial vehicles operating below minus 20 degrees Celsius. The proposed rules would require documented pre-heat system validation across standardized test cycles. Heavy-duty diesel applications in the Upper Midwest and Rocky Mountain states face the steepest compliance burden, with fleet operators already budgeting for retrofit installations ahead of anticipated enforcement dates.
Asset-light leasing of cold start infrastructure is displacing direct capital expenditure by regional fleet operators. Third-party thermal service providers now contract for guaranteed starting reliability across seasonal operating windows, assuming hardware lifecycle risk. This model has gained traction among mid-size trucking operators in North Dakota and Wyoming who lack in-house maintenance scale for specialized heating system upkeep.
Cold Start System Market Segmentation
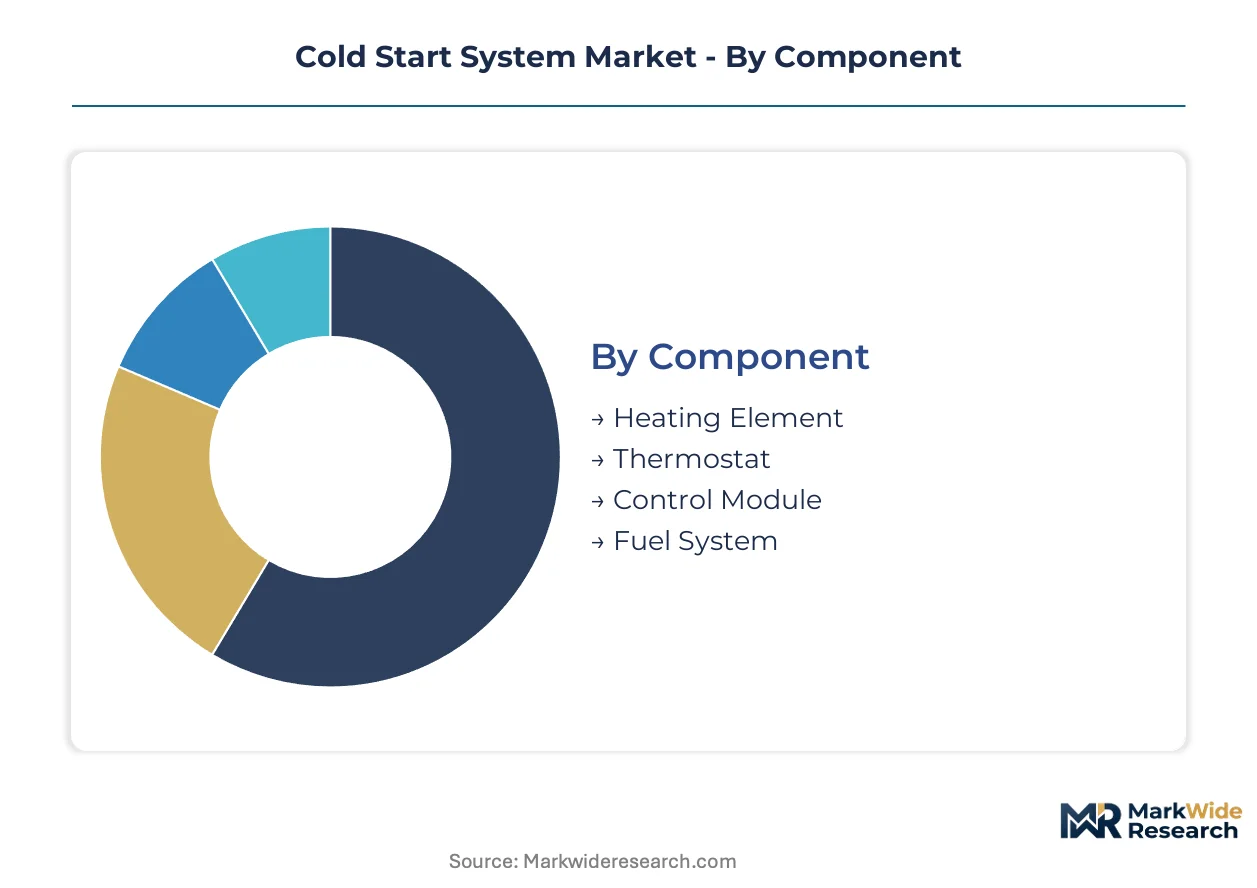
Cold start system procurement patterns diverge sharply across component tiers and installation channels, with aftermarket service intensity varying by vehicle duty cycle and regional climate severity. Fleet operators in sub-zero corridors demand differentiated technical specifications compared to temperate-zone passenger applications, fragmenting supplier go-to-market approaches.
Component:
After-sales service intensity concentrates in control modules and heating elements, where calibration drift and thermal degradation drive recurring maintenance visits across commercial fleets.
- Control Module:Embedded software governs heating element sequencing and temperature thresholds through engine control unit integration. Demand clusters in Upper Midwest commercial truck fleets where EPA Phase 3 cold-start compliance mandates precise thermal management algorithms. Silicon carbide power electronics are compressing response times while reducing energy draw during pre-heat cycles.
- Heating Element:Electric resistance coils or fuel-actuated burners deliver thermal energy to engine blocks, coolant circuits, or battery packs. Minnesota and Montana interstate logistics operators specify heavy-duty elements rated for sustained minus-thirty-degree operation, with replacement cycles accelerating under extreme duty conditions.
- Thermostat:Bimetallic or electronic sensors regulate heating element activation thresholds based on ambient and coolant temperature readings.
- Fuel System:Self-contained diesel or gasoline combustion chambers enable off-grid pre-heating for remote mining and extraction fleets lacking electrical infrastructure.
Control Module holds the largest share; momentum sits with Heating Element as fleet electrification expands battery thermal conditioning requirements.
Form:
Cost tier separation is pronounced, with hybrid architectures commanding premium positioning against legacy combustion-only alternatives.
- Electric:Grid-dependent resistance heating dominates passenger vehicle and light commercial applications with reliable shore power access. Urban delivery fleets in temperate zones favor these systems for lower capital outlay and simplified maintenance protocols.
- Hybrid:Dual-mode systems combine electric pre-conditioning with fuel-actuated backup for extreme cold events. Rocky Mountain heavy-duty operators specify these configurations to satisfy NHTSA reliability standards while managing energy costs across variable grid availability.
- Gas:Propane or natural gas combustion units serve agricultural and construction equipment in rural locations without three-phase electrical service.
- Diesel:Fuel-actuated systems leverage onboard fuel supplies for autonomous operation in oil sands logistics and remote pipeline maintenance corridors.
Electric systems retain volume leadership; Hybrid configurations are climbing the fastest as electrified powertrain penetration accelerates.
Vehicle Type:
Application severity drives specification divergence, with commercial duty cycles demanding extended service intervals versus passenger car replacement patterns.
- Commercial Trucks:Class 8 long-haul and regional delivery vehicles require redundant starting reliability under federal safety regulations. North Dakota and Wyoming fleet operators now contract asset-light thermal service agreements rather than maintaining in-house heating system expertise.
- Passenger Cars:Light-duty applications prioritize compact packaging and rapid cabin warming for consumer comfort expectations.
- Light Vehicles:Pickup trucks and vans serving trades and last-mile delivery occupy a specification middle ground between passenger and heavy-duty requirements.
- Motorcycles:Minimalist thermal solutions address cold-start emissions compliance in small-displacement engines without significant battery capacity.
Commercial Trucks command the dominant revenue position; Light Vehicles are gaining share fastest through electrified delivery van proliferation.
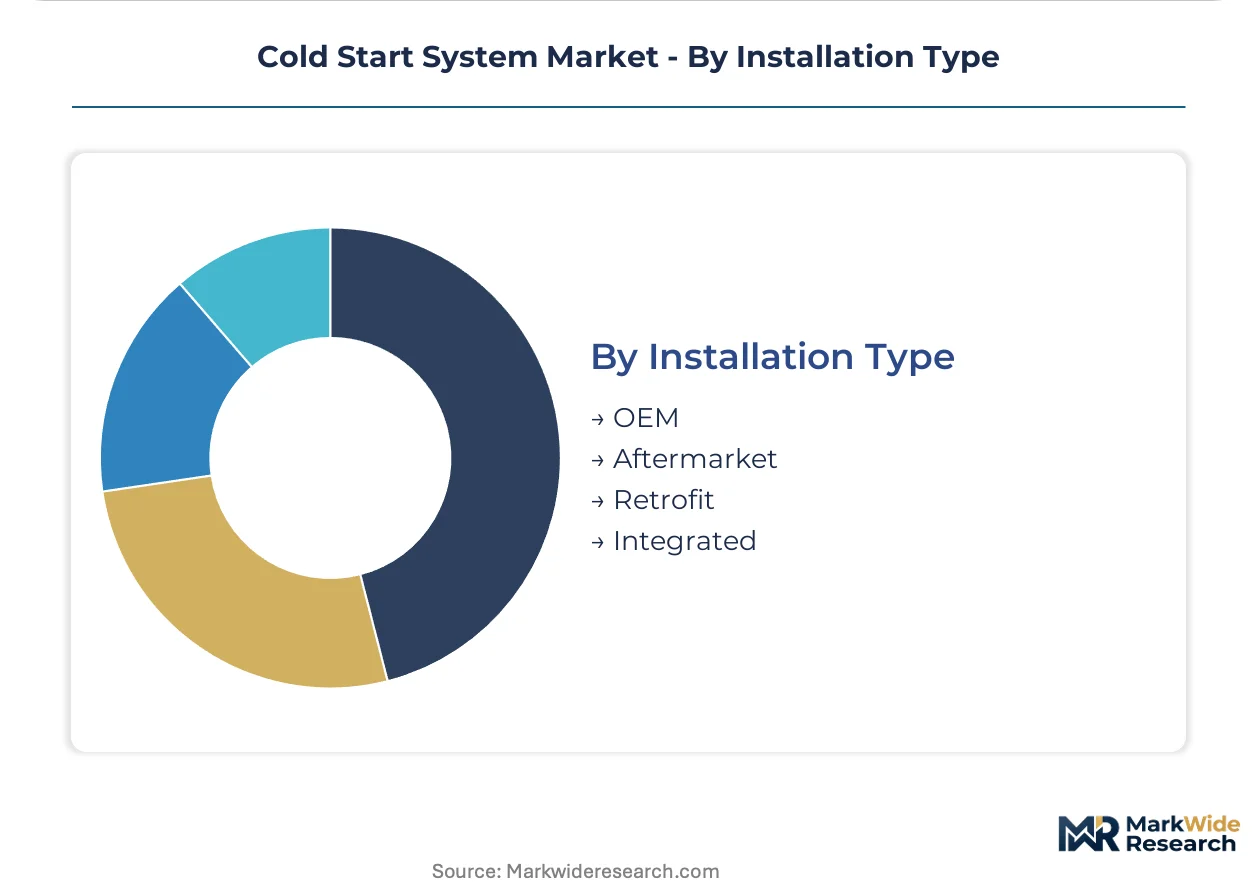
Installation Type:
Customer type fragmentation separates OEM-integrated procurement from independent aftermarket decision-makers with diverging technical capabilities.
- OEM:Factory-installed systems are bundling into comprehensive thermal management platforms, absorbing standalone cold start hardware procurement. BorgWarner and Denso supply these integrated architectures to North American heavy-duty manufacturers under multi-year supply agreements.
- Aftermarket:Independent service channels face structural pressure as OEM designs become less field-serviceable. Mid-size fleet operators in Alberta and Saskatchewan oil sands corridors sustain demand for specialized retrofit expertise unavailable through dealer networks.
- Retrofit:Legacy vehicle upgrades address pending NHTSA cold weather reliability mandates ahead of anticipated enforcement dates.
- Integrated:Powertrain suppliers are absorbing cold start functionality within broader battery and cabin thermal conditioning systems for electric architectures.
OEM integration retains the largest share; Aftermarket channels face steepest expansion constraints from platform bundling strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Upper Midwest fleet corridors where sub-zero duty cycles command premium specifications, while temperate-zone operators extract standard-tier economics from simpler thermal architectures.
United States
Minnesota and Montana interstate logistics operators drive concentrated demand for heavy-duty heating elements rated to minus-thirty degrees. NHTSA cold weather reliability rulemaking mandates documented pre-heat system validation across standardized test cycles. North Dakota mid-size fleets now contract asset-light thermal service agreements rather than maintaining in-house heating system expertise.
Canada
Alberta and Saskatchewan oil sands logistics corridors sustain demand for self-contained fuel-actuated heating systems without grid access. Environment Canada winter emissions protocols constrain allowable pre-heat energy consumption profiles for remote extraction fleets. Western Canada mining operators specify extended-service-interval diesel combustion units for autonomous extreme-cold operation.
Germany
Baden-Württemberg automotive suppliers integrate cold start functionality within broader thermal management platforms for hybrid powertrains. EU F-Gas Regulation and REACH compliance requirements shape heating element material specifications for export-bound systems. Stuttgart-area engineering clusters specialize in silicon carbide control module development for reduced energy draw during pre-heat sequences.
Japan
Tokyo-Osaka industrial corridors anchor control module production for electrified powertrain thermal conditioning. METI energy efficiency standards drive heating algorithm optimization across disparate battery architectures. Nagoya-area suppliers develop architectures serving both legacy combustion and emerging battery-dominant segments without duplicating engineering resources.
South Korea
Seoul Capital Area battery manufacturers expand thermal conditioning requirements for electrified commercial vehicle platforms. KBA-aligned certification protocols for European export markets extend product validation timelines for domestic suppliers. Busan-Ulsan heavy-duty OEM supply chains absorb cold start capability within integrated powertrain thermal management systems.
Cold Start System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying heating elements and control modules to bundled architectures. Market structure consolidates around Tier 1 powertrain suppliers with captive thermal management portfolios, while independent aftermarket channels face structural compression from OEM bundling strategies. Two strategic archetypes dominate: diversified industrial conglomerates with captive component manufacturing, and specialized thermal engineering firms with embedded software calibration expertise. Competitive moves concentrate on backward integration into heating element alloys and strategic partnerships with battery-electric powertrain developers.
Within the diversified industrial tier, Bosch and Denso Corporation exemplify platform integrators with captive manufacturing spanning control modules through heating elements. BorgWarner Inc. occupies a position representing the thermal-system-specialist archetype, with integrated architectures spanning electric and combustion powertrain categories. These three anchors illustrate how supplier positioning diverges between conglomerate-scale bundling strategies and focused thermal engineering depth.
| Leading Market Players |
|---|
| Bosch |
| Denso Corporation |
| Continental AG |
| Schaeffler AG |
| Robert Bosch GmbH |
| BorgWarner Inc. |
| Delphi Automotive |
| Johnson Controls |
| Hitachi Ltd |
| Others |
Value Network & Pricing Analysis
Silicon carbide wafer production concentration in Japan and Germany anchors margin capture at the control module tier, where embedded software calibration commands premium positioning against commodity heating element suppliers. Pricing power fragments across the value stack as OEM bundling compresses standalone hardware premiums while specialized thermal engineering expertise sustains value in integrated architectures.
Pricing Analysis
Configured-to-order pricing for hybrid cold start systems commands spreads exceeding standard electric configurations due to dual-mode engineering complexity and NHTSA reliability certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated thermal platforms from aftermarket retrofit kits and basic resistance heating units. Cost compression in heating element alloys is intensifying because nickel and cobalt price volatility from concentrated mining jurisdictions erodes margin visibility for component manufacturers. Mid-size fleet operators in temperate zones exhibit highest price sensitivity, while Upper Midwest commercial operators absorbing asset-light thermal service contracts show lowest sensitivity due to guaranteed reliability requirements.
Supply Chain Analysis
Export control regimes limiting silicon carbide power electronics flows from Japan constrain control module availability for North American suppliers developing next-generation heating algorithms. Manufacturing concentration centers on Germany for precision thermal management components, Japan for advanced power electronics, and China for base heating element production. Supply chain risk hinges on single-source vulnerability for silicon carbide substrates essential to EPA Phase 3 compliance timelines. Distribution runs through captive OEM channels for integrated platforms and specialized aftermarket distributors for retrofit installations serving remote mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
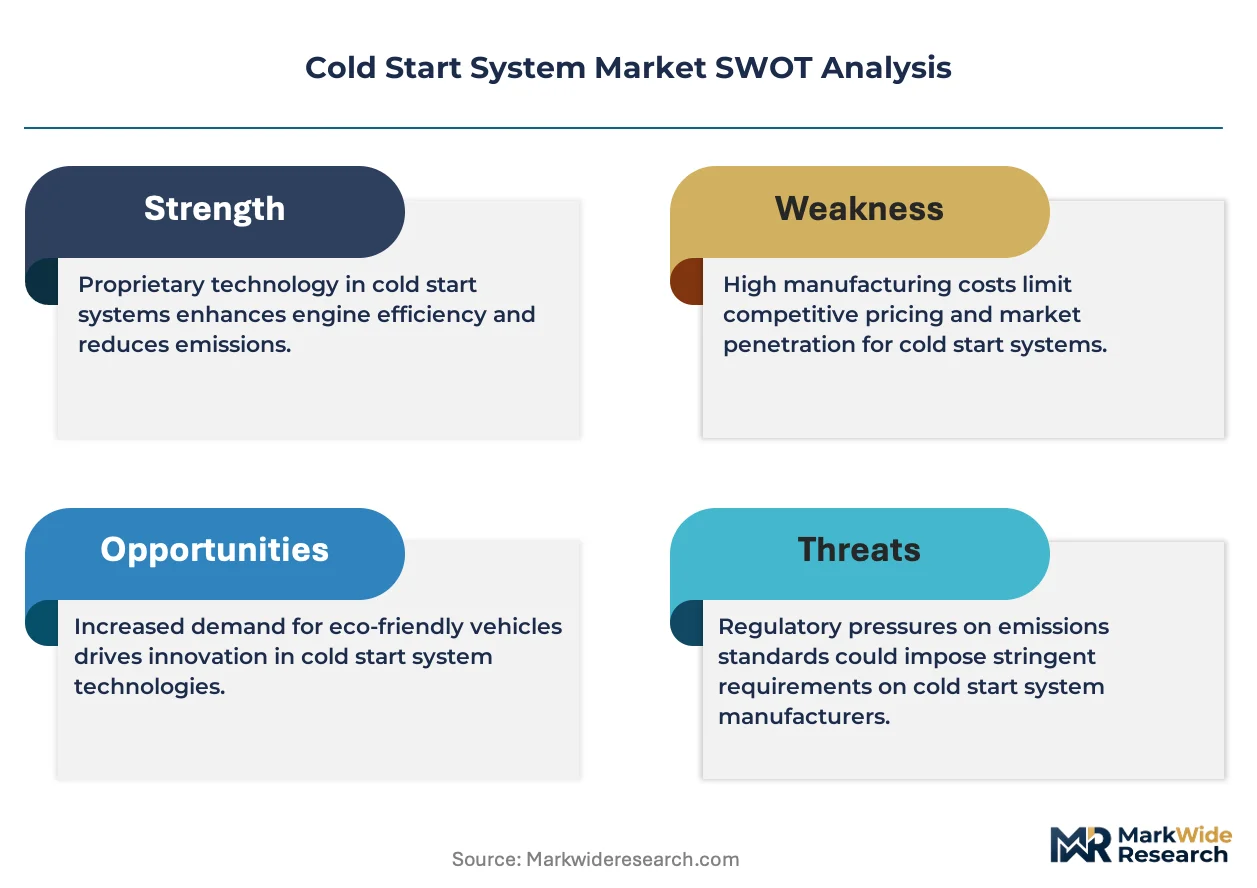
Battery-electric powertrain substitution threatens conventional engine starting hardware demand as zero-emission truck adoption accelerates, forcing incumbents to defend thermal conditioning relevance across electrified architectures.
For Market Incumbents: Build embedded software calibration moats around silicon carbide control module architectures to differentiate against commodity heating element suppliers. Secure backward integration into nickel alloy supply through long-term offtake agreements with Australian and Canadian mining operations to buffer cobalt price volatility. Deepen captive manufacturing of heating elements to sustain margin control as OEM bundling strategies absorb standalone procurement. For New Entrants and Emerging Players: Alberta and Saskatchewan oil sands logistics corridors represent the most penetrable entry point for self-contained fuel-actuated heating systems lacking established service infrastructure. NHTSA cold weather reliability rulemaking creates retrofit demand windows ahead of anticipated enforcement dates for legacy fleet upgrades. Pursue telematics-enabled predictive pre-heating partnerships with fleet management software providers to bypass direct OEM channel competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed thermal engineering specialists possessing embedded software calibration expertise but lacking scale for OEM platform integration. Long-term viability centers on dual-use architectures serving both legacy combustion and battery-dominant powertrains without duplicating engineering resources. Watch battery-electric truck adoption curves in Upper Midwest interstate corridors as inflection indicator for traditional cold start hardware displacement rates.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Control Module Development | Reduces energy draw during pre-heat cycles for EPA Phase 3 compliance. |
| Backward Integration into Nickel Alloys | Buffers margin compression from cobalt price volatility in heating elements. |
| Telematics-Enabled Predictive Pre-Heating | Integrates GPS route data with engine control modules for automated activation. |
| Asset-Light Thermal Service Contracts | Transfers hardware lifecycle risk from mid-size fleet operators to third-party providers. |
| Dual-Use Architecture Engineering | Serves combustion and battery-dominant powertrains without duplicating R&D resources. |
Research Methodology
Operator-level perspectives from fleet maintenance directors, Tier 1 supplier procurement teams, thermal management engineers, and aftermarket service technicians anchored the qualitative base. Primary interviews combined with secondary validation from EPA certification databases, NHTSA rulemaking dockets, vehicle production registries, and customs trade records. Bottom-up component demand modeling triangulated against top-down fleet penetration analysis.
Scenario-bracketing around battery-electric adoption curves and NHTSA enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include component tier, powertrain architecture, vehicle duty class, installation channel, and regional climate severity cluster. CAGRs derived from weighted average of historical replacement cycles and regulatory compliance windows. Industry-specific forecast inputs incorporated silicon carbide adoption rates and fleet electrification timelines from OEM platform disclosures.
Practitioners should monitor EPA Phase 3 implementation pacing and NHTSA cold weather reliability rulemaking finalization for early signals of retrofit demand acceleration. Forecasts reflect assumptions regarding electrification substitution rates and alloy price stability. Material shifts in battery-electric truck adoption curves or export control expansion on power electronics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
AI Computing Hardware Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
SONAR System Market