
 Vacuum Pulse System Market | 2026-2036
Vacuum Pulse System Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Pulse System Market Analytics
Aftermarket service revenue is rewriting profit expectations for incumbent suppliers. Atlas Copco leverages its compressor service infrastructure to cross-sell vacuum pulse maintenance contracts. Busch Vacuum Solutions anchors European demand through localized technical centers and rapid spare-part fulfillment. Ebara Corporation competes in Asia-Pacific with dedicated semiconductor-grade vacuum pulse engineering teams.
A vacuum pulse system generates controlled pressure differentials through cyclic evacuation and venting sequences, typically achieving ultimate pressures below 0.1 mbar with cycle frequencies tuned to process chemistry. These systems serve industrial applications requiring precise moisture removal, degassing, or contaminant extraction without thermal damage. Fixed systems dominate capital expenditure budgets in pharmaceutical freeze-drying, where validated pulse profiles protect API stability. Portable units are gaining traction in food processing facilities requiring flexible line reconfiguration. Custom solutions capture premium pricing in semiconductor wafer handling, where OEMs specify pulse timing to sub-second tolerances.
FDA validation requirements for sterile manufacturing equipment shape product development timelines and documentation burdens for suppliers targeting North American healthcare verticals. The EU MDR and REACH chemical compliance frameworks constrain material selection for vacuum chambers and sealing components in European markets. ISO 9001 and ISO 13485 certifications function as baseline qualifiers rather than differentiators in procurement decisions. Stakeholders must track evolving EPA emissions standards for vacuum pump lubricants and refrigerants, as these rules threaten to obsolete established liquid ring pump installations and redirect replacement demand toward dry scroll and diaphragm technologies.
Market Dynamics
Pharmaceutical sterilization workflows are absorbing vacuum pulse units at accelerating rates as batch integrity standards tighten across regulated manufacturing environments. The FDA 21 CFR Part 11 and EU MDR validation requirements are compressing procurement cycles toward pre-validated, auditable vacuum cycle architectures.
Growth Catalysts
- EU MDR compliance deadlines:Sterile device manufacturers in Germany and Ireland are retrofitting legacy autoclave lines with validated vacuum pulse modules to meet notified body audit requirements.
- Semiconductor wafer handling:Sub-second pulse timing specifications from OEMs in Taiwan and South Korea are expanding the addressable market for precision vacuum engineering.
- Freeze-drying API stability:Biologics producers are specifying fixed vacuum pulse systems to protect moisture-sensitive active pharmaceutical ingredients during lyophilization cycles.
Market Restraints
- Specialized alloy feedstock volatility:Vacuum chamber fabrication depends on nickel-based superalloys and medical-grade stainless steels subject to energy-intensive smelting cost swings.
- German precision manufacturing concentration:Critical OEM integration expertise clusters in Bavaria and Baden-Württemberg, creating geographic supply risk for validated system commissioning.
- EPA emissions standards for pump lubricants:Liquid ring vacuum pump installations face obsolescence pressure as refrigerant and lubricant rules tighten, stranding existing capital.
Strategic Opportunities
- Portable unit penetration in food processing:Flexible line reconfiguration requirements at North American protein packaging facilities are opening demand for mobile vacuum pulse skids.
- India pharmaceutical manufacturing expansion:CDSCO regulatory alignment with ICH Q7 guidelines is prompting domestic sterile API producers to import validated vacuum sterilization infrastructure.
- Dry scroll and diaphragm technology convergence:Oil-free vacuum architectures combined with Industry 4.0 predictive maintenance are creating premium positioning for replacement cycle capture.
Industry Challenges
- ISO 13485 certification timelines:Medical device sterilization equipment suppliers face 12-18 month documentation and audit cycles before commercial deployment.
- Legacy system integration complexity:Pharmaceutical facilities running 1990s-era freeze-dryers require custom pulse profile retrofitting, extending commissioning schedules and eroding margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Pulse System Market |
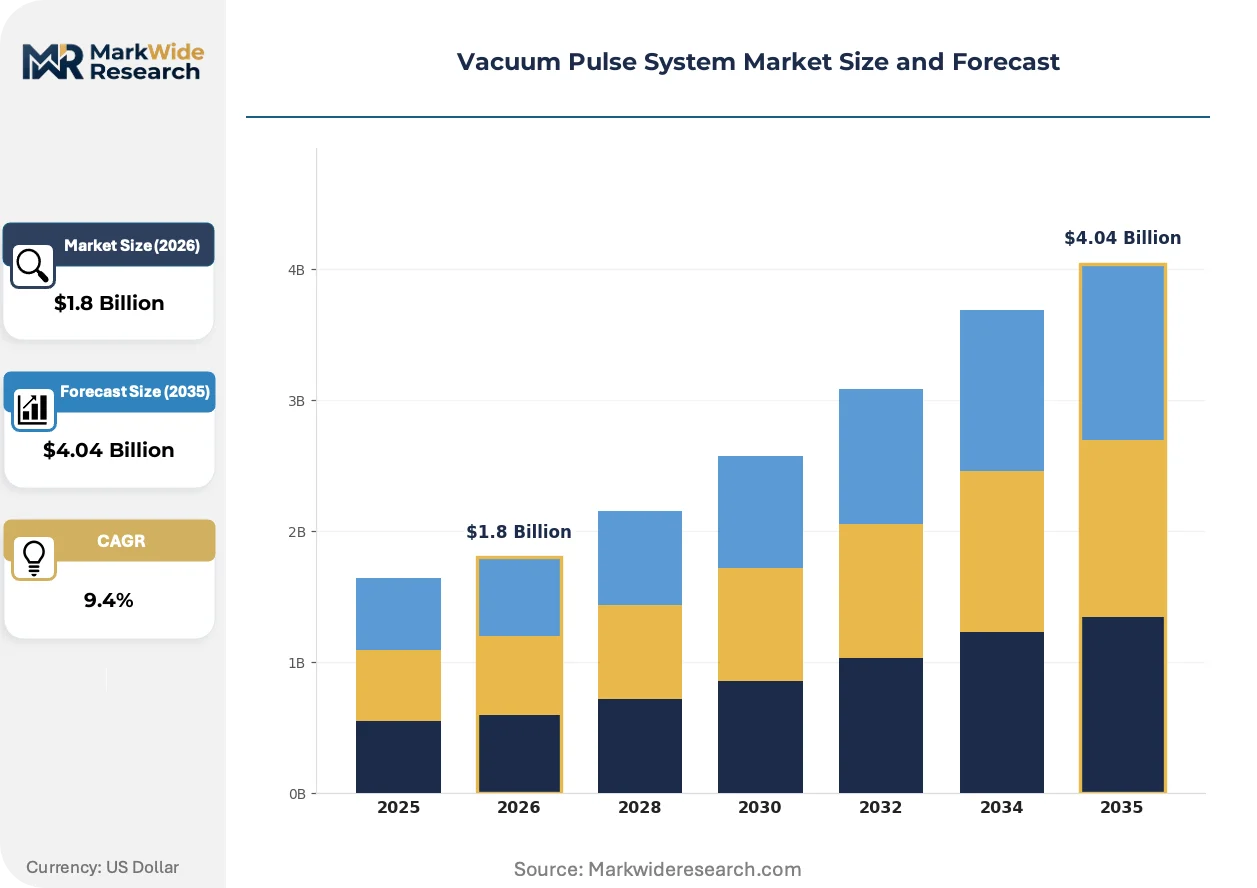
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Fixed Systems, Custom Solutions, High-Throughput Models Industry Vertical: Manufacturing, Healthcare, Food Processing, Pharmaceuticals Application: Material Handling, Vacuum Packaging, Vacuum Drying, Surface Coating Technology: Rotary Pumps, Diaphragm Pumps, Liquid Ring Pumps, Scroll Pumps |
| Companies Covered | Atlas Copco, Busch Vacuum Solutions, Ebara Corporation, ULVAC, Becker Pumps Corporation, Ingersoll Rand, Eunsung, Azo, Ace Cutting Equipment & Supply, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Pulse System Market Evolving Landscape
Dry vacuum technologies are rendering oil-sealed pump architectures uncompetitive in regulated environments. Three distinct vectors are reshaping competitive positioning: hardware electrification, compliance automation, and service model restructuring.
Variable frequency drive (VFD) controlled dry scroll pumps are rendering obsolete liquid ring vacuum systems in pharmaceutical freeze-drying suites. Biologics manufacturers in Switzerland and Massachusetts are specifying oil-free architectures to eliminate batch contamination risk from hydrocarbon sealant backstreaming. This transition is compressing aftermarket revenue pools for incumbent lubricant-dependent pump suppliers while expanding predictive maintenance attach rates.
REACH chemical compliance and the EU F-Gas Regulation are constraining elastomer and refrigerant selection for vacuum chamber seals and cooling circuits. European OEMs are accelerating fluoropolymer substitution programs and redesigning thermal management loops to eliminate high-GWP refrigerants. Semiconductor equipment suppliers in the Netherlands face the steepest reformulation timelines as wafer handling specifications intersect with chemical authorization sunsets.
Aftermarket service unbundling is fragmenting traditional capital-plus-maintenance procurement bundles. Pharmaceutical facilities in Singapore and North Carolina are negotiating discrete validation, spare part, and remote monitoring contracts rather than turnkey service agreements. This disaggregation favors suppliers with localized technical centers and rapid fulfillment infrastructure over centralized manufacturing footprints.
Vacuum Pulse System Market Segmentation
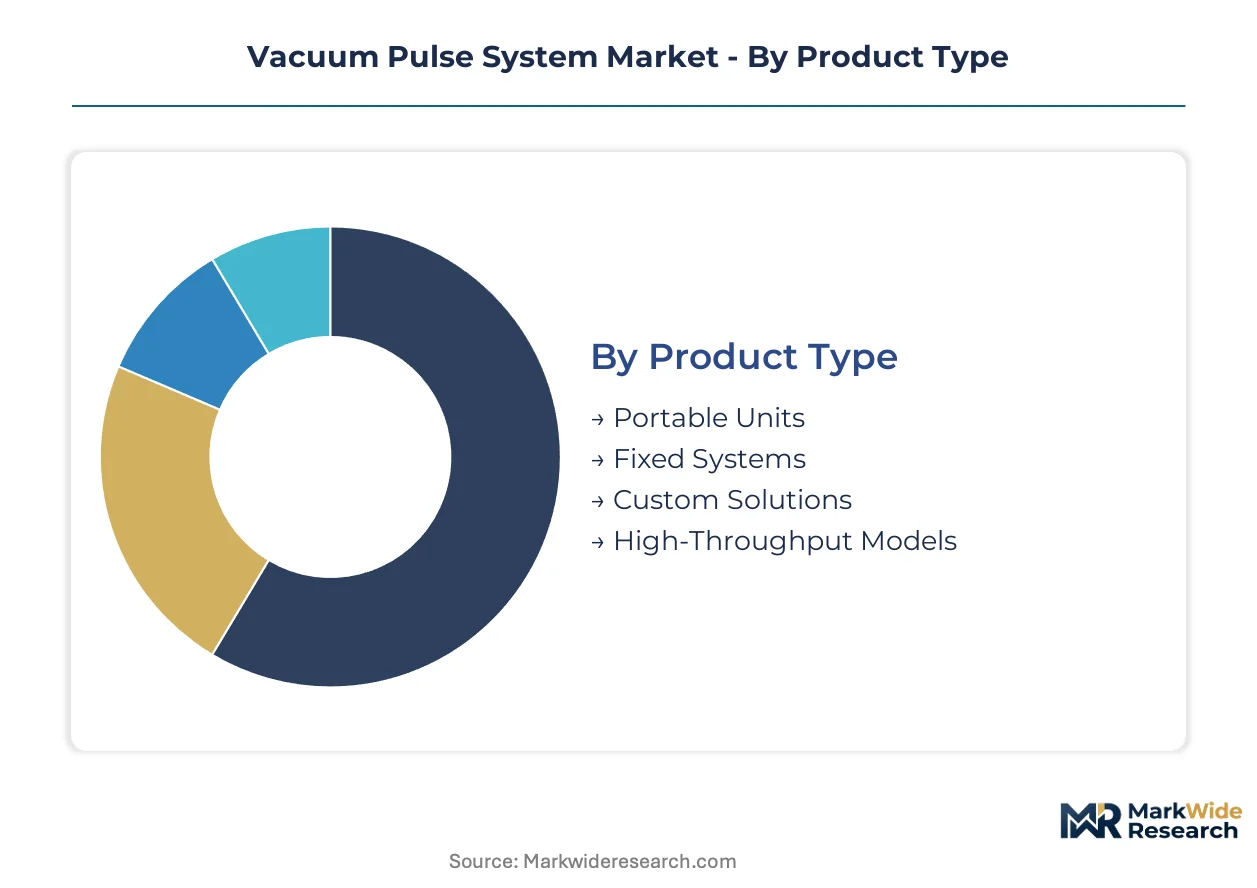
Segmentation in vacuum pulse systems reveals how capital allocation priorities diverge across regulated industries. Product architecture, end-use compliance burden, and pump technology selection each create distinct procurement pathways with margin implications for suppliers.
Product Type:
Capital intensity and mobility requirements split procurement behavior across facility types and production scales.
- Fixed Systems:Permanent installations anchor pharmaceutical freeze-drying suites with validated pulse profiles tuned to API stability requirements. Biologics producers in Switzerland and Massachusetts specify these for moisture-sensitive lyophilization cycles where batch integrity failures carry regulatory penalties.
- Portable Units:Mobile skids on casters serve protein packaging facilities requiring rapid line reconfiguration between product runs. North American food processors absorb these for seasonal production flexibility without permanent infrastructure commitment.
- Custom Solutions:Engineered-to-order architectures for semiconductor wafer handling with sub-second pulse timing tolerances.
- High-Throughput Models:Continuous-duty systems for large-scale manufacturing environments with minimal cycle interruption requirements.
Fixed systems command the established base. The steepest expansion runs through portable configurations.
Industry Vertical:
Regulatory stringency and contamination risk tolerance determine technology specification and service contract attachment rates.
- Pharmaceuticals:Sterile API manufacturing demands FDA 21 CFR Part 11 validated vacuum cycles with full audit trails. CDSCO alignment with ICH Q7 guidelines in India is prompting import demand for pre-validated sterilization infrastructure as domestic capacity expands.
- Healthcare:Medical device sterilization workflows require ISO 13485 certified equipment with 12-18 month documentation cycles before commercial deployment.
- Food Processing:Protein packaging and modified atmosphere operations prioritize rapid cycle completion over extreme vacuum depth.
- Manufacturing:General industrial degassing and moisture removal applications with lower validation burdens and faster procurement timelines.
Pharmaceuticals anchors premium pricing. Healthcare represents the fastest-growing trajectory as EU MDR compliance deadlines compress retrofit schedules.
Application:
Process chemistry and substrate sensitivity dictate pulse frequency, ultimate pressure targets, and chamber material selection.
- Vacuum Drying:Thermal-sensitive biologics processing requires precisely controlled pressure descent rates to prevent API denaturation. Lyophilization suites in Germany's precision manufacturing corridor specify pulse profiles protecting moisture-sensitive compounds.
- Vacuum Packaging:Food shelf-life extension drives demand for rapid evacuation cycles with oxygen residual targets below 1%.
- Material Handling:Semiconductor wafer transport systems requiring contaminant-free environments with minimal particulate generation.
- Surface Coating:Thin-film deposition processes demanding stable base pressures before process gas introduction.
Vacuum drying commands the established base. The steepest expansion runs through vacuum packaging applications.
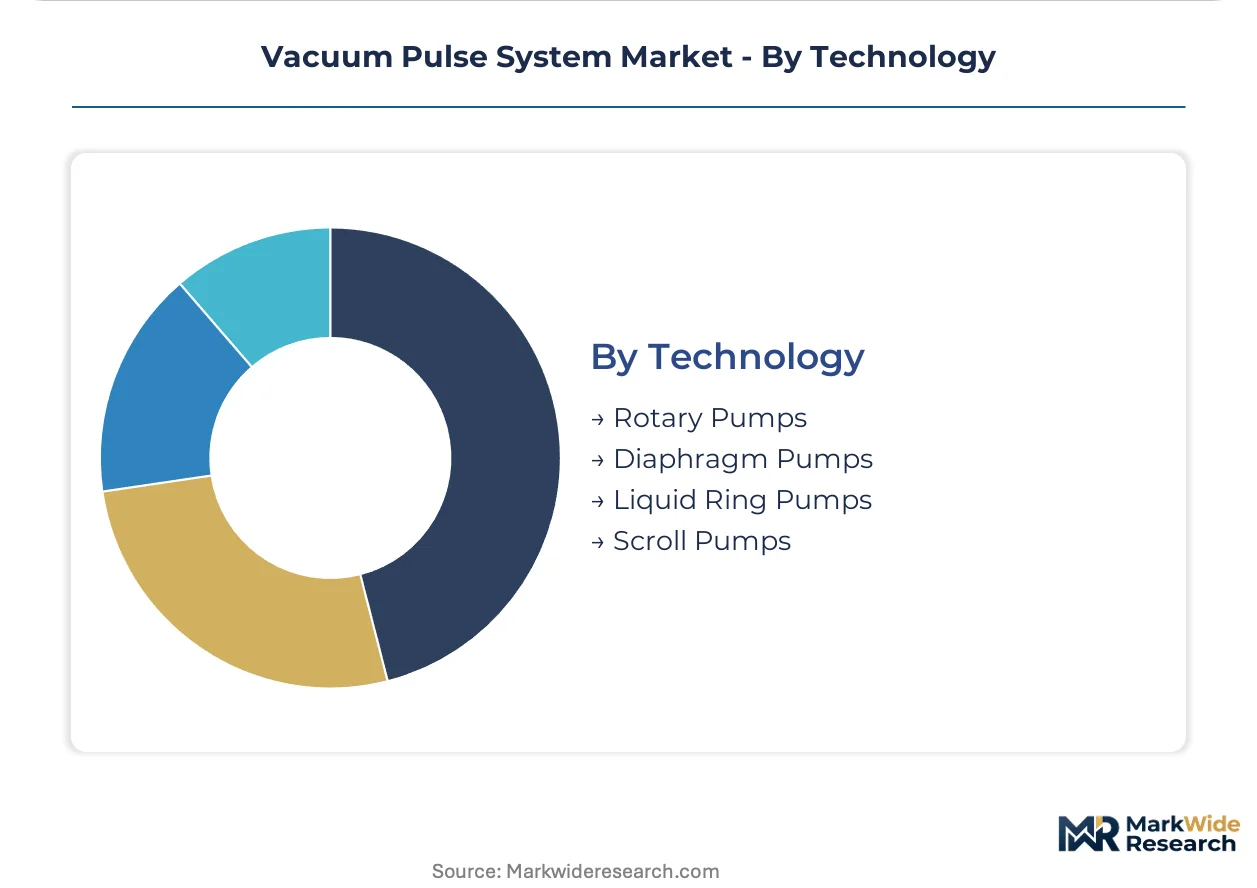
Technology:
Pump architecture selection is concentrating as EPA emissions standards and oil-free process requirements displace legacy technologies.
- Scroll Pumps:Dry, oil-free architectures with VFD control are displacing liquid ring systems in regulated pharmaceutical environments. Biologics manufacturers specify these to eliminate hydrocarbon backstreaming risks while enabling predictive maintenance attach rates.
- Diaphragm Pumps:Oil-free, chemically resistant designs gaining traction in semiconductor and laboratory applications requiring minimal maintenance intervention.
- Rotary Pumps:Traditional oil-sealed designs with established service infrastructure but facing obsolescence pressure from emissions regulations.
- Liquid Ring Pumps:Water-sealed systems threatened by EPA refrigerant and lubricant rules, redirecting replacement demand toward dry alternatives.
Scroll pumps command the established base. The steepest expansion runs through diaphragm configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys vacuum pulse systems for precision manufacturing integration, while the United States prioritizes pharmaceutical validation workflows and India concentrates on sterile API infrastructure imports.
United States
FDA 21 CFR Part 11 compliance deadlines drive pharmaceutical facilities in Massachusetts and North Carolina toward pre-validated vacuum pulse architectures. EPA emissions standards for pump lubricants are accelerating displacement of liquid ring systems in freeze-drying suites. Greater Boston biologics producers specify oil-free scroll pumps to eliminate hydrocarbon backstreaming risks during API lyophilization.
Germany
EU MDR notified body audit requirements are compressing retrofit schedules for legacy autoclave lines in Bavaria and Baden-Württemberg. REACH chemical compliance constrains elastomer selection for vacuum chamber seals across precision manufacturing corridors. Stuttgart-area OEMs integrate pulse-controlled vacuum into automated production lines with sub-second timing tolerances.
India
CDSCO regulatory alignment with ICH Q7 guidelines prompts domestic sterile API producers to import validated vacuum sterilization infrastructure. Pharmaceutical manufacturing expansion in Maharashtra and Gujarat concentrates demand for fixed vacuum pulse systems with full audit trail documentation. Mumbai and Ahmedabad facilities prioritize pre-validated equipment to accelerate commercial deployment timelines.
Switzerland
Swissmedic oversight of biologics manufacturing elevates specification standards for moisture-sensitive API stability during lyophilization cycles. Basel-area pharmaceutical clusters specify validated pulse profiles with pressure descent rates tuned to protein denaturation thresholds. The country's precision engineering heritage supports integration expertise for complex freeze-drying suite retrofits.
South Korea
MFDS pharmaceutical manufacturing standards intersect with semiconductor OEM demand for contaminant-free wafer handling systems. Sub-second pulse timing specifications from equipment manufacturers in Suwon and Pyeongtaek expand the addressable market for precision vacuum engineering. The concentration of memory and logic fabrication creates dual demand streams for both pharmaceutical and electronics-grade systems.
Vacuum Pulse System Market Competitive Landscape
Capability concentration sits with specialized vacuum engineering firms; scale advantage sits with diversified industrial equipment conglomerates. The market structures around three tiers: precision specialists serving semiconductor OEMs, pharmaceutical-focused validators with ISO 13485 certification infrastructure, and diversified compressors and pump manufacturers cross-selling maintenance contracts. Consolidation pressure runs through aftermarket service unbundling and geographic expansion into India pharmaceutical manufacturing corridors.
Among diversified industrial equipment groups, Atlas Copco and Ingersoll Rand occupy positions anchored by compressor service infrastructure that supports cross-selling of vacuum pulse maintenance contracts. Busch Vacuum Solutions exemplifies the European specialist archetype with localized technical center presence. Ebara Corporation represents Asia-Pacific precision engineering capability with dedicated semiconductor-grade vacuum teams. These three named entities illustrate how geographic origin and legacy infrastructure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Atlas Copco |
| Busch Vacuum Solutions |
| Ebara Corporation |
| ULVAC |
| Becker Pumps Corporation |
| Ingersoll Rand |
| Eunsung |
| Azo |
| Ace Cutting Equipment & Supply |
| Others |
Value Network & Pricing Analysis
Nickel-based superalloy feedstock volatility determines both the premium-to-economy pricing spread across vacuum chamber fabricators and the geographic clustering of validated system suppliers near German precision manufacturing corridors. Buyers of FDA-validated pharmaceutical sterilization equipment absorb 40-60% price premiums over standard industrial configurations, while procurement officers at North American protein packaging facilities prioritize mobile unit availability over alloy-grade specifications.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical sterilization infrastructure procurement, with biologics manufacturers in Switzerland and Massachusetts locking in multi-year service bundles covering validation documentation, spare part availability, and predictive maintenance attach rates. Price differentiation rests on ISO 13485 certification tier and geographic proximity to technical service centers, with validated systems commanding substantial premiums over unvalidated industrial alternatives. Cost compression in portable configurations is intensifying as food processing buyers prioritize capital efficiency over pulse timing precision. Contract manufacturing organizations exhibit the sharpest price sensitivity, while sterile API producers show minimal elasticity given regulatory audit exposure.
Supply Chain Analysis
Tariff exposure between the United States and China concentrates risk for vacuum pump electronics and precision sensor components, forcing European OEMs to diversify sourcing toward Taiwanese semiconductor-grade suppliers and South Korean automation vendors. German and Japanese fabricators anchor chamber production, drawing from Swedish specialty steel mills and Italian precision machining clusters. Single-source vulnerability persists for medical-grade elastomer seals subject to REACH authorization sunsets. Distribution runs through authorized technical centers with rapid spare-part fulfillment rather than traditional industrial distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
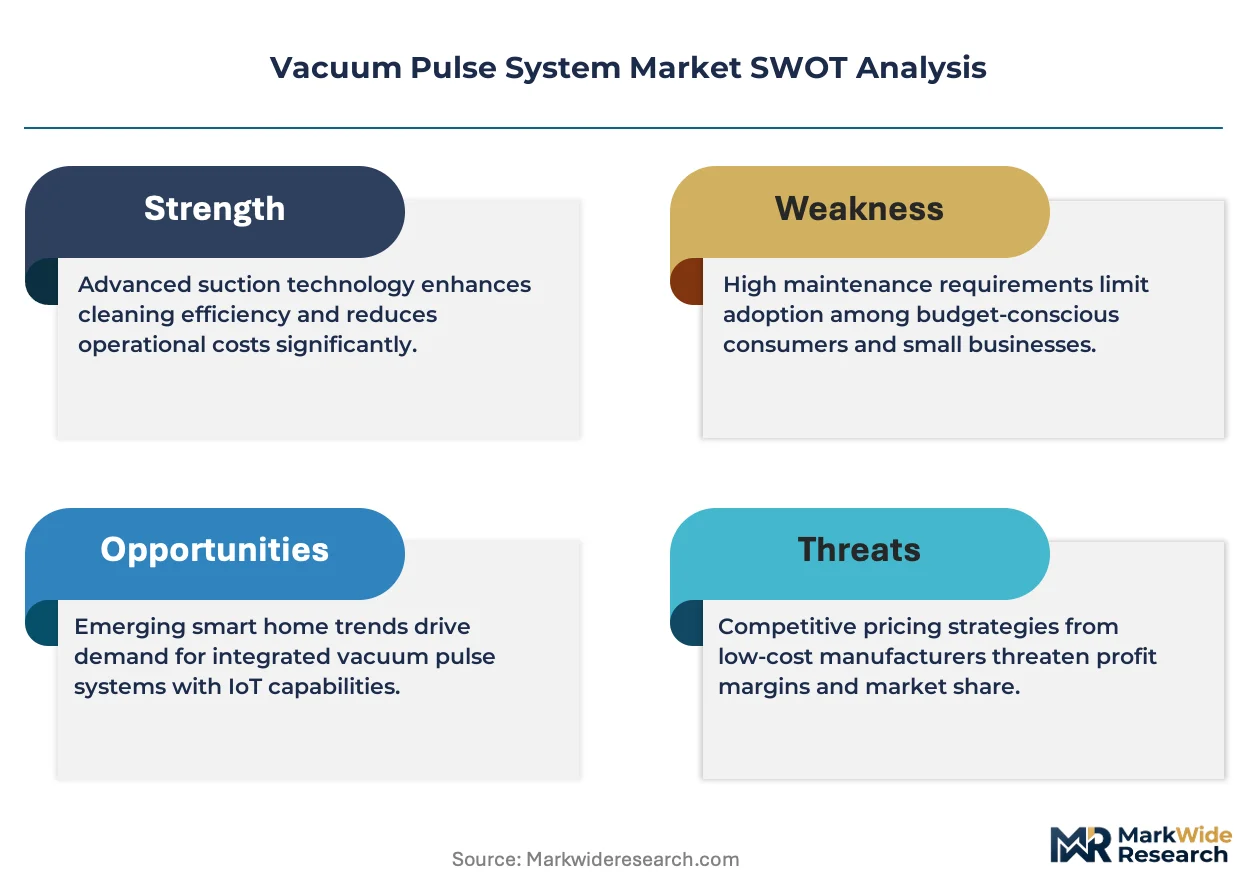
Aftermarket service unbundling is expanding validation, spare part, and remote monitoring contract pools faster than hardware shipment growth, repositioning supplier economics toward recurring revenue architectures.
For Market Incumbents: Harden defensive positions by deepening backward integration into nickel-based superalloy sourcing and securing captive supply of medical-grade elastomer compounds ahead of REACH authorization deadlines. Anchor capacity in Bavaria and Baden-Württemberg to preserve OEM integration expertise clusters, while cross-selling predictive maintenance contracts through existing compressor service infrastructure to offset displacement of liquid ring pump aftermarket revenue. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO-aligned sterile API manufacturing corridor, where domestic producers import validated vacuum sterilization infrastructure to accelerate commercial deployment timelines. Target portable unit configurations for North American protein packaging facilities requiring seasonal line reconfiguration flexibility. Lead with oil-free scroll pump architectures combined with Industry 4.0 predictive maintenance capabilities to differentiate against legacy lubricant-dependent incumbents. For Investors and Strategic Acquirers: EU MDR compliance deadlines reshape the acquisition landscape by compressing retrofit schedules and elevating the scarcity value of ISO 13485-certified equipment suppliers with established notified body relationships. Long-term viability favors precision engineering specialists with semiconductor-grade vacuum capabilities and localized technical center footprints. Monitor CDSCO regulatory alignment progress as the signal indicating inflection in Indian pharmaceutical infrastructure import intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Captive sourcing of nickel-based superalloys insulates margin from energy-intensive smelting cost swings. |
| ISO 13485 Certification Infrastructure Investment | Accelerated documentation capabilities capture compressed procurement cycles driven by FDA and EU MDR deadlines. |
| Predictive Maintenance Platform Development | VFD-controlled dry scroll architectures enable remote monitoring attach rates that replace obsolete lubricant service revenue. |
| Localized Technical Center Expansion | Rapid spare-part fulfillment in Maharashtra and Gujarat addresses CDSCO-aligned sterile API producer demand. |
| Fluoropolymer Seal Reformulation Program | REACH-compliant elastomer substitution eliminates authorization sunset risk for European vacuum chamber deployments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, SEC 10-K equipment supplier disclosures, and specialty alloy trade flow records. Primary interviews engaged maintenance directors at pharmaceutical freeze-drying facilities, OEM procurement teams in German precision manufacturing corridors, aftermarket service heads at diversified industrial equipment groups, and regulatory affairs leads navigating CDSCO alignment timelines. Bottom-up shipment data triangulates against top-down capital expenditure tracking across biologics manufacturing clusters.
Forecast inputs span product architecture segmentation across fixed, portable, and custom configurations; pump technology migration from liquid ring to dry scroll and diaphragm architectures; and regulatory compliance tier differentiation. Modeled dimensions include industry vertical concentration in pharmaceuticals versus food processing, application intensity across vacuum drying and packaging workflows, and regional adoption patterns shaped by FDA, EU MDR, and CDSCO enforcement timelines. CAGRs derive from installed base growth, replacement cycle acceleration, and service revenue expansion trajectories.
Sensitivities concentrate around EPA emissions standard enforcement timelines for pump lubricants, REACH authorization sunsets affecting elastomer selection, and German OEM integration expertise availability. Forecasts reflect assumptions regarding regulatory deadline adherence, alloy feedstock cost stability, and semiconductor fabrication capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
AI Computing Hardware Market